
 Belgium Data Center Market | 2026-2036
Belgium Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Data Center Market Insights
Immersion cooling fluids are broadening the thermal design envelope for high-density racks in Belgian facilities. Digital Realty leverages its interconnection platform to anchor wholesale demand across the Brussels-Antwerp corridor. Microsoft Corporation sustains competitive positioning through direct renewable power contracting with offshore wind developers in the North Sea. LCL Data Centers differentiates via sovereign-certified facilities that meet Belgian federal cybersecurity requirements for defense and intelligence workloads.
A data center constitutes a dedicated facility housing compute, storage, and network infrastructure with controlled environmental parameters—typically maintaining temperatures between 18°C and 27°C per ASHRAE guidelines—and redundant power architectures designed for 99.999% uptime availability. Colocation services command the largest revenue pool as enterprises exit owned facilities, while cloud services represent the fastest-expanding segment as Belgian SMEs migrate workloads to hyperscale platforms. Managed services capture premium margins where providers integrate security operations and compliance monitoring for financial services end users.
Belgium's federal energy regulator and the Brussels Environment agency enforce PUE reporting thresholds and green building certifications that filter market entry for new constructions. The EU AI Act and national cybersecurity framework impose data sovereignty and algorithmic transparency obligations that reshape procurement criteria for government and financial end users. Stakeholders must monitor grid interconnection queue positions and renewable energy certificate markets to secure cost-competitive power for planned capacity additions.
Market Dynamics
Liquid cooling retrofits are compressing deployment timelines for high-density AI infrastructure as Belgian operators race to meet EU Energy Efficiency Directive mandates before enforcement deadlines tighten.
Growth Catalysts
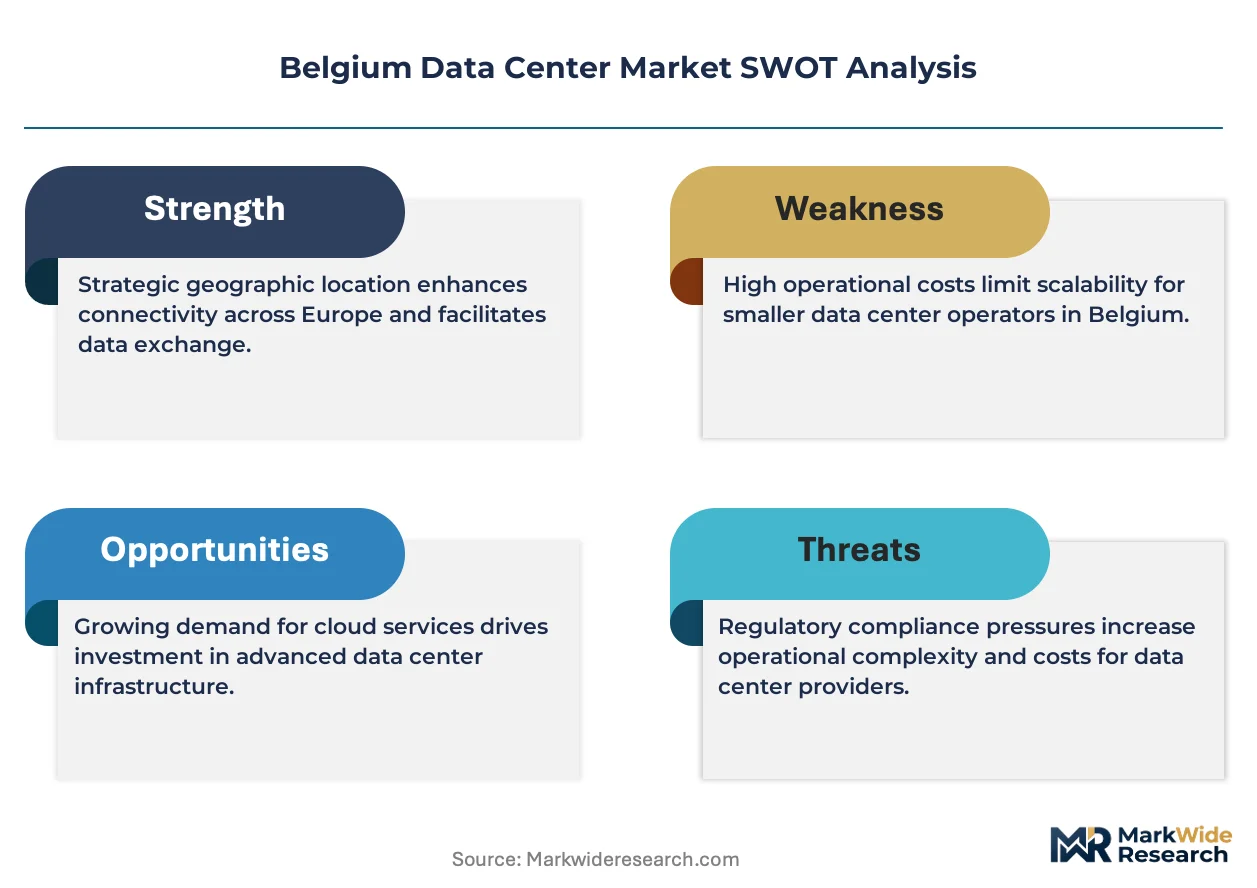
- EU AI Act:Algorithmic transparency obligations for government workloads are mandating sovereign-certified facilities, expanding procurement pools for domestic operators.
- Financial services latency requirements:Real-time trading platforms are driving colocation demand in the Brussels-Capital Region where fiber density minimizes round-trip delays.
- North Sea offshore wind:Direct renewable power contracting is enabling 24/7 carbon-free matching for hyperscale campuses, reducing long-term energy cost volatility.
Market Restraints
- Liquid cooling fluid supply concentration:Synthetic dielectric fluids rely on a narrow supplier base concentrated in Germany and the Netherlands, creating input cost volatility for retrofits.
- Grid interconnection queues:Elia's transmission planning process extends lead times for new substations, delaying capacity additions in Flanders and Wallonia.
- Skilled technician scarcity:Immersion cooling maintenance requires specialized certification programs that Belgian technical institutes have not yet scaled to meet demand.
Strategic Opportunities
- Wallonia industrial zones:Decommissioned steel mill sites offer brownfield power capacity and cooling water access for large-scale campus development.
- AI training workload migration:Belgian SMEs are shifting from on-premise inference to cloud-based training clusters, opening wholesale demand segments.
- Green building certification premiums:BREEAM-Outstanding-rated facilities command rental premiums from ESG-mandated institutional investors.
Industry Challenges
- Legacy raised-floor incompatibility:Conventional air-cooled designs require complete mechanical overhaul to accommodate direct-to-chip liquid loops, complicating tenant retention during retrofits.
- Federal cybersecurity certification timelines:Belgian federal INFOSEC clearance for defense workloads extends 14-18 months, compressing revenue recognition for new sovereign facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Data Center Market |
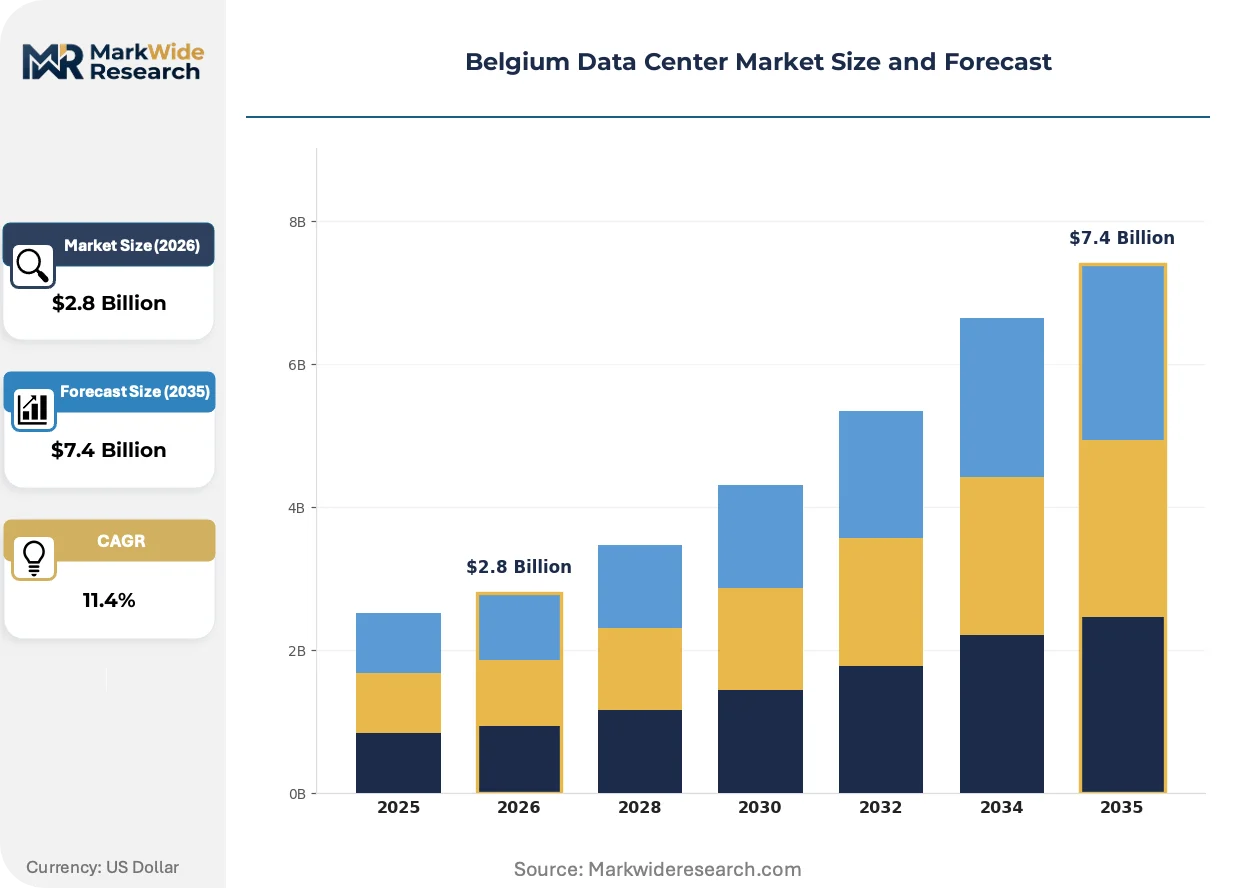
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Managed Services, Cloud Services, Hosting Deployment Model: On-Premises, Off-Premises, Hybrid, Multi-Cloud End User: Government, Financial Services, Telecom, IT Services Infrastructure: Power Systems, Cooling Solutions, Security Systems, Connectivity |
| Companies Covered | Google LLC, Microsoft Corporation, Amazon Web Services, Digital Realty, LCL Data Centers, Datacenter United, EdgeConneX, Proximus, AtlasEdge, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Data Center Market Trends and Innovations
Belgian data center architecture is pivoting from air-cooled standardization to thermal-fluid innovation as power densities exceed 50kW per rack. This shift is reconfiguring supply chains, procurement criteria, and facility design protocols across the Brussels-Antwerp corridor.
Single-phase immersion cooling is electrifying the thermal management landscape for GPU-intensive workloads. The technology submerges servers in dielectric fluid, eliminating fans and reducing mechanical failure rates. Hyperscale cloud operators are piloting 100kW+ rack densities in Belgian facilities. This density compression is electrifying wholesale pricing models, enabling revenue per square meter multiples that justify premium construction costs.
Brussels Environment agency enforcement of PUE reporting thresholds is hardening market entry barriers for new constructions. Operators must demonstrate annualized efficiency below 1.3 for facilities above 500kW connected load. Financial services end users are incorporating these metrics into RFP scoring, disqualifying legacy designs. The Brussels-Capital Region is responding with expedited permitting for liquid-cooled projects that guarantee sub-1.2 PUE.
Enterprise buyers are consolidating vendor relationships around integrated platform contracts that bundle colocation, interconnection, and managed security. The traditional siloed procurement of space, power, and cross-connects is contracting as CFOs seek single-line-item visibility. Belgian mid-market enterprises are driving this consolidation, preferring operational expenditure treatment over capital-intensive owned infrastructure. This bundling is most visible in Antwerp's port district where logistics and commodity trading firms dominate demand.
Belgium Data Center Market Segmentation
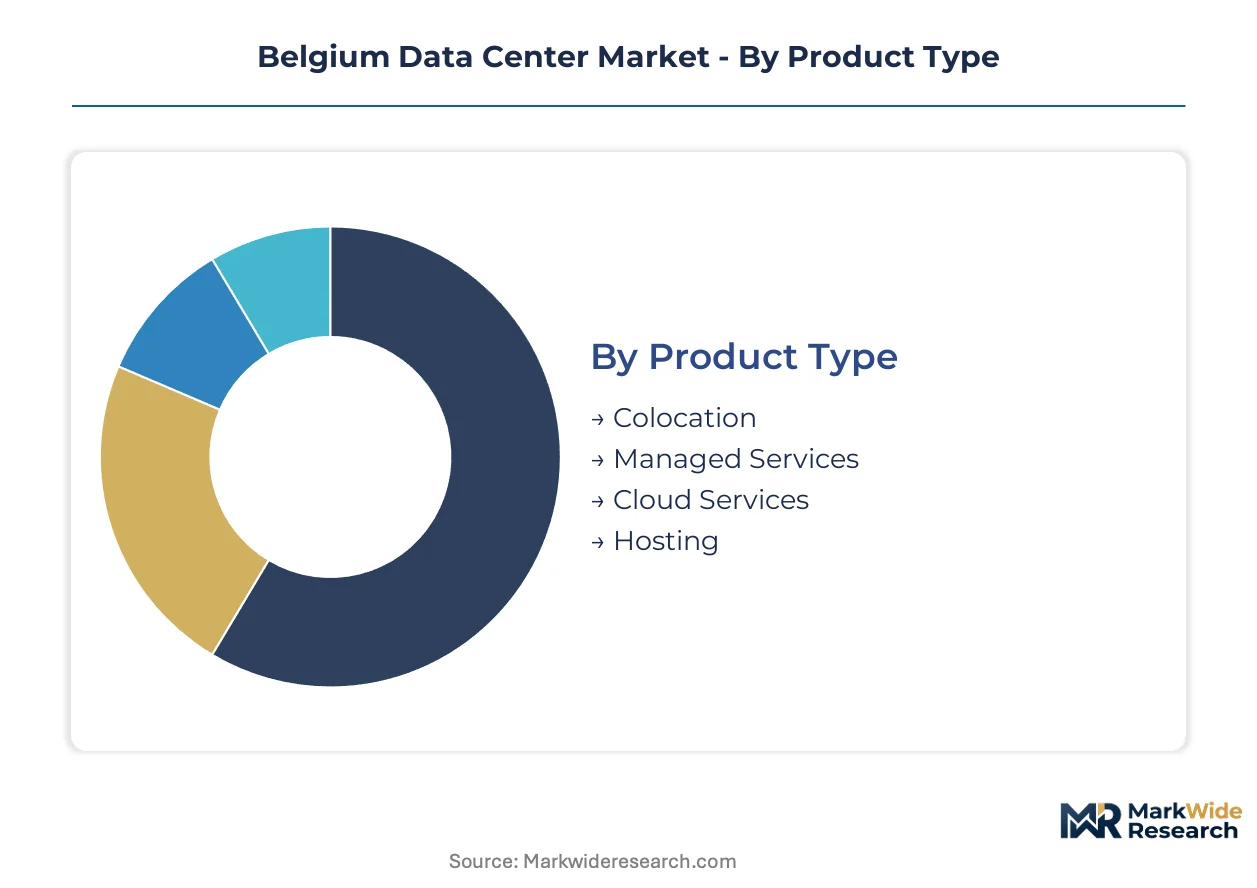
Segmentation in the Belgium data center market reveals how procurement criteria diverge across buyer archetypes. Financial institutions prioritize latency and sovereign certification, while SMEs optimize for operational expenditure treatment. These divergent priorities reshape competitive positioning across the Brussels-Antwerp corridor.
Product Type:
Enterprises select product tiers based on capital intensity tolerance and internal IT headcount availability.
- Colocation:Wholesale and retail space leasing with redundant power and cooling infrastructure operated by third-party providers. Financial services firms in the Brussels-Capital Region drive demand here to satisfy sub-10 millisecond latency requirements for algorithmic trading platforms.
- Managed Services:Integrated security operations, compliance monitoring, and infrastructure management delivered as bundled subscriptions. Belgian federal cybersecurity frameworks for defense workloads mandate these comprehensive service wraps, extending procurement cycles but locking in multi-year revenue visibility.
- Cloud Services:Hyperscale compute and storage accessed via utility pricing models.
- Hosting:Dedicated server provisioning with single-tenant isolation guarantees.
Volume sits with Colocation; growth tilts toward Cloud Services.
Deployment Model:
Architecture choices reflect data sovereignty obligations and workload portability requirements across regulated industries.
- Off-Premises:Complete workload migration to third-party facilities with no retained owned infrastructure. Belgian SMEs expanding AI training capabilities favor this model to avoid capital expenditure on GPU clusters.
- Hybrid:Orchestrated distribution across owned and colocated environments with unified management planes. Financial services firms deploy hybrid architectures to retain sensitive trading algorithms on-premise while bursting analytics workloads to Brussels-based colocation facilities.
- On-Premises:Fully owned facilities with captive infrastructure management.
- Multi-Cloud:Workload distribution across competing hyperscale platforms to mitigate vendor concentration risk.
Off-Premises carries current volume leadership; Hybrid architectures are gaining share fastest among regulated enterprises.
End User:
Sector-specific compliance regimes and latency sensitivity create distinct procurement patterns across verticals.
- Financial Services:Banks, insurance carriers, and trading venues with real-time transaction processing requirements. Brussels-based fiber density and proximity to European securities exchanges concentrate demand in the capital region.
- Government:Federal agencies and defense entities with sovereign data residency mandates. Belgian federal INFOSEC certification requirements filter vendor eligibility, extending sales cycles but creating durable competitive moats for approved providers.
- Telecom:Network operators requiring edge compute colocation for 5G service delivery.
- IT Services:Systems integrators and managed service providers reselling capacity to downstream clients.
Financial Services anchors revenue concentration; Government procurement is climbing the fastest as EU AI Act enforcement tightens.
Infrastructure:
Facility performance differentiation increasingly depends on thermal and power architecture choices rather than connectivity alone.
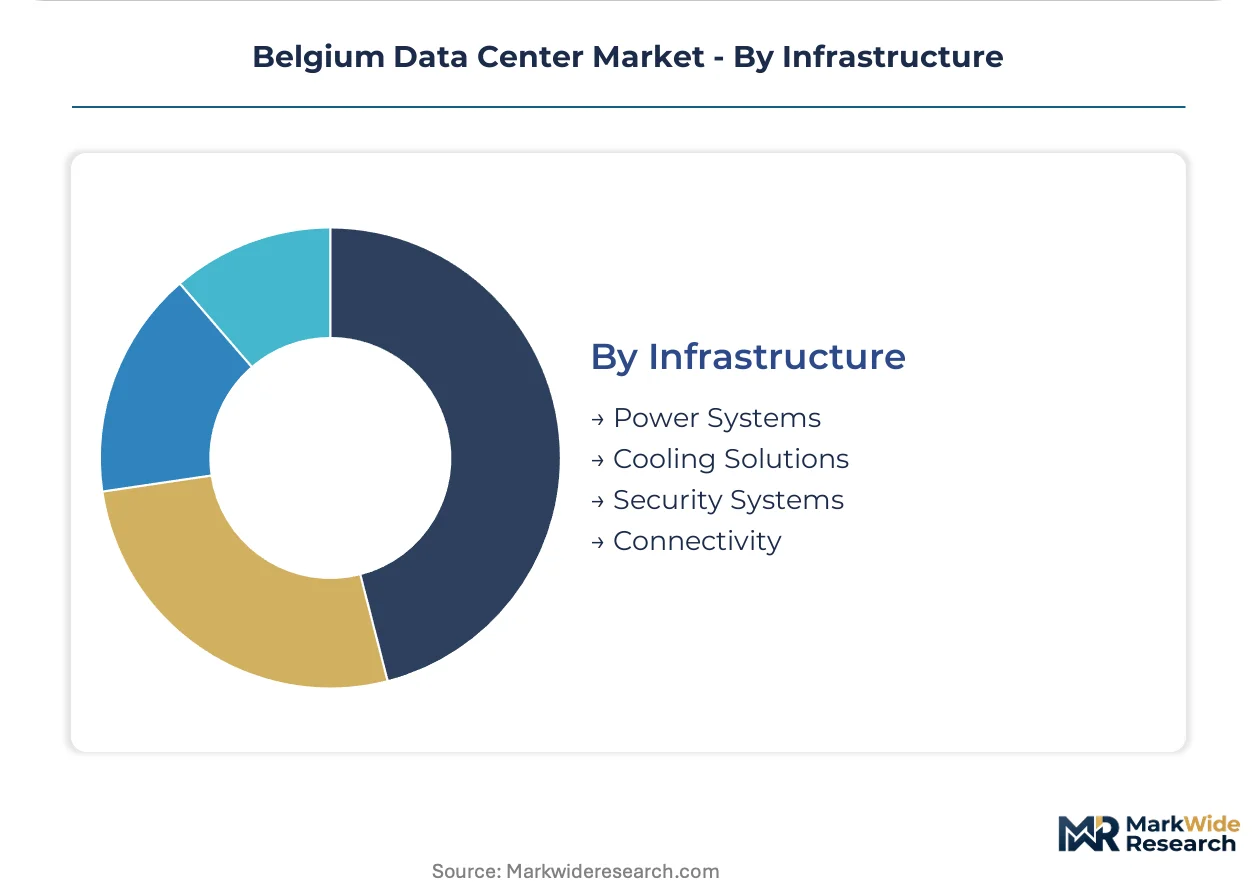
- Cooling Solutions:Air-cooled, liquid-cooled, and immersion-cooled thermal management systems. Single-phase immersion cooling is electrifying wholesale pricing models for GPU-intensive workloads as Belgian operators retrofit facilities to meet Brussels Environment agency PUE thresholds below 1.3.
- Power Systems:Uninterruptible power supply configurations, switchgear, and renewable energy integration. Direct contracting with North Sea offshore wind developers enables 24/7 carbon-free matching for hyperscale campuses, reducing long-term energy cost volatility.
- Security Systems:Physical access controls, biometric authentication, and surveillance infrastructure.
- Connectivity:Cross-connects, internet exchanges, and dark fiber provisioning.
Power Systems represents the largest capital allocation; Cooling Solutions is expanding most quickly as rack densities exceed 50kW.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Brussels-Capital Region where fiber density and power grid access create clustering advantages for latency-sensitive financial services workloads.
Brussels-Capital Region
Financial services firms drive colocation demand to meet sub-10 millisecond latency requirements for algorithmic trading platforms. Brussels Environment agency enforces PUE reporting thresholds below 1.3 for facilities above 500kW connected load. The Brussels-Antwerp corridor anchors hyperscale campus development where Digital Realty leverages interconnection platforms.
Flanders
Decommissioned steel mill sites in Wallonia industrial zones offer brownfield power capacity for large-scale campus development. Elia's transmission planning process extends lead times for new substations, delaying capacity additions. Antwerp's port district concentrates demand from logistics and commodity trading firms preferring bundled operational expenditure treatment.
Wallonia
Cooling water access from former industrial infrastructure attracts immersion cooling retrofits for GPU-intensive AI training workloads. The EU Energy Efficiency Directive accelerates liquid cooling adoption before enforcement deadlines tighten. Liège and Charleroi sub-regions emerge as alternative sites where grid interconnection queues prove shorter than Flanders.
Antwerp Metropolitan Area
Enterprise buyers consolidate vendor relationships around integrated platform contracts bundling colocation and managed security. Belgian federal cybersecurity frameworks mandate sovereign-certified facilities for defense workloads. The port district's fiber density supports real-time commodity trading platforms requiring redundant connectivity.
Belgium Data Center Market Competitive Landscape
Capacity expansion dominates the current landscape as operators race to meet EU Energy Efficiency Directive mandates before enforcement deadlines tighten. The vendor base organizes around three strategic archetypes: hyperscale cloud operators with direct renewable power contracting, wholesale colocation providers leveraging interconnection platforms, and sovereign-certified specialists meeting federal cybersecurity requirements. M&A activity and liquid cooling retrofits represent the two dominant competitive moves reshaping facility portfolios.
Within the sovereign-certified tier, LCL Data Centers exemplifies domestic operators capturing defense and intelligence workloads through Belgian federal INFOSEC clearance. Among hyperscale cloud providers, Microsoft Corporation and Google LLC anchor wholesale demand through direct renewable power contracting with North Sea offshore wind developers. Digital Realty occupies a position bridging wholesale colocation and interconnection services across the Brussels-Antwerp corridor.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft Corporation |
| Amazon Web Services |
| Digital Realty |
| LCL Data Centers |
| Datacenter United |
| EdgeConneX |
| Proximus |
| AtlasEdge |
| Others |
Pricing and Supply Chain Analysis
Dielectric fluid costs cascade through Belgian data center pricing tiers as synthetic immersion cooling liquids from German and Dutch suppliers feed into facility retrofits and new construction bids. Brussels Environment agency PUE thresholds below 1.3 compress margins for air-cooled legacy operators while rewarding liquid-cooled premium positioning.
Pricing Analysis
Volume concentrates in wholesale colocation contracts while margins accrue to sovereign-certified managed services. Price differentiation hinges on federal INFOSEC clearance status and renewable energy matching guarantees. Pricing pressure stems from Elia grid interconnection queue delays extending lead times for new capacity. Financial services firms exhibit lowest price sensitivity due to latency mandates, while Belgian SMEs migrating to cloud services drive commoditization in utility-priced compute tiers.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Antwerp anchor dielectric fluid and precision cooling component flows into Belgian facilities. Manufacturing concentrates in Germany for switchgear, the Netherlands for thermal management systems, and Taiwan for GPU server assemblies. Raw material dependencies span copper for busbars, lithium for battery storage, and engineered fluoropolymers for immersion fluids. Single-source vulnerability in synthetic dielectric chemistry creates input cost volatility. Distribution runs through direct manufacturer relationships for hyperscale operators and VAR channels for mid-market colocation tenants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Belgium's data center market reads as supply-constrained where Elia transmission queue positions prop pricing power for connected capacity. Grid interconnection scarcity filters new entrants while rewarding early-movers with secured substations.
For Market Incumbents: Extend liquid cooling retrofit programs ahead of EU Energy Efficiency Directive enforcement tightening. Secure long-term dielectric fluid supply agreements with German and Dutch chemical producers to hedge input volatility. Anchor tenant retention through sovereign certification investments that lock in defense and intelligence workloads against emerging domestic competitors.
For New Entrants and Emerging Players: Systems integrators reselling managed security wraps represent the most accessible channel partner type for market penetration. Target Wallonia industrial zones where decommissioned steel mill sites offer brownfield power capacity with shorter interconnection queues than Flanders. Lead with AI training cluster specialization to differentiate from hyperscale commodity compute positioning.
For Investors and Strategic Acquirers: Accelerated Brussels Environment agency permitting for sub-1.2 PUE liquid-cooled projects is the leading indicator that green building certification premiums will sustain. Long-term viability centers on facilities with secured renewable energy contracting and sovereign clearance moats. Acquisition target archetype: domestic operators with federal INFOSEC certification and secured grid positions. Watch North Sea offshore wind PPA pricing as the inflection signal for hyperscale campus economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Retrofit Program | Brussels Environment agency PUE enforcement hardens market entry barriers below 1.3 threshold. |
| Direct Renewable Power Contracting | North Sea offshore wind PPAs enable carbon-free matching for hyperscale campus demand. |
| Sovereign Certification Investment | Federal INFOSEC clearance extends procurement cycles but creates durable competitive moats. |
| Wallonia Brownfield Development | Decommissioned steel mill sites offer cooling water access and shorter Elia queue positions. |
| Integrated Platform Bundling | Antwerp port district logistics firms consolidate vendor relationships around single-line-item contracts. |
Research Methodology
Regulatory filings from Elia and Brussels Environment agency, hyperscaler renewable energy procurement disclosures, and federal cybersecurity certification databases formed the secondary backbone of this analysis. Primary fieldwork encompassed interviews with data center facility directors, colocation procurement officers at financial services firms, Elia transmission planning engineers, and thermal systems specialists at Belgian technical institutes. Bottom-up capacity tracking across the Brussels-Antwerp corridor was triangulated against top-down demand modeling from enterprise IT expenditure patterns.
Historical trendline analysis of connected load growth, PUE compliance trajectories, and interconnection queue durations informed the projection framework. Segmentation dimensions modeled encompass deployment model architecture, end-user vertical compliance regimes, infrastructure thermal technology tiers, and regional grid access patterns. CAGRs were derived from capacity expansion pipelines cross-referenced against demand elasticity estimates for latency-sensitive workloads. Forecast inputs incorporated EU AI Act implementation timelines and North Sea offshore wind capacity buildout schedules.
Caveats apply where Elia transmission planning delays, dielectric fluid supply disruptions, or Belgian federal cybersecurity certification backlogs could materially shift the outlook. Forecasts reflect documented assumptions regarding grid interconnection sequencing and renewable energy certificate market liquidity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Taiwan Data Center Physical Security Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
North America Containerized Data Center Market
Data Center Infrastructure
Europe Data Center Power Market
Data Center Infrastructure
High Availability Server Market
Data Center Infrastructure
South Korea Data Center Physical Security Market