
 Saudi Arabia Data Center Construction Market | 2026-2036
Saudi Arabia Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Data Center Construction Market Insights
Managed maintenance contracts is hardening as a discrete revenue layer in Saudi data center construction, shifting vendor economics from pure build contracts toward lifecycle service agreements. Fortis Construction leverages its regional project portfolio to capture recurring facility management revenue. Alfanar Group anchors its position through integrated electrical and mechanical capabilities that span construction into operations. Turner Construction Co competes on complex mission-critical delivery timelines for hyperscale clients.
Saudi Arabia data center construction encompasses the engineering, procurement, and physical build-out of facilities housing IT infrastructure, with specifications typically requiring N+1 redundancy in power and cooling systems alongside tier-certified uptime guarantees. Cooling Systems and Power Supply Units command the dominant product spend pools given the Kingdom's extreme ambient temperatures and grid reliability demands. Edge Computing infrastructure represents the fastest-growing technology segment as latency-sensitive applications proliferate across retail, healthcare, and industrial zones.
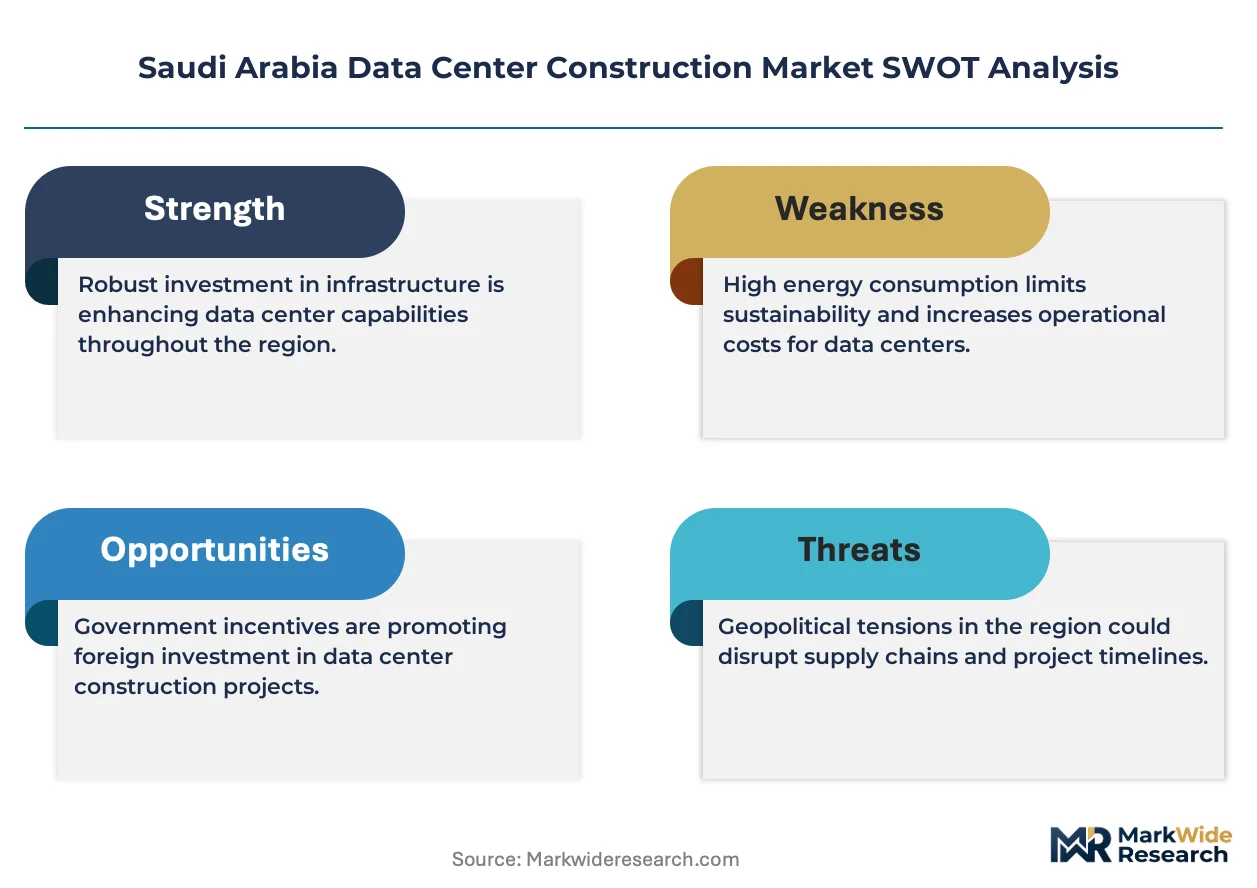
SFDA data localization mandates, CITC cybersecurity licensing, and SASO building code compliance collectively dictate facility design standards and operator certification requirements in the Kingdom. These frameworks elevate barrier costs for new entrants while privileging contractors with demonstrated regulatory navigation experience. Stakeholders must monitor evolving sovereign cloud policies and green building benchmarks as these will reshape capital allocation and vendor qualification criteria.
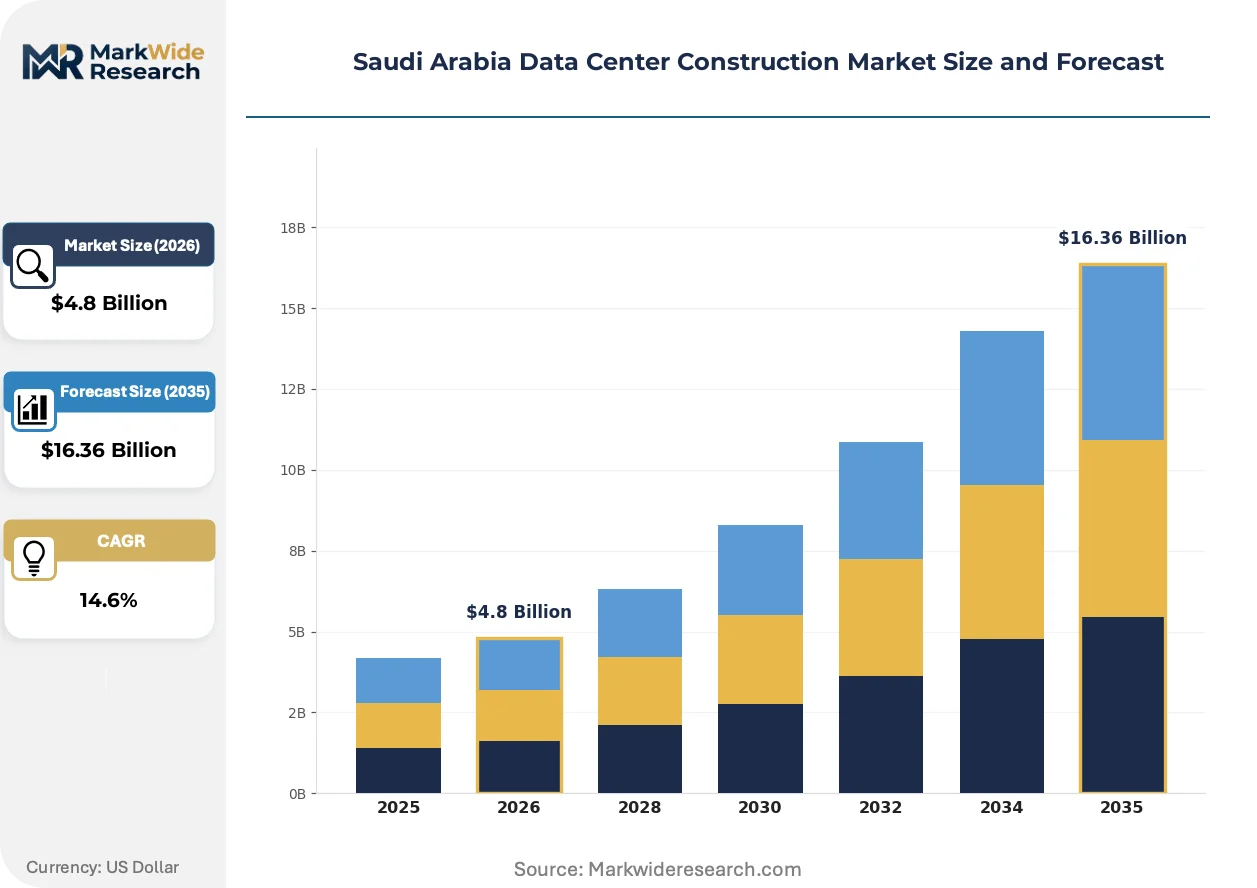
Market Dynamics
SFDA data localization mandates and CITC cybersecurity licensing are compressing facility design timelines while elevating capital intensity for contractors without proven regulatory navigation experience. The shift from pure construction contracts to lifecycle service agreements is redistributing margin pools toward facility management specialists.
Growth Catalysts
- Hyperscale Cloud Expansion:Major cloud service providers are scaling physical infrastructure footprints across Riyadh and Jeddah to meet sovereign data requirements. This creates sustained demand for tier-certified facilities with N+1 redundancy specifications.
- SFDA Localization Mandates:Healthcare and pharmaceutical data residency rules are forcing domestic facility buildouts that would otherwise locate offshore. Compliance deadlines are accelerating procurement cycles for certified contractors.
- Edge Computing Proliferation:Latency-sensitive applications in retail, healthcare, and industrial zones are dispersing infrastructure beyond primary hubs. Distributed architectures require smaller-footprint facilities with modular cooling and power systems.
Market Restraints
- Specialized Labor Scarcity:Mission-critical electrical and mechanical installation expertise concentrates among a limited pool of Saudi-based contractors. Wage premiums for certified technicians are elevating project cost structures.
- Cooling Equipment Import Dependency:High-capacity chillers and precision air handling units rely on supply chains originating in East Asian manufacturing clusters. Lead time volatility constrains construction scheduling certainty.
- Grid Reliability Limitations:Utility power quality variations in secondary cities necessitate oversized on-site generation capacity. Generator fuel storage and switching infrastructure add capital overhead beyond baseline facility costs.
Strategic Opportunities
- Neom and Red Sea Project Corridors:Greenfield city developments are embedding data infrastructure into master planning from inception. Early contractor positioning captures recurring maintenance relationships as these zones operationalize.
- Integrated Renewable Microgrids:Solar PV and battery storage convergence with facility power architecture reduces operational expenditure exposure to fossil fuel price volatility. SASO green building benchmarks are accelerating adoption.
- Managed Services Contracting Models:Operators are unbundling construction from decade-long facility management agreements. Vendors with commissioning-to-operations capabilities capture margin expansion through service attachment.
Industry Challenges
- Tier Certification Timeline Compression:Uptime Institute and TIA-942 certification processes are extending project closeout phases. Documentation and testing protocols require specialized commissioning expertise that outstrips current market supply.
- Legacy System Integration Complexity:Enterprise clients are retrofitting existing facilities while maintaining operational continuity. Phased construction sequencing demands contractor capabilities spanning brownfield and greenfield delivery.
- Cybersecurity-Physical Security Convergence:CITC licensing requirements are merging IT security audits with facility access control specifications. Design-build teams must coordinate across previously siloed technical disciplines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Data Center Construction Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooling Systems, Power Supply Units, Racks, Fire Protection Systems Technology: Edge Computing, Cloud Infrastructure, Virtualization, Automation End User: Cloud Service Providers, Telecommunication Companies, Government Entities, Enterprises Service Type: Design, Construction, Maintenance, Consulting |
| Companies Covered | Fortis Construction, Alfanar Group, Turner Construction Co, Linesight, M+W Group (Exyte), DPR Construction Inc, ALEC Engineering & Contracting, ICS Arabia, AECOM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Data Center Construction Market Trends and Innovations
Digital infrastructure deployment in Saudi Arabia is pivoting toward predictive operational models that compress human intervention in facility management. Construction specifications now embed sensor networks and control platforms as primary design elements rather than retrofit additions.
Artificial intelligence-driven building management systems are automating cooling optimization, fault detection, and energy load balancing across hyperscale facilities. Cloud operators and colocation providers are deploying these platforms at greenfield sites to reduce operational headcount requirements. The technology is automating previously manual commissioning and tuning processes that extended facility ramp periods.
CITC cybersecurity licensing frameworks are mandating encrypted physical access controls, biometric authentication layers, and air-gapped operational technology networks in certified facilities. These requirements are elevating construction costs while disqualifying contractors without security-cleared workforces. Hyperscale deployments in Riyadh and Jeddah are absorbing the most stringent interpretations as anchor clients demand compliance demonstration prior to lease execution.
Enterprise buyers are consolidating vendor relationships toward single-source construction-to-operations contracts that transfer uptime risk to contractors. Traditional design-bid-build procurement is yielding to integrated project delivery models with decade-long service attachments. Financial services and healthcare verticals in the Eastern Province are driving this consolidation fastest as SFDA and SAMA compliance complexity favors vendor accountability bundling.
Saudi Arabia Data Center Construction Market Segmentation
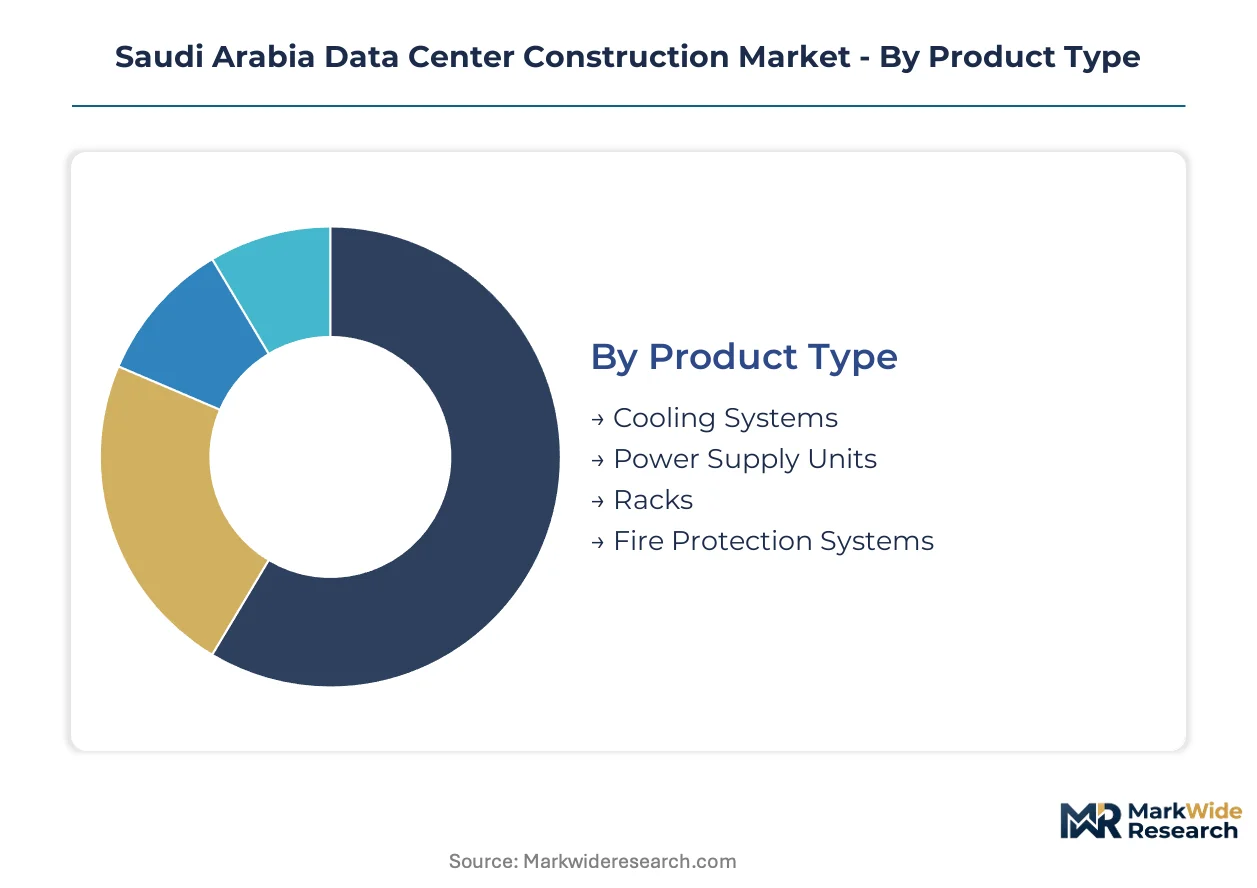
Segmentation in Saudi data center construction reveals how regulatory requirements and climate constraints reshape procurement patterns across product, technology, and service categories. Understanding these divisions exposes where SFDA compliance, CITC licensing, and SASO certification create divergent cost structures and vendor qualification barriers.
Product Type:
Cooling and power equipment carry the heaviest certification burden under SASO building codes and CITC cybersecurity mandates for physical infrastructure resilience.
- Cooling Systems:Precision air handling units and high-capacity chillers engineered for 50°C ambient operating conditions. Hyperscale deployments in Riyadh and Jeddah absorb the dominant share as cloud operators prioritize thermal efficiency under extreme heat loads.
- Power Supply Units:Uninterruptible power systems and switchgear configured for N+1 redundancy with integrated generator synchronization. Grid reliability limitations in secondary cities drive oversized on-site generation specifications that elevate capital intensity beyond baseline facility costs.
- Racks:Cabinet infrastructure with cable management and airflow containment for high-density compute loads.
- Fire Protection Systems:Clean agent suppression and early warning smoke detection for mission-critical uptime guarantees.
Cooling Systems sits at the top of the volume ranking, with Power Supply Units climbing the fastest.
Technology:
Technology segments diverge by latency tolerance and data sovereignty requirements, with edge deployments facing lighter CITC licensing than centralized cloud infrastructure.
- Edge Computing:Distributed micro-facilities positioned within 10 milliseconds of end-users for latency-sensitive applications. Retail, healthcare, and industrial zones across the Eastern Province and secondary cities are absorbing capacity as SFDA mandates force data residency closer to point-of-care systems.
- Cloud Infrastructure:Hyperscale server farms with software-defined networking and storage orchestration. Riyadh and Jeddah concentrate demand as sovereign cloud policies compel domestic physical infrastructure for government and financial services workloads.
- Virtualization:Hypervisor and container platforms enabling multi-tenant resource pooling.
- Automation:Robotic process control and AI-driven building management for operational headcount reduction.
Cloud Infrastructure commands the dominant revenue position, while Edge Computing gains share fastest among technology categories.
End User:
End user segments stratify by compliance complexity, with government and healthcare entities imposing the most stringent facility certification timelines.
- Cloud Service Providers:Hyperscale operators leasing or owning tier-certified facilities with decade-long operational commitments. These buyers are consolidating vendor relationships toward single-source construction-to-operations contracts that transfer uptime risk to contractors.
- Government Entities:State agencies and sovereign wealth vehicles deploying classified and citizen-service infrastructure. CITC cybersecurity licensing and National Cybersecurity Authority standards impose encrypted physical access controls and air-gapped operational technology networks that disqualify contractors without security-cleared workforces.
- Telecommunication Companies:Incumbent carriers building edge and core facilities for 5G backhaul and enterprise services.
- Enterprises:Private sector buyers in financial services, healthcare, and energy retrofitting existing facilities while maintaining operational continuity.
Cloud Service Providers anchor procurement volume, with Government Entities expanding most quickly on sovereign infrastructure mandates.
Service Type:
Service segments reflect a market pivot from transactional construction toward recurring revenue relationships, with maintenance contracts hardening as a discrete margin layer.
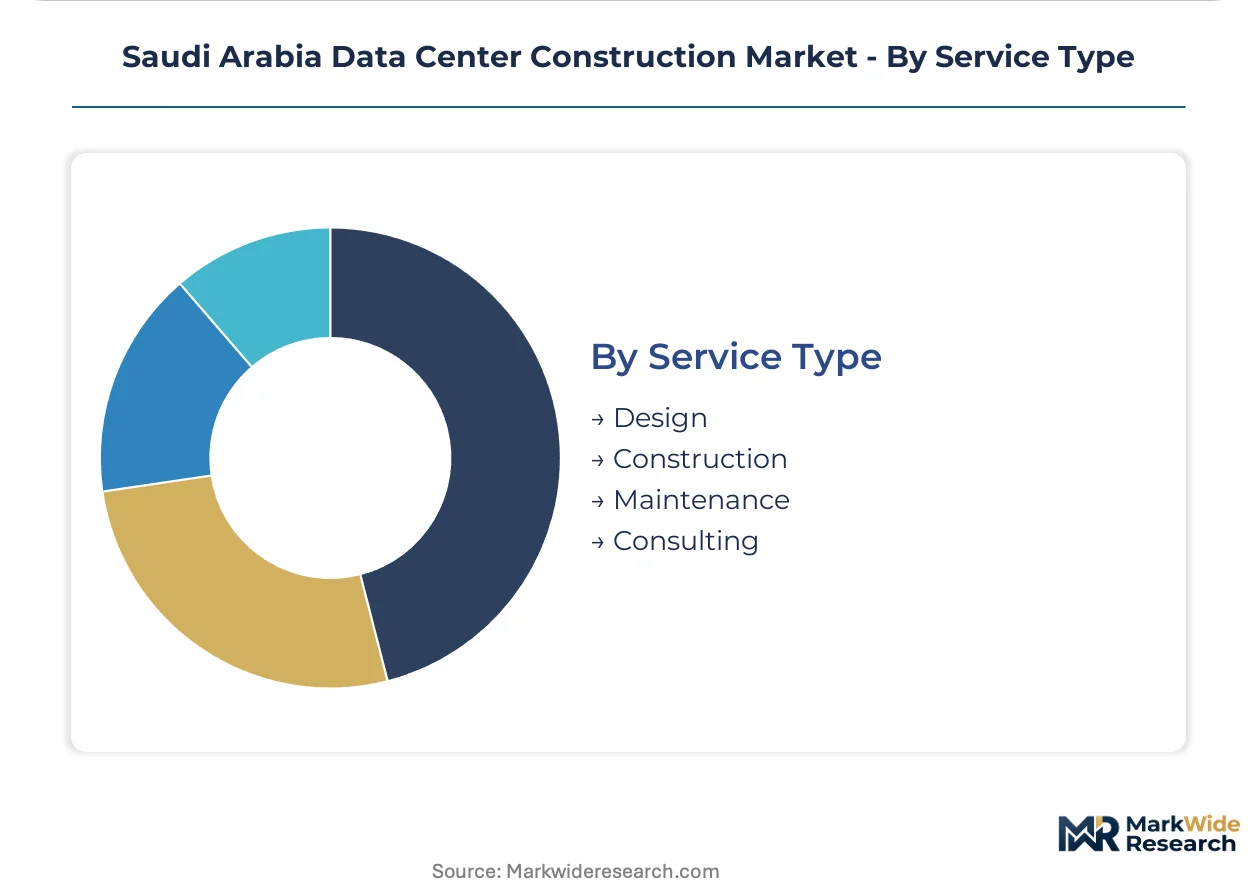
- Construction:Physical build-out encompassing civil works, MEP installation, and commissioning for tier certification. Traditional design-bid-build procurement is yielding to integrated project delivery models with decade-long service attachments as operators unbundle construction from facility management.
- Maintenance:Managed services covering preventive electrical and mechanical upkeep, spare parts logistics, and emergency response. Vendors with commissioning-to-operations capabilities capture margin expansion through service attachment as enterprise buyers consolidate vendor relationships.
- Design:Architectural and engineering planning for site selection, power density, and cooling topology.
- Consulting:Regulatory navigation, tier certification advisory, and sustainability benchmarking.
Construction retains the largest revenue pool, with Maintenance expanding fastest as lifecycle service agreements displace pure build contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping data center construction patterns across the Middle East, with compliance cost gaps between jurisdictions redirecting hyperscale investment flows. The Kingdom's SFDA localization mandates and CITC cybersecurity frameworks create distinct facility specifications that differentiate Saudi Arabia from neighboring markets.
Riyadh
Hyperscale cloud operators and sovereign wealth vehicles dominate procurement, with N+1 redundancy specifications becoming standard for tier-certified facilities. CITC cybersecurity licensing imposes encrypted physical access controls and air-gapped operational technology networks. King Abdullah Financial District and King Salman Energy Park concentrate demand as financial services and government entities mandate domestic data residency.
Eastern Province
Energy sector digitalization and industrial IoT deployments drive edge computing infrastructure across Jubail and Dammam. SFDA pharmaceutical data localization rules accelerate healthcare facility buildouts near major hospital clusters. Aramco's digital transformation programs anchor demand for mission-critical facilities with specialized cooling systems engineered for extreme ambient conditions.
Western Region
Jeddah serves as the primary Red Sea gateway for submarine cable landings and international connectivity hubs. CITC licensing frameworks for telecommunications infrastructure elevate construction specifications for carrier-neutral facilities. King Abdullah Economic City attracts enterprise colocation demand as logistics and retail verticals disperse compute closer to consumer populations.
NEOM Northwest
Greenfield city development embeds data infrastructure into master planning from inception, with renewable microgrids and AI-driven building management specified as primary design elements. SASO green building benchmarks accelerate solar PV and battery storage integration. Early contractor positioning captures decade-long facility management relationships as the zone operationalizes.
Saudi Arabia Data Center Construction Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated project delivery models displacing traditional design-bid-build procurement. The vendor base concentrates among regional contractors with demonstrated SFDA and CITC regulatory navigation experience. Two strategic archetypes dominate: electrical-mechanical integrators capturing lifecycle service revenue, and mission-critical specialists competing on tier certification timelines. Capacity expansion and strategic partnerships represent the dominant competitive moves as operators unbundle construction from facility management.
Among regional contractors with integrated capabilities, Fortis Construction, Alfanar Group, and Turner Construction Co exemplify distinct positioning archetypes. Fortis represents the lifecycle service model, Alfanar anchors electrical-mechanical integration, and Turner occupies the complex mission-critical delivery tier. These firms capture margin expansion through service attachment as enterprise buyers consolidate vendor relationships toward single-source accountability.
| Leading Market Players |
|---|
| Fortis Construction |
| Alfanar Group |
| Turner Construction Co |
| Linesight |
| M+W Group (Exyte) |
| DPR Construction Inc |
| ALEC Engineering & Contracting |
| ICS Arabia |
| AECOM |
| Others |
Pricing and Supply Chain Analysis
Tier certification divergence between Uptime Institute Tier III and Tier IV specifications creates a bifurcated pricing architecture that simultaneously concentrates procurement among certified contractors and fragments cooling equipment sourcing across East Asian manufacturing clusters. SFDA and CITC compliance mandates amplify this split, as healthcare and government buyers absorb 15-25% construction premiums for security-cleared workforces while commercial cloud operators negotiate volume discounts on standardized Tier III builds.
Pricing Analysis
Contractor margin layers dominate pricing architecture, with electrical-mechanical integrators capturing lifecycle service attachments that extend revenue recognition across decade-long facility management agreements. Price differentiation rests on Uptime Institute certification grade and security clearance depth, with CITC-licensed contractors commanding premiums over uncertified rivals. Pricing pressure intensifies in the hyperscale segment as cloud operators consolidate vendor relationships toward single-source accountability. Enterprise buyers in the Eastern Province exhibit highest price sensitivity due to brownfield retrofit complexity, while government entities absorb premium tiers with minimal negotiation.
Supply Chain Analysis
Regional distribution centers in Dubai and Jeddah coordinate hub-and-spoke patterns for precision cooling equipment, though high-capacity chillers and air handling units ultimately originate from manufacturing clusters in China, South Korea, and Japan. Critical component dependencies center on semiconductor-based power electronics, copper winding stock for transformers, and specialized refrigerants subject to F-Gas regulatory restrictions. Single-source vulnerability concentrates in precision cooling OEMs with limited Saudi stocking presence. Distribution runs through CITC-licensed system integrators who bundle equipment procurement with installation and commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia data center construction functions as a stable compounder, with sovereign data localization mandates generating predictable facility buildout pipelines regardless of cyclical cloud capex fluctuations.
For Market Incumbents: Hedge against margin compression in pure construction by deepening facility management service penetration and securing recurring maintenance contracts with decade-long terms. SFDA compliance complexity threatens to displace contractors without security-cleared workforces, making certification investment the priority defensive lever. Alfanar Group and Fortis Construction demonstrate viable archetypes through integrated electrical-mechanical capabilities that span commissioning into operations. For New Entrants and Emerging Players: Launch via specialized edge computing deployments in secondary cities where hyperscale incumbents maintain limited presence. The Neom corridor offers most penetrable geography given greenfield master planning that embeds infrastructure from inception. Government and healthcare verticals present accessible entry segments due to SFDA localization deadlines that accelerate procurement cycles beyond incumbent capacity constraints. For Investors and Strategic Acquirers: Consolidation pressure builds where CITC licensing requirements outstrip contractor certification velocity, creating acquisition opportunities for security-cleared regional specialists. Long-term viability favors vendors with demonstrated regulatory navigation across SFDA, CITC, and SASO frameworks. Watch hyperscale lease execution timelines as the signal indicating inflection in construction backlog pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Project Delivery Adoption | Combines construction with decade-long facility management agreements that transfer uptime risk to contractors. |
| CITC Cybersecurity Certification Investment | Security-cleared workforces capture government and healthcare verticals barred from uncertified competitors. |
| Renewable Microgrid Integration | Solar PV and battery storage convergence reduces operational expenditure exposure to fossil fuel volatility under SASO benchmarks. |
| Edge Computing Infrastructure Positioning | Latency-sensitive applications in retail and industrial zones disperse capacity beyond Riyadh-Jeddah concentration. |
| Lifecycle Service Contract Expansion | Maintenance revenue hardens as discrete margin layer displacing pure transactional construction economics. |
Research Methodology
Direct dialogue with data center construction executives, CITC compliance officers, SFDA regulatory consultants, and hyperscale cloud procurement directors grounded qualitative findings in operational reality. Secondary validation drew from SEC filings of listed contractors, CITC licensing databases, SASO building code updates, and hyperscaler capex disclosure reports. Bottom-up project pipeline tracking triangulated against top-down market sizing across product, technology, and service segmentation dimensions.
Bottom-up volume estimates aggregated individual facility announcements, permitting records, and contractor backlog disclosures, while top-down analysis calibrated spending ratios against cloud operator infrastructure investment trends. Segmentation modeling spanned cooling systems, power supply units, edge computing, and cloud infrastructure categories across the projection horizon. CAGRs derived from regression of historical buildout velocity against regulatory mandate timelines and sovereign cloud policy announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SFDA deadline acceleration or CITC licensing backlog scenarios. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that cooling equipment import lead times and grid reliability investments in secondary cities represent material revision risks to facility completion schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
Data Center Modeling and Simulation Tools Market
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
Chile Data Center Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
South Korea Data Center Rack Market
Data Center Infrastructure
Italy Data Center Rack Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
China Data Center Physical Security Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Thailand Data Center Physical Security Market
Data Center Infrastructure
United Arab Emirates Data Center Market