
 Europe Crane Market | 2026-2036
Europe Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Crane Market Intelligence
Utility-scale renewable energy developers is collapsing as the dominant buyer archetype that once anchored European crane procurement, while data center construction consortiums and rail infrastructure authorities capture expanding order volumes. Liebherr Group leverages its integrated manufacturing footprint across Germany and Austria to dominate heavy-lift tower crane supply for wind farm installation. Konecranes PLC anchors its position in overhead crane systems for automated manufacturing environments, particularly in Nordic automotive and aerospace clusters. Terex Corporation competes through specialized rough-terrain mobile cranes engineered for confined European urban job sites.
A crane is a powered lifting machine employing wire ropes, sheaves, hydraulic pistons, or electric motors to raise and lower loads with precision, typically rated by maximum lifting capacity and boom reach parameters. Its primary industrial purpose centers on vertical transport of heavy materials during construction, manufacturing assembly, cargo handling, and resource extraction operations. Mobile crane configurations lead European revenue contribution due to versatility across dispersed infrastructure sites, while overhead crane installations sustain margin pools through aftermarket service contracts tied to factory automation upgrades. Tower crane demand concentrates in above-100-ton capacity classes as offshore wind foundation projects multiply along the North Sea coastline.
The EU Machinery Directive harmonizes safety requirements across member states, mandating conformity assessment procedures that filter non-compliant imports from third-country manufacturers. REACH and the F-Gas Regulation constrain hydraulic fluid formulations and refrigerant choices in climate-controlled operator cabins, elevating compliance costs for fleet operators. ECHA's substance restriction protocols are forcing component suppliers to reformulate greases and coatings used in bearing assemblies. Stakeholders must monitor how the EU AI Act's risk classification framework applies to autonomous crane operation systems before committing R&D budgets to semi-automated lifting platforms.
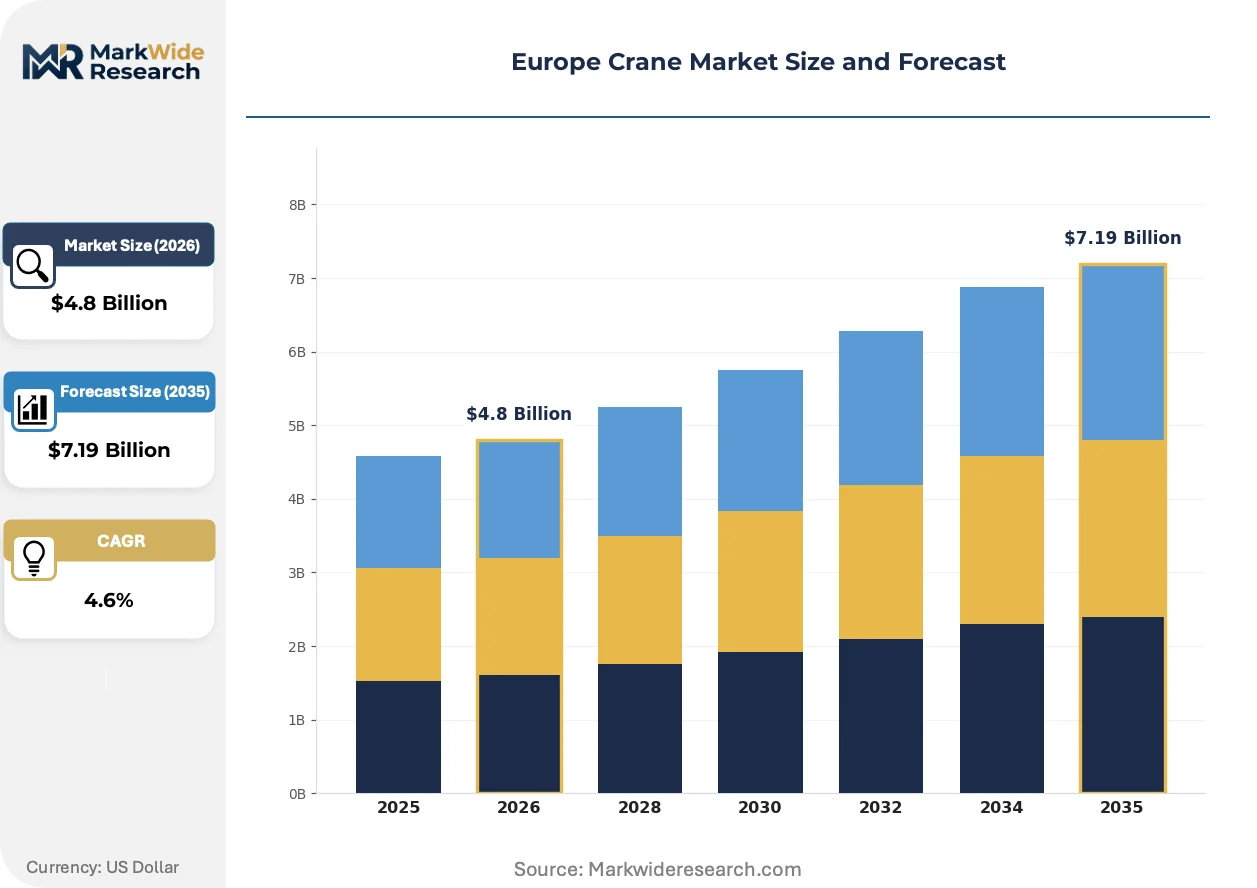
Market Dynamics
EU Green Deal embodied carbon reporting rules are forcing fleet operators to retire diesel-heavy portfolios ahead of depreciation schedules, compressing replacement cycles and redirecting capital toward electrified lifting platforms.
Growth Catalysts
- Offshore wind foundation installation:North Sea corridor projects in Germany and Denmark require above-100-ton capacity tower cranes for monopile and jacket foundation lifts, sustaining order backlogs through 2030.
- Data center construction consortiums:Hyperscale facility builds across Frankfurt, Amsterdam, and Stockholm are absorbing rough-terrain and all-terrain mobile crane fleets for rapid site mobilization.
- EU Machinery Directive harmonization:Conformity assessment procedures for autonomous lifting systems are creating first-mover advantages for OEMs with integrated sensor-to-control architectures.
Market Restraints
- Battery energy density limitations:Electric mobile cranes face payload-range tradeoffs that constrain deployment on remote wind farm sites without grid-tethered charging infrastructure.
- Hydraulic fluid formulation costs:REACH restrictions on mineral oil additives are elevating maintenance expenses for legacy fleet operators in Poland and Romania.
- Specialized technician scarcity:Crane automation integration requires mechatronics competencies that outpace vocational training output in France and Italy.
Strategic Opportunities
- Rail infrastructure authorities in Poland:EU Cohesion Fund allocations for high-speed corridor construction are unlocking demand for heavy-lift crawler cranes in bridge and tunnel segments.
- Remanufacturing and retrofit electrification:Existing diesel tower crane bases in Spain and Portugal present conversion revenue streams for powertrain suppliers.
- Semi-autonomous operation platforms:Convergence of LiDAR positioning with anti-collision algorithms is enabling single-operator configurations that reduce labor costs on congested urban job sites.
Industry Challenges
- CE marking timeline compression:Notified body backlogs for novel crane automation systems are delaying commercial deployment by 8-14 months.
- Legacy fleet integration complexity:Telematics retrofits for mixed-age crane portfolios require protocol bridging that fragments fleet management software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Crane Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Crane, Tower Crane, Crawler Crane, Overhead Crane End User: Construction, Manufacturing, Mining, Shipping Capacity: Below 10 Tons, 10-50 Tons, 51-100 Tons, Above 100 Tons Installation: Onshore, Offshore, Permanent, Temporary |
| Companies Covered | Konecranes PLC, Kobelco Cranes Co Ltd, Liebherr Group, Sany Group, Palfinger AG, Terex Corporation, Tadano Limited, Caterpillar Inc, Manitowoc Company Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Crane Market Strategic Shifts & Innovations
Electrification and automation are converging to redefine crane operational economics, with regulatory pressure accelerating technology adoption beyond natural replacement cycles.
Modular battery-swapping architectures for mobile cranes are decomposing the traditional tradeoff between runtime and payload capacity. Wind farm developers in Scotland and Norway are piloting containerized battery exchange systems that eliminate dwell time for grid charging. This configuration is decomposing the competitive advantage of diesel range autonomy in remote infrastructure sites.
F-Gas Regulation phase-down schedules are constraining refrigerant choices for climate-controlled operator cabins, compelling HVAC system redesigns across German and Austrian manufacturing footprints. Component suppliers must reformulate thermal management circuits using lower-GWP alternatives. Tower crane deployments in Mediterranean climates face the steepest adaptation costs due to extended cooling season demands.
Consolidated procurement by data center construction consortiums is compressing vendor qualification timelines and unbundling after-sales service contracts from equipment supply. Tier-1 contractors in the Netherlands and Ireland now negotiate direct maintenance agreements with regional service networks, bypassing OEM captive service arms. This pattern is most pronounced in hyperscale campus developments where crane utilization intensity justifies dedicated on-site technical presence.
Europe Crane Market Segmentation
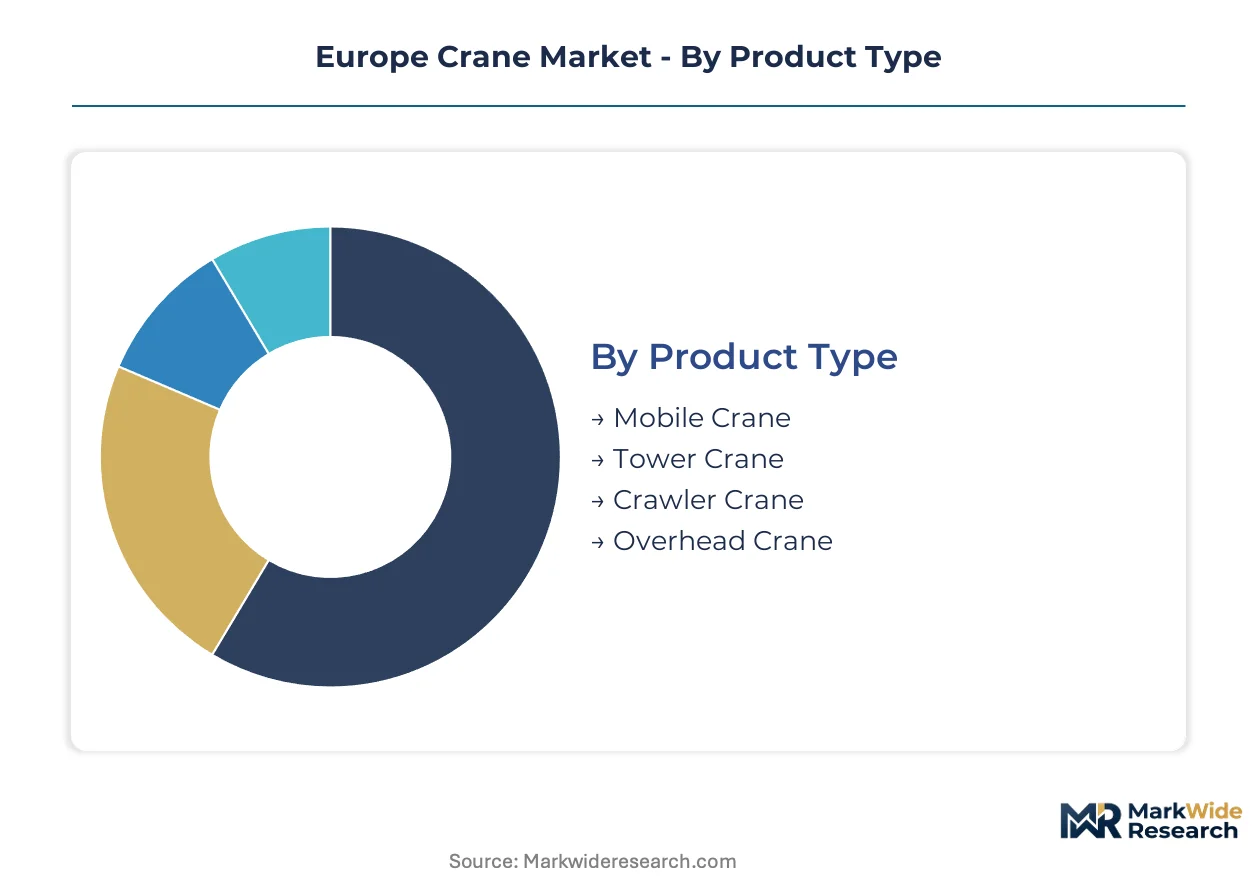
Crane procurement patterns across Europe diverge sharply by application environment and regulatory exposure. Fleet operators align equipment specifications with EU Machinery Directive conformity requirements and site-specific carbon reporting obligations.
Product Type:
CE marking timelines and F-Gas Regulation compliance costs create divergent competitive barriers across crane configurations.
- Mobile Crane:Rough-terrain and all-terrain variants deploy hydraulic boom systems for rapid site mobilization. Data center construction consortiums in Frankfurt and Amsterdam absorb fleets for hyperscale facility builds where grid-tethered charging infrastructure supports electrified units. Mobile configurations handle the majority of throughput; tower crane installations are gaining share fastest in wind energy applications.
- Tower Crane:Fixed-base luffing and hammerhead designs deliver vertical lift precision for high-rise construction and offshore wind foundation work. Above-100-ton capacity classes concentrate along Germany's North Sea coastline for monopile and jacket foundation installations.
- Crawler Crane:Tracked undercarriage systems distribute heavy loads across soft ground conditions. Rail infrastructure authorities in Poland deploy units for bridge and tunnel segments in EU Cohesion Fund corridors.
- Overhead Crane:Bridge and gantry systems integrate with factory automation architectures. Nordic automotive clusters sustain aftermarket service contracts for manufacturing assembly lines.
Mobile crane revenue pools dominate dispersed infrastructure sites; tower crane order backlogs extend furthest into the forecast window.
End User:
Capital expenditure cycles and embodied carbon accounting intensity vary substantially across buyer archetypes.
- Construction:General contractors and specialized trade firms deploy mixed fleets across residential, commercial, and civil engineering sites. EU Green Deal reporting rules compress replacement cycles for diesel-heavy portfolios in France and Italy.
- Manufacturing:Automotive and aerospace clusters in Germany and Sweden anchor overhead crane demand through factory automation upgrades. Manufacturing absorbs the highest service contract attachment rates; mining presents the steepest electrification challenges due to remote site power constraints.
- Mining:Surface extraction operations in Eastern Europe require heavy-lift crawler configurations for equipment maintenance and material handling.
- Shipping:Port terminal operators in Rotterdam and Hamburg integrate ship-to-shore and mobile harbor cranes for container throughput optimization.
Construction channels the largest equipment volumes; manufacturing delivers the most stable recurring revenue streams.
Capacity:
Payload specifications determine regulatory scrutiny levels and operator certification requirements under national labor codes.
- Below 10 Tons:Compact electric and mini-crawler units serve urban renovation and confined industrial maintenance. Below-10-ton units dominate unit shipment counts; above-100-ton classes command the highest average selling prices.
- 10-50 Tons:Mid-range mobile cranes balance transportability with lift capacity for general construction contractors.
- 51-100 Tons:Heavy mobile and tower configurations address infrastructure-scale projects including rail bridge segments.
- Above 100 Tons:Specialized crawler and tower systems execute offshore wind foundation lifts. North Sea developers in Germany and Denmark sustain order backlogs through monopile installation campaigns.
Mid-capacity segments serve the broadest customer base; super-heavy classes face the longest procurement lead times.
Installation:
Site permanence and marine exposure dictate corrosion protection standards and foundation engineering costs.
- Onshore:Fixed and mobile deployments across terrestrial construction and manufacturing sites. Onshore installations represent the default procurement mode; offshore configurations carry the steepest total cost of ownership premiums.
- Offshore:Jack-up barge and vessel-mounted systems for wind farm installation and oil platform maintenance. North Sea operators face saltwater corrosion protocols and dynamic positioning integration.
- Permanent:Tower crane bases and overhead crane runway systems integrated into building infrastructure. Spanish and Portuguese legacy fleets present retrofit electrification opportunities.
- Temporary:Rental and lease-based mobile crane deployments for project-specific durations. Dutch and Irish contractors increasingly unbundle after-sales service from equipment supply agreements.
Permanent installations lock in long-term service relationships; temporary arrangements expand most quickly in data center construction procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Austrian manufacturing footprints anchor tower crane fabrication for North Sea wind projects, while Polish rail corridors and Nordic data center clusters absorb mobile crane deployments across dispersed infrastructure sites.
Germany
Offshore wind foundation installation along the North Sea coastline sustains demand for above-100-ton capacity tower cranes. EU Green Deal embodied carbon reporting rules compress replacement cycles for diesel-heavy fleets in Hamburg and Bremen port zones. Liebherr Group leverages its integrated manufacturing footprint across southern Germany to dominate heavy-lift supply for monopile and jacket foundation campaigns.
Poland
EU Cohesion Fund allocations for high-speed rail corridor construction unlock demand for heavy-lift crawler cranes in bridge and tunnel segments. REACH restrictions on hydraulic fluid formulations elevate maintenance expenses for legacy fleet operators in Warsaw and Kraków construction markets. Rail infrastructure authorities concentrate equipment procurement in the Silesian and Lesser Poland voivodeships where tunneling activity intensifies.
France
Data center construction consortiums in the Paris region and southern France absorb rough-terrain mobile crane fleets for hyperscale facility builds. ECHA substance restriction protocols force component suppliers to reformulate greases used in bearing assemblies for fleet operators. Île-de-France contractors face specialized technician scarcity as crane automation integration demands mechatronics competencies that outpace vocational training output.
Netherlands
Rotterdam port terminal operators integrate ship-to-shore and mobile harbor cranes for container throughput optimization. Consolidated procurement by data center construction consortiums compresses vendor qualification timelines and unbundles after-sales service contracts from equipment supply. Dutch contractors in Amsterdam and Eindhoven increasingly negotiate direct maintenance agreements with regional service networks, bypassing OEM captive service arms.
Sweden
Hyperscale data center builds in Stockholm and surrounding regions absorb all-terrain mobile crane fleets for rapid site mobilization. F-Gas Regulation phase-down schedules constrain refrigerant choices for climate-controlled operator cabins, compelling HVAC system redesigns. Nordic automotive and aerospace clusters sustain aftermarket service contract attachment rates for overhead crane systems integrated with factory automation architectures.
Europe Crane Market Key Industry Players
Concentration sits with diversified industrial conglomerates and specialized lifting equipment manufacturers that span mobile, tower, and overhead crane configurations. The vendor base organizes around three strategic archetypes: integrated European manufacturers with captive component supply, Asian scale players leveraging cost-optimized production, and niche specialists focused on automated or electrified subsystems. Competitive dynamics center on M&A activity targeting regional service networks and technology licensing partnerships for autonomous operation platforms.
Among the integrated European manufacturers, Liebherr Group and Konecranes PLC occupy positions that exemplify divergent specialization vectors—Liebherr representing heavy-lift tower crane supply for infrastructure-scale projects, Konecranes anchoring overhead crane systems for automated manufacturing environments. Terex Corporation sits within the mobile crane specialist tier, competing through configurations engineered for confined urban job sites. Together these three illustrate how geographic manufacturing footprint and product-line breadth determine competitive positioning under EU Machinery Directive conformity requirements.
| Leading Market Players |
|---|
| Konecranes PLC |
| Kobelco Cranes Co Ltd |
| Liebherr Group |
| Sany Group |
| Palfinger AG |
| Terex Corporation |
| Tadano Limited |
| Caterpillar Inc |
| Manitowoc Company Inc. |
| Others |
Cost & Logistics Intelligence
Battery-electric powertrain substitution for diesel-hydraulic systems is simultaneously redrawing component sourcing maps and compressing margin structures across European crane manufacturing. This shift relocates value capture toward lithium-ion cell suppliers and power electronics specialists while OEMs absorb upfront engineering costs for modular battery-swapping architectures.
Pricing Analysis
Volume-discount tiering structures separate hyperscale data center construction consortiums from fragmented general contractors. CE marking certification levels and after-sales service bundling create price differentiation between integrated European manufacturers and Asian scale players. Cost compression in standard-capacity mobile cranes is intensifying because battery energy density limitations force payload-range tradeoffs. General contractors in Poland and Romania exhibit highest price sensitivity; offshore wind developers in Germany and Denmark show lowest sensitivity due to project-scale procurement power.
Supply Chain Analysis
Strategic stockpiling of high-grade steel and copper windings dominates inventory strategy as lead times for specialized bearing assemblies extend. Manufacturing concentration rests on Germany, Austria, and China for structural steel fabrication, power electronics, and precision hydraulics. Lithium-ion cells, rare-earth permanent magnets, and high-tensile steel plate constitute critical input dependencies. Single-source vulnerability in semiconductor-based motor controllers threatens production continuity. Distribution runs through OEM captive networks and independent regional service providers with direct maintenance agreements increasingly common in Dutch and Irish markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe crane market sits at a regulatory-driven technology inflection where EU Green Deal embodied carbon rules are forcing premature fleet replacement ahead of natural depreciation cycles.
For Market Incumbents: Compound defensive positioning through captive battery supply agreements and CE marking fast-track investments for autonomous lifting systems. Electrified rough-terrain mobile cranes face margin pressure from Asian competitors with cost-optimized production; backward integration into lithium-ion pack assembly secures cost control. Prioritize sensor-to-control architecture R&D before notified body backlogs extend commercialization delays. For New Entrants and Emerging Players: CE marking fast-track specialization for retrofit electrification kits offers entry into Spanish and Portuguese legacy tower crane bases. Rail infrastructure authorities in Poland present the most penetrable buyer segment given EU Cohesion Fund allocation scale and limited incumbent service presence. Pursue direct maintenance agreements with regional contractors to bypass established OEM captive networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional service network acquisitions over manufacturing capacity expansion. Long-term viability hinges on electrification technology portfolios and autonomous operation platform IP. Target acquisition archetypes include powertrain retrofit specialists and LiDAR-integrated anti-collision algorithm developers. Watch for inflection when notified body clearance timelines for novel automation systems compress below six months.| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Electrification Program | Spanish and Portuguese legacy fleets present conversion revenue streams for powertrain suppliers. |
| Autonomous Operation Platform Development | LiDAR positioning convergence with anti-collision algorithms enables single-operator configurations. |
| Regional Service Network Acquisition | Dutch contractors increasingly negotiate direct maintenance agreements bypassing OEM captive arms. |
| Battery Supply Agreement | Modular battery-swapping architectures decompose runtime-payload tradeoffs for remote wind sites. |
| CE Marking Fast-Track Investment | Notified body backlogs delay commercial deployment by 8-14 months for novel automation systems. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with fleet operators, OEM procurement directors, and aftermarket service heads; and secondary validation through EU Machinery Directive filings, ECHA substance restriction protocols, and customs trade records for crane component imports. Bottom-up equipment shipment tallies and top-down infrastructure investment forecasts were triangulated to anchor volume estimates.
The projection horizon spans segmentation across product type, end user, capacity class, and installation permanence with regional regulatory exposure as an overlay dimension. CAGRs were derived from replacement cycle compression analysis tied to EU Green Deal compliance deadlines and infrastructure project pipeline assessments. Offshore wind foundation installation schedules and data center construction consortium procurement patterns served as demand-side forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Cohesion Fund allocation levels or accelerated F-Gas Regulation phase-down schedules would require recalibration. Forecasts assume current notified body capacity for CE marking assessments and stable lithium-ion cell supply chains. Revision becomes warranted when battery energy density improvements cross thresholds that eliminate payload-range tradeoffs for mobile crane configurations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Europe Stud Welding Machine Market
Construction Equipment
CNC Lathe Machine Market
Construction Equipment
Middle East and Africa Construction Equipment Market
Construction Equipment
Global Wheel Aligner Equipment Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Backhoes Market
Construction Equipment
Demolition Equipment Market
Construction Equipment
Bulldozer Rental Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Vibratory Plate Compactors Market
Construction Equipment
Tunneling Equipment Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
Assembly Machine Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Latin America Heavy Construction Equipment Market