
 Bulldozer Rental Market | 2026-2036
Bulldozer Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Bulldozer Rental Market Analytics
Certified heavy-equipment operator availability is collapsing across North American construction corridors, forcing contractors toward rental models that bundle trained personnel with machine deployment. United Rentals sustains the industry's broadest branch network, covering over 1,400 locations that reduce mobilization friction for remote earthmoving jobs. H&E Equipment Services anchors its position through captive maintenance infrastructure, keeping rental bulldozers in active-duty cycles rather than idle repair queues. EquipmentShare differentiates via telematics-integrated fleet tracking, giving contractors real-time visibility into undercarriage wear and fuel burn across job sites.
Bulldozer rental denotes the commercial practice of temporarily procuring tracked earthmoving machines—typically weighing 8 to 104 metric tons with blade capacities from 2.3 to 18 cubic meters—for site preparation, grading, and material push operations without capital ownership. Short-term rental commands the largest transaction volume as contractors flex capacity around seasonal infrastructure windows and project-specific soil conditions. Long-term rental and lease-to-own arrangements are gaining structural share among mid-tier construction companies seeking balance-sheet preservation amid interest rate volatility. Large and extra-large bulldozers concentrate margin pools in mining applications, where rental providers command premium day-rates for machines configured with ripper attachments and specialized undercarriage packages.
EPA Tier 4 Final and CARB emissions frameworks in the United States restrict non-compliant diesel bulldozers from operating in federally funded projects, directly steering rental fleet refresh cycles toward newer engine platforms. OSHA excavation safety standards and MSHA surface mining regulations further shape machine specification requirements, mandating rollover protection, operator visibility enhancements, and noise suppression for permitted job sites. Stakeholders must monitor how pending EPA Phase 3 greenhouse gas rules for off-road equipment will compress the residual value of pre-2024 rental fleets and accelerate capital redeployment timing.
Market Dynamics
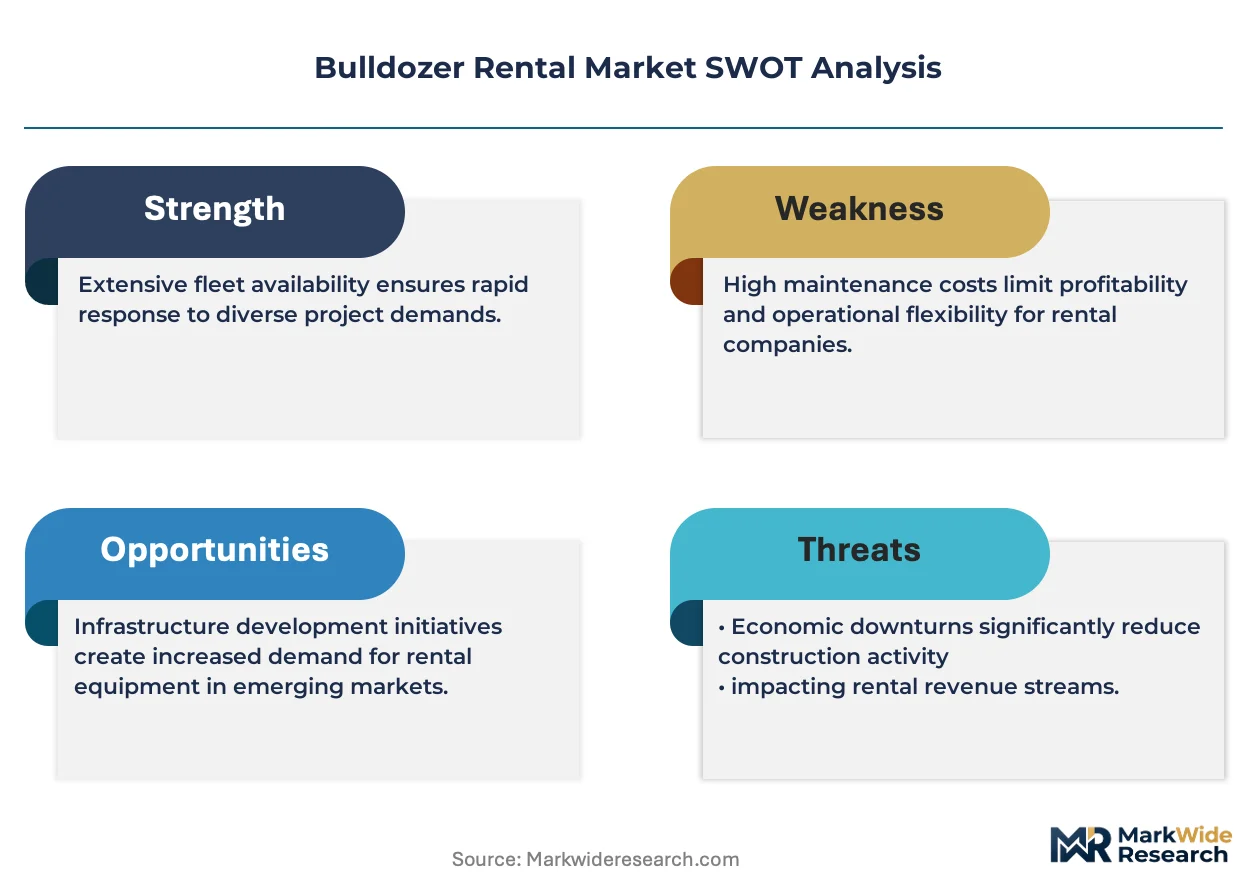
EPA Tier 4 Final emissions mandates are compressing the operational lifespan of legacy diesel bulldozers in federally funded U.S. construction, forcing rental fleets toward accelerated capital redeployment cycles and newer engine platforms that preserve project eligibility.
Growth Catalysts
- Indonesian Infrastructure Pipeline:State-backed highway and dam construction across Kalimantan and Sulawesi is absorbing significant crawler dozer rental capacity, pulling machines from regional pools.
- Emissions Compliance Deadlines:EPA Tier 4 Final standards in the United States restrict non-compliant machines from public works, steering contractors toward rental providers with certified fleets.
- Telematics Integration:Real-time undercarriage wear monitoring and fuel burn tracking is reducing unplanned downtime, extending active-duty cycles for rental bulldozers.
Market Restraints
- Steel and Component Volatility:Fluctuations in high-grade steel prices and hydraulic system components are compressing rental margin structures and complicating fleet expansion timing.
- Operator Certification Bottlenecks:Collapsing availability of certified heavy-equipment operators across North American construction corridors is constraining deployment velocity even when machines are available.
- Residual Value Compression:Pending EPA Phase 3 greenhouse gas rules threaten to accelerate obsolescence of pre-2024 diesel platforms, shortening useful fleet life.
Strategic Opportunities
- Lease-to-Own Structuring:Mid-tier construction companies facing interest rate volatility are migrating toward balance-sheet-preserving rental arrangements that embed purchase options.
- Mining Configuration Premiums:Large and extra-large bulldozers with ripper attachments and specialized undercarriage packages command elevated day-rates in extractive applications.
- Captive Maintenance Infrastructure:Rental providers investing in in-house repair capacity can compress idle queue time and differentiate against competitors reliant on third-party service networks.
Industry Challenges
- MSHA and OSHA Compliance Timelines:Surface mining and excavation safety mandates require rollover protection, visibility enhancements, and noise suppression retrofits that extend machine preparation cycles.
- Legacy Fleet Integration:Contractors operating mixed-age bulldozer populations face spare parts standardization gaps and technician training complexity across electronic and mechanical control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulldozer Rental Market |
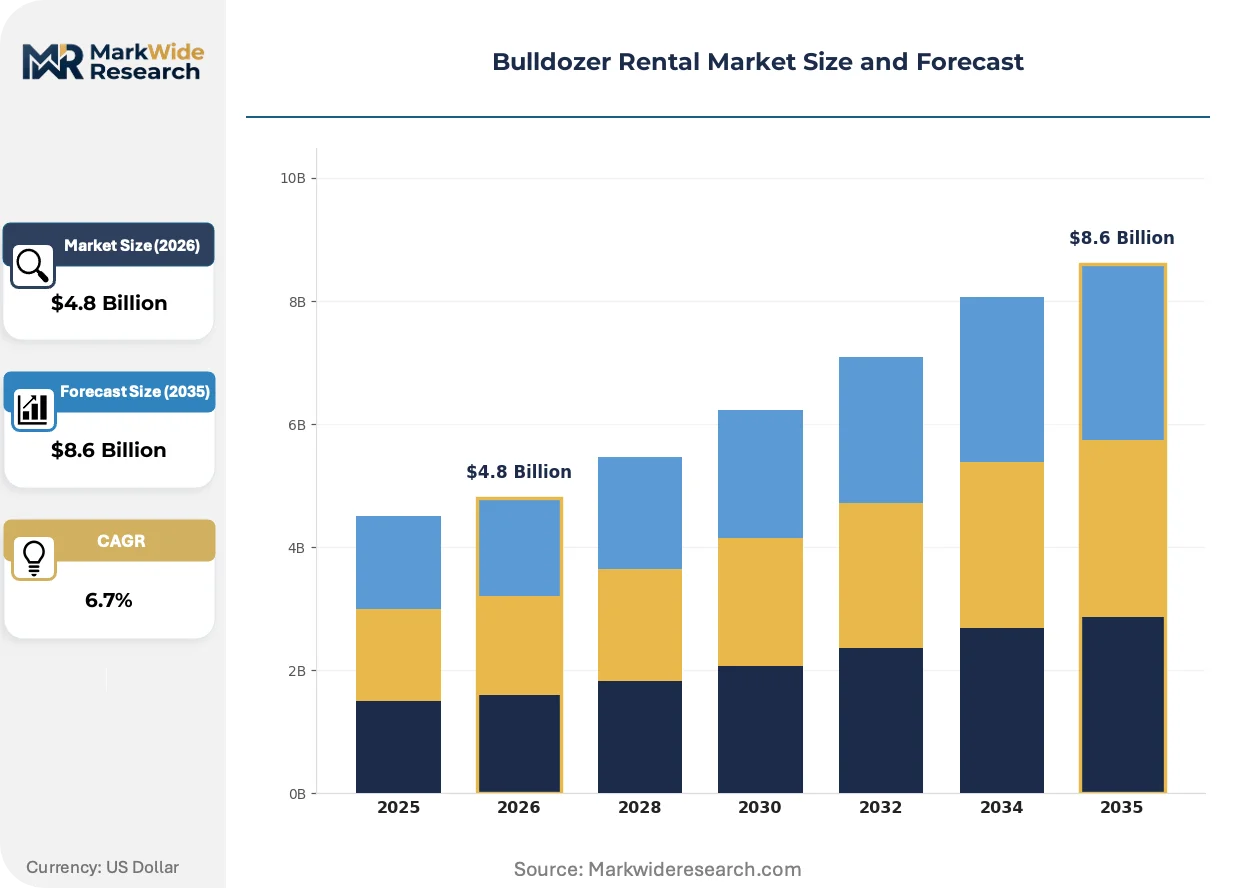
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-term Rental, Long-term Rental, Lease-to-Own, Maintenance Services End User: Construction Companies, Mining Firms, Infrastructure Developers, Landscaping Services Machine Size: Small Bulldozers, Medium Bulldozers, Large Bulldozers, Extra-large Bulldozers Delivery Model: On-site Delivery, Store Pick-up, Direct Shipping, Third-party Logistics |
| Companies Covered | H&E Equipment Services, Neff Rental, United Rentals, Finning International, EquipmentShare, Sunbelt Rentals, Ahern Rentals, HOLT CAT, Herc Rentals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulldozer Rental Market Evolving Landscape
Telematics-enabled fleet visibility and predictive maintenance protocols are restructuring how rental providers manage machine lifecycle value and how contractors optimize earthmoving asset utilization across distributed job sites.
Machine learning algorithms applied to undercarriage wear prediction are decomposing traditional time-based maintenance schedules. Mining contractors in Western Australia and highway builders in Texas are adopting these systems fastest. The shift is compressing preventive maintenance costs and extending mean-time-between-failures for high-duty crawler dozers.
EPA Phase 3 greenhouse gas standards for off-road equipment will tighten carbon intensity thresholds for diesel bulldozers operating in federally funded U.S. projects. Rental fleets must accelerate refresh cycles or face exclusion from public infrastructure contracts. Tier 4 Final-compliant machines are becoming baseline table stakes rather than premium specifications.
Contractors are unbundling operator certification from equipment ownership, driving demand for rental packages that bundle trained personnel with machine deployment. This pattern concentrates in remote earthmoving corridors where mobilization friction is highest. United States infrastructure corridors and Indonesian island developments exhibit the strongest pull for integrated operator-machine rental solutions.
Bulldozer Rental Market Segmentation
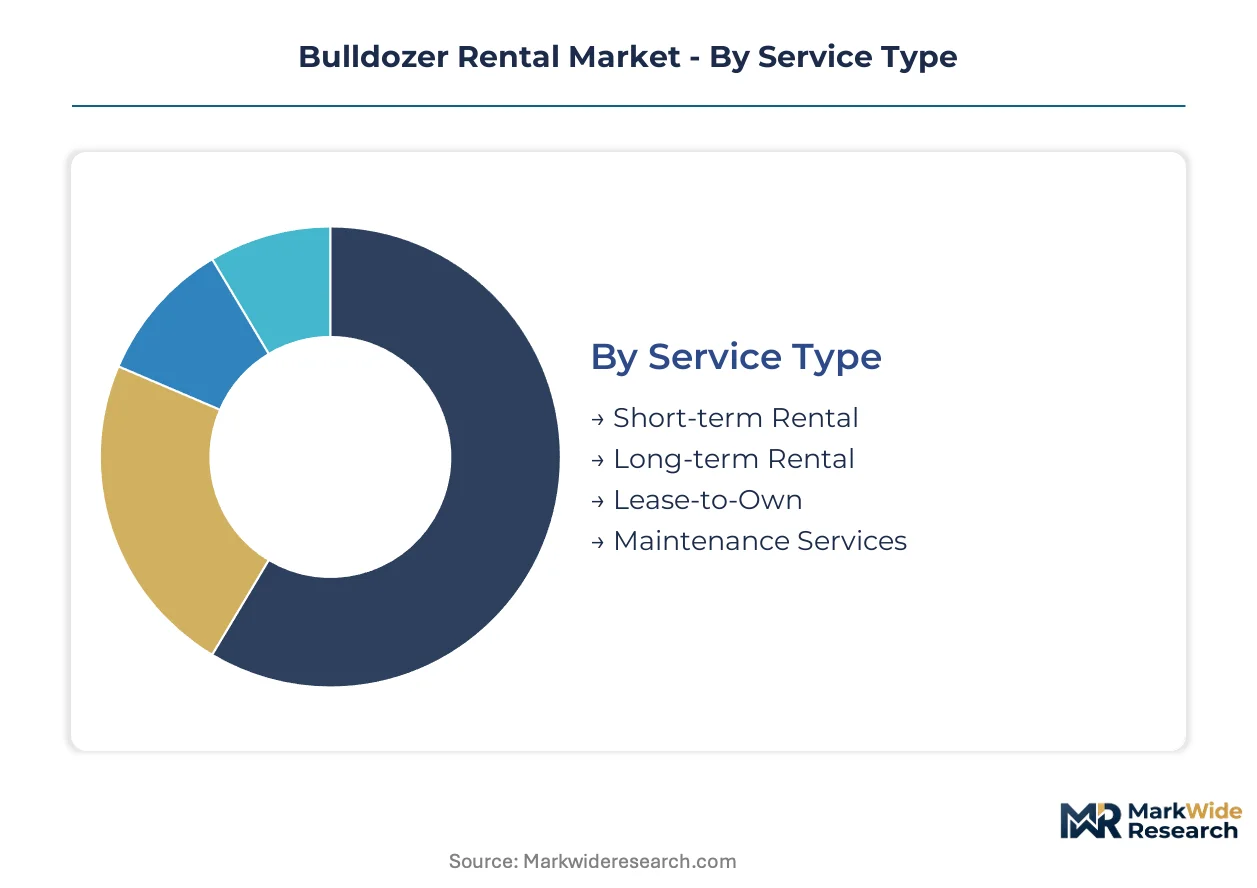
Bulldozer rental segmentation reveals how contractors match machine specifications and contract structures to project duration, soil conditions, and capital constraints. Channel mix varies sharply across service types and delivery models, with remote mining corridors pulling integrated solutions while urban construction favors flexible short-term arrangements.
Service Type:
Short-term rentals flow through branch networks for immediate deployment, while lease-to-own arrangements concentrate in direct sales channels with embedded financing.
- Short-term Rental:Daily to monthly contracts dominate seasonal infrastructure windows and emergency earthmoving needs. Indonesian dam projects in Kalimantan absorb significant crawler dozer capacity through this channel during construction surges.
- Long-term Rental:Multi-year agreements preserve balance sheets amid interest rate volatility. Mid-tier construction companies in Texas highway corridors favor this structure for fleet normalization without ownership risk.
- Lease-to-Own:Embedded purchase options appeal to contractors building permanent earthmoving capabilities. Financing terms track residual value risk from pending EPA Phase 3 rules.
- Maintenance Services:Captive repair infrastructure differentiates providers by compressing idle queue time. H&E Equipment Services anchors market position through this capability.
By volume, Short-term Rental leads. By growth pace, Lease-to-Own is climbing the fastest as contractors seek asset-light expansion paths.
End User:
Cost tier stratification separates mining premium configurations from standard construction specifications, with infrastructure developers occupying the mid-tier value band.
- Construction Companies:General contractors drive transaction velocity through project-specific soil condition matching. EPA Tier 4 Final compliance requirements steer this segment toward certified rental fleets for federally funded work.
- Mining Firms:Extractive operations command premium day-rates for large bulldozers with ripper attachments and specialized undercarriage packages. Western Australian iron ore developments exhibit strongest demand concentration.
- Infrastructure Developers:State-backed highway and dam construction across Southeast Asia pulls machines from regional rental pools. Indonesian government commitments in Sulawesi absorb significant capacity.
- Landscaping Services:Small bulldozer configurations serve residential grading and commercial site preparation. This segment shows highest price sensitivity and seasonal demand fluctuation.
By revenue contribution, Mining Firms generate highest margins per machine. By expansion trajectory, Infrastructure Developers are gaining share fastest on state-backed project pipelines.
Machine Size:
Application requirements dictate size selection, with mining and heavy earthmoving specifying large platforms while urban constraints favor compact configurations.
- Small Bulldozers:Eight to twenty metric ton machines navigate confined residential and commercial sites. Landscaping Services in suburban Texas corridors deploy these for precision grading work.
- Medium Bulldozers:Twenty to forty metric ton platforms balance power and maneuverability for general construction. This specification dominates highway maintenance and municipal earthmoving contracts.
- Large Bulldozers:Forty to seventy metric ton machines concentrate in mining overburden removal and major dam construction. Kalimantan coal operations specify these with reinforced undercarriage packages.
- Extra-large Bulldozers:Seventy to one hundred four metric ton platforms command specialized logistics and operator certification. Surface mining applications in Western Australia and Indonesia absorb limited global production.
By fleet count, Medium Bulldozers dominate rental inventories. By margin expansion, Extra-large Bulldozers show steepest trajectory on configuration premiums and scarcity value.
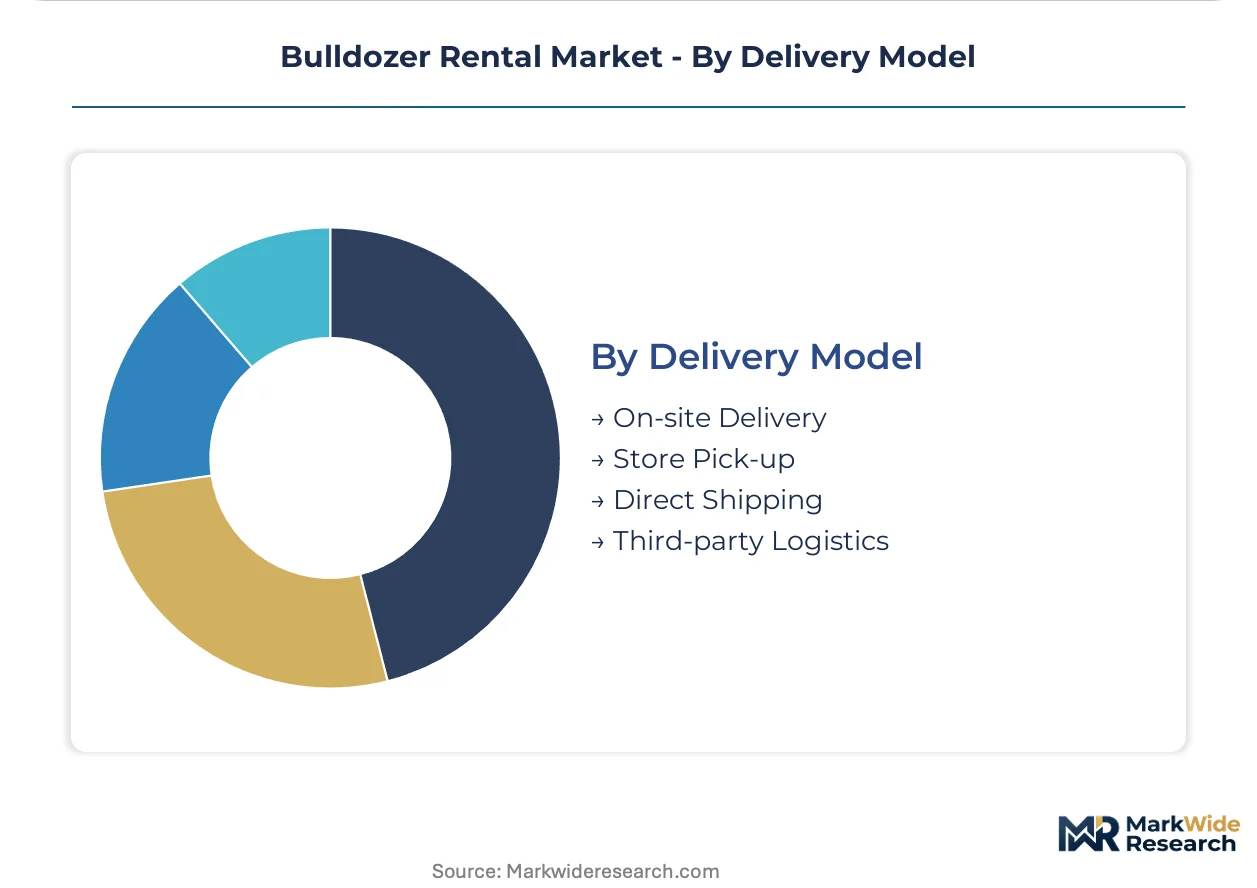
Delivery Model:
Customer type and geography determine channel selection, with remote operations requiring integrated logistics while urban contractors minimize mobilization friction.
- On-site Delivery:Provider-managed transport reduces contractor logistics burden for remote earthmoving jobs. United Rentals leverages its branch network density to compress mobilization timelines.
- Store Pick-up:Contractor-arranged collection suits urban projects with established logistics capabilities. This channel minimizes rental provider overhead and enables price competition.
- Direct Shipping:Manufacturer-coordinated delivery serves specialized mining configurations with factory preparation requirements. Large and extra-large bulldozers flow through this channel for ripper attachment integration.
- Third-party Logistics:Independent transport providers handle overflow capacity and non-standard routing. This model expands during peak construction seasons when captive fleets saturate.
By transaction frequency, Store Pick-up leads. By strategic priority, On-site Delivery is expanding most quickly as providers compete on mobilization speed for remote infrastructure corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 Final standards in the United States are compressing rental fleet refresh cycles, while Indonesian state-backed infrastructure absorbs regional crawler dozer capacity. Demand concentrates in mining corridors and highway construction belts across five major economies.
United States
Federally funded highway maintenance and surface mining operations drive crawler dozer deployment across Texas and the Mountain West. OSHA excavation safety standards and EPA emissions mandates restrict non-compliant machines from public works contracts. Permian Basin oilfield services and Arizona copper extraction sites pull significant rental capacity from Southwest branch networks.
Indonesia
State-backed dam construction in Kalimantan and Sulawesi absorbs substantial crawler dozer rental fleets during construction surges. Government infrastructure commitments prioritize highway connectivity across the archipelago. Mining overburden removal in East Kalimantan coal belts concentrates demand for large bulldozers with reinforced undercarriage packages.
Australia
Western Australian iron ore developments command premium day-rates for extra-large bulldozers configured with ripper attachments. Surface mining regulations administered by state resources departments mandate rollover protection and operator visibility enhancements. Pilbara extraction corridors exhibit fastest adoption of telematics-enabled predictive maintenance systems.
Canada
Alberta oil sands extraction and British Columbia hydroelectric projects sustain demand for heavy earthmoving configurations. Health Canada and provincial environmental regulators enforce noise suppression and emissions standards for permitted job sites. Fort McMurray mining services and Lower Mainland infrastructure corridors anchor regional rental demand.
Germany
Rhineland lignite mining and Bavarian highway maintenance sustain medium and large bulldozer rental volumes. EU Green Deal carbon intensity targets and national emissions standards accelerate fleet refresh toward compliant engine platforms. Ruhr industrial belt earthmoving contractors and Munich metropolitan construction clusters concentrate equipment deployment.
Bulldozer Rental Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding dense branch networks and captive maintenance infrastructure. The middle tier competes on telematics integration and regional fleet specialization. Fragmentation persists among local operators serving single-state or single-province construction corridors. Consolidation pressures favor providers with balance-sheet capacity for emissions-compliant fleet refresh. Strategic partnerships between rental providers and original equipment manufacturers are compressing machine procurement costs.
Among North American integrated rental networks, United Rentals and H&E Equipment Services exemplify scale-driven branch density and captive repair infrastructure respectively. EquipmentShare occupies a position within the telematics-integrated tier, representing providers that differentiate through real-time fleet visibility rather than physical network scale. Sunbelt Rentals and Herc Rentals sit within the diversified industrial equipment tier, anchoring multi-category rental portfolios that cross-sell earthmoving capacity with aerial work platforms and material handling equipment.
| Leading Market Players |
|---|
| H&E Equipment Services |
| Neff Rental |
| United Rentals |
| Finning International |
| EquipmentShare |
| Sunbelt Rentals |
| Ahern Rentals |
| HOLT CAT |
| Herc Rentals |
| Others |
Value Network & Pricing Analysis
Ninety-day engine procurement lead times for EPA Tier 4 Final-compliant powertrains compress rental fleet refresh windows and concentrate pricing power among providers with captive supplier relationships. This inventory dynamic reinforces margin stratification between integrated national networks and regional operators dependent on spot-market component access.
Pricing Analysis
Day-rate spreads between Texas highway corridors and Indonesian mining sites exceed configuration premiums for ripper-equipped extra-large bulldozers. Three-tier pricing structure across premium, standard, and economy levels tracks EPA certification status, with Tier 4 Final machines commanding sustained premiums against pre-compliant inventory. Price differentiation stems from telematics bundling and operator certification inclusion. Landscaping services exhibit highest price sensitivity, while mining firms absorb elevated rates for specialized undercarriage packages.
Supply Chain Analysis
Japan and Germany anchor high-horsepower engine and precision hydraulic component production for rental fleet manufacturers. China supplies steel castings and track assemblies that feed assembly plants in the United States and Indonesia. Component sourcing draws from single-source forging capacity for critical undercarriage parts, creating vulnerability to alloy price spikes. Distribution runs through manufacturer-authorized dealer networks for large mining configurations, while standard construction machines flow through rental provider branch inventories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled predictive maintenance and EPA Phase 3 greenhouse gas compliance deadlines are forcing capital redeployment cycles that favor providers with balance-sheet capacity for fleet refresh.
For Market Incumbents: Compound branch network density in Indonesian infrastructure corridors and Permian Basin oilfield services to capture state-backed project flows. Deepen captive maintenance infrastructure to compress idle queue time against telematics-integrated competitors. Defend margin pools by accelerating Tier 4 Final fleet turnover ahead of residual value compression.
For New Entrants and Emerging Players: Operator certification bundling represents the most penetrable service-layer gap, as collapsing certified heavy-equipment operator availability constrains deployment velocity for established providers. Target remote earthmoving corridors in Sulawesi and Kalimantan where mobilization friction is highest. Lead with integrated operator-machine rental packages rather than asset-only deployment.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because emissions compliance deadlines and telematics infrastructure requirements favor scaled providers with capital access. Acquisition targets should display dense regional branch networks and captive repair capacity. Monitor EPA Phase 3 rulemaking timelines as the signal for fleet refresh acceleration and residual value inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Emissions Compliance Upgrade | EPA Tier 4 Final certification preserves eligibility for federally funded highway and dam construction contracts. |
| Telematics Platform Integration | Real-time undercarriage wear monitoring extends mean-time-between-failures for high-duty crawler dozers in mining applications. |
| Captive Maintenance Infrastructure Expansion | In-house repair capacity differentiates H&E Equipment Services against third-party service network dependence. |
| Lease-to-Own Product Structuring | Embedded purchase options attract mid-tier construction companies seeking balance-sheet preservation amid interest rate volatility. |
| Regional Branch Network Densification | United Rentals leverages 1,400-plus locations to compress mobilization timelines for remote earthmoving jobs. |
Research Methodology
A spread of perspectives from rental fleet managers, construction procurement officers, mining operations directors, and OEM distribution heads converged on the working assumptions driving fleet deployment patterns. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, equipment registration databases, and customs trade records. Bottom-up triangulation across service type, machine size, and end-user segments anchored volume estimates, while top-down macroeconomic cross-checks tested demand elasticity assumptions.
Segmentation dimensions modeled include service type, machine size tier, end-user industry, and delivery model across the projection horizon. CAGRs derived from equipment replacement cycle analysis and infrastructure pipeline tracking. Forecast inputs incorporated EPA regulatory timeline assumptions and Indonesian state-backed project commitment flows.
Underlying assumptions cover emissions compliance adoption curves and steel price stability, with deviation risk concentrated in operator certification bottleneck severity and pending greenhouse gas rule stringency. Recalibration cycles align with material shifts in regulatory deadlines and infrastructure appropriation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Trenchers Market
Construction Equipment
Dock Door Market
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
Industrial Steam Washer Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
Bucket Elevator Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Asia-Pacific Heavy Construction Equipment Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Hose End Sprayers Market
Construction Equipment
Hexagonal Wire Netting Machine Market
Construction Equipment
Cementing Accessories Market