
 Hydraulic Rotary Drilling Rig Market | 2026-2036
Hydraulic Rotary Drilling Rig Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Rotary Drilling Rig Market Insights
Aftermarket service revenue is reconfiguring margin distribution across the hydraulic rotary drilling rig value chain. Epiroc AB leverages its global parts network to capture recurring service contracts. SANY Group Co. Ltd. anchors its competitive stance through integrated manufacturing scale in crawler-mounted platforms. Junttan Oy specializes in foundation drilling applications, occupying a defensible niche in European infrastructure projects.
A hydraulic rotary drilling rig employs a hydraulically powered rotating drill string to bore vertical or directional holes through rock, soil, or overburden, with typical torque ratings from 50 to 500 kNm and mast heights exceeding 25 meters for deep foundation work. The machine serves primarily to create boreholes for piles, water wells, mineral extraction, or hydrocarbon exploration. Crawler-mounted configurations dominate in mining and heavy civil applications where site mobility across unimproved terrain determines equipment selection. Hybrid drive technology is gaining share as contractors face dual pressure from fuel costs and emissions compliance. Energy exploration commands premium pricing but exhibits cyclical demand volatility tied to commodity investment cycles.
The EPA enforces Tier 4 Final diesel emissions standards that effectively bar non-compliant rigs from federal projects and restrict resale liquidity. OSHA drilling safety regulations mandate fall protection, pressure control systems, and operator certification programs that elevate equipment specification thresholds. EU machinery directives through CE marking impose additional conformity requirements for rigs sold into European infrastructure markets. Stakeholders must weigh compliance-driven replacement schedules against extended maintenance strategies as regulatory thresholds tighten without grandfathering relief.
Market Dynamics
EPA Tier 4 Final diesel emissions standards are forcing fleet-wide replacement cycles across North American onshore operations, compressing resale liquidity for non-compliant assets and redirecting capital toward hybrid drive retrofits and new-build acquisitions.
Growth Catalysts
- Pad drilling density:Permian Basin operators in Texas and New Mexico are deploying multi-well pad configurations that maximize rig utilization rates and reduce mobilization downtime between boreholes.
- REACH compliance in Europe:EU machinery directives through CE marking create specification thresholds that favor certified rig suppliers in foundation drilling applications.
- Hybrid drive technology:Dual-power systems combining diesel prime movers with electric assist motors are cutting fuel consumption by a third in high-torque rotary table operations.
Market Restraints
- Steel alloy input volatility:Mast fabrication and Kelly bar production depend on high-strength structural steel grades subject to commodity price swings and mill capacity constraints.
- Hydraulic component supply concentration:Precision piston pumps and closed-loop valve assemblies source predominantly from German and Japanese specialty manufacturers, creating single-source vulnerability.
- Electrification substitution:All-electric top drive systems for shallow geothermal and water well applications are capturing torque segments below 150 kNm.
Strategic Opportunities
- Geothermal expansion in Germany:The country's national energy regulator has streamlined permitting for deep bore heat exchangers, opening foundation rig redeployment into thermal gradient drilling.
- India's PLI scheme for capital goods:Production-linked incentives for domestic manufacturing of construction equipment are attracting crawler rig assembly investments for mining and infrastructure verticals.
- Digital twin convergence:Real-time mast stress monitoring combined with predictive hydraulic failure algorithms is enabling condition-based maintenance contracts.
Industry Challenges
- Mast rigger certification timelines:OSHA fall protection mandates and API derrickman qualification programs are extending crew readiness periods for new rig deployments.
- Legacy SCADA integration:Tier 4 Final engine control modules must interface with decade-old rig management systems, requiring custom protocol gateways that delay commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Rotary Drilling Rig Market |
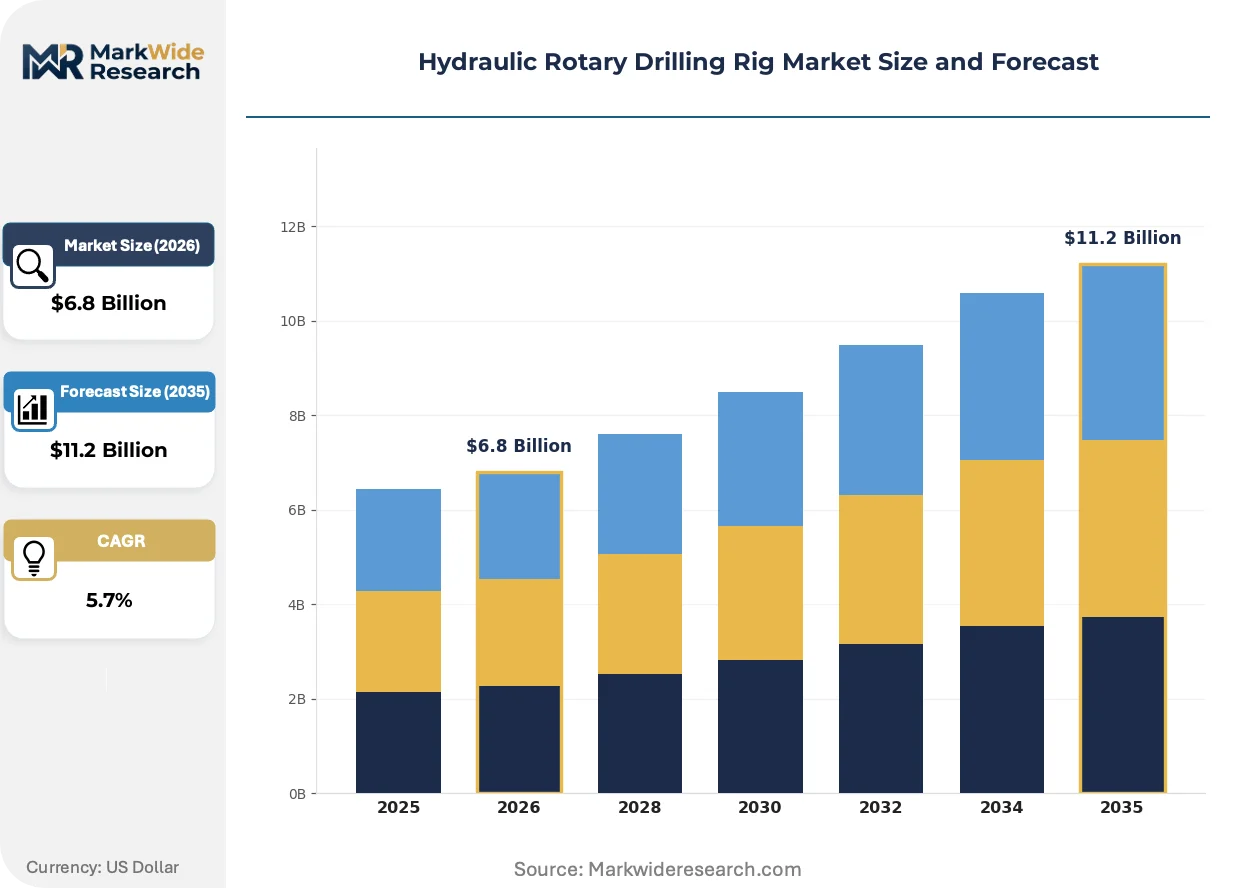
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crawler Mounted, Truck Mounted, Track Mounted, Skid Mounted, Trailer Mounted Technology: Hydraulic Drive, Pneumatic Drive, Electric Drive, Hybrid Drive Application: Construction Projects, Mining Operations, Geotechnical Investigation, Water Well Drilling, Energy Exploration End User: Contractors, Drilling Service Providers, Exploration Companies, Infrastructure Developers |
| Companies Covered | Soilmec S.p.A., Junttan Oy, SANY Group Co. Ltd., Epiroc AB, Delmag GmbH & Co. KG, XCMG, Liebherr-International AG, Zoomlion Heavy Industry Science & Technology Co. Ltd., Caterpillar Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Rotary Drilling Rig Market Trends and Innovations
Automation of pipe handling sequences and real-time downhole telemetry are compressing drilling cycle times while reducing crew exposure to high-risk manual operations.
Automated iron roughnecks and mechanized pipe racking systems are eliminating manual connection makeup in triple-stand operations. Shale operators in the Permian Basin are retrofitting existing rigs with robotic pipe handling at pace, with pad drilling contractors prioritizing units that cut connection time below 90 seconds. This mechanization is rendering obsolete the traditional five-man floor crew model that dominated land rig operations for decades.
EPA Tier 4 Final standards for off-road diesel engines above 751 horsepower now require diesel particulate filters and selective catalytic reduction systems that add weight and cooling load. Rig builders are responding with redesigned engine compartments and auxiliary power units that maintain Tier 4 compliance during idle periods. Deep foundation contractors in Texas face the most acute compliance pressure, as their rigs accumulate engine hours in continuous duty cycles that accelerate maintenance intervals.
Contractors are unbundling aftermarket service contracts from original equipment purchases, selecting third-party hydraulic rebuild shops and independent mast inspection services based on turnaround speed rather than OEM affiliation. This disintermediation is most pronounced in the water well segment, where municipal procurement officers prioritize local service presence over factory-authorized coverage. Equipment lessors in Oklahoma and Kansas report that non-OEM maintenance contracts now capture half of their fleet's annual service spend.
Hydraulic Rotary Drilling Rig Market Segmentation
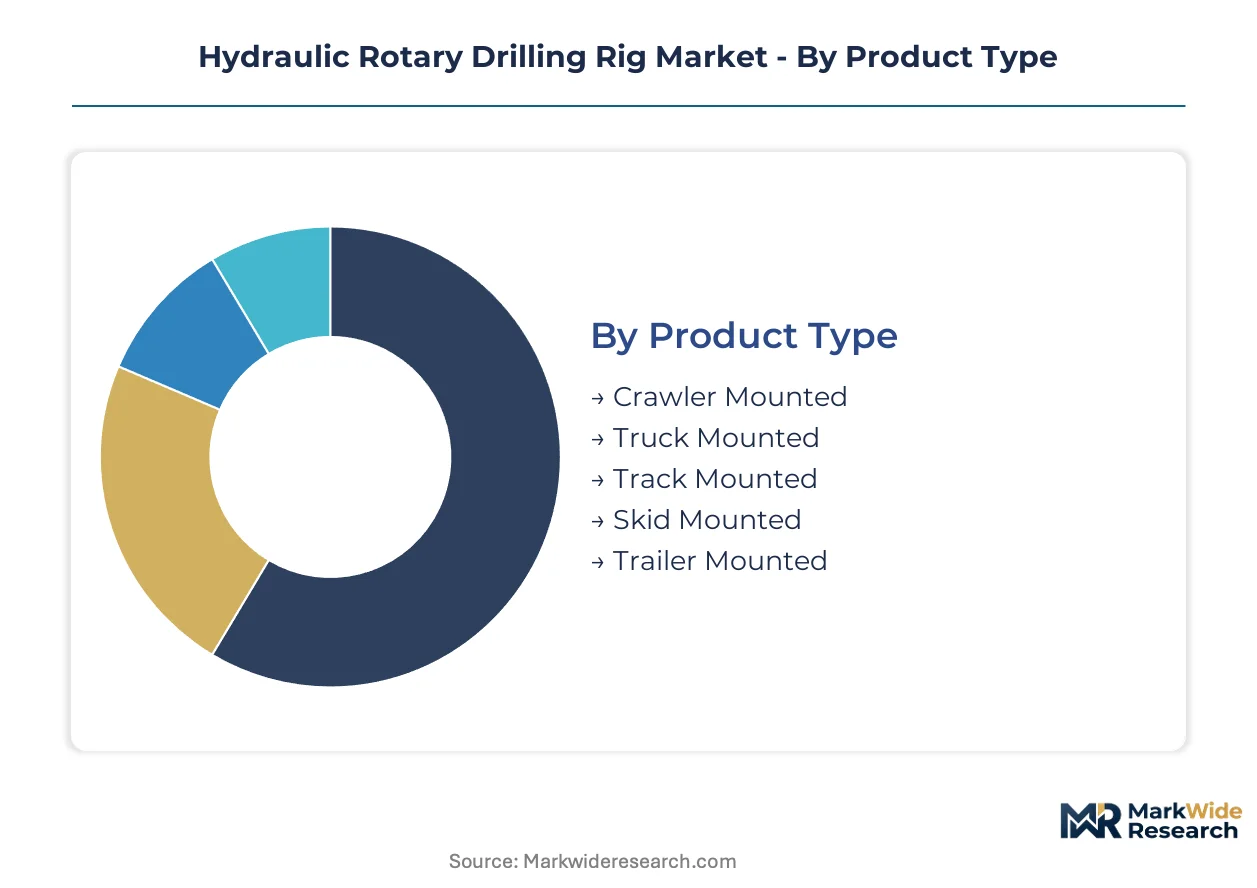
Segmentation in hydraulic rotary drilling rigs reveals how equipment specifications align with terrain constraints, power requirements, and project economics. Contractors select mounting configurations and drive systems based on mobilization frequency, site access, and emissions exposure.
Product Type:
Mature configurations dominate heavy civil and mining applications, while lighter mounting systems serve specialized niches requiring rapid deployment.
- Crawler Mounted:Steel-tracked undercarriages distribute machine weight across soft or uneven ground conditions. Mining contractors in Australia and foundation specialists in Germany specify crawler platforms for continuous duty cycles exceeding 16 hours daily, though transport costs between sites run higher than wheeled alternatives.
- Truck Mounted:Highway-legal chassis integrate drilling masts with commercial truck drivetrains, enabling same-day mobilization between urban job sites. Municipal water well programs in Texas and emergency geotechnical response teams in California prioritize this format for reduced permitting complexity.
- Track Mounted:Rubber-tracked systems bridge the mobility gap between steel crawlers and highway trucks, serving pipeline corridor work and renewable energy foundation projects where ground disturbance must be minimized.
- Skid Mounted:Modular platforms without self-propulsion suit permanent mining installations and offshore platform drilling modules where cranes handle all positioning.
- Trailer Mounted:Lightweight masts on towable frames address residential geothermal loops and shallow environmental monitoring boreholes.
Crawler mounted configurations handle the majority of throughput in mining and heavy foundation verticals; hybrid adaptations of truck mounted units are gaining share fastest in municipal infrastructure.
Technology:
Cost tiers separate established hydraulic systems from emerging electric and hybrid architectures competing on fuel economics and regulatory compliance.
- Hydraulic Drive:Closed-loop piston pumps deliver torque modulation across 50-500 kNm ranges with proven reliability in abrasive drilling conditions. EPA Tier 4 Final retrofit costs and particulate filter maintenance intervals now pressure fleet operators toward replacement rather than upgrade.
- Hybrid Drive:Diesel-electric combinations cut fuel consumption through regenerative braking and optimized engine loading. Foundation contractors in Germany facing the EU Green Deal's emissions benchmarks are deploying hybrid rigs for deep bore heat exchanger programs.
- Electric Drive:Grid-tied or battery-powered top drives eliminate local emissions for indoor mining development and urban construction sites with shore power access.
- Pneumatic Drive:Compressed air systems persist in shallow blast hole drilling and certain water well applications where explosion-proofing overrides efficiency concerns.
Hydraulic drive retains dominant installed base; hybrid drive is climbing the fastest on share as dual-power architectures prove durability in continuous duty cycles.
Application:
Volume concentration in energy and mining contrasts with margin stability in geotechnical and water well segments less exposed to commodity cycles.
- Energy Exploration:Land rigs for oil and gas development command premium day rates but exhibit pronounced demand volatility tied to upstream capital allocation decisions. Pad drilling density in the Permian Basin maximizes utilization per rig deployment.
- Construction Projects:Building foundation piling and infrastructure anchoring generate recurring revenue streams with lower cyclical amplitude. European infrastructure stimulus programs are sustaining rig demand for bridge and transit foundations.
- Mining Operations:Blast hole production drilling and exploration coring require high-availability equipment in remote locations with limited service infrastructure.
- Water Well Drilling:Municipal supply and agricultural irrigation projects favor smaller, more mobile rigs with simplified maintenance protocols.
- Geotechnical Investigation:Site characterization for civil engineering projects demands precision sampling capabilities and rapid mobilization between scattered locations.
Energy exploration represents the largest revenue pool; construction projects offer the steadiest expansion trajectory as infrastructure investment decouples from hydrocarbon price swings.
End User:
Customer type determines procurement patterns, with integrated developers favoring ownership and specialized contractors preferring lease or service-based arrangements.
- Contractors:General construction and specialty foundation firms balance equipment ownership against rental flexibility based on project backlog visibility and balance sheet capacity.
- Drilling Service Providers:Dedicated rig operators compete on crew expertise and equipment uptime, often maintaining mixed fleets across mounting configurations to match diverse client requirements.
- Exploration Companies:Mining and energy firms with in-house drilling capabilities prioritize standardization for supply chain efficiency and crew interchangeability across operations.
- Infrastructure Developers:Public agencies and private concessionaires increasingly bundle drilling services within design-build contracts, reducing direct equipment procurement.
Contractors represent the broadest customer base; drilling service providers are expanding most quickly as project owners outsource specialized capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States show low price elasticity as EPA Tier 4 Final and EU Green Deal mandates force compliance-driven replacement regardless of capital cost, while contractors in India and Mexico remain highly sensitive to upfront equipment pricing despite favorable financing schemes.
United States
Pad drilling density in the Permian Basin of Texas and New Mexico is compressing mobilization downtime and maximizing rig utilization rates. EPA Tier 4 Final emissions standards bar non-compliant rigs from federal projects and restrict resale liquidity, forcing fleet-wide replacement cycles. Houston anchors the largest concentration of drilling service providers and rig lessors, with Oklahoma City emerging as a secondary hub for water well and geothermal retrofit activity.
Germany
The national energy regulator has streamlined permitting for deep bore heat exchangers, opening foundation rig redeployment into thermal gradient drilling for district heating networks. EU machinery directives through CE marking impose conformity requirements that favor certified rig suppliers in European infrastructure markets. The Rhine-Ruhr industrial corridor concentrates demand from foundation contractors serving bridge and transit projects, while Bavaria hosts specialized manufacturers of precision hydraulic components.
China
Dual carbon goals under MEE oversight are accelerating hybrid drive adoption in mining and heavy civil applications where continuous duty cycles dominate. GB standards for construction machinery safety are elevating specification thresholds for crawler-mounted platforms in domestic infrastructure programs. Xuzhou in Jiangsu Province anchors integrated manufacturing clusters for crawler rig assembly, with Sany and XCMG headquarters driving captive supply chain concentration.
India
The PLI scheme for capital goods is attracting crawler rig assembly investments for mining and infrastructure verticals, offsetting price sensitivity through production-linked incentives. BIS certification requirements for construction equipment are creating specification barriers that favor domestic fabricators over imported units. Maharashtra and Gujarat concentrate demand from metro rail and highway foundation projects, with Mumbai-Pune corridor contractors prioritizing rapid-mobilization truck-mounted configurations.
Australia
Iron ore and coal mining operations in Western Australia and Queensland require high-availability equipment in remote locations with limited service infrastructure. The country's national mining safety regulator enforces fall protection and pressure control mandates that elevate equipment specification thresholds. Perth anchors the largest fleet of blast hole production rigs serving Pilbara Basin operations, with Brisbane emerging as a hub for exploration coring contractors.
Hydraulic Rotary Drilling Rig Market Competitive Landscape
Integrated conglomerates and specialized foundation equipment fabricators split the market along application lines, with scale-driven players dominating mining and energy verticals while niche specialists capture margin in geotechnical and infrastructure segments. The vendor base concentrates among three strategic archetypes: diversified heavy machinery conglomerates with captive component supply, pure-play drilling rig specialists with regional service density, and emerging Asian fabricants leveraging integrated manufacturing scale. Competitive moves center on hybrid drive technology licensing and aftermarket service contract unbundling as contractors prioritize turnaround speed over OEM affiliation.
Within the diversified conglomerate tier, Caterpillar Inc. and Liebherr-International AG exemplify scale-driven positioning across multiple equipment categories. Epiroc AB occupies a position within the mining-focused specialist archetype, while SANY Group Co. Ltd. and XCMG represent the integrated manufacturing scale model emerging from Chinese industrial clusters. Junttan Oy sits within the European foundation specialist segment, and Soilmec S.p.A. anchors Italian engineering heritage in crawler-mounted platform design.
| Leading Market Players |
|---|
| Soilmec S.p.A. |
| Junttan Oy |
| SANY Group Co. Ltd. |
| Epiroc AB |
| Delmag GmbH & Co. KG |
| XCMG |
| Liebherr-International AG |
| Zoomlion Heavy Industry Science & Technology Co. Ltd. |
| Caterpillar Inc. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese crawler rig assembly clusters is compressing supplier pricing power while elevating buyer leverage in procurement negotiations across Asia-Pacific markets. Tier 4 Final compliance costs in North America and EU Green Deal benchmarks in Europe are simultaneously pulling pricing premiums for certified configurations, creating divergent margin trajectories by geography.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture as contractors unbundle maintenance from original equipment purchases. Three-tier pricing structure across premium, standard, and economy levels separates OEM-authorized service networks from independent hydraulic rebuild shops and local inspection providers. Cost compression in the standard tier is intensifying because municipal water well programs prioritize turnaround speed over factory certification. Drilling service providers in Oklahoma and Kansas exhibit highest price sensitivity; integrated mining operators in Western Australia show lowest elasticity due to uptime penalties.
Supply Chain Analysis
Bosch Rexroth, Kawasaki Precision Machinery, and Linde Hydraulics hold concentrated capacity for closed-loop piston pumps and valve assemblies serving rig OEMs. High-strength structural steel for mast fabrication draws from German and Japanese mill networks, while precision castings for Kelly bar production rest on Chinese and Italian foundry capacity. Single-source vulnerability in hydraulic component sourcing creates exposure to German and Japanese export licensing shifts. Distribution runs through captive OEM service networks in mining verticals and independent dealers in municipal infrastructure segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as hybrid drive adoption penetrates foundation drilling verticals previously locked in pure hydraulic architectures. Pad drilling density in Permian Basin shale operations is accelerating rig utilization rates and shortening replacement cycles.
For Market Incumbents: Pre-empt all-electric substitution in shallow geothermal and water well segments below 150 kNm by accelerating hybrid drive licensing to European foundation contractors. Secure backward integration into precision hydraulic component supply through captive sourcing agreements with German and Japanese specialty manufacturers. Anchor certification investment in EU machinery directives through CE marking to defend margin position against emerging Asian fabricants.
For New Entrants and Emerging Players: Build out rapid-mobilization truck-mounted configurations for India's metro rail and highway foundation projects, leveraging PLI scheme incentives to offset domestic price sensitivity. Target geothermal expansion in Germany where streamlined permitting for deep bore heat exchangers is redeploying foundation rig capacity. Pursue third-party aftermarket service contracts unbundled from OEM affiliations, prioritizing turnaround speed over factory authorization in municipal water well segments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hybrid drive technology licensing as dual-power architectures achieve scale validation in continuous duty cycles. Long-term viability favors specialized foundation equipment fabricators with regional service density over diversified conglomerates exposed to mining and energy commodity volatility. Monitor EPA enforcement discretion on Tier 4 Final resale liquidity restrictions as inflection indicator for North American replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Drive Technology Licensing | Dual-power architectures cut fuel consumption by a third in high-torque rotary table operations. |
| Aftermarket Service Contract Unbundling | Independent hydraulic rebuild shops capture half of fleet annual service spend in Oklahoma and Kansas. |
| Digital Twin Convergence | Real-time mast stress monitoring enables condition-based maintenance contracts with predictive failure algorithms. |
| Geothermal Rig Redeployment | German foundation contractors redeploy crawler platforms into deep bore heat exchanger programs. |
| PLI Scheme Assembly Investment | Production-linked incentives attract crawler rig investments for Maharashtra and Gujarat infrastructure verticals. |
Research Methodology
Initial hypotheses were tested against primary input from rig fleet managers, foundation drilling contractors, hydraulic component procurement leads, and aftermarket service heads, then refined through secondary validation. Primary interviews captured equipment specification priorities, replacement cycle timing, and unbundled service procurement patterns. Secondary sources included EPA engine certification databases, EU machinery directive conformity records, customs trade data for high-strength steel imports, and SEC filings from diversified equipment manufacturers. Bottom-up rig deployment counts by basin and application were triangulated against top-down energy and infrastructure capital expenditure projections.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling rig fleet expansion against replacement cycle compression from emissions compliance mandates. Segmentation dimensions included mounting configuration, drive technology architecture, application vertical, end-user procurement pattern, and regional regulatory cluster. CAGRs were derived from rig count trajectories and day rate elasticity modeling. Forecast inputs incorporated Permian Basin pad drilling density trends and EU Green Deal emissions benchmark implementation pacing.
Stress conditions across steel alloy input volatility, hydraulic component supply disruption, and electrification substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement continuity and commodity investment cycle amplitude. Quarterly review of EPA Tier 4 Final compliance timelines and EU machinery directive amendment proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
CNC Polishing Machines Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Benelux Metal Fabrication Equipment Market
Construction Equipment and Machinery
Concrete Block Making Machines Market
Construction Equipment and Machinery
Global Construction Machinery Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Engineering Machinery Counterweight Iron Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
Australia Conveyor Maintenance Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Friction Stir Welding Equipment Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Africa Heavy Construction Equipment Rental Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market