
 CNC Lathe Machine Market | 2026-2036
CNC Lathe Machine Market Size, Share, and Industry Trends Forecast 2026-2036
CNC Lathe Machine Market Insights
Job shops and small-batch manufacturers are unwinding decades of reliance on general-purpose equipment, redirecting capital toward multi-tasking CNC lathes that combine milling and turning in single setups. DMG Mori leverages its integrated spindle and control technology to capture premium contracts from medical device makers requiring sub-micron repeatability. Haas Automation anchors the mid-market segment with standardized vertical lathe configurations that compress delivery lead times for North American automotive tier suppliers. Yamazaki Mazak competes through its iSMART factory connectivity platform, which extends machine uptime monitoring to remote job shop operators.
A CNC lathe machine rotates workpieces against fixed cutting tools to remove material and produce cylindrical, conical, or threaded geometries with programmed precision, typically achieving positional accuracies within 0.005 millimeters under ISO 230-2 test conditions. Horizontal lathe configurations dominate volume shipments to high-throughput automotive OEMs, where steel and aluminium powertrain shafts require uninterrupted production cycles. Multi-tasking platforms represent the fastest-expanding product category as aerospace manufacturers consolidate five-axis milling and turning operations to reduce work-in-process inventory. Electric drive technology leads new order intake, displacing hydraulic systems in medical device machining where oil-free environments prevent titanium implant contamination.
ISO standards govern machine tool accuracy verification and safety interlocks, while CE marking mandates compliance with EU Machinery Directive electromagnetic compatibility and emergency stop requirements for European market access. Japan's METI enforces JIS B 6191 geometric precision benchmarks that effectively filter lower-tier Chinese builders from supplying Japanese automotive supply chains. Stakeholders must monitor how NMPA medical device registration rules in China and FDA quality system regulations in the United States reshape titanium and plastic component machining specifications across their installed base decisions.
Market Dynamics
Multi-tasking platform adoption is restructuring capital allocation across precision manufacturing, forcing job shops to consolidate five-axis milling and turning operations into single-setup workflows that compress work-in-process inventory.
Growth Catalysts
- ISO 230-2 Accuracy Mandates:Stricter geometric precision verification in Germany, Japan, and the United States is disqualifying legacy equipment from certified supplier pools, accelerating replacement cycles among automotive tier-one manufacturers.
- Electric Drive Conversion:Oil-free machining environments are becoming mandatory for titanium implant production, pulling medical device OEMs away from hydraulic systems toward servo-electric spindle technology.
- Shenzhen-Shanghai Industrial Clustering:China's domestic aerospace supply chain expansion is concentrating demand for multi-tasking platforms around these manufacturing hubs, creating localized scale effects for machine builders.
Market Restraints
- Controller Chip Supply Concentration:Dependence on Taiwanese and German industrial semiconductor suppliers creates vulnerability in CNC control system availability, extending machine delivery timelines.
- Ball Screw and Linear Guide Input Costs:Precision motion components face price volatility tied to specialty steel alloys and rare earth magnet materials, squeezing margin structures for mid-market equipment.
- JIS B 6191 Compliance Barriers:Japan's geometric precision benchmarks effectively block lower-tier Chinese builders from penetrating Japanese automotive supply chains, limiting market access.
Strategic Opportunities
- India's PLI Scheme for Manufacturing:Production-linked incentives for precision engineering sectors are creating first-mover advantages for CNC lathe vendors establishing localized assembly and service infrastructure.
- AI-Enabled Predictive Maintenance Convergence:Integration of machine learning algorithms with spindle vibration monitoring is opening subscription-based uptime guarantee models for remote job shop operators.
- Remanufacturing Channel Development:Certified rebuild programs for legacy horizontal lathes are capturing price-sensitive buyers in Mexico and Eastern European automotive supply chains.
Industry Challenges
- Multi-Axis Programming Skill Scarcity:Shortages of operators capable of simultaneous five-axis CAM programming are limiting utilization rates of advanced multi-tasking installations.
- CE Marking Certification Timelines:EU Machinery Directive compliance documentation for electromagnetic compatibility and safety interlocks extends product launch schedules by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNC Lathe Machine Market |
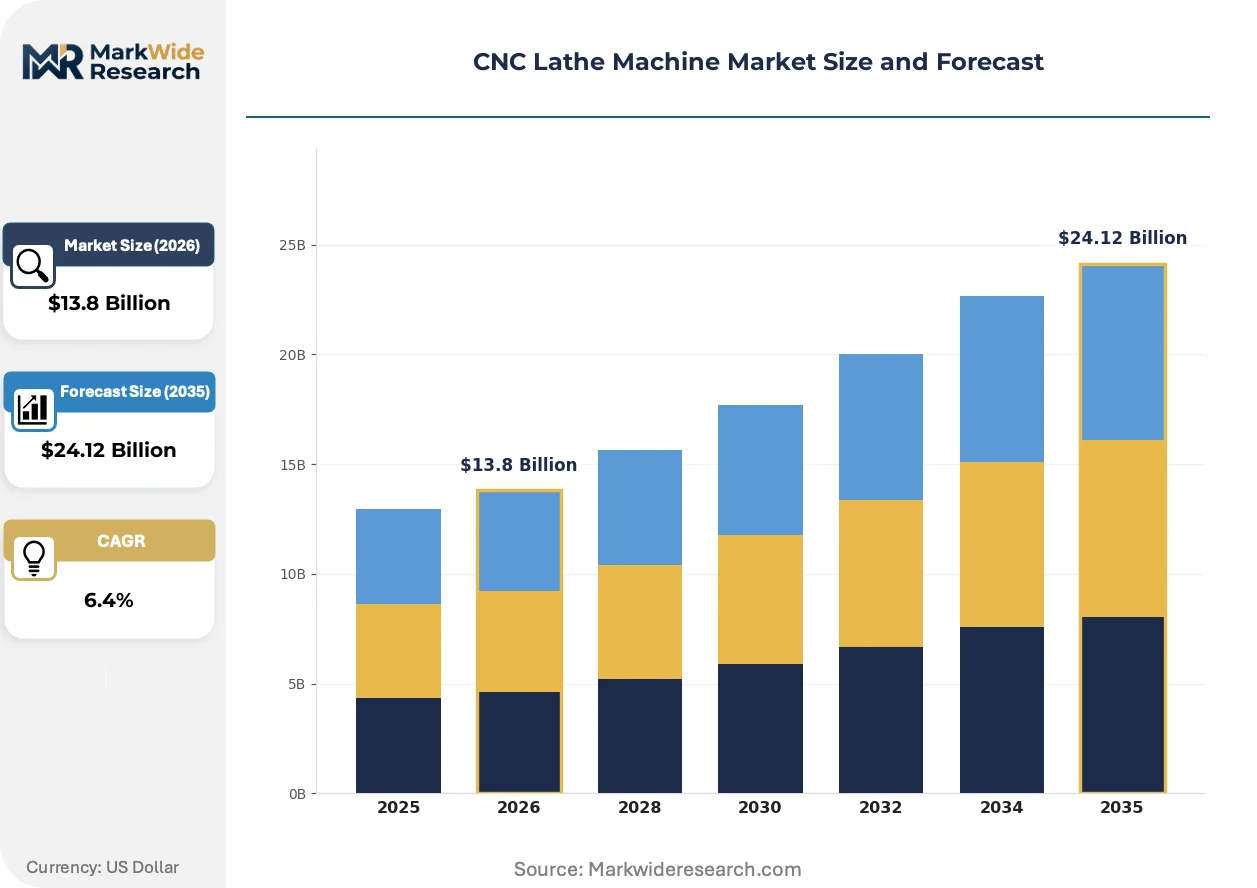
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Multi-Tasking, Specialty End User: Aerospace, Automotive OEMs, Medical Devices, Railways Material: Aluminium, Steel, Titanium, Plastic Technology: Hydraulic, Electric, Hybrid, CNC Control |
| Companies Covered | DMG Mori, Haas Automation, Yamazaki Mazak, Okuma Corporation, FANUC, Makino Milling Machine, Hurco Companies, JTEKT Corporation, Hardinge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNC Lathe Machine Market Trends and Innovations
Digital thread integration is redefining how machine tool data flows into manufacturing execution systems, compressing the feedback loop between shop-floor performance and production planning.
Hybrid additive-subtractive manufacturing is decomposing traditional boundaries between CNC turning and metal deposition processes. Aerospace engine manufacturers are piloting laser cladding heads mounted on multi-tasking platforms to repair and build up worn turbine blade roots in single setups. This convergence is collapsing separate capital equipment budgets for repair and new production into unified procurement decisions.
REACH substance restrictions on coolant biocides and lubricant additives are forcing reformulation of metalworking fluid chemistries across European installations. Machine builders must now validate spindle seal compatibility with new synthetic ester bases, adding qualification overhead for CE-marked equipment. Medical device machining cells in Ireland and Switzerland are responding by accelerating closed-loop minimum quantity lubrication adoption.
Service contract unbundling is fragmenting how job shops acquire machine uptime. Tier-one automotive suppliers in Michigan and South Carolina are separating preventive maintenance from spindle rebuild coverage, negotiating point solutions with independent service providers rather than captive OEM networks. This disaggregation is most pronounced among high-volume powertrain manufacturers running three-shift operations on standardized horizontal lathe configurations.
CNC Lathe Machine Market Segmentation
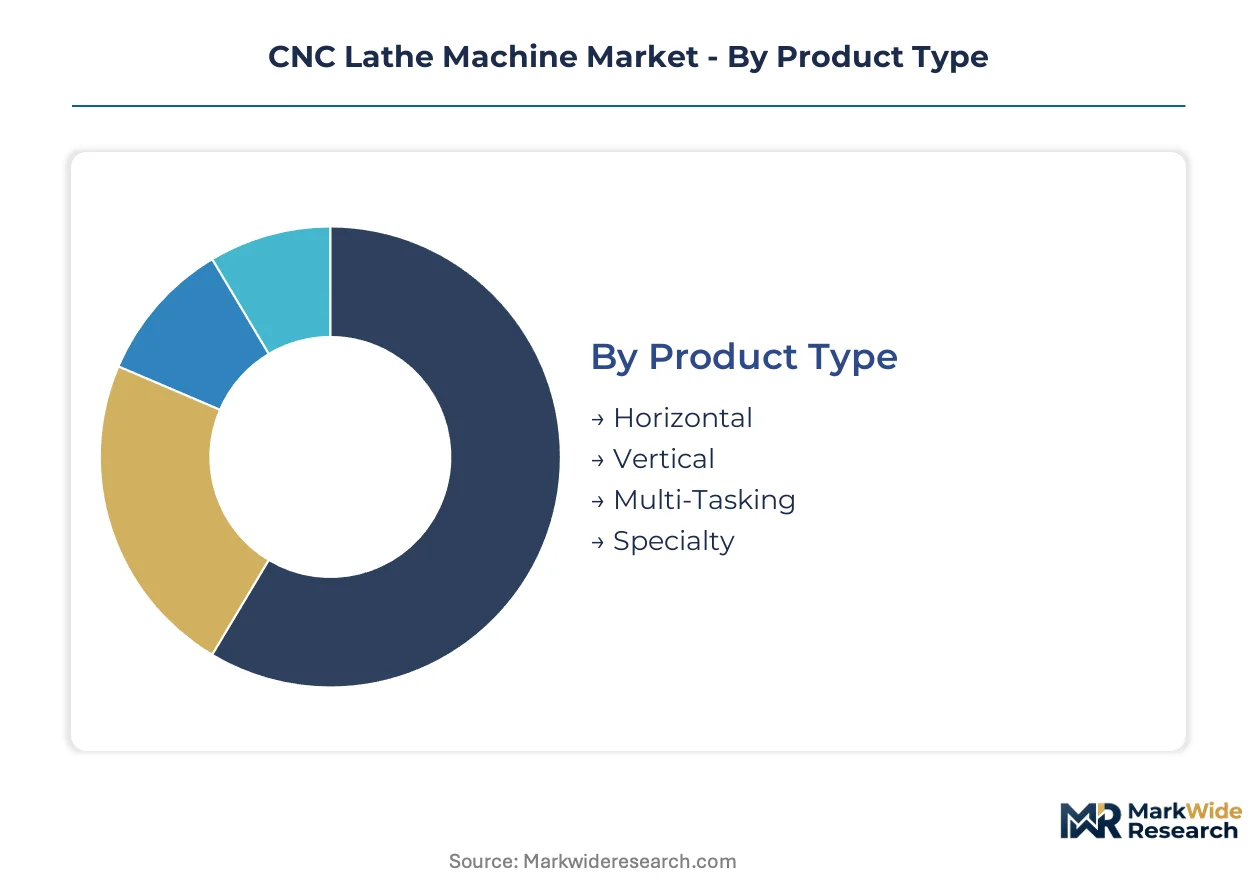
Segmentation in CNC lathe procurement reveals how regulatory compliance, material specifications, and automation requirements reshape capital allocation across precision manufacturing verticals. Understanding these divides exposes where technology premiums command pricing power versus where standardization drives volume.
Product Type:
ISO 230-2 geometric verification standards and CE marking safety interlocks create divergent compliance burdens across configurations, with multi-axis platforms facing extended certification timelines in European markets.
- Horizontal:Spindle-mounted workpieces rotate parallel to the floor, enabling gravity-assisted chip evacuation and continuous production cycles. Automotive OEMs in Germany and the United States concentrate demand here for steel powertrain shaft machining, where uninterrupted throughput outweighs setup flexibility requirements.
- Multi-Tasking:Integrated five-axis milling and turning capabilities consolidate operations into single setups, collapsing work-in-process inventory for complex geometries. Aerospace manufacturers in China's Shenzhen-Shanghai corridor are accelerating adoption of these platforms to meet domestic supplier qualification deadlines for commercial aircraft programs.
- Vertical:Gravity-reinforced clamping suits heavy disc and flange components, with standardized configurations compressing delivery timelines for North American automotive tier suppliers.
- Specialty:Configurations include Swiss-type sliding headstock designs for long slender medical device components and wheel lathes for railway maintenance depots.
Established volume favors Horizontal; emerging adoption favors Multi-Tasking.
End User:
Customer procurement maturity spans from price-sensitive commodity machining to specification-driven certified supplier relationships, with regulatory stringency determining technology tier selection.
- Automotive OEMs:High-throughput powertrain production demands 24/7 equipment utilization, with JIS B 6191 compliance filtering supplier pools in Japanese supply chains. Tier-one manufacturers prioritize electric drive systems for energy recovery and reduced maintenance intervals.
- Medical Devices:FDA quality system regulations and NMPA registration rules mandate oil-free machining environments for titanium implant production, pulling demand toward servo-electric spindle technology with sub-micron repeatability verification.
- Aerospace:Dual-carbon goals in China's domestic programs and FAA certification requirements in the United States drive multi-tasking platform investment for complex structural components.
- Railways:Wheel reprofiling and axle turning operations favor robust horizontal configurations with hardened guideways for abrasive cast iron machining.
Procurement scale concentrates with Automotive OEMs; specification intensity peaks with Medical Devices.
Material:
Workpiece metallurgy dictates cutting parameter envelopes, thermal management requirements, and coolant system architectures across machine configurations.
- Steel:Ferrous alloys dominate automotive powertrain applications, with high-torque spindles and rigid box-way construction prioritizing chip volume over surface speed.
- Titanium:Low thermal conductivity and work-hardening tendencies demand controlled cutting speeds and specialized minimum quantity lubrication systems for medical implant machining in Switzerland and Ireland.
- Aluminium:High-speed spindles with through-tool coolant delivery suit aerospace structural components, where chip evacuation speed determines cycle time economics.
- Plastic:Medical device housings and precision gears require reduced cutting forces and temperature control to prevent melting or residual stress accumulation.
Volume throughput anchors Steel; value-added margins concentrate in Titanium.
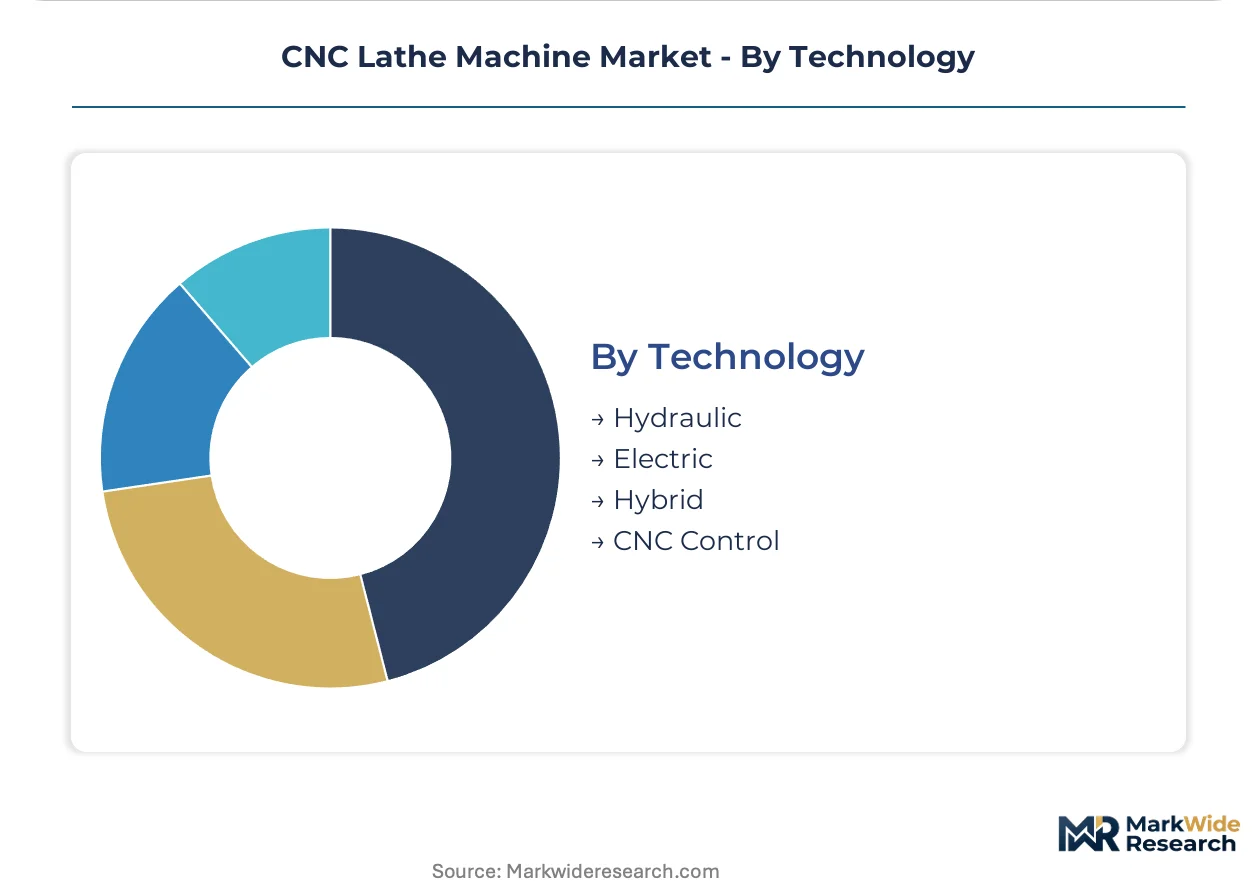
Technology:
Drive system selection determines energy efficiency, environmental compliance, and maintenance cost structures across end-use verticals.
- Electric:Servo motor and ball screw architectures eliminate hydraulic oil contamination risks, satisfying FDA and NMPA requirements for implant-grade titanium machining while enabling regenerative braking energy recovery.
- CNC Control:Integrated motion controllers with real-time tool path optimization and factory connectivity protocols form the intelligence layer across all drive configurations, with semiconductor supply concentration from Taiwanese and German suppliers creating availability vulnerabilities.
- Hydraulic:Legacy systems persist in heavy roughing applications where stall torque density exceeds electric motor capabilities, though REACH substance restrictions on hydraulic fluids accelerate replacement in European installations.
- Hybrid:Combinations reserve hydraulic clamping and tailstock pressure for specific operations while converting spindle and axis drives to electric architectures.
Replacement cycles favor Electric; installed base inertia sustains Hydraulic in select applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine tool builders cluster their assembly capacity near precision component demand, with regulatory compliance requirements fragmenting procurement patterns across national supply chains.
China
Domestic aerospace programs and electric vehicle powertrain investments concentrate demand for multi-tasking platforms. NMPA medical device registration rules tighten machining specifications for titanium implants. Shenzhen and Shanghai industrial corridors host local builders scaling five-axis platforms for commercial aircraft suppliers.
Germany
Automotive OEMs and tier-one suppliers drive replacement cycles for ISO 230-2 certified equipment. CE marking under the EU Machinery Directive extends product launch timelines for electromagnetic compatibility validation. Bavaria and Baden-Württemberg machine tool clusters supply precision equipment across European automotive supply chains.
United States
FAA certification requirements for aerospace structural components pull investment toward sub-micron repeatability systems. FDA quality system regulations govern titanium implant machining specifications for medical device OEMs. Michigan and South Carolina automotive corridors standardize on horizontal lathe configurations for three-shift powertrain production.
Japan
METI enforces JIS B 6191 geometric precision benchmarks that filter supplier pools for domestic automotive manufacturers. Electric drive conversion accelerates as servo-electric spindles displace hydraulic systems in medical device machining. Chubu and Kansai industrial regions concentrate high-precision platform manufacturing for export markets.
India
PLI scheme incentives for precision engineering sectors attract machine tool vendors establishing localized assembly infrastructure. BIS standards adoption lags behind ISO benchmarks, creating certification gaps for premium equipment imports. Maharashtra and Gujarat industrial clusters absorb mid-market vertical lathe shipments for automotive component suppliers.
CNC Lathe Machine Market Competitive Landscape
Concentration sits with diversified machinery conglomerates and specialized precision equipment builders. The vendor base spans Japanese integrated manufacturers, German engineering specialists, and North American mid-market standardizers. Three archetypes dominate: premium precision specialists commanding medical and aerospace specifications, mid-market volume players compressing delivery timelines through configuration standardization, and connectivity-focused builders embedding factory automation platforms. Competitive positioning hardens around M&A consolidation of control system capabilities and geographic expansion into India's PLI-subsidized manufacturing corridors.
Among Japanese precision machinery builders, DMG Mori, Yamazaki Mazak, and Okuma Corporation exemplify the premium-tier archetype. These integrated manufacturers occupy positions where sub-micron repeatability verification and factory connectivity platforms anchor customer relationships. DMG Mori represents the spindle and control technology convergence strategy. Yamazaki Mazak sits within the digital factory connectivity vector. Okuma Corporation anchors the dual-track approach combining proprietary control architectures with multi-tasking platform development.
| Leading Market Players |
|---|
| DMG Mori |
| Haas Automation |
| Yamazaki Mazak |
| Okuma Corporation |
| FANUC |
| Makino Milling Machine |
| Hurco Companies |
| JTEKT Corporation |
| Hardinge |
| Others |
Pricing and Supply Chain Analysis
Electric spindle displacement of hydraulic drive systems reconfigures sourcing geography toward Taiwanese and German semiconductor suppliers while compressing margin structures for mid-market builders unable to absorb servo motor cost premiums. This substitution dynamic simultaneously elevates pricing power among integrated control technology vendors and exposes price-sensitive automotive tier suppliers to extended delivery timelines.
Pricing Analysis
ISO 230-2 geometric precision verification dictates the pricing tier structure across the CNC lathe market, separating premium multi-tasking platforms with sub-micron repeatability from standardized horizontal configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and factory connectivity bundling, with medical device OEMs showing least price sensitivity due to FDA and NMPA compliance mandates. Cost compression in the economy tier is intensifying because Chinese domestic builders scale five-axis platforms for aerospace suppliers. Automotive tier-one manufacturers in Germany and the United States exhibit highest price sensitivity, prioritizing throughput per capital dollar over advanced capability sets.
Supply Chain Analysis
Extended machine delivery timelines now stretch eighteen to twenty-four months as controller chip inventory depletes across Taiwanese and German industrial semiconductor suppliers. Precision motion components draw from specialty steel alloy foundries in Japan and Germany alongside rare earth magnet processors in China, creating multi-node geographic concentration. Single-source vulnerability sits with ball screw and linear guide suppliers facing rare earth price volatility. Distribution runs through captive OEM service networks for premium installations, while independent distributors and remanufacturing channels capture mid-market replacement demand in Mexico and Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CNC lathe market is recovering from a cyclical trough as automotive OEMs accelerate powertrain equipment replacement cycles and aerospace suppliers consolidate machining operations. Capital expenditure normalization across precision manufacturing verticals supports this recovery trajectory.
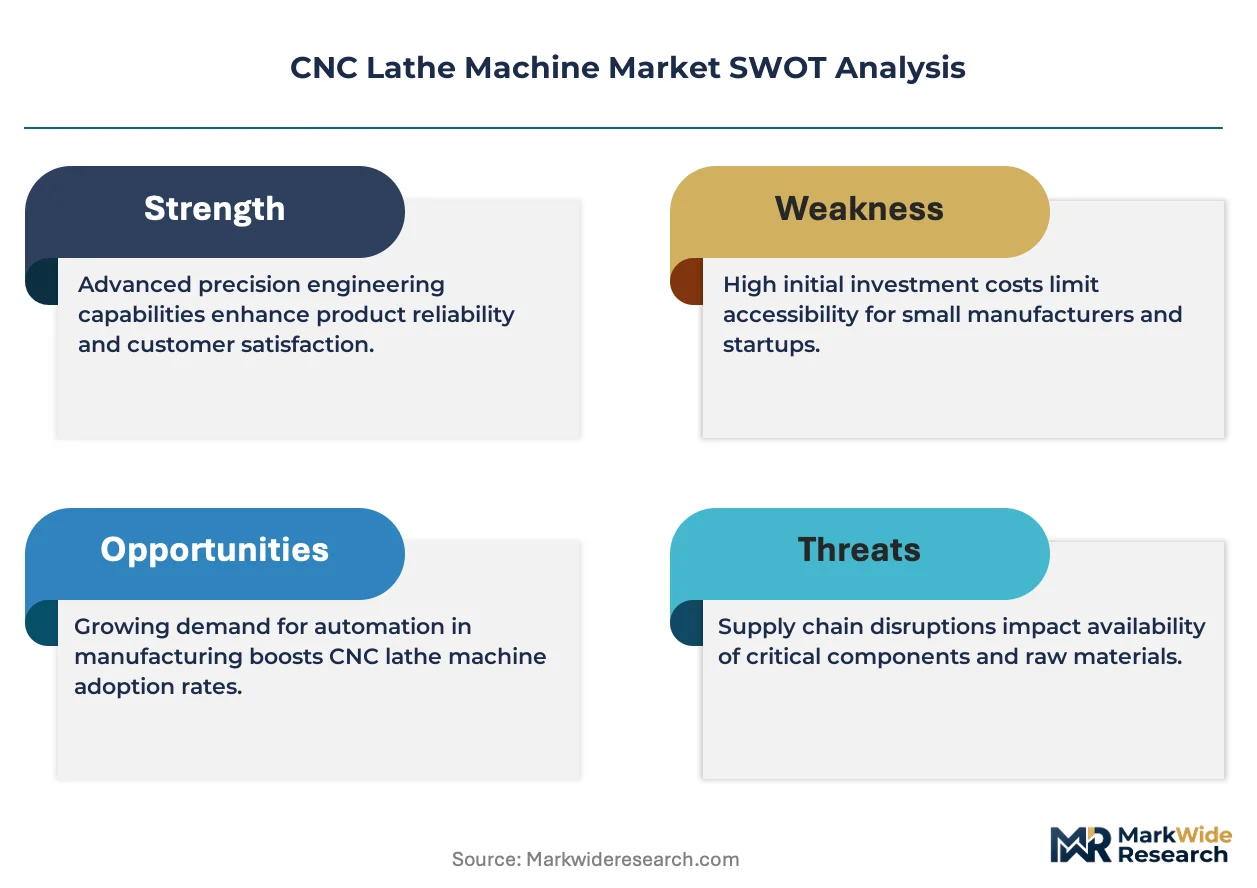
For Market Incumbents: Shield installed base relationships through captive spindle rebuild programs and extended warranty bundling that locks out independent service providers. Backward integration into control system semiconductor sourcing mitigates Taiwanese supplier concentration risk. ISO 230-2 certification investment preserves access to German and Japanese automotive supply chains where JIS B 6191 compliance filters disqualify lower-tier competitors. For New Entrants and Emerging Players: Differentiate on AI-enabled predictive maintenance subscriptions that guarantee machine uptime for remote job shop operators lacking in-house technical staff. India's PLI-subsidized precision engineering corridors offer the most penetrable geography for localized assembly infrastructure. Target remanufacturing channel partnerships in Mexico and Eastern Europe as the primary go-to-market angle, capturing price-sensitive buyers in automotive supply chains. For Investors and Strategic Acquirers: Capital is best deployed toward control system capability consolidators and connectivity platform specialists with proven factory automation integration. The five-to-ten year viability window favors vendors with demonstrated sub-micron repeatability verification and established aerospace supplier relationships. Monitor electric spindle order intake ratios versus hydraulic systems as the primary inflection indicator for technology transition momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Control System Backward Integration | Captive semiconductor sourcing insulates DMG Mori and Yamazaki Mazak from Taiwanese supplier bottlenecks. |
| AI-Enabled Predictive Maintenance Launch | Subscription uptime guarantees penetrate remote job shop segments with limited technical staffing. |
| India PLI Corridor Manufacturing Scale-Up | Localized assembly infrastructure captures production-linked incentive subsidies for precision engineering. |
| CE Marking Acceleration Program | Compressed EU Machinery Directive compliance timelines restore European market access for multi-axis platforms. |
| Remanufacturing Channel Partnership | Certified rebuild programs capture price-sensitive automotive demand in Mexico and Eastern Europe. |
Research Methodology
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors and secondary validation through customs trade data, SEC equipment manufacturer filings, ISO certification registries, and machine tool builder order backlogs anchors the qualitative findings. Bottom-up segmentation modeling triangulates against top-down macroeconomic manufacturing investment indicators to constrain variance.
Sensitivity analysis across electric versus hydraulic drive adoption scenarios, semiconductor availability assumptions, and regional regulatory enforcement intensity frames the projection uncertainty. Segmentation dimensions span product configuration, end-use vertical, workpiece material, and drive technology architecture across the modeling period. CAGRs derive from installed base replacement cycle analysis and greenfield capacity addition tracking, with aerospace program qualification deadlines and automotive powertrain transition timelines serving as industry-specific demand anchors.
The analysis sits within stated boundaries; outcomes outside sustained automotive capital expenditure recovery or prolonged semiconductor supply disruption would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and material cost trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Middle East Flexible Concrete Vibrator Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Plasma Cutting Equipment Market
Construction Equipment
Used Construction Equipment Market
Construction Equipment
Automated Bending Machine Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Trenchers Market
Construction Equipment
Skid Steer Loader Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
China Elevator Ropes Market
Construction Equipment
Cranes Rental Market
Construction Equipment
Drilling Machine Market