
 Autonomous Heavy Equipment Market | 2026-2036
Autonomous Heavy Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Heavy Equipment Market Insights
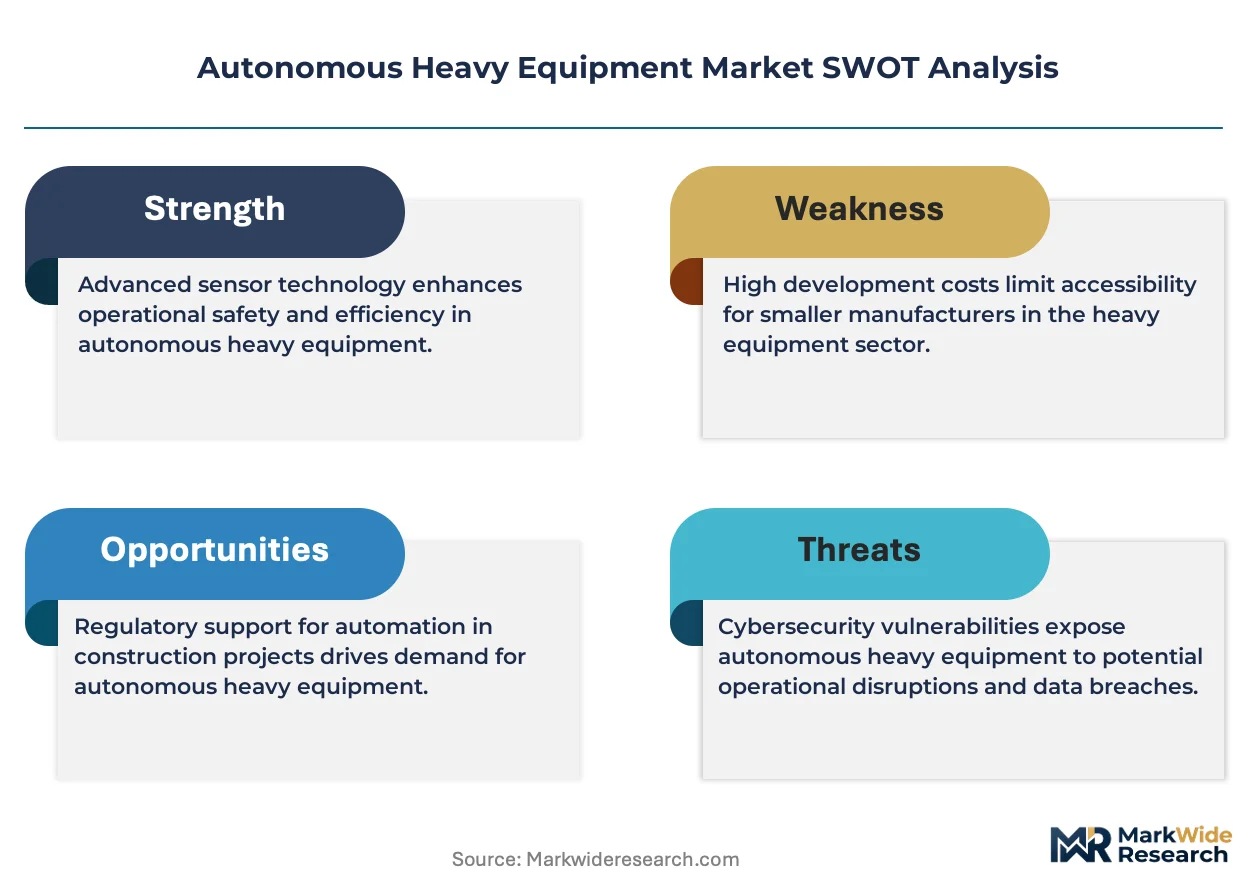
Sensor fusion architectures combining LiDAR, radar, and computer vision is reshaping how autonomous heavy equipment perceives and navigates unstructured terrain. Caterpillar leverages its MineStar Command platform to dominate autonomous mining truck deployments across North America and Australia. Komatsu Ltd anchors its competitive position through the FrontRunner autonomous haulage system, which sustains long-haul operations in Pilbara iron ore corridors. Deere & Company differentiates by extending precision autonomy from agriculture into construction grading applications, where GPS-guided blade control reduces rework cycles.
Autonomous heavy equipment denotes self-operating machinery capable of executing earthmoving, material handling, and site preparation tasks without continuous human operator intervention, typically relying on GNSS positioning, LiDAR point-cloud mapping, and AI-driven path planning algorithms that process terrain data at sub-10-centimeter accuracy. These systems eliminate operator fatigue errors, enable 24-hour continuous operation in hazardous environments, and reduce fuel consumption through optimized driving profiles. The technology dimension shows LiDAR and AI commanding premium system value, while GPS and computer vision segments compete on retrofit accessibility for legacy fleet upgrades. The end-user dimension reveals mining as the most mature deployment environment, with construction and agriculture representing faster-growing adoption curves where labor shortages and precision requirements intensify.
The US Mine Safety and Health Administration and OSHA impose operational standards that directly shape autonomous system validation protocols, while the EU Machinery Directive and forthcoming ISO 17757 for autonomous mining equipment establish cross-border certification benchmarks that OEMs must satisfy for market access. China's MIIT and SAMR are drafting national standards for autonomous construction machinery that will condition import eligibility and domestic procurement preferences. Stakeholders must monitor how divergent regulatory timelines across Washington, Brussels, and Beijing fragment type-approval processes and force parallel compliance investments.
Market Dynamics
Sensor fusion architectures and AI-driven path planning algorithms are compressing operational decision cycles, forcing OEMs to redesign validation protocols around sub-10-centimeter positioning accuracy rather than traditional operator-skill benchmarks.
Growth Catalysts
- Pit safety mandates:Australia's Work Health and Safety Act enforcement is accelerating autonomous haul truck adoption in Western Australia's iron ore corridors to eliminate operator fatigue incidents.
- ISO 17757 progression:The forthcoming autonomous mining equipment standard is creating certification clarity that reduces OEM liability exposure and accelerates fleet procurement timelines.
- LiDAR cost curves:Solid-state LiDAR manufacturing scale is reducing sensor package costs for retrofitting legacy construction and agriculture equipment with autonomy stacks.
Market Restraints
- Compute hardware concentration:GPU and specialized AI accelerator supply chains concentrate in Taiwan and South Korea, creating vulnerability for autonomous system production scaling.
- EU Machinery Directive compliance costs:The directive's safety integrity level requirements impose multi-million-euro validation burdens that disadvantage smaller OEMs and retrofit providers.
- GNSS signal vulnerability:Jamming and spoofing risks in remote mining locations create operational continuity concerns that slow full autonomy deployment in contested electromagnetic environments.
Strategic Opportunities
- Underpenetrated construction grading:GPS-guided blade control systems in North American infrastructure projects represent a white space where precision requirements meet labor shortage pressures.
- China MIIT standardization:Draft national standards for autonomous construction machinery will condition import eligibility, creating first-mover advantage for domestic OEMs and compliant foreign suppliers.
- 5G private networks:Ultra-reliable low-latency communication is enabling real-time teleoperation fallback and multi-machine coordination in underground mining applications previously inaccessible to autonomy.
Industry Challenges
- Autonomy systems engineering talent scarcity:The intersection of robotics, mining operations, and safety certification expertise concentrates in Pittsburgh, Perth, and Munich, creating recruitment bottlenecks for OEM expansion.
- Retrofit integration complexity:Legacy haul truck fleets from the 2010-2015 manufacturing wave lack CAN bus architectures compatible with modern sensor fusion stacks, forcing expensive electrical system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Heavy Equipment Market |
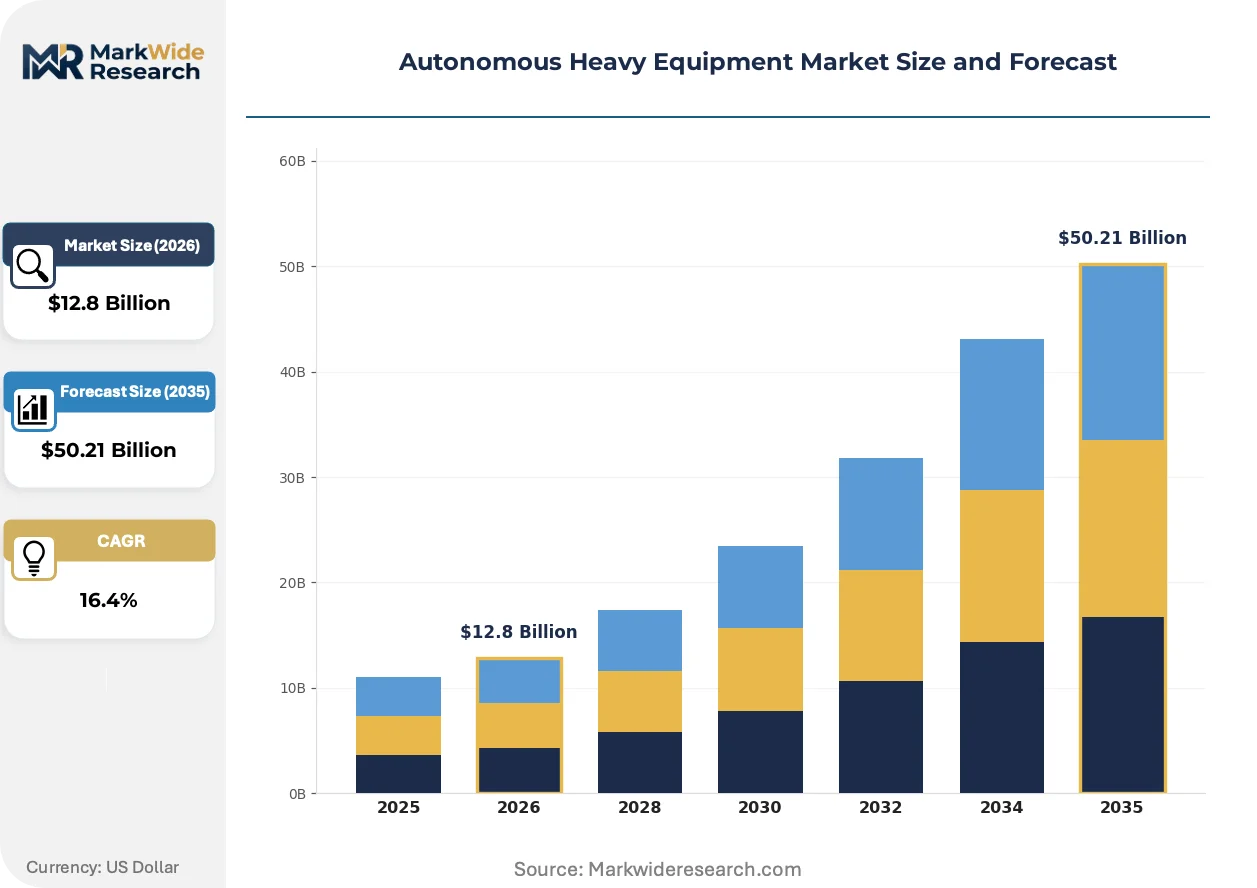
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $50.21 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Dump Trucks, Loaders, Graders Technology: LiDAR, GPS, Computer Vision, AI End User: Construction, Mining, Agriculture, Forestry Installation: On-site, Off-site, Retrofitting, New Build |
| Companies Covered | Caterpillar, Komatsu Ltd, Volvo Construction Equipment, Deere & Company, CNH Industrial, Hitachi Construction Machinery, Liebherr Group, Doosan Bobcat, Built Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Heavy Equipment Market Trends and Innovations
Digital twin simulation environments are displacing physical prototype testing, compressing development cycles while expanding the scenarios OEMs can validate before field deployment.
Edge computing architectures with onboard tensor processing units are digitizing terrain classification and obstacle detection workflows that previously required continuous cloud connectivity. Underground mining operators in Canada's oil sands and Chile's copper districts are deploying these systems to maintain autonomy in connectivity-deprived environments. The shift is digitizing safety-critical decision latency from hundreds of milliseconds to sub-50-millisecond response times, enabling faster operational speeds in hazardous conditions.
The EU Machinery Directive's 2023 amendments introduced explicit requirements for autonomous mobile machinery risk assessments, forcing OEMs to document failure mode probabilities for AI-driven path planning systems. Mining equipment manufacturers must now submit technical files demonstrating compliance with safety integrity levels before CE marking. The directive's machinery-specific scope is tightening fastest for autonomous haul trucks above 100-ton payload capacity, where Brussels regulators view collision consequences as systemically significant.
Equipment-as-a-service contracting is displacing traditional capital purchase models in Australian iron ore operations, transferring technology obsolescence risk from mine operators to OEM balance sheets. Rio Tinto and BHP are negotiating multi-year output-based agreements where payment ties to tonnes moved rather than machine availability. This procurement evolution concentrates most visibly in Western Australia's Pilbara region, where fleet scale justifies performance-guarantee structures that smaller North American construction contractors cannot replicate.
Autonomous Heavy Equipment Market Segmentation
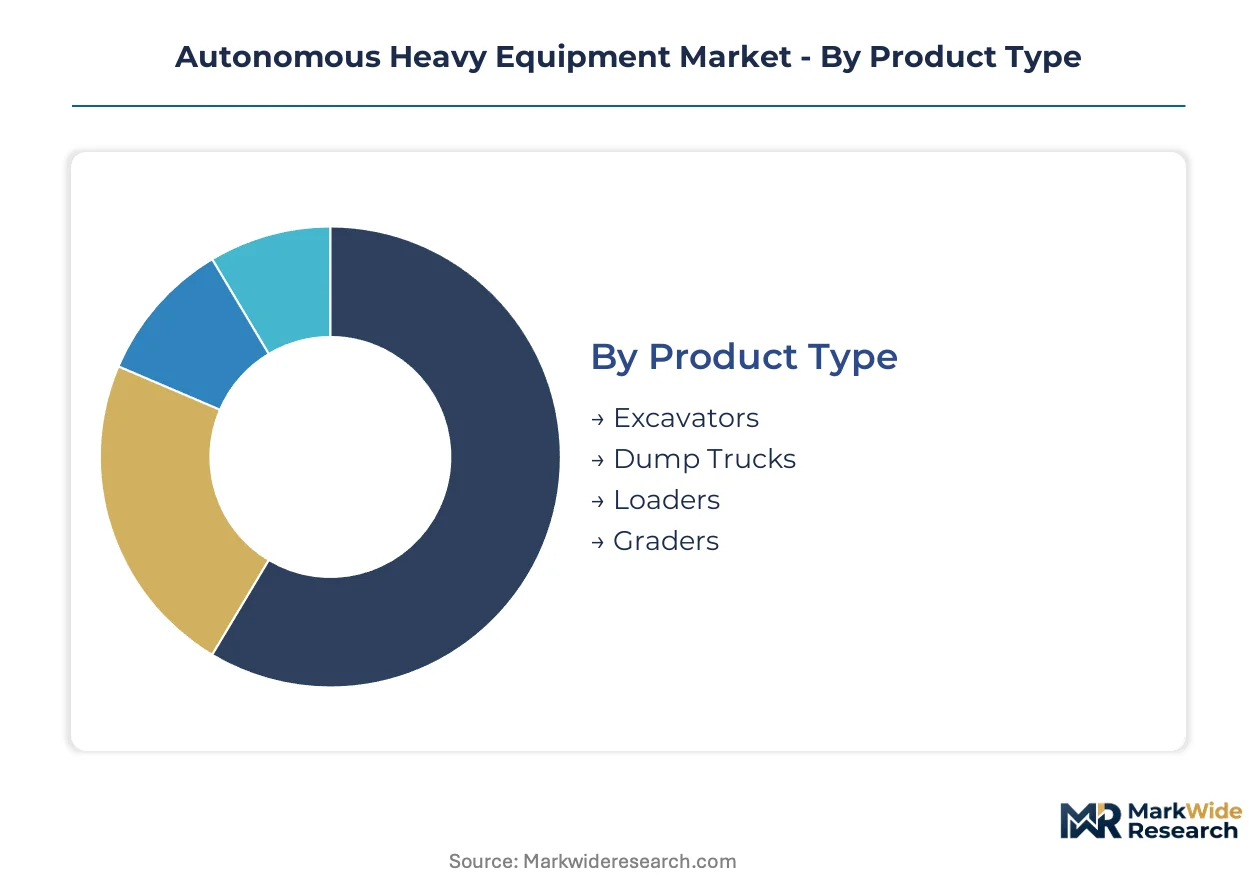
Equipment heterogeneity and technology stack diversity create distinct commercialization pathways across product types and end-use environments. Segmentation reveals where autonomy premiums command pricing power versus where retrofit economics dominate procurement decisions.
Product Type:
Mature autonomous haulage in mining contrasts sharply with emerging precision grading in construction, creating a bifurcated equipment development roadmap.
- Dump Trucks:Haul trucks above 100-ton payload capacity integrate MineStar Command and FrontRunner systems for 24-hour pit operations in Australia's Pilbara iron ore corridors. Fleet-scale deployments at Rio Tinto and BHP validate sub-10-centimeter positioning accuracy for collision avoidance in high-density haul routes.
- Excavators:Hydraulic excavators with AI-driven bucket control automate digging cycles in structured mining benches, though unstructured construction demolition sites demand more complex terrain classification algorithms that extend development timelines.
- Loaders:Wheel loaders for material handling in confined quarry environments concentrate sensor fusion packages for near-field obstacle detection.
- Graders:Motor graders with GPS-guided blade control reduce rework cycles in North American infrastructure grading where labor shortages intensify precision requirements.
Dump trucks retain volume leadership; graders hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium perception systems from accessible retrofit solutions, reshaping OEM R&D allocation and partnership strategies.
- LiDAR:Solid-state LiDAR arrays generate dense point-cloud maps for obstacle detection in dust-heavy mining environments, with manufacturing scale reducing unit costs for retrofit accessibility. Australia's autonomous haulage corridors drive concentrated demand for 360-degree coverage architectures.
- AI:Machine learning path planning algorithms process terrain classification and predictive maintenance signals, commanding premium system value through continuous operational optimization.
- GPS:GNSS positioning with RTK correction enables centimeter-grade blade control for construction grading applications at lower retrofit cost points.
- Computer Vision:Camera-based perception systems supplement LiDAR in clear-weather construction sites where cost constraints limit full sensor fusion deployment.
LiDAR retains volume leadership; computer vision climbs the fastest as retrofit penetration accelerates.
End User:
Application maturity varies sharply, with mining operationalizing full autonomy while construction and agriculture navigate fragmented deployment economics.
- Mining:Surface and underground extraction operations deploy autonomous haul trucks and loaders to eliminate operator fatigue incidents and enable continuous production cycles. Western Australia's Work Health and Safety Act enforcement accelerates fleet conversion in iron ore and coal corridors.
- Construction:Earthmoving and site preparation contractors adopt GPS-guided grading and excavation where labor scarcity meets infrastructure investment timelines, though project-based procurement limits fleet-scale autonomy economics.
- Agriculture:Precision farming operations extend autonomy from planting into harvest logistics, with Deere & Company transferring control algorithms from agricultural equipment into construction applications.
- Forestry:Harvesting and forwarding operations in Nordic and Canadian timber regions test autonomous forwarders for remote terrain access where operator recruitment proves persistently difficult.
Mining retains volume leadership; construction gains share fastest as labor shortages intensify.
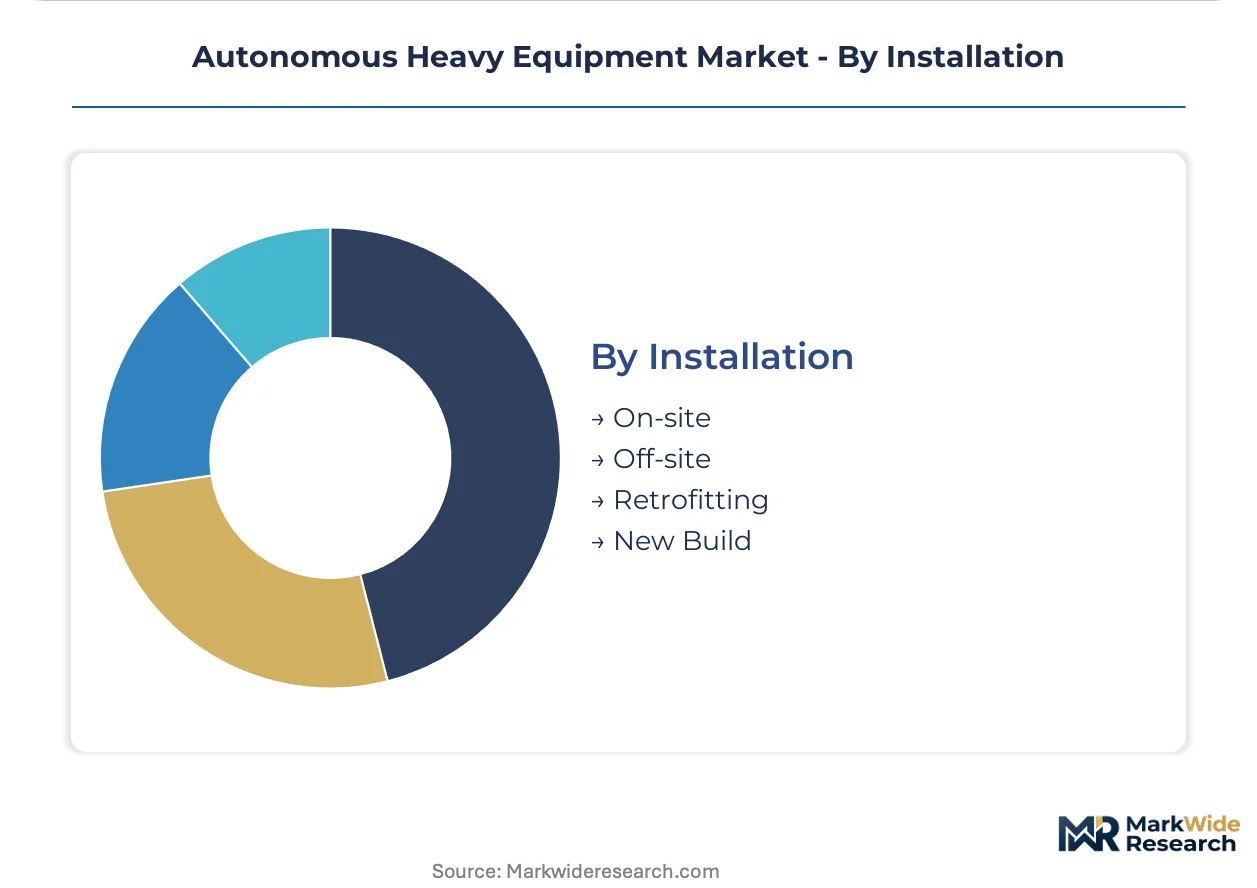
Installation:
Customer type and fleet age distribution determine whether OEMs capture value through new build premiums or retrofit service contracts.
- New Build:Factory-integrated autonomy stacks from Caterpillar and Komatsu command pricing premiums with validated safety integrity documentation for EU Machinery Directive compliance. Mining fleet replacement cycles in Australia and Chile concentrate demand for OEM-delivered integrated systems.
- Retrofitting:Aftermarket sensor fusion packages extend autonomy to legacy haul trucks from the 2010-2015 manufacturing wave, though CAN bus incompatibility forces expensive electrical system overhauls that constrain provider margins.
- On-site:Field integration services deploy modular autonomy kits at customer locations for fleet-specific terrain calibration.
- Off-site:Depot-based conversion programs centralize electrical rework and sensor calibration for smaller contractors lacking technical infrastructure.
New build retains volume leadership; retrofitting climbs the fastest as fleet age extends replacement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mining conglomerates and infrastructure contractors constitute the dominant buyer archetypes, with procurement concentrated in iron ore belts, highway corridors, and precision agriculture zones where labor economics and safety mandates converge.
Australia
Western Australia's Pilbara region hosts the world's largest operational autonomous haul truck fleets at Rio Tinto and BHP operations. The Work Health and Safety Act enforcement accelerates fleet conversion to eliminate operator fatigue incidents in 24-hour pit environments. Perth anchors engineering talent concentration for autonomy system validation and remote operations centers.
Chile
Copper mining operators in the Atacama Desert expand autonomous haulage to reduce labor costs in remote high-altitude extraction zones. The Ministry of Mining's safety protocols align with ISO 17757 progression to reduce OEM liability exposure. Antofagasta and Calama cluster equipment deployment for Codelco and BHP's Escondida operations.
United States
Infrastructure contractors adopt GPS-guided grading systems where labor shortages intensify precision requirements for federal highway projects. OSHA and MSHA operational standards shape autonomous system validation protocols for earthmoving equipment. Texas and California highway corridors concentrate deployment of precision blade control systems.
China
Construction machinery OEMs prepare for MIIT and SAMR national standards that will condition import eligibility and domestic procurement preferences. The dual carbon goals accelerate electric-autonomous integration in surface mining and port logistics. Shandong Province and Yangtze River Delta manufacturing bases prototype autonomous excavator and loader platforms.
Germany
Industrial machinery specialists develop safety integrity documentation for EU Machinery Directive compliance on autonomous mobile machinery above 100-ton capacity. KBA and Brussels regulators enforce CE marking requirements for AI-driven path planning systems. Bavaria and Baden-Württemberg engineering clusters concentrate validation testing for OEM export certification.
Autonomous Heavy Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation concentrates around integrated mining equipment OEMs with factory-delivered autonomy stacks, while fragmentation persists among retrofit service providers addressing legacy fleet upgrades. Three archetypes dominate: full-stack mining system integrators, precision agriculture-to-construction crossovers, and aftermarket sensor fusion specialists. Competitive moves center on strategic partnerships for 5G private network deployment and portfolio diversification into construction grading applications.
Among North American integrated system providers, Caterpillar and Deere & Company exemplify contrasting archetypes—Caterpillar anchors mining haulage dominance through scale-driven platform economics, while Deere & Company represents agricultural autonomy extension into adjacent construction segments. Komatsu Ltd occupies a position as the third anchor, representing Japanese engineering concentration in long-haul autonomous operations. These three entities collectively illustrate how geographic origin and legacy industry verticals shape competitive positioning without guaranteeing segment exclusivity.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu Ltd |
| Volvo Construction Equipment |
| Deere & Company |
| CNH Industrial |
| Hitachi Construction Machinery |
| Liebherr Group |
| Doosan Bobcat |
| Built Robotics |
| Others |
Pricing and Supply Chain Analysis
Taiwan and South Korea's concentration in GPU and specialized AI accelerator manufacturing concentrates margin capture upstream, forcing OEMs to absorb component volatility or pass through costs to mining operators locked into long-term fleet contracts. This upstream chokepoint reshapes where pricing power accumulates across the autonomous heavy equipment value chain.
Pricing Analysis
Cost-plus contracts with sensor package indexation dominate Australian iron ore fleet procurement, tying payments to LiDAR and compute module spot markets. Three-tier pricing structure across premium, standard, and economy levels separates factory-integrated OEM systems from retrofit kits and aftermarket service bundles. Pricing pressure stems from solid-state LiDAR manufacturing scale reducing hardware costs and compressing retrofit provider margins. Mining conglomerates exhibit lowest price sensitivity due to operational continuity premiums, while North American construction contractors face acute budget constraints on project-based grading equipment.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for autonomous system OEMs dependent on rare earth magnet motors and lithium-ion battery packs. Component sourcing draws from Taiwan for AI accelerators, Germany for precision hydraulic systems, and Japan for industrial-grade camera sensors. Single-source vulnerability concentrates in solid-state LiDAR emitter arrays where limited qualified suppliers constrain rapid scaling. Distribution runs through OEM-direct sales teams for mining fleet contracts and regional equipment dealers for construction and agriculture retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection where interoperability between Caterpillar's MineStar and Komatsu's FrontRunner systems could unlock multi-OEM fleet coordination, transforming competitive dynamics from hardware differentiation to ecosystem control.
For Market Incumbents: Harden defensive positions by deepening backward integration into AI accelerator supply through captive partnerships with Taiwanese foundries, and accelerate EU Machinery Directive safety integrity documentation to raise certification barriers against retrofit competitors. The ISO 17757 progression creates compliance leverage that factory-integrated OEMs can weaponize against aftermarket providers lacking validation infrastructure. For New Entrants and Emerging Players: Establish a beachhead in North American construction grading where labor shortages meet fragmented contractor bases underserved by mining-focused incumbents. Target GPS-guided blade control retrofits for mid-sized earthmoving fleets lacking capital for full autonomy stacks. Partner with 5G private network deployers to bundle connectivity-as-a-service with sensor fusion packages, reducing upfront customer adoption friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed retrofit service providers holding legacy fleet relationships but lacking factory integration capabilities. Long-term viability hinges on whether construction autonomy adoption curves steepen sufficiently to justify platform-scale investments. Monitor Rio Tinto and BHP equipment-as-a-service contract renewal rates as the signal for whether performance-guarantee economics transfer technology obsolescence risk sustainably to OEM balance sheets.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Private Network Deployment | Enables real-time teleoperation fallback for underground mining autonomy in connectivity-deprived environments. |
| Sensor Fusion Platform Integration | Unifies LiDAR, radar, and computer vision architectures across haul truck and excavator product lines. |
| Equipment-as-a-Service Transition | Transfers technology obsolescence risk from mine operators to OEMs through output-based contracting. |
| EU Machinery Directive Compliance Investment | Establishes CE marking documentation barriers that disadvantage smaller retrofit competitors. |
| Construction Grading Application Expansion | Extends precision autonomy from mining into infrastructure projects facing acute labor shortages. |
Research Methodology
Initial hypotheses were tested against primary input from mining operations directors, autonomous system validation engineers, OEM procurement managers, and aftermarket service heads, then refined through secondary validation against SEC filings, ISO standard progression documents, customs equipment import data, and mining safety regulator enforcement records. Bottom-up fleet deployment counts triangulated against top-down OEM revenue segmentation to anchor volume estimates.
Demand-supply-balance framing structured the analytical approach across the analysis window, modeling equipment type, technology stack tier, end-use environment, and installation method as core segmentation dimensions. CAGRs derived from logistic diffusion curves fitted to autonomous haul truck penetration rates in Australia's Pilbara region, extrapolated to construction and agriculture adoption patterns. Industry-specific inputs included Work Health and Safety Act enforcement timelines and MIIT standardization progression for Chinese market access.
Sensitivities concentrate around LiDAR cost curve acceleration, GNSS jamming incident frequency in remote mining corridors, and EU Machinery Directive amendment implementation timing. Forecasts reflect documented assumptions on technology maturation and regulatory harmonization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Pre-Owned Construction Equipment Market
Construction Equipment
India Heavy Construction Equipment Rental Market
Construction Equipment
Vertical Mill Market
Construction Equipment
Concrete Grinder Market
Construction Equipment
Jackhammer Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Automatic Bending Machine Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
Drone-Based Solutions in Construction Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Global Crane Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Thermal Spray Equipment Market