
 Demolition Equipment Market | 2026-2036
Demolition Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Demolition Equipment Market Analysis
Buyer concentration among demolition contractors is decoupling from traditional generalist construction firms as specialized operators capture larger municipal decommissioning contracts. Caterpillar leverages its integrated dealer network to sustain aftermarket parts revenue across North American urban renewal zones. Komatsu anchors its position through telematics-enabled fleet management systems that reduce idle time on congested job sites. XCMG competes aggressively on manufacturing scale, occupying cost-sensitive procurement channels across Southeast Asia and the Middle East.
Demolition equipment encompasses heavy machinery engineered for controlled structural dismantling, typically featuring reinforced booms, specialized attachments, and operator protection systems rated for impact and debris hazards. Hydraulic excavators configured with high-reach booms and concrete pulverizers remain the dominant platform for multi-story building takedowns. Breakers and grapples command premium margins in dense urban corridors where precision demolition limits collateral structural damage. Electric technology variants are gaining fastest traction in European and Japanese markets where noise ordinances and indoor air quality rules restrict diesel operation.
OSHA mandates govern operator exposure limits and machine guarding standards across US demolition sites, while the EU Machinery Directive and CE marking framework enforce design safety and electromagnetic compatibility for equipment sold in member states. Japan's METI promotes carbon-neutral construction machinery through subsidy programs tied to battery-electric and hydrogen fuel cell platforms. Stakeholders must monitor how evolving emissions enforcement timelines reshape capital deployment between retrofit hybrid systems and full-electric platform development.
Market Dynamics
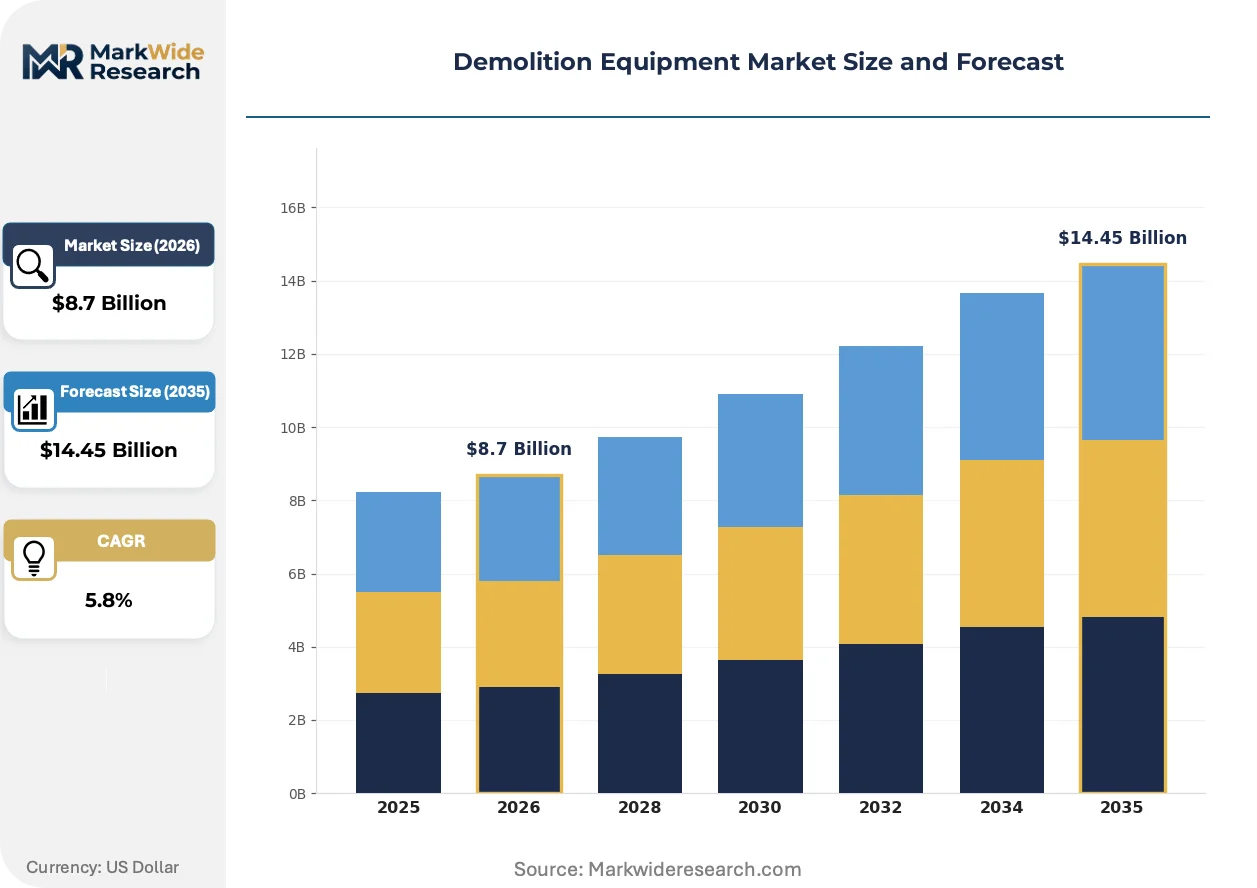
Fleet electrification is forcing capital reallocation across manufacturer R&D programs as municipal contractors face tightening emissions enforcement timelines in dense urban corridors.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for hydrofluorocarbon-based systems are accelerating refrigerant recovery equipment demand in building decommissioning workflows across German and French municipal contracts.
- Telematics integration:Real-time fuel monitoring and idle-reduction algorithms are cutting operating costs for high-reach excavator fleets deployed on congested Asian job sites.
- Urban densification:Vertical construction replacement cycles in Mumbai, Shanghai, and Jakarta are generating sustained tender volumes for precision demolition specialists.
Market Restraints
- Battery energy density limitations:Lithium-ion pack weight penalties restrict operational duration for electric excavators below 30-ton classes, compressing daily utilization rates.
- Specialized steel supply concentration:High-grade abrasion-resistant plate production clusters in South Korea and Japan expose boom fabricators to input cost volatility and extended lead times.
- Operator certification scarcity:OSHA-compliant high-reach equipment licensing programs face instructor bottlenecks, throttling workforce expansion in US metropolitan markets.
Strategic Opportunities
- Japan METI subsidy programs:Battery-electric and hydrogen fuel cell construction machinery incentives are creating first-mover advantages for OEMs establishing localized service networks.
- Modular attachment systems:Quick-coupler standardization across pulverizer, grapple, and shear interfaces is enabling rental fleet flexibility and reducing customer capex requirements.
- Indoor air quality rules:European noise and emissions ordinances in Amsterdam, Copenhagen, and Vienna are mandating zero-emission equipment for enclosed structure takedowns.
Industry Challenges
- Electrical infrastructure retrofit:Job site charging and grid connection standards vary across jurisdictions, complicating electric fleet deployment logistics for contractors operating across multiple cities.
- Legacy hydraulic system interoperability:Mixed fleet environments with decades-old excavator bases create parts complexity and technician training burdens for service departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Demolition Equipment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Breakers, Grapples Technology: Hydraulic, Pneumatic, Mechanical, Electric Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, Government, Construction Firms, Demolition Specialists |
| Companies Covered | Hitachi Construction Machinery, SANY, Volvo Construction Equipment, Doosan, XCMG, Liebherr, Caterpillar, John Deere, Komatsu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Demolition Equipment Market Emerging Trajectories
Autonomous machine control and predictive maintenance systems are compressing operational risk profiles for contractors bidding fixed-price decommissioning contracts in regulated environments.
Electrified powertrains are overtaking diesel-electric hybrids as the dominant development pathway for sub-50-ton excavator classes. German and Japanese municipal fleets are adopting battery-electric units for nighttime and indoor operations where noise restrictions apply. This transition is compressing residual values for Tier 4 Final diesel inventories and redirecting aftermarket parts revenue toward electrical system servicing.
The EU Machinery Directive's 2023 amendments to electromagnetic compatibility and cybersecurity requirements are mandating design overhauls for telematics-enabled equipment. Manufacturers must now certify against updated CE marking frameworks before placing connected machines on member state markets. Demolition specialists in France and Italy are prioritizing compliant platforms to avoid project delays from customs holds at port of entry.
Service contract unbundling is fragmenting traditional full-maintenance leasing arrangements. Large municipal authorities in the United Kingdom and Australia are separating equipment rental from parts and labor coverage, forcing OEMs to compete on transparent hourly rates rather than bundled lifecycle pricing. This shift favors regional service networks with localized parts stocking over centralized manufacturer-controlled programs.
Demolition Equipment Market Segmentation
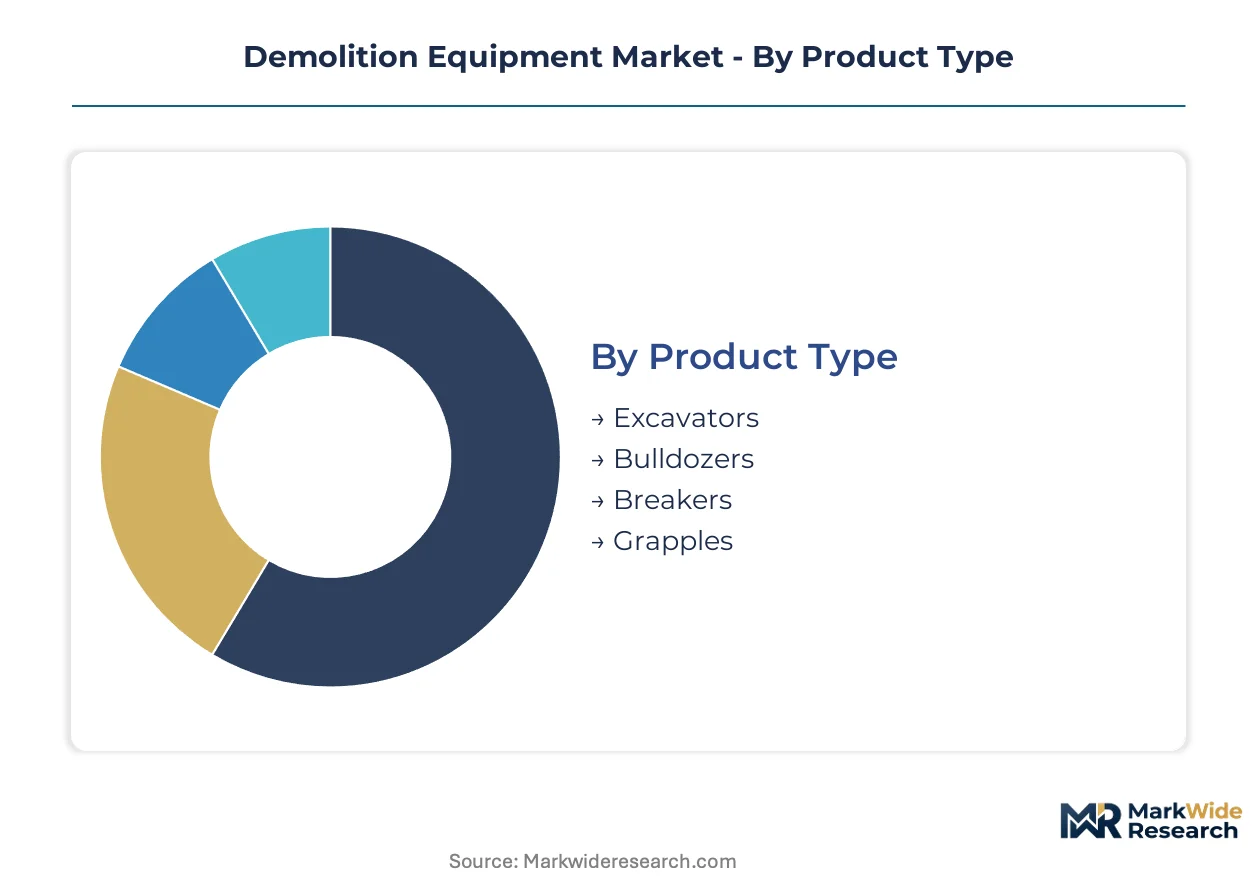
Segmentation in demolition equipment reveals how procurement decisions split between heavy civil contractors optimizing for utilization rates and municipal authorities prioritizing emissions compliance. Equipment specifications diverge sharply across urban density gradients, with high-reach configurations dominating vertical decommissioning while compact units serve constrained infrastructure corridors.
Product Type:
Contractor fleet composition hinges on project mix flexibility, with attachment interchangeability often outweighing base platform specifications in capital allocation decisions.
- Excavators:Configurable high-reach booms with reinforced undercarriages handle multi-story structural takedowns. Demand clusters with municipal decommissioning specialists in Shanghai, Mumbai, and Jakarta where vertical replacement cycles intensify; EPA Tier 4 Final and EU Stage V compliance costs are compressing residual values for diesel-intensive fleets.
- Bulldozers:Tracked platforms with specialized rakes and protective cab enclosures clear debris fields and grade demolition sites. Volume concentrates in US Sun Belt markets where single-story commercial strip redevelopment outpaces vertical urban renewal; operating cost sensitivity favors telematics-enabled idle reduction systems.
- Breakers:Hydraulic percussion attachments rated for reinforced concrete fracture command premium positioning in precision urban corridors.
- Grapples:Rotating multi-tine configurations sort structural steel and masonry for recycling streams.
Volume sits with excavators; growth tilts toward grapples as circular economy mandates elevate material recovery rates.
Technology:
Powertrain selection increasingly tracks regulatory enforcement geography rather than operational duty cycle alone.
- Hydraulic:Mature fluid power systems with established service infrastructure dominate heavy-lift applications above 50-ton classes. Deployment concentrates in Middle Eastern and Southeast Asian markets where grid infrastructure limitations and extreme ambient temperatures constrain electric alternatives; OEM parts revenue remains anchored to seal and hose replacement cycles.
- Electric:Battery-electric platforms with regenerative boom lowering systems eliminate local emissions for indoor and nighttime operations. Adoption accelerates in Amsterdam, Copenhagen, and Vienna where municipal noise ordinances and indoor air quality rules mandate zero-emission equipment; METI subsidy programs in Japan are creating first-mover service network advantages for localized OEMs.
- Pneumatic:Compressed air systems serve explosive atmosphere zones and underwater cutting applications.
- Mechanical:Direct-drive cable and winch systems persist in cost-sensitive salvage operations.
Revenue concentrates in hydraulic platforms; steepest expansion trajectory belongs to electric variants as F-Gas Regulation phase-downs and urban emissions enforcement timelines tighten.
Application:
Project scale and structural complexity determine attachment specifications, with precision requirements escalating in dense urban fabric.
- Commercial:Multi-story office and retail decommissioning demands high-reach excavators with concrete pulverizers and dust suppression systems. Tender volumes are climbing in German and French municipal contracts where EU F-Gas Regulation mandates refrigerant recovery equipment integration; fixed-price bidding compresses risk tolerance for contractors deploying autonomous machine control systems.
- Industrial:Heavy manufacturing facility takedowns involving process equipment and hazardous material abatement require specialized containment protocols. Activity concentrates in US Rust Belt and German Ruhr region where post-industrial site remediation funding flows through EPA Superfund and national environmental agency programs; OSHA exposure limits govern operator protection system specifications.
- Residential:Single-family and low-rise multifamily demolition favors compact equipment with neighborhood access constraints.
- Infrastructure:Bridge, tunnel, and roadway decommissioning involves traffic management and structural load transfer engineering.
Equipment hours accumulate in commercial applications; technology refresh rates run highest in industrial segments due to contamination liability exposure.
End User:
Procurement authority fragmentation between public agencies and private operators creates divergent contract structures and financing preferences.
- Demolition Specialists:Dedicated decommissioning contractors with high-reach operator certifications and hazardous materials licensing capture premium municipal contracts. Fleet investment concentrates in UK and Australian markets where service contract unbundling separates equipment rental from parts and labor coverage; transparent hourly rate competition favors regional service networks with localized parts stocking.
- Government:Municipal authorities and environmental agencies directly procure for public infrastructure removal and contaminated site remediation. Budget cycles in Japan, Germany, and the United Kingdom are steering capital toward battery-electric and hydrogen fuel cell platforms aligned with carbon-neutral construction machinery targets; electromagnetic compatibility certification under amended EU Machinery Directive requirements is filtering vendor eligibility.
- Contractors:Generalist construction firms with demolition as ancillary capability prioritize equipment versatility across project types.
- Construction Firms:Integrated developers with captive demolition units optimize for site clearing speed and foundation preparation sequencing.
Capital deployment scale rests with government purchasers; margin capture tilts toward demolition specialists through certified labor premiums and specialized attachment utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates demolition equipment procurement through state-backed infrastructure replacement cycles, while Germany and Japan drive technology premiumization via emissions enforcement timelines.
China
Municipal decommissioning tenders in Shanghai and Beijing are accelerating fleet turnover as vertical construction replacement intensifies. The Ministry of Ecology and Environment enforces Stage IV emissions standards that compress residual values for legacy diesel inventories. Manufacturing clusters in Xuzhou and Changzhou anchor global excavator production scale.
Germany
Ruhr region post-industrial site remediation and commercial building takedowns in Berlin sustain high-reach equipment demand. The EU F-Gas Regulation mandates refrigerant recovery equipment integration in municipal contracts. Industrial fabricators in Baden-Württemberg specialize in precision attachment systems for dense urban corridors.
United States
Sun Belt commercial strip redevelopment and Rust Belt industrial facility decommissioning generate divergent equipment specifications. OSHA governs operator exposure limits and high-reach certification requirements. Fleet operators in Texas and Florida prioritize telematics-enabled idle reduction systems to cut fuel costs.
Japan
Tokyo and Osaka metropolitan noise ordinances are mandating battery-electric units for nighttime operations. METI subsidy programs for carbon-neutral construction machinery are redirecting capital toward hydrogen fuel cell platform development. Equipment lessors in Kansai region are establishing localized service networks for electric fleet support.
India
Mumbai and Delhi-NCR vertical densification projects are generating sustained tender volumes for precision demolition specialists. The Central Pollution Control Board enforces construction equipment emissions norms that phase out older diesel classes. Rental fleet operators in Gujarat and Maharashtra are expanding attachment interchangeability to improve utilization rates.
Demolition Equipment Market Vendor Landscape
Japanese and German producers anchor one tier; Chinese fabricators hold volume-driven positions in cost-sensitive procurement channels. The vendor base splits between integrated construction equipment conglomerates and specialized demolition attachment manufacturers. Three archetypes dominate: full-line OEMs with captive financing arms, regional rental fleet operators with service contract unbundling expertise, and attachment specialists with quick-coupler standardization capabilities. Competitive moves concentrate on telematics integration partnerships and modular platform development to reduce customer capex requirements.
Within the full-line OEM tier, Hitachi Construction Machinery and Komatsu exemplify integrated service network strategies, while XCMG occupies a position among scale-driven Chinese fabricators competing on manufacturing throughput. These three anchors demonstrate how geographic origin correlates with competitive emphasis—Japanese producers prioritizing fleet management systems, Chinese manufacturers leveraging production scale, and European specialists targeting emissions-compliant premium segments.
| Leading Market Players |
|---|
| Hitachi Construction Machinery |
| SANY |
| Volvo Construction Equipment |
| Doosan |
| XCMG |
| Liebherr |
| Caterpillar |
| John Deere |
| Komatsu |
| Others |
Supply Flow & Price Mechanics
High-reach excavator operator certification concentration in the US Rust Belt and German industrial corridors feeds labor-cost differentials into pricing-tier spreads, with certified premium operators commanding hourly rate premiums that separate municipal contract winners from secondary bidders.
Pricing Analysis
Volume concentrates in hydraulic excavator platforms where manufacturing scale in China compresses unit economics; premium-mid-economy pricing differentiation tracks emissions compliance tier and telematics integration depth. Price differentiation hinges on CE marking certification under amended EU Machinery Directive requirements and EPA Tier 4 Final compliance status. Cost compression in diesel-intensive fleets is intensifying because residual value erosion accelerates as electrification timelines tighten. Municipal authorities in Germany and Japan exhibit lowest price sensitivity due to subsidy-backed procurement, while rental fleet operators in Southeast Asia remain most cost-constrained.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for high-reach boom fabricators, while regional distributor networks serve fragmented municipal contractor bases. Geographic supply concentration centers on China for base excavator platforms, South Korea and Japan for abrasion-resistant steel plate, and Germany for precision attachment systems. Raw material dependencies draw from high-grade structural steel, lithium-ion battery packs, and hydraulic component castings. Single-source vulnerability in specialized steel plate exposes boom manufacturers to input cost volatility. Distribution runs through captive dealer networks for full-line OEMs and unbundled rental-service hybrids for municipal specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The demolition equipment market reads as a cost-of-compliance story where EU F-Gas Regulation refrigerant recovery mandates and amended Machinery Directive electromagnetic compatibility requirements create barrier-to-entry moats for certified platform providers.
For Market Incumbents: Extend telematics-enabled fleet management capabilities into predictive maintenance service contracts, locking in aftermarket revenue as electric platform residual values compress. Deepen backward integration into battery pack assembly for sub-50-ton excavator classes to capture margin from electrification transitions. Anchor position through quick-coupler standardization alliances that reduce customer capex requirements and raise switching costs.
For New Entrants and Emerging Players: Begin with modular attachment system development targeting unbundled service contract markets in the United Kingdom and Australia where transparent hourly rate competition favors regional parts-stocking networks. Target indoor air quality compliance segments in Amsterdam, Copenhagen, and Vienna where zero-emission equipment mandates outpace incumbent electric fleet deployment. Pursue METI subsidy-aligned joint ventures with Japanese equipment lessors to establish localized service infrastructure.
For Investors and Strategic Acquirers: Re-rating potential sits with regional rental fleet operators with unbundled service expertise given municipal procurement fragmentation toward transparent hourly rate structures. Long-term viability favors acquisition targets with certified high-reach operator training programs and hazardous materials licensing moats. Monitor Japan METI hydrogen fuel cell construction machinery subsidy disbursement velocity as inflection indicator for platform technology winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrification Platform Development | Battery-electric excavator R&D captures Amsterdam and Vienna zero-emission procurement mandates. |
| Telematics Integration Partnership | Real-time idle reduction algorithms secure municipal contract wins in congested Asian job sites. |
| Quick-Coupler Standardization Alliance | Modular attachment interoperability reduces rental fleet capex burdens and raises switching costs. |
| Backward Integration into Battery Assembly | In-house lithium-ion pack production insulates margin from raw material volatility. |
| Certified Operator Training Program Expansion | OSHA-compliant high-reach licensing moats capture premium labor rates in US metropolitan markets. |
Methodological Framework
Document review covered customs and trade flow databases, EPA enforcement action records, EU Machinery Directive amendment filings, and METI subsidy program disclosures, complemented by interviews with demolition contractor fleet managers, municipal procurement officers, OEM aftermarket service directors, and high-reach equipment training instructors. Secondary validation drew from equipment registration databases, tender announcement aggregators, and steel plate import-export statistics. Bottom-up project pipeline analysis and top-down fleet replacement cycle modeling were cross-referenced for triangulation.
Historical utilization rate trajectories were cross-referenced against panel input from equipment lessors and municipal authorities across the analysis window. Segmentation dimensions modeled include product type, powertrain technology, application complexity, and end-user procurement authority. CAGRs were derived from fitted trend extrapolation against regulatory enforcement timeline acceleration. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down schedules and Japan METI carbon-neutral machinery subsidy disbursement patterns.
Underlying measurement precision varies by segment; electric platform adoption rates carry tighter precision than hydrogen fuel cell development timelines due to commercial deployment visibility gaps. Forecasts reflect assumptions around emissions enforcement adherence and subsidy program continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Robotic Total Stations (RTS) Market
Construction Equipment
France Metal Fabrication Equipment Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Crane Buffer Market
Construction Equipment
North America Welding Equipment Market
Construction Equipment
Wood Chipper Machines Market
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
North America Construction Equipment Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Piles Turner Market
Construction Equipment
Automated Bending Machine Market
Construction Equipment
India Construction Equipment Rental Market
Construction Equipment
CNC Machine Tools Market
Construction Equipment
Global Portable Light Towers Market
Construction Equipment
Autonomous Construction Equipment Market