
 Crawler Dozers Market | 2026-2036
Crawler Dozers Market Size, Share, and Industry Trends Forecast 2026-2036
Crawler Dozers Market Intelligence
Mining enterprises is reorganizing procurement priorities toward automated earthmoving fleets. Caterpillar leverages integrated GPS-controlled blade systems to anchor its position in autonomous mine sites. Komatsu competes through in-house electric drive development, while Shantui dominates cost-optimized mechanical transmission segments across emerging Asian contractors.
Crawler dozers are tracked earthmoving machines propelled by continuous steel tracks, typically powered by diesel engines rated from 80 to 850 horsepower, designed to push soil, rock, and overburden via a hydraulically actuated blade. Hydraulic crawler dozers command the largest installed base due to superior blade control precision in mining and quarrying environments. Automated blade control technology is gaining fastest among technology segments as contractors seek grade accuracy without survey crews. Infrastructure development applications generate the deepest margin pools given multi-year project financing and fleet bundling contracts.
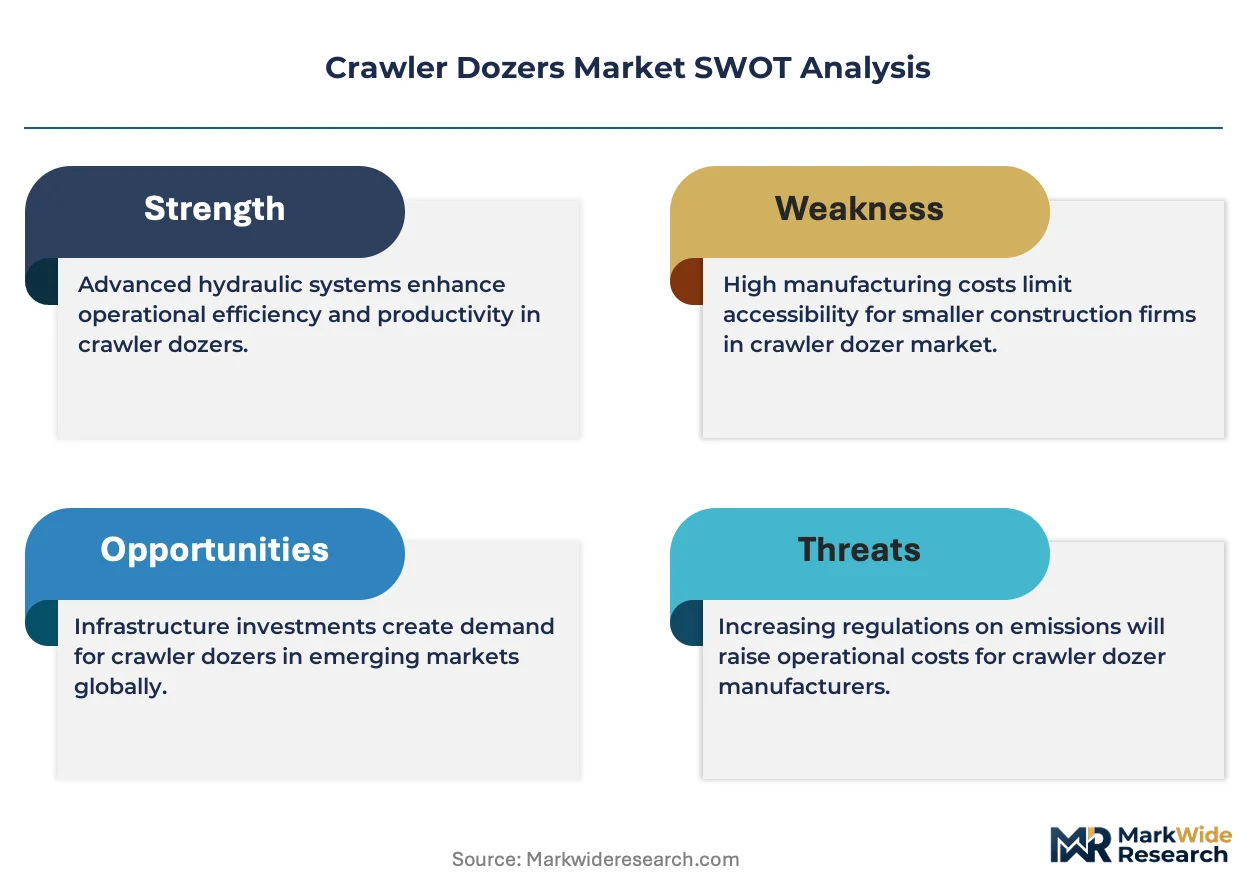
EPA Tier 4 Final regulations in the United States and EU Stage V standards enforced by ECHA compel engine redesigns, raising OEM compliance costs but filtering out smaller import competitors. China's MEE enforces GB emission standards that restrict non-certified equipment from state-funded infrastructure tenders. Stakeholders must monitor electrification readiness across their dealer service networks before binding fleet commitments.
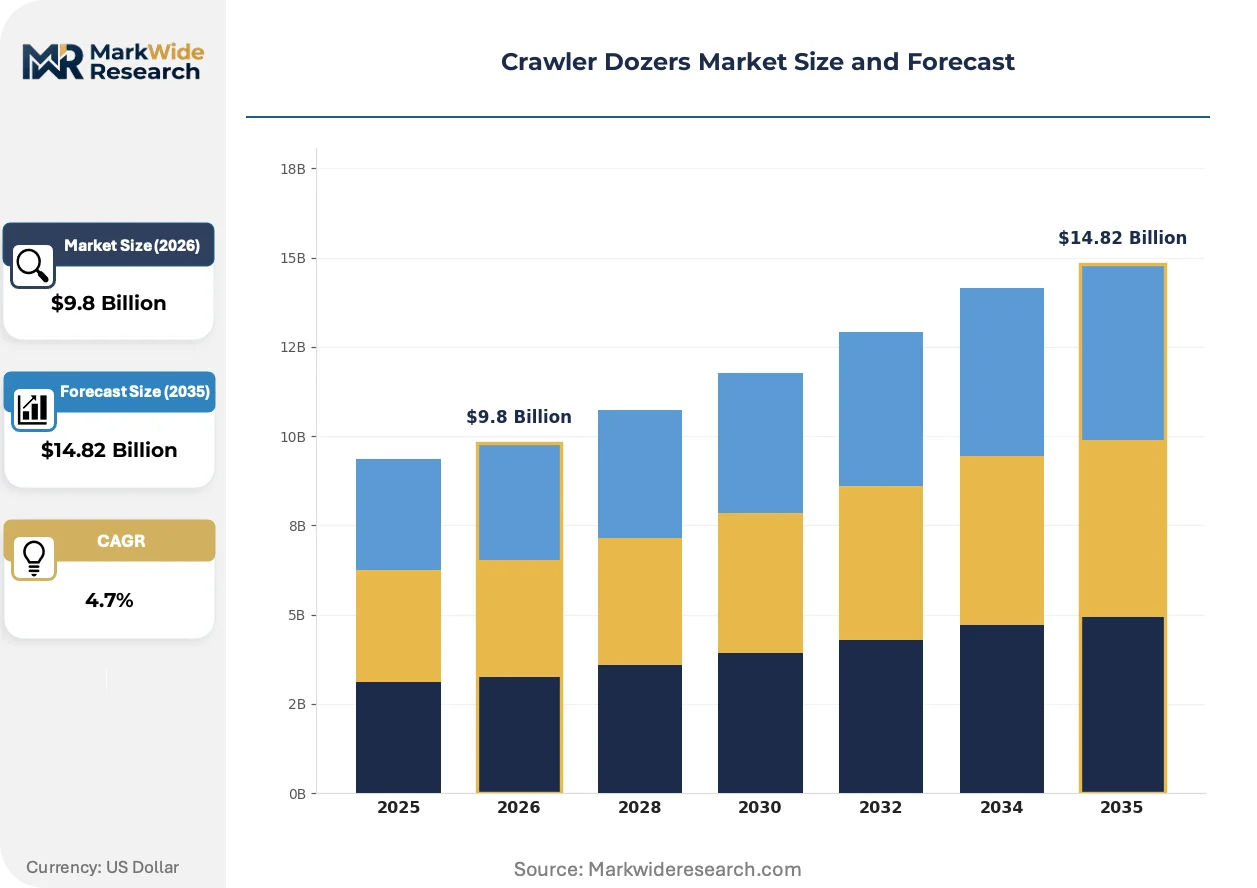
Market Dynamics
EPA Tier 4 Final and EU Stage V emission mandates are forcing OEMs to redesign powertrains, raising compliance costs and filtering out smaller competitors while concentrating procurement among mining enterprises seeking automated earthmoving fleets.
Growth Catalysts
- Automated blade control systems:Mining contractors in Western Australia deploy GPS-guided grading to eliminate survey crew dependency and accelerate overburden removal cycles.
- Hybrid-electric powertrain development:Komatsu's in-house electric drive technology reduces fuel consumption in high-horsepower applications above 400 horsepower.
- India's National Infrastructure Pipeline:State-funded road and rail projects trigger fleet replacement cycles among domestic earthmoving contractors.
Market Restraints
- Diesel engine aftertreatment costs:Selective catalytic reduction and diesel particulate filter systems add 15-20% to powertrain manufacturing costs.
- Steel track and undercarriage supply concentration:Japanese and South Korean forged component suppliers control critical high-wear parts for machines above 500 horsepower.
- Labor substitution by autonomous haulage:Self-driving dump trucks in Pilbara iron ore operations reduce ancillary dozer support requirements.
Strategic Opportunities
- Indonesia's nickel processing corridor:Battery-grade nickel smelting projects in Sulawesi and Halmahera require specialized swamp dozers for marshy terrain reclamation.
- Rental fleet digitization:Telematics-enabled hourly utilization tracking allows equipment lessors to offer performance-guaranteed contracts.
- EU Green Deal construction procurement rules:Public works tenders now award technical points for machinery meeting Stage V emission standards.
Industry Challenges
- Autonomous system integration complexity:Mine operators struggle to synchronize dozer blade control with centralized fleet dispatch systems.
- Service technician certification timelines:EPA and EU-mandated emission diagnostics training extends dealer readiness periods by 6-9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crawler Dozers Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.82 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Crawler Dozers, Mechanical Crawler Dozers, Wheel Crawler Dozers, Compact Crawler Dozers Technology: GPS Controlled Systems, Automated Blade Control, Diesel Engines, Electric Drive Systems, Hybrid Engines Application: Mining Operations, Land Clearing, Forestry Management, Infrastructure Development, Quarrying End User: Construction Companies, Mining Enterprises, Forest Management Firms, Road Builders |
| Companies Covered | Liebherr, CASE Construction Equipment, Caterpillar, LiuGong, Fiat Allis, Komatsu, John Deere, ACCO, Shantui, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crawler Dozers Market Strategic Shifts & Innovations
Powertrain electrification and autonomous control systems are splitting the crawler dozer market into premium technology-enabled segments and cost-optimized mechanical alternatives.
Electrified powertrains spanning battery-electric and fuel-cell configurations are bifurcating the high-horsepower segment. Mining operators in Canada and Chile pilot hydrogen fuel-cell dozers for underground ventilation-constrained environments. This technology is compressing the addressable market for conventional diesel engines above 600 horsepower.
REACH chemical registration and EU Stage V particulate limits tighten material composition rules for hydraulic fluids and engine lubricants. OEMs reformulate component specifications to maintain warranty coverage across European Union member states. Mining contractors in Germany and Sweden now specify biodegradable hydraulic oil to preempt regulatory penalties.
Performance-based equipment leasing displaces traditional capital purchase models in North American construction markets. Fleet managers bundle dozer hours with telematics-verified availability guarantees rather than owning depreciating assets. This shift concentrates most visibly among highway contractors in Texas and California facing project financing constraints.
Crawler Dozers Market Segmentation
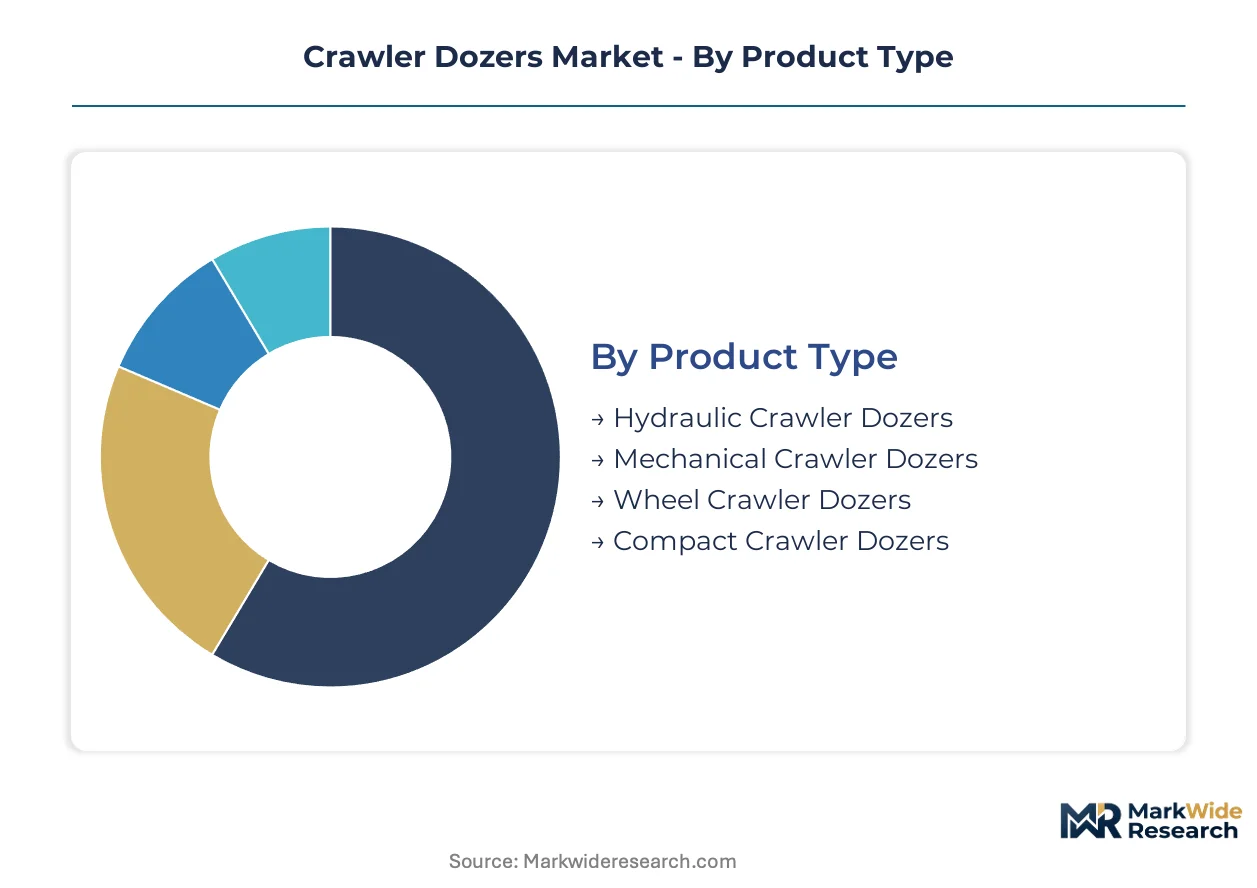
Crawler dozer segmentation reveals how technology tiers and application intensity create divergent margin profiles. Procurement patterns split between precision-demanding mining operators and cost-sensitive land clearing contractors, with electrification pressure reshaping traditional category boundaries.
Product Type:
Substitution pressure from electric drive alternatives and autonomous haulage systems threatens conventional mechanical platforms most severely in high-horsepower mining applications.
- Hydraulic Crawler Dozers:These machines deploy closed-loop hydraulic circuits delivering precise blade positioning through variable displacement pumps. Mining contractors in Western Australia specify hydraulic units for overburden removal where GPS integration demands millimeter-grade blade control accuracy.
- Mechanical Crawler Dozers:Direct mechanical power transmission via torque converters and manual gearboxes dominates emerging Asian contractor fleets. Cost-optimized procurement by domestic road builders in India favors mechanical simplicity over electronic complexity.
- Wheel Crawler Dozers:Rubber-tired variants sacrifice traction for transport speed between dispersed job sites. Forestry management firms in Nordic regions deploy wheel configurations for rapid repositioning across harvested compartments.
- Compact Crawler Dozers:Sub-100 horsepower machines with reduced ground pressure ratings serve residential grading and utility trenching. Urban infrastructure contractors in Japan specify compact units for constrained right-of-way restoration.
Hydraulic crawler dozers anchor the volume base while electric drive configurations gain share at the steepest rate among product categories.
Technology:
Cost tier stratification separates premium autonomous platforms from economy diesel mechanical alternatives, with mid-tier hybrid systems capturing transitional procurement.
- GPS Controlled Systems:Satellite-guided blade positioning eliminates survey stake dependency through real-time kinematic correction. Mining enterprises in Chile's copper belt deploy GPS-controlled fleets to accelerate bench preparation cycles.
- Automated Blade Control:Laser and sonic sensor arrays enable operator-free grading within specified tolerance bands. Highway contractors in Texas specify automated systems for subgrade preparation where labor availability constrains project schedules.
- Diesel Engines:Compression-ignition powertrains from 80 to 850 horsepower retain installed base dominance. EPA Tier 4 Final aftertreatment requirements have compressed margins for standalone diesel configurations.
- Electric Drive Systems:Battery-electric and fuel-cell architectures eliminate exhaust emissions for underground ventilation-constrained environments. Canadian hard rock mining operators pilot fuel-cell dozers to reduce ventilation infrastructure capital.
- Hybrid Engines:Diesel-electric configurations capture regenerative braking energy to supplement peak power demands. Komatsu's in-house hybrid development targets 400+ horsepower applications with measurable fuel consumption reduction.
Diesel engine technology anchors the volume base while automated blade control gains share at the steepest rate among technology segments.
Application:
Volume concentration in mining operations creates procurement scale effects that cascade through supplier pricing and service network requirements.
- Mining Operations:High-horsepower dozers in 500+ horsepower class push overburden and maintain haul road gradients. Iron ore producers in Western Australia operate the largest installed fleet of autonomous-capable units.
- Land Clearing:Root rake and brush blade attachments convert standard dozers for vegetation removal. Southeastern US timberland developers deploy specialized configurations for site preparation ahead of plantation establishment.
- Forestry Management:Winch-equipped machines extract felled timber from steep terrain inaccessible to forwarders. Nordic forest cooperatives specify protective undercarriage guarding for rocky soil conditions.
- Infrastructure Development:Multi-year project financing enables fleet bundling contracts with telematics-enabled availability guarantees. India's National Infrastructure Pipeline triggers replacement cycles among domestic earthmoving contractors.
- Quarrying:Ripper-equipped dozers fracture consolidated rock ahead of blasting operations. Aggregate producers in Germany specify Stage V-compliant units to meet EU Green Deal procurement technical scoring.
Infrastructure development anchors the volume base while mining operations gains share at the steepest rate among application segments.
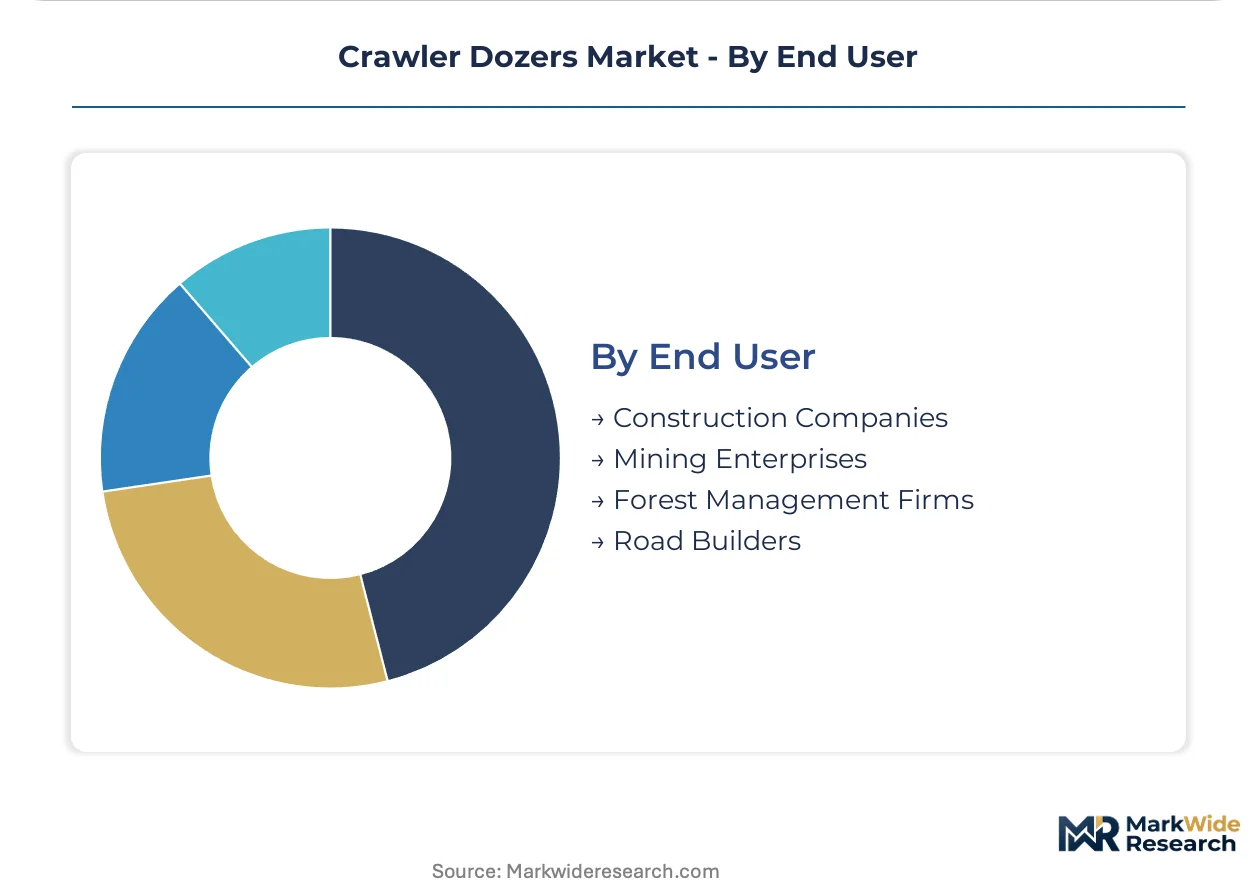
End User:
Customer type determines financing structure preferences, with mining enterprises favoring performance-based leasing and construction companies retaining capital purchase models.
- Construction Companies:General contractors deploy dozers across dispersed residential and commercial sites with variable utilization. Performance-based leasing with telematics verification displaces ownership among highway specialists in California.
- Mining Enterprises:Integrated operators synchronize dozer fleets with autonomous haul truck dispatch systems. Pilbara iron ore producers specify high-horsepower units with integrated GPS blade control for overburden management.
- Forest Management Firms:Timberland investment vehicles and state forestry agencies operate seasonal fleets with storage-intensive maintenance requirements. Biodegradable hydraulic fluid specifications now appear in Swedish procurement tenders.
- Road Builders:Specialized highway contractors require precision grading capability for subgrade and base course preparation. State-funded projects in Texas impose emission compliance documentation for equipment eligibility.
Construction companies anchor the volume base while mining enterprises gains share at the steepest rate among end user segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese manufacturers export high-horsepower crawler dozers to Australian iron ore operations, while Chinese OEMs supply cost-optimized mechanical units across Southeast Asian infrastructure projects. This trade-flow pattern concentrates procurement influence in mining-driven replacement cycles and state-funded construction programs.
Australia
Iron ore producers in Western Australia's Pilbara region operate the largest fleet of autonomous-capable crawler dozers for overburden management. The Australian government's Critical Minerals Facility funds fleet modernization at nickel and lithium projects. Perth-based mining contractors coordinate equipment procurement with autonomous haul truck dispatch systems.
United States
Highway contractors in Texas and California deploy GPS-controlled dozers for subgrade preparation under multi-year infrastructure financing. EPA Tier 4 Final emission standards filter equipment eligibility for federal highway tenders. Equipment lessors in the Southwest concentrate telematics-enabled rental fleets near Phoenix and Dallas-Fort Worth logistics corridors.
China
State-funded infrastructure tenders enforce GB emission standards that restrict non-certified crawler dozers from government contracts. Domestic road builders in Sichuan and Shandong provinces favor cost-optimized mechanical transmission units. XCMG and Shantui anchor production clusters in Jiangsu and Shandong for export to Belt and Road construction sites.
Germany
EU Stage V emission standards enforced by ECHA compel engine redesigns for quarrying and landfill applications. The EU Green Deal awards technical scoring points to machinery meeting Stage V particulate limits in public works tenders. Bavarian aggregate producers specify biodegradable hydraulic fluids to preempt regulatory penalties.
India
The National Infrastructure Pipeline triggers fleet replacement cycles among domestic earthmoving contractors executing road and rail projects. BIS certification requirements shape procurement specifications for state-funded construction equipment. Earthmoving contractors in Maharashtra and Gujarat concentrate fleet deployment around Mumbai-Ahmedabad industrial corridors.
Crawler Dozers Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and technology integration dimensions. The vendor base splits between consolidated premium-tier OEMs with integrated autonomous systems and fragmented mechanical transmission specialists serving cost-sensitive emerging markets. Two strategic archetypes dominate: integrated technology platforms bundling telematics and blade control, and component-optimized fabricators emphasizing transmission simplicity. Competitive moves concentrate on electrification partnerships and dealer network digitization.
Within the integrated technology tier, Caterpillar and Komatsu occupy positions defined by in-house powertrain development and autonomous system integration. Shantui exemplifies the cost-optimized archetype, anchoring mechanical transmission supply for emerging Asian contractors. John Deere sits within the agricultural-industrial crossover segment, leveraging common powertrain architectures across construction and farm equipment portfolios.
| Leading Market Players |
|---|
| Liebherr |
| CASE Construction Equipment |
| Caterpillar |
| LiuGong |
| Fiat Allis |
| Komatsu |
| John Deere |
| ACCO |
| Shantui |
| Others |
Cost & Logistics Intelligence
Electric drive powertrain substitution for conventional diesel architectures simultaneously shifts component sourcing toward East Asian battery supply clusters and compresses pricing premiums previously commanded by EPA Tier 4 Final compliant engine packages. Mining procurement officers in Western Australia now benchmark total cost of ownership across electrified and mechanical alternatives, forcing OEMs to reposition service bundling as the primary margin defense.
Pricing Analysis
Technology-generation pricing gaps separate Tier 4 Final diesel configurations from emerging hybrid-electric platforms and developmental fuel-cell alternatives. Three-tier pricing structure across premium autonomous-capable units, standard GPS-integrated models, and economy mechanical transmission segments reflects divergent certification burdens and after-sales service intensity. Cost compression in the mechanical tier intensifies because Chinese OEMs export standardized units through Belt and Road financing channels. Mining enterprises exhibit lowest price sensitivity given fleet-scale procurement and performance-guaranteed leasing structures, while domestic road builders in India demonstrate highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Busan port corridors constrain just-in-time delivery of forged undercarriage components for machines above 500 horsepower. High-wear track link and idler manufacturing concentrates in Japan, South Korea, and selected German forging operations. Raw material dependencies span high-grade steel plate, hydraulic fluid formulations, and semiconductor content for GPS and automation systems. Single-source vulnerability characterizes forged component supply for extreme-duty mining applications. Distribution runs through OEM-owned dealer networks with certified service capabilities rather than independent equipment traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against autonomous haulage systems that reduce ancillary dozer deployment in Pilbara-style operations. Incumbents must anchor customer relationships through integrated fleet management platforms that resist disintermediation.
For Market Incumbents: Compound defensive positioning through captive control over blade control software ecosystems and telematics data architectures. Deepen backward integration into electric drive motor production to offset Tier 4 Final aftertreatment margin erosion. Prioritize certification investment for EU Stage V and China's GB standards to filter import competition from uncertified fabricators.
For New Entrants and Emerging Players: Lead with specialized swamp dozer configurations for Indonesia's nickel processing corridor, where terrain constraints resist standardization by integrated OEMs. Target rental fleet digitization partnerships with telematics-native lessors in Texas and California seeking performance-guaranteed contract structures. Pursue go-to-market alignment with state-funded infrastructure tenders in India's National Infrastructure Pipeline.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors component-optimized specialists with electric drive readiness over pure mechanical transmission fabricators. Long-term viability across the projection horizon rests on electrification partnership access and dealer network digitization capabilities. Watch hydrogen fuel-cell pilot outcomes in Canadian underground mining as inflection indicator for powertrain technology trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drive Platform Development | Komatsu's in-house hybrid technology reduces fuel consumption in 400+ horsepower mining applications. |
| Autonomous Blade Control Integration | Caterpillar's GPS-controlled systems eliminate survey crew dependency in Western Australian overburden operations. |
| Dealer Network Digitization | Telematics-enabled hourly tracking allows Southwest US lessors to offer performance-guaranteed contracts. |
| Biodegradable Hydraulic Fluid Certification | German aggregate producers specify EU Green Deal-compliant fluids to preempt ECHA regulatory penalties. |
| Swamp Dozer Specialization | Marsh-terrain configurations serve Indonesia's Sulawesi nickel smelting projects with limited OEM competition. |
Research Approach
Cross-validation between OEM procurement director interviews and mining contractor fleet manager assessments anchors the qualitative findings on technology adoption trajectories. Primary fieldwork encompassed maintenance directors at Pilbara iron ore operations, aftermarket service heads at Australian dealer networks, plant engineers at German quarrying sites, and procurement teams at Indian road construction firms. Secondary validation drew from EPA engine certification databases, EU ECHA Stage V registration filings, Australian Bureau of Statistics mining capital expenditure series, and Indian BIS equipment certification records. Bottom-up unit shipment modeling triangulated against top-down mining production and infrastructure investment forecasts.
Sensitivity analysis tested forecast robustness across diesel-electric substitution speed scenarios and autonomous haulage penetration assumptions. The analytical framework segmented volume and value projections across the analysis window by powertrain technology, blade control automation level, application intensity, and end-user financing structure. CAGR derivation incorporated equipment replacement cycle analysis, mining production forecasts, and state-funded infrastructure pipeline commitments. Industry-specific inputs included iron ore overburden removal ratios and highway subgrade preparation equipment intensity metrics.
The analysis sits within stated boundaries; outcomes outside sustained mining capital expenditure and infrastructure financing commitment conditions would require recalibration. Forecasts reflect documented assumptions regarding emission standard enforcement timelines and electrification technology cost curves. Specific risk factors span commodity price volatility affecting mining fleet procurement, regulatory delay in emission standard phase-ins, and faster-than-anticipated autonomous haulage substitution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
US Welding Consumables Market
Construction Equipment
Global Floor Grinding Machine Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Deep Hole Drilling Machines Market
Construction Equipment
Ceramic Tile Printing Machine Market
Construction Equipment
Saudi Arabia Completion Equipment and Services Market
Construction Equipment
Portable Welding Generators Market
Construction Equipment
Industrial Nailers Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Global Tablet Press Machine Market
Construction Equipment
Global Portable Light Towers Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market