
 Latin America Heavy Construction Equipment Market | 2026-2036
Latin America Heavy Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Heavy Construction Equipment Market Analytics
The gap between premium-tier and commodity-grade heavy construction equipment is expanding across Latin America. Caterpillar leverages its integrated dealer network to sustain aftermarket revenue streams throughout Brazil. Komatsu Ltd. anchors its position through autonomous haulage technology leadership in Chilean copper operations. XCMG Group competes aggressively on delivered cost, occupying the value-tier segment where state-backed infrastructure tenders dominate purchasing criteria.
Latin America heavy construction equipment encompasses self-propelled machinery engineered for earthmoving, material handling, and vertical lifting at scales exceeding 12 metric tons operating weight, typically powered by diesel engines rated above 130 kW and built with high-tensile steel frames to withstand 15,000+ hour duty cycles in abrasive mining and civil works environments. Excavators command the largest installed base across the region, with hydraulic systems above 200 kW now standard for open-pit stripping operations. Contractors represent the fastest-growing end-user category as Brazil's highway concession program and Mexico's intermodal freight corridors accelerate fleet turnover. The rental service segment is gaining structural importance as mining companies outsource capital intensity to preserve balance-sheet flexibility amid mineral price volatility.
Brazil's ANTT freight regulations and Mexico's NOM emissions standards are tightening particulate matter thresholds, forcing OEMs to certify Tier 4 Final or Stage V equivalent powertrains for market access. Chile's environmental evaluation service, SEA, mandates closure-plan bonding that extends equipment depreciation schedules and reshapes replacement timing. Stakeholders must monitor how Peru's emerging lithium extraction concessions and Argentina's Vaca Muerta shale logistics corridors redirect fleet deployment patterns before competitor positioning crystallizes.
Market Dynamics
Fleet electrification timelines and autonomous retrofit compatibility are compressing replacement cycles across Latin American mining and infrastructure sectors. Brazil's ANTT freight regulations and Chile's SEA closure-plan bonding are forcing contractors to recalculate total cost of ownership equations before procurement.
Growth Catalysts
- Copper corridor expansion:Chilean open-pit operators are accelerating haul truck replacements to meet copper output targets amid electrification infrastructure buildouts.
- ANTT regulatory alignment:Brazil's freight weight and emissions standards are mandating newer-generation equipment for highway concession contracts.
- Autonomous haulage retrofit kits:Mining contractors in Peru are upgrading existing fleets with sensor-integrated control systems rather than purchasing new units.
Market Restraints
- Steel input volatility:High-tensile alloy plate prices fluctuate with Brazilian and Chinese mill output, compressing OEM margin buffers on long-delivery orders.
- Hydraulic component concentration:Precision pump and valve supply clusters in Germany and Japan create 14-18 week lead time exposure for Latin American assembly plants.
- Tier 4 Final certification lag:Mexican NOM emissions compliance timelines delay market entry for non-certified powertrain variants by 8-12 months.
Strategic Opportunities
- Argentina Vaca Muerta logistics:Shale extraction transport corridors require specialized heavy-haul tractors and low-ground-pressure trailers for remote Patagonian routes.
- Peru lithium extraction concessions:Brine pond construction and processing plant earthworks are creating demand for amphibious excavators and long-reach variants.
- Rental fleet digitization:Telematics-integrated hourly billing platforms are displacing traditional lease structures among mid-tier Brazilian contractors.
Industry Challenges
- Autonomous systems integration:Mining operators struggle to synchronize legacy fleet telematics with new OEM control architectures, requiring specialized technician training programs.
- Closure-plan bonding compliance:Chile's SEA mandates extended equipment depreciation schedules that conflict with standard 5-year replacement cycles, forcing balance-sheet restructuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Heavy Construction Equipment Market |
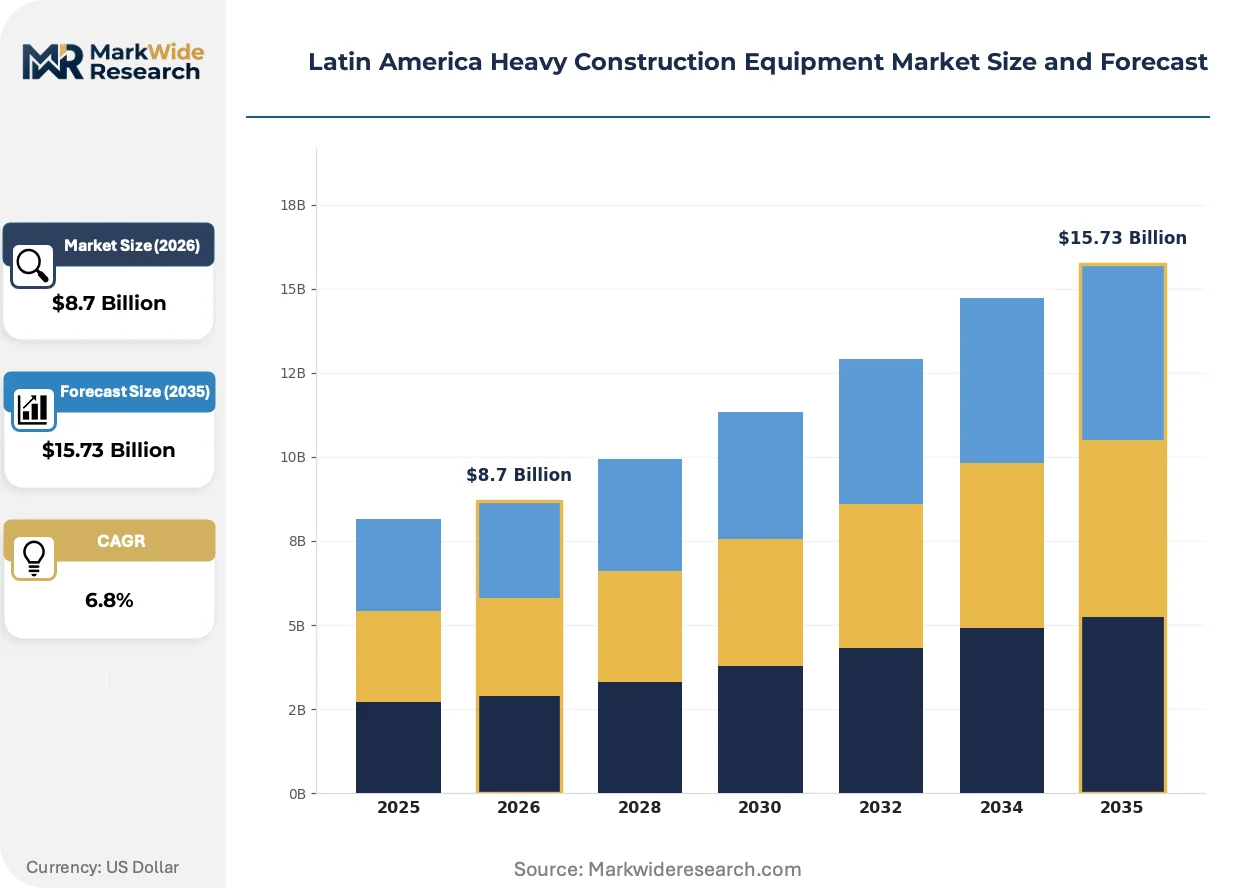
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Cranes, Backhoe Loaders End User: Contractors, Infrastructure Developers, Mining Companies, Government Agencies Deployment: On-Road, Off-Road, Urban, Rural Service Type: Rental, Repair, Maintenance, Sales |
| Companies Covered | Caterpillar, Komatsu Ltd., AB Volvo, Hitachi Construction Machinery Co., Ltd., Liebherr, CNH Industrial N.V., SANY Group, XCMG Group, Kobelco Construction Machinery Co., Ltd., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Heavy Construction Equipment Market Evolving Landscape
Electrification and autonomy are converging to redefine equipment specifications across Latin American extraction and infrastructure verticals. These shifts are compressing traditional procurement timelines and reshaping aftermarket service architectures.
Autonomous haulage retrofit technology is automating operator-dependent cycle times in Chilean copper corridors. Large open-pit miners are deploying sensor-fusion kits on existing truck fleets to reduce labor turnover exposure. This convergence of perception systems and legacy mechanical platforms is automating shift scheduling and fuel consumption optimization without full fleet replacement.
Brazil's ANTT freight regulations are tightening particulate matter thresholds for heavy-duty diesel engines operating on federal highway concessions. OEMs must now certify Tier 4 Final equivalent powertrains before bidding on infrastructure tenders. Southeastern Brazilian contractors are absorbing compliance costs through extended financing terms rather than equipment specification downgrades.
Telematics-enabled rental contracts are displacing traditional fixed-term leases among mid-cap Brazilian construction firms. Hourly utilization tracking and predictive maintenance bundling reduce capital intensity for highway concession bidders. This procurement model evolution is most visible in São Paulo state's intermodal freight corridor projects, where fleet flexibility outweighs ownership economics.
Latin America Heavy Construction Equipment Market Segmentation
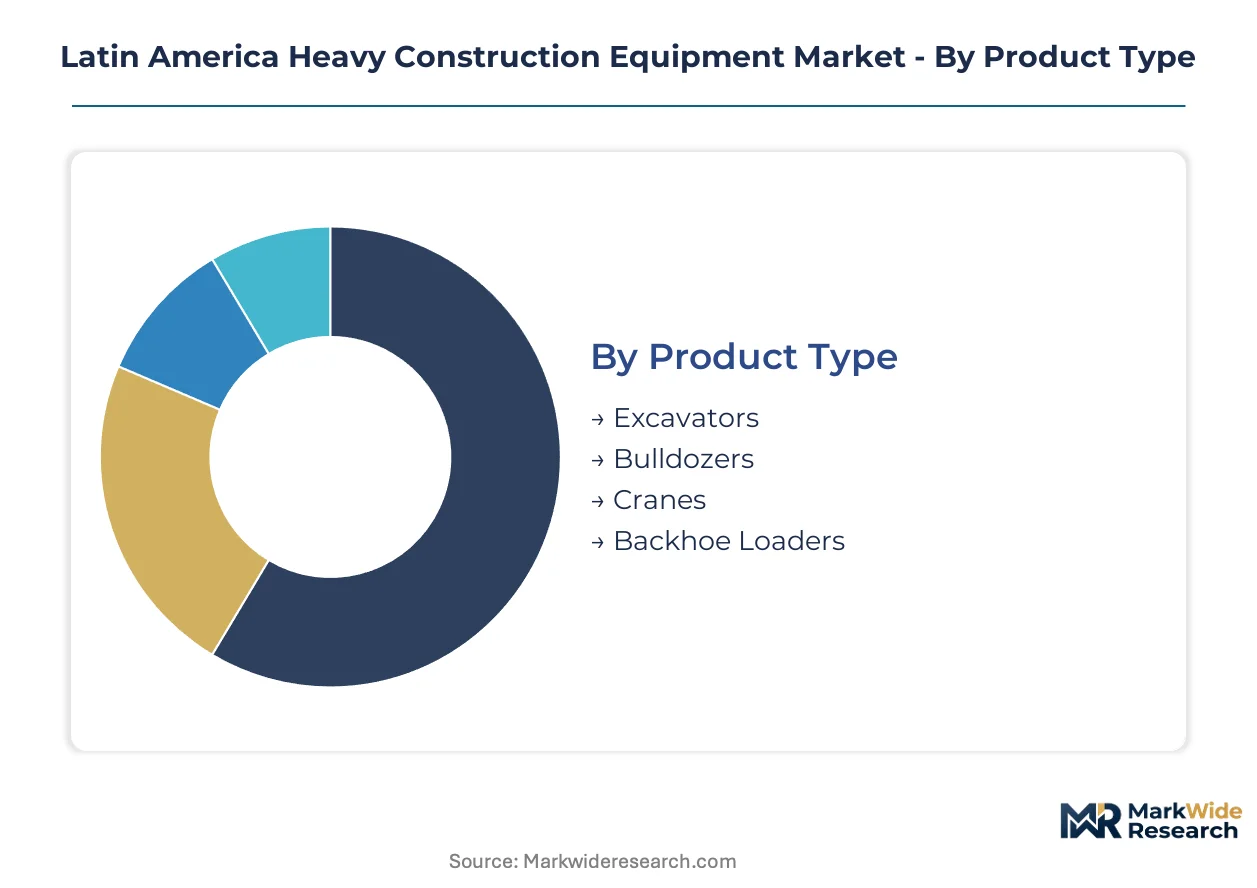
Segmentation across Latin America's heavy construction equipment market reveals how procurement priorities diverge between capital-intensive mining operators and project-based contractors. Understanding these splits enables OEMs to align powertrain certifications, financing structures, and aftermarket service architectures with distinct buyer economics.
Product Type:
Volume deployment concentrates in earthmoving categories where duty cycles exceed 15,000 hours, while premium specifications dominate vertical lifting applications requiring precision load control.
- Excavators:Hydraulic systems above 200 kW now constitute the regional standard for open-pit stripping operations in Chile's copper corridor. Brazilian mining contractors are accelerating replacements to meet ANTT emissions thresholds while preserving breakout force specifications for abrasive iron ore environments.
- Bulldozers:Track-type tractors with elevated sprocket undercarriages dominate Peru's Andean mining sites where ground pressure management determines slope stability. Fleet managers in Brazil's southeastern mining belt prioritize blade capacity over fuel efficiency given diesel subsidy structures for extractive industries.
- Cranes:All-terrain and crawler variants serve Mexico's intermodal freight corridor construction with lifting capacities above 300 tons.
- Backhoe Loaders:Versatile loader-excavator combinations address municipal infrastructure maintenance across mid-sized Brazilian municipalities.
Mature deployment sits with excavators. Newer deployment is concentrated in crane specifications for energy infrastructure logistics.
End User:
Customer type determines whether procurement favors ownership economics or operational flexibility, with mining operators optimizing total cost of ownership against contractor preferences for balance-sheet preservation.
- Contractors:Highway concession bidders in São Paulo state are adopting telematics-integrated rental contracts to align equipment costs with project milestones rather than capital depreciation schedules. This procurement shift is displacing traditional fixed-term leases among mid-cap Brazilian construction firms.
- Mining Companies:Chilean open-pit operators are deploying autonomous haulage retrofit kits on existing truck fleets to reduce labor turnover exposure without full fleet replacement. SEA closure-plan bonding requirements are extending depreciation schedules and compressing replacement cycle flexibility.
- Infrastructure Developers:Mexican energy reform beneficiaries are specifying Tier 4 Final powertrains for federal highway concession compliance.
- Government Agencies:State-backed tenders in Brazil's northern states prioritize delivered cost over technology specifications for rural road maintenance programs.
Volume concentration rests with mining companies. Procurement flexibility is expanding most quickly among contractors.
Deployment:
Operating environment dictates chassis configuration, with off-road specifications commanding premium pricing for undercarriage durability and on-road variants optimized for regulatory compliance.
- Off-Road:Specialized low-ground-pressure configurations serve Argentina's Vaca Muerta shale logistics corridors where remote Patagonian routes demand enhanced traction systems. Amphibious excavator variants are emerging for Peru's lithium extraction brine pond construction.
- On-Road:Heavy-haul tractors with Tier 4 Final certification dominate Brazil's ANTT-regulated federal highway concessions. Southeastern contractors absorb compliance premiums through extended financing terms rather than specification downgrades.
- Urban:Compact excavators below 20 metric tons address space-constrained infrastructure renewal in Mexico City's metropolitan area.
- Rural:Simplified hydraulic systems prioritize field serviceability over electronic complexity for remote maintenance access.
Established deployment patterns center on off-road mining applications. Emerging deployment is concentrating in on-road configurations for concession logistics.
Service Type:
Revenue model selection reflects capital availability, with rental structures gaining share among liquidity-constrained operators and integrated service contracts preserving OEM margin for premium-tier suppliers.
- Rental:Hourly utilization tracking with predictive maintenance bundling is displacing traditional lease structures among Brazilian highway concession bidders. Telematics platforms enable real-time billing transparency that aligns equipment costs with project cash flows.
- Sales:Direct procurement persists among Chilean copper operators with balance-sheet capacity to absorb autonomous haulage technology investments and SEA-mandated closure bonding.
- Maintenance:Scheduled service contracts with OEM dealer networks preserve residual value for fleet operators in Peru's emerging lithium concessions.
- Repair:Component remanufacturing programs address hydraulic system failures where German and Japanese precision pump supply creates 14-18 week lead time exposure.
Traditional revenue concentration remains with sales transactions. Structural shift is accelerating fastest in rental service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's southeastern mining belt concentrates Brazil's heaviest equipment deployment, with fleet turnover accelerating across Latin America's extractive and infrastructure corridors.
Brazil
Highway concession bidders in São Paulo state absorb ANTT Tier 4 Final compliance costs through extended financing terms. The southeastern mining belt drives excavator replacements as iron ore operators recalibrate depreciation schedules. Rio de Janeiro port logistics corridors demand certified heavy-haul tractors for intermodal freight expansion.
Chile
Copper corridor open-pit operators deploy autonomous retrofit kits to reduce labor turnover exposure without full fleet replacement. SEA closure-plan bonding mandates extend equipment depreciation schedules beyond standard cycles. Antofagasta's mining clusters concentrate haul truck replacements amid electrification infrastructure buildouts.
Mexico
Energy reform beneficiaries specify Tier 4 Final powertrains for federal highway concession compliance. NOM emissions timelines delay market entry for non-certified variants by 8-12 months. Mexico City's metropolitan renewal drives compact excavator demand for space-constrained vertical construction.
Peru
Andean mining contractors upgrade existing fleets with sensor-integrated control systems rather than purchasing new units. Emerging lithium extraction concessions create demand for amphibious excavators and long-reach variants. Lima's infrastructure procurement prioritizes delivered cost over technology specifications for rural road programs.
Argentina
Vaca Muerta shale logistics corridors require specialized heavy-haul tractors and low-ground-pressure trailers for remote Patagonian routes. Brine pond construction for lithium extraction drives amphibious equipment specifications. Neuquén's extraction transport networks anchor specialized chassis deployment for abrasive terrain conditions.
Latin America Heavy Construction Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Latin America's equipment procurement tiers. Integrated manufacturers with captive dealer networks sustain aftermarket revenue streams against price-focused challengers with direct sales models. Three archetypes dominate: premium-tier OEMs with autonomous technology portfolios, value-tier suppliers competing on delivered cost, and rental service platforms with telematics-integrated billing. Consolidation pressure favors M&A among mid-tier distributors, while technology licensing partnerships accelerate autonomous retrofit penetration.
Among Japanese and European heavy machinery specialists, Komatsu Ltd. and Hitachi Construction Machinery Co., Ltd. exemplify the integrated technology archetype with autonomous haulage positioning. Caterpillar anchors the premium-tier service infrastructure model through its regional dealer network density. XCMG Group occupies the value-tier segment where state-backed infrastructure tenders dominate purchasing criteria.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu Ltd. |
| AB Volvo |
| Hitachi Construction Machinery Co., Ltd. |
| Liebherr |
| CNH Industrial N.V. |
| SANY Group |
| XCMG Group |
| Kobelco Construction Machinery Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Autonomous haulage retrofit technology is compressing equipment replacement cycles while simultaneously concentrating procurement power among technology-integrated OEMs across Brazil and Chile. This convergence of automation hardware and legacy fleet economics is reshaping both upfront capital requirements and long-term service revenue structures for mining contractors navigating ANTT emissions mandates and SEA closure bonding.
Pricing Analysis
Outcome-based uptime guarantees now anchor pricing negotiations between Chilean copper operators and premium-tier OEMs, with contracts tying payment schedules to haul truck availability metrics rather than unit delivery. Three-tier pricing structure across premium, standard, and economy levels reflects divergent certification grades, with Tier 4 Final compliance commanding substantial premiums in Brazil's southeastern mining belt. Cost compression in the value tier is intensifying because XCMG Group and SANY Group are absorbing steel input volatility to secure state-backed infrastructure tenders. Government agencies in Brazil's northern states exhibit highest price sensitivity, while Chilean mining companies with SEA-mandated bonding capacity demonstrate lowest sensitivity to specification premiums.
Supply Chain Analysis
Component remanufacturing flows from Peru's emerging lithium concessions back to Brazilian assembly plants are creating reverse-logistics infrastructure that reduces hydraulic system lead time exposure. Precision pump and valve supply clusters in Germany and Japan feed Latin American assembly operations, while high-tensile alloy plate sourcing draws from Brazilian and Chinese mill output. Single-source vulnerability around German-Japanese hydraulic components creates structural risk for 14-18 week procurement cycles. Distribution runs through captive dealer networks for Caterpillar and Komatsu, while value-tier competitors employ direct sales models for state tender participation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's ANTT freight regulations and Mexico's NOM emissions standards have erected compliance moats that reward OEMs with certified Tier 4 Final powertrain portfolios, filtering out non-compliant competitors from federal concession bidding.
For Market Incumbents: Deploy autonomous retrofit certification programs to lock in aftermarket revenue from Chilean copper operators facing SEA-mandated depreciation schedule extensions. Deepen captive dealer network density across Brazil's southeastern mining belt to preempt XCMG Group's state tender penetration. Counter SANY Group's delivered-cost aggression through telematics-integrated service bundling that demonstrates total cost of ownership superiority over upfront price gaps. For New Entrants and Emerging Players: The mid-tier contractor segment in São Paulo state's highway concession programs represents the most penetrable white-space target, where telematics-enabled rental contracts are displacing traditional fixed-term leases. Target Peru's emerging lithium extraction concessions with amphibious excavator specifications that established OEMs have not yet configured for brine pond construction. Pursue joint venture structures with Brazilian regional distributors to bypass captive network barriers without capital-intensive dealer buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier distributor consolidation plays as autonomous technology licensing demands scale beyond family-owned network capabilities. Five-to-ten year viability favors OEMs with backward integration into hydraulic component sourcing or captive remanufacturing infrastructure. Monitor Argentina's Vaca Muerta logistics corridor development velocity as the critical inflection signal for specialized heavy-haul tractor demand.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Retrofit Certification | Enables aftermarket revenue capture from Chilean copper operators extending fleet depreciation cycles. |
| Tier 4 Final Powertrain Compliance | Unlocks federal highway concession bidding in Brazil under ANTT particulate matter thresholds. |
| Telematics-Integrated Rental Platforms | Aligns equipment costs with project cash flows for São Paulo state highway contractors. |
| Amphibious Excavator Development | Addresses Peru lithium extraction brine pond construction specifications absent from standard portfolios. |
| Remanufacturing Infrastructure Buildout | Mitigates German-Japanese hydraulic component lead time exposure for Latin American assembly plants. |
Research Methodology
Document review covered SEC filings from heavy equipment OEMs, ANTT regulatory bulletins, SEA environmental evaluation standards, and Chilean mining association production reports, complemented by interviews with maintenance directors at Brazilian iron ore operators, procurement leads at Mexican infrastructure developers, aftermarket service heads at regional Caterpillar dealers, and fleet managers at Peruvian copper contractors. Secondary validation drew from customs trade data, Brazilian mining federation equipment deployment surveys, and Mexican federal concession registry records. Bottom-up unit deployment estimates were triangulated against top-down market value assessments.
Historical replacement cycle patterns were cross-referenced against panel input from OEM regional executives to model demand trajectories across the analysis window. Segmentation dimensions included product type, end-user category, deployment environment, and service model, with additional granularity on powertrain certification tier. CAGRs were derived from equipment stock depreciation schedules overlaid with regulatory compliance deadlines and mineral price volatility assumptions. Forecast inputs incorporated ANTT enforcement timelines, SEA bonding requirement phase-ins, and lithium extraction concession award velocities.
Inputs from Brazilian regulatory filings and Chilean mining operator disclosures were available through the study window; gaps in Peruvian lithium project development timelines and Argentine shale logistics corridor completion schedules introduce uncertainty bands around outer-year projections. Forecasts reflect assumptions regarding mineral price recovery trajectories and concession program continuity. Practitioners should monitor ANTT inspection enforcement intensity and SEA closure bond claim rates for early signals of replacement cycle compression or extension.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Oxy-Fuel Welding Equipment Market
Construction Equipment
Italy Metal Fabrication Equipment Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Refurbished Construction Equipment Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Global Airport Snow Removal Vehicles and Equipment Market
Construction Equipment
Saudi Arabia Construction Equipment Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Roadheaders Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
Latin America Construction Equipment Market
Construction Equipment
Hammer Unions Market
Construction Equipment
LAMEA Water Pump Market