
 Global Adhesive Bandages Market | 2026-2036
Global Adhesive Bandages Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adhesive Bandages Market Foresight
Home care buyers is reorganizing demand patterns across the adhesive bandages landscape as post-acute preferences shift toward self-administered treatment. Johnson & Johnson Services, Inc. anchors its position through deep retail pharmacy partnerships and heritage brand recognition. 3M competes via materials science leadership in breathable film technologies. Medline Industries controls substantial hospital supply contract volume through centralized procurement platforms.
Adhesive bandages are pressure-sensitive medical dressings comprising a woven or nonwoven backing substrate coated with a hypoallergenic adhesive layer and an absorbent nonstick pad, designed to protect minor wounds from contamination while permitting moisture vapor transmission. Fabric variants dominate institutional procurement due to superior conformability and tensile strength during joint movement. Waterproof segments command premium positioning in sports injuries applications where sustained adhesion during perspiration exposure determines repurchase behavior. Home care end users represent the fastest-expanding channel as telehealth protocols and discharge acceleration push wound management beyond clinical walls.
The U.S. FDA's 510(k) clearance framework governs adhesive bandage market entry, while the EU MDR intensifies clinical documentation requirements for products claiming antimicrobial properties. India's CDSCO aligns with BIS standards for sterile medical dressings, creating compliance complexity for exporters targeting government tender programs. Stakeholders must monitor evolving biocompatibility testing protocols and home care reimbursement policies to anticipate where procurement authority will migrate next.
Market Dynamics
Home care migration is compressing institutional procurement volumes while fragmenting buyer power across retail pharmacies, direct-to-consumer platforms, and telehealth-integrated distributors. This demand dispersion is forcing manufacturers to reconfigure fulfillment networks and packaging formats simultaneously.
Growth Catalysts
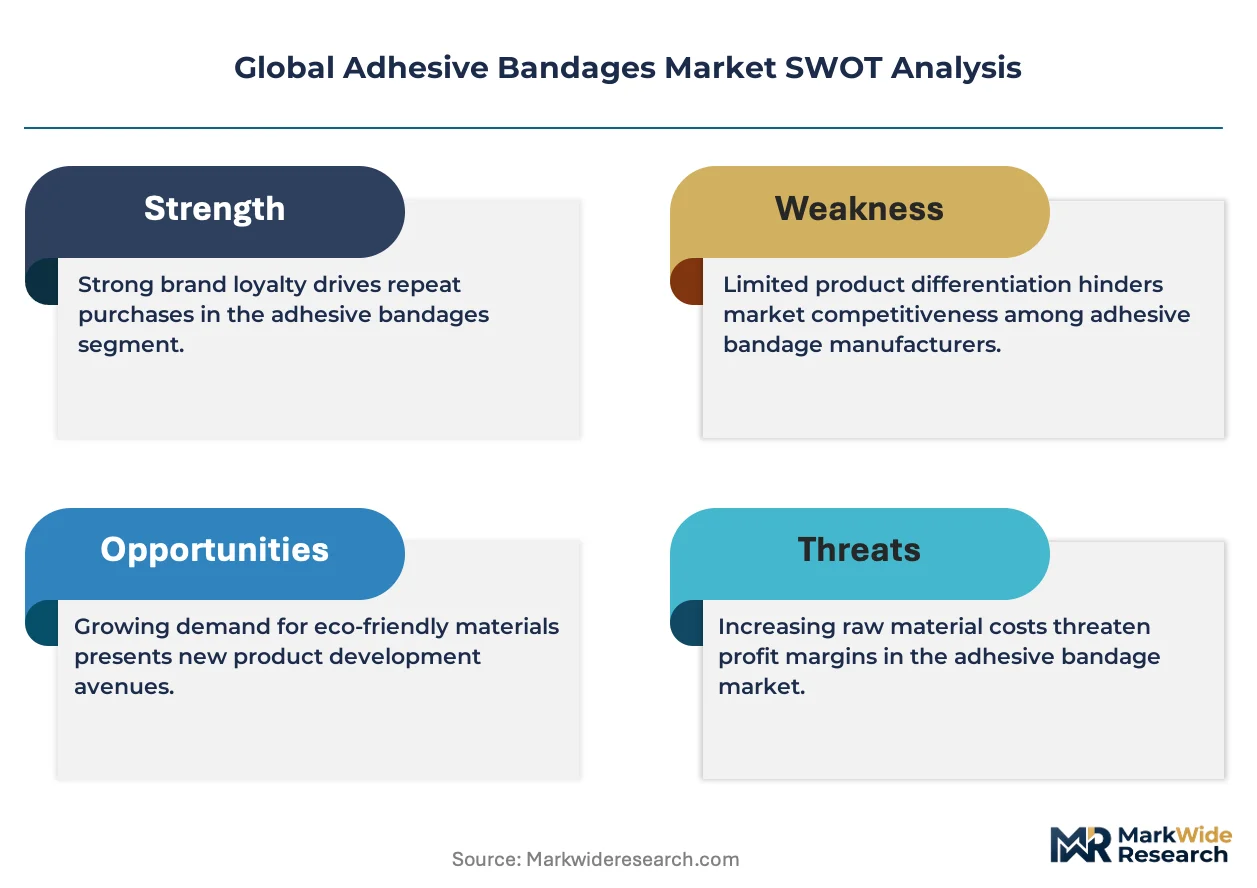
- EU MDR antimicrobial claims pathway:Products demonstrating documented bioburden reduction now command preferential formulary placement in German and French hospital systems, accelerating R&D investment in silver-ion and PHMB-impregnated substrates.
- India's Ayushman Bharat rural expansion:Government tender volumes for sterile dressings in tier-3 and tier-4 cities have tripled procurement throughput, creating dedicated manufacturing capacity in Gujarat and Tamil Nadu clusters.
- Breathable film lamination:Advanced polyurethane coextrusion technologies enable moisture vapor transmission rates exceeding 800 g/m²/24hr, satisfying sports medicine specifications previously requiring specialized hydrocolloid alternatives.
Market Restraints
- Medical-grade adhesive feedstock concentration:Hydrogenated rosin ester and acrylic emulsion supply chains cluster in Zhejiang province and the US Gulf Coast, exposing converters to petrochemical volatility and tariff friction.
- FDA 510(k) substantial equivalence barriers:Novel substrate materials lacking predicate devices face 18-24 month clearance timelines, freezing incremental innovation in antimicrobial and smart bandage categories.
- Advanced wound care substitution:Hydrofiber and foam dressings for exuding wounds capture cases that previously used multiple layered fabric bandages, compressing unit volume in post-surgical discharge kits.
Strategic Opportunities
- Indonesia's universal health coverage scale-up:BPJS Kesehatan enrollment expansion into Eastern provinces creates first-mover advantage for localized sterile dressing production serving archipelago logistics constraints.
- Wearable biosensor convergence:Integration of impedance-based hydration monitoring with standard adhesive substrates enables remote wound assessment, opening reimbursement pathways through Medicare remote patient monitoring codes.
- Amazon Pharmacy and CVS Caremark platform centralization:E-pharmacy aggregators are consolidating SKU rationalization authority, favoring suppliers with direct fulfillment infrastructure and private-label manufacturing flexibility.
Industry Challenges
- Biocompatibility testing capacity bottlenecks:ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization study backlogs at contracted laboratories extend product launch timelines by 4-6 months for novel adhesive formulations.
- Legacy ERP-to-EDI integration complexity:Hospital supply chain digitization mandates require real-time inventory visibility, forcing mid-tier manufacturers to absorb SAP or Oracle implementation costs without guaranteed contract renewal.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adhesive Bandages Market |
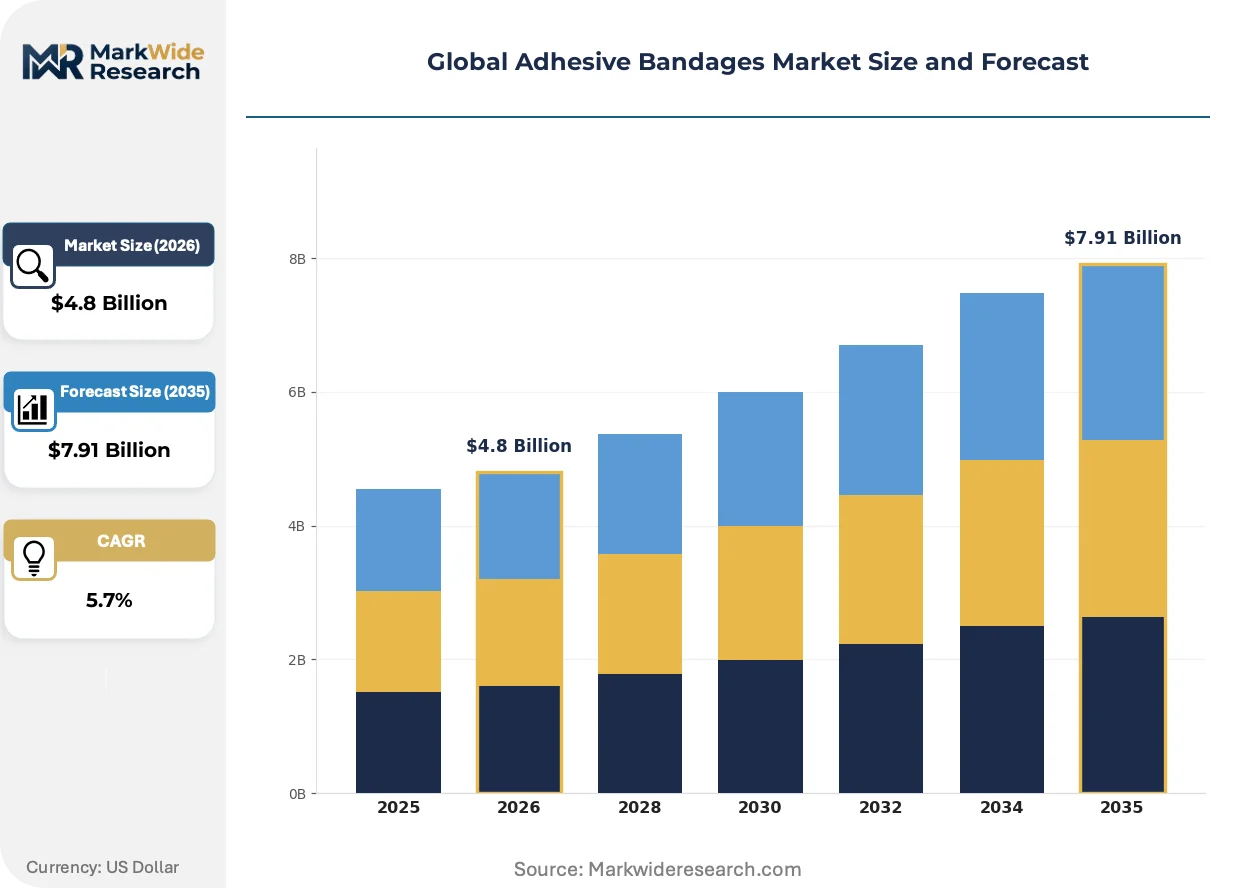
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fabric, Plastic, Waterproof, Foam, Transparent Application: First Aid, Wound Care, Sports Injuries, Surgical Procedures, Dermatology End User: Hospitals, Clinics, Emergency Services, Home Care, Nursing Homes Distribution Channel: Pharmacies, Online Stores, Supermarkets, Medical Suppliers, Direct Sales |
| Companies Covered | Johnson & Johnson Services, Inc., 3M, Beiersdorf AG, Cardinal Health, Medline Industries, ConvaTec Inc., Smith & Nephew, B. Braun Melsungen AG, Dynarex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adhesive Bandages Market Shifts & Advancements
Materials science convergence with digital health infrastructure is redefining what adhesive bandages measure, transmit, and enable beyond passive wound coverage. Three developments are compressing development cycles and expanding functional boundaries.
Printed electronics integration is miniaturizing sensor arrays onto flexible substrates without compromising conformability or adhesion. Sports medicine clinics and diabetes wound programs in the US and Germany are piloting these devices for continuous moisture and temperature monitoring. The technology is compressing the gap between consumer-grade wearables and clinical monitoring equipment, enabling home-based surveillance previously requiring outpatient visits.
REACH Annex XVII restrictions on skin-sensitizing preservatives are forcing reformulation of acrylic adhesive systems across EU-manufactured product lines. Industrial consequence includes accelerated migration to hot-melt silicone adhesives with lower allergenic potential but higher unit cost. Pediatric and geriatric segments are most affected, with Nordic procurement authorities now mandating preservative-free documentation for tender eligibility.
Subscription-based replenishment models are displacing episodic retail purchasing among chronic wound patient populations. Direct-to-patient platforms integrated with telehealth providers in Australia and the UK are capturing recurring revenue streams that pharmacies previously dominated. This shift is most visible in vascular ulcer and pressure injury management, where predictable consumption patterns align with automated fulfillment economics.
Global Adhesive Bandages Market Segmentation
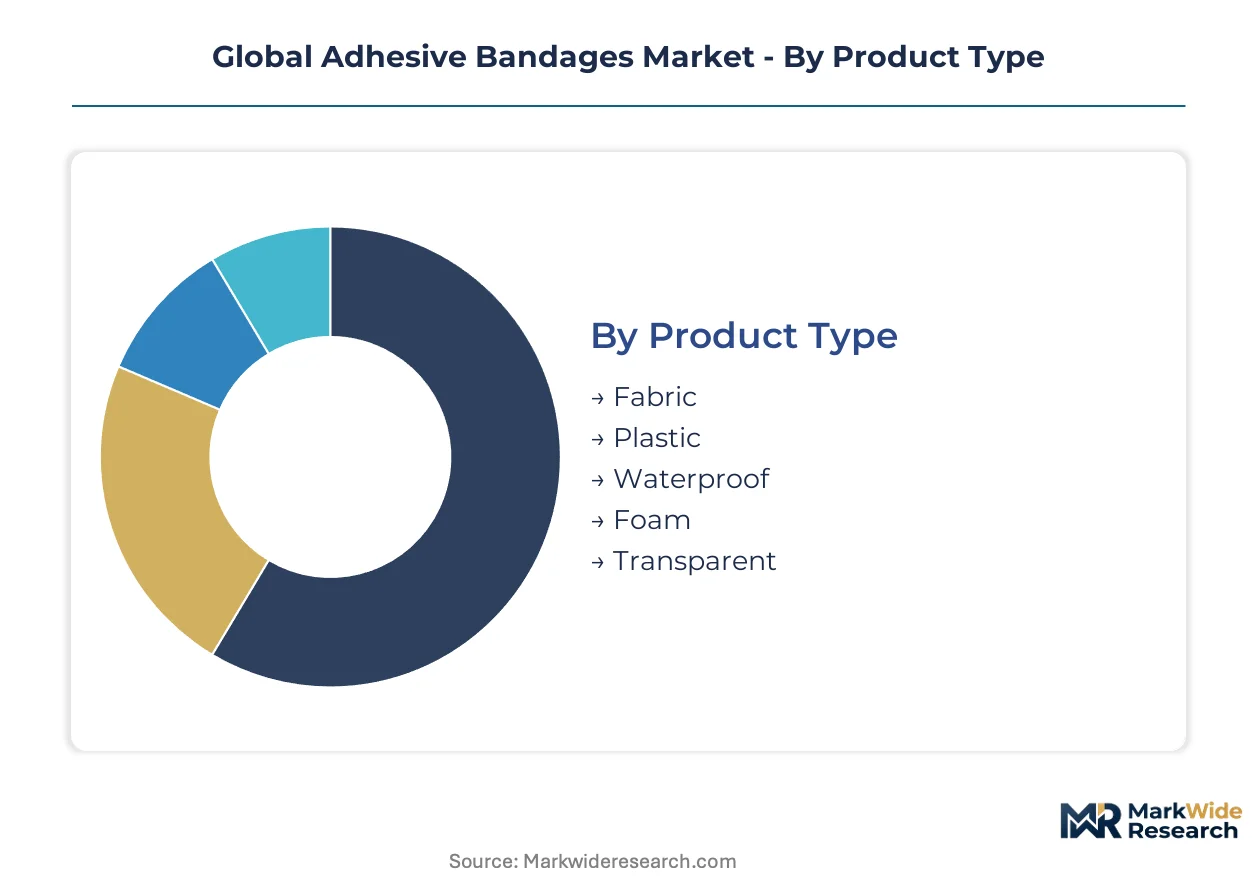
Segmentation in adhesive bandages reveals how procurement authority fragments across clinical settings and retail channels. Manufacturers must align substrate technologies with specific wound environments and buyer workflows to defend shelf space and contract renewals.
Product Type:
Fabric variants dominate domestic hospital procurement in the US, Germany, and Japan, while waterproof and transparent segments drive export-led growth into tropical climates and sports medicine markets.
- Fabric:Woven cotton or rayon substrates bonded with zinc oxide or synthetic rubber adhesives deliver tensile strength during joint flexion. US hospital systems and German ambulatory surgery centers specify fabric for post-operative discharge kits, though raw cotton price volatility squeezes converter margins.
- Waterproof:Polyurethane film laminates with hydrophobic coatings maintain adhesion during perspiration or immersion. Australian surf rescue programs and Brazilian football club medical rooms specify these for field trauma, with demand climbing fastest in Southeast Asian occupational health tenders.
- Plastic:Polyethylene or polypropylene backings with porous acrylic adhesives offer lowest unit cost for high-volume institutional procurement. India's Ayushman Bharat rural dispensaries and Nigerian primary health centers standardize on plastic for basic wound coverage.
- Foam:Polyurethane foam substrates with silicone or acrylic adhesives cushion bony prominences and absorb light exudate. UK district nursing services and Japanese long-term care facilities specify foam for pressure injury prevention in wheelchair users.
- Transparent:Thin polyurethane films permit wound visualization without dressing removal. US outpatient wound clinics and French hospital-at-home programs favor transparent substrates for monitoring surgical incisions remotely.
Fabric holds the largest share; momentum sits with waterproof.
Application:
Cost tier stratification separates commodity first aid from premium surgical applications, with reimbursement codes determining viable price floors in each bracket.
- Wound Care:Chronic wound management requires breathable substrates with moisture vapor transmission rates above 500 g/m²/24hr. German statutory health insurance funds and US Medicare Advantage plans now reimburse advanced bandages for diabetic foot ulcers, expanding home-based consumption.
- First Aid:Standard adhesive strips for minor lacerations and abrasions constitute the highest unit volume segment. Mass retail channels in the US, UK, and Australia move first aid SKUs through pharmacy and supermarket chains with minimal clinical oversight.
- Sports Injuries:Elastic fabric or cohesive bandages with aggressive adhesives withstand dynamic movement and perspiration. Professional sports franchises in Spain, Italy, and Argentina specify sports-specific variants with team colors and antimicrobial claims.
- Surgical Procedures:Sterile island dressings for post-operative incision coverage require validated sterilization and biocompatibility documentation. Japanese surgical centers and Swiss private clinics demand lot traceability and ethylene oxide residual testing.
- Dermatology:Hypoallergenic silicone adhesives minimize skin trauma for patients with adhesive-related contact dermatitis. Pediatric wards in Nordic countries and geriatric units in the Netherlands mandate dermatology-grade substrates for fragile skin populations.
Wound care commands premium pricing; first aid generates volume throughput.
End User:
Customer type determines packaging formats, with institutional buyers requiring bulk sterile cases and home care favoring individual peel pouches or retail blister packs.
- Home Care:Patients discharged under telehealth monitoring or managing chronic wounds independently drive fastest-expanding consumption. US remote patient monitoring reimbursement codes and UK NHS virtual ward programs accelerate direct-to-patient fulfillment models.
- Hospitals:Centralized procurement departments negotiate multi-year supply agreements with formulary restrictions. French public hospital groups and Italian regional health authorities consolidate purchasing through cooperative buying organizations.
- Clinics:Outpatient facilities require mixed assortments spanning basic first aid to post-procedural dressings. Mexican IMSS primary care clinics and Indonesian community health centers balance cost constraints with infection control protocols.
- Emergency Services:Ambulance and first responder units need rapid-application bandages in compact packaging. Australian rural flying doctor services and South African emergency medical response fleets specify trauma dressings with integrated pressure applicators.
- Nursing Homes:Long-term care facilities prioritize skin-friendly adhesives for elderly residents with fragile integument. Canadian provincial long-term care standards and German Pflegekassen reimbursement rules shape tender specifications.
Hospitals retain procurement volume dominance; home care climbs the fastest.
Distribution Channel:
Supply concentration varies sharply, with medical suppliers controlling institutional contracts while platform aggregators capture retail and direct-to-consumer flows.
- Pharmacies:Community and hospital pharmacies maintain formulary influence through pharmacist counseling and insurance adjudication. US CVS and Walgreens chains, plus Boots in the UK, rationalize SKUs based on turnover velocity and private-label margin contribution.
- Online Stores:E-pharmacy platforms and marketplace sellers enable subscription replenishment for chronic wound patients. Amazon Pharmacy in the US, DocMorris in Germany, and 1mg in India aggregate demand and disintermediate traditional wholesale tiers.
- Supermarkets:Mass merchandisers move basic first aid SKUs through high-velocity retail with minimal clinical engagement. Walmart in the US, Tesco in the UK, and Aeon in Japan leverage private-label manufacturing for price-positioned alternatives.
- Medical Suppliers:Specialized distributors like Medline, Cardinal Health, and McKesson control hospital and clinic contract logistics. These intermediaries require EDI integration, consignment inventory, and compliance with group purchasing organization terms.
- Direct Sales:Manufacturers bypass intermediaries for large institutional accounts or government tender programs. India's CDSCO-registered producers sell directly to state medical services corporations; US Department of Veterans Affairs contracts similarly eliminate distributor markups.
Medical suppliers anchor institutional volume; online stores gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites Asia-Pacific supply chain dominance for medical dressing exports. Rotterdam's Europoort distribution complex anchors European import logistics for sterile wound care products. The Port of Los Angeles-Long Beach twin facility shapes North American inventory positioning for retail pharmacy replenishment cycles.
United States
Telehealth reimbursement expansion and Medicare remote patient monitoring codes accelerate home care bandage consumption. The FDA's 510(k) clearance framework governs antimicrobial claim substantiation for novel substrates. Manufacturing concentrates in North Carolina's Research Triangle and Minnesota's Twin Cities corridor, where medical device clusters co-locate with polymer science research centers.
Germany
Statutory health insurance funds drive premium pricing acceptance for advanced wound care substrates in outpatient settings. The EU MDR intensifies clinical documentation requirements for products claiming bioburden reduction. Production gravity sits in North Rhine-Westphalia's Ruhr industrial belt, where adhesive tape converters cluster near petrochemical feedstock pipelines.
India
Ayushman Bharat rural health mission procurement triples tender volumes for sterile dressings in tier-3 and tier-4 cities. CDSCO alignment with BIS standards creates compliance complexity for exporters targeting government medical stores. Manufacturing hubs in Gujarat's Ahmedabad-Surat corridor and Tamil Nadu's Chennai-Coimbatore belt expand dedicated capacity for basic wound care supplies.
Japan
Aging demographics and long-term care facility expansion sustain demand for skin-friendly silicone adhesive variants. PMDA's pharmaceutical affairs law governs medical device quality management system certifications. Industrial concentration in Osaka-Kobe's Hanshin manufacturing zone and Tokyo's Kanto hinterland supports precision coating technologies for transparent film substrates.
Brazil
ANVISA's medical device registration requirements shape import pathways for sterile dressing manufacturers. Universal health system expansion into Northern and Northeastern states creates distribution infrastructure challenges across Amazonian logistics networks. São Paulo state's industrial corridor hosts regional converting operations serving Mercosur markets.
Global Adhesive Bandages Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational agility dimensions. The vendor base stratifies into three tiers: diversified healthcare conglomerates with retail pharmacy anchoring, medical supply distributors with hospital contract dominance, and regional converters with government tender specialization. Strategic moves concentrate on M&A for geographic footprint expansion and portfolio diversification into adjacent advanced wound care categories.
Among diversified healthcare conglomerates, Johnson & Johnson Services, Inc. and 3M occupy positions reflecting heritage brand recognition and materials science capabilities respectively. Medline Industries exemplifies the distributor archetype with centralized procurement platform influence. These three entities represent distinct competitive vectors: consumer-facing retail anchoring, industrial technology leadership, and institutional supply chain integration.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| 3M |
| Beiersdorf AG |
| Cardinal Health |
| Medline Industries |
| ConvaTec Inc. |
| Smith & Nephew |
| B. Braun Melsungen AG |
| Dynarex Corporation |
| Others |
Supply & Pricing Matrix
Capacity utilization at Zhejiang province adhesive resin plants and US Gulf Coast petrochemical corridors shapes margin structures across converter tiers. Scale advantages at these feedstock nodes translate directly into price floors for fabric and waterproof bandage categories, while smaller regional converters absorb volatility through contract renegotiation cycles.
Pricing Analysis
Volume-discount tiering structures separate hospital GPO procurement from retail pharmacy and direct-to-consumer channels. Three-tier pricing stratification across premium antimicrobial, standard sterile, and economy plastic variants reflects certification grade and moisture vapor transmission performance. Cost compression in economy tiers intensifies as India's Ayushman Bharat tender volumes concentrate buying power. Hospital systems demonstrate lowest price sensitivity due to formulary lock-in, while supermarket private-label buyers drive hardest unit-cost negotiations.
Supply Chain Analysis
Just-in-time inventory strategies dominate hospital and clinic procurement through distributor-managed consignment programs, while strategic stockpiling characterizes government tender fulfillment in India and Indonesia. Hydrogenated rosin ester and acrylic emulsion feedstocks draw from Zhejiang province, US Gulf Coast, and German Ruhr industrial belt chemical complexes. Single-source vulnerability concentrates in medical-grade adhesive precursors. Distribution runs through Medline, Cardinal Health, and McKesson for institutional accounts, with Amazon Pharmacy and CVS Caremark capturing direct-to-patient flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized coating capabilities for breathable polyurethane films and antimicrobial substrate integration represent scarce assets that differentiate sustainable competitive position. Manufacturers lacking in-house lamination expertise face margin compression as raw material volatility accelerates.
For Market Incumbents: Consolidate backward integration into medical-grade adhesive production to offset petrochemical price swings and tariff exposure. Acquire regional converters in Gujarat and Tamil Nadu to capture India's government tender growth. Defend hospital GPO relationships through EDI-enabled inventory visibility investments that mid-tier competitors cannot replicate. For New Entrants and Emerging Players: Telehealth-integrated replenishment services present under-served white space where incumbents lack direct-to-patient infrastructure. Target Australia's chronic wound subscription market and UK's NHS virtual ward programs through partnerships with remote patient monitoring platforms. Pursue white-label manufacturing for Amazon Pharmacy and DocMorris to bypass wholesale tier markups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with silicone adhesive formulation capabilities serving geriatric and pediatric segments. Long-term viability favors targets with EU MDR antimicrobial claim documentation and Medicare remote patient monitoring code eligibility. Watch FDA 510(k) clearance timeline compression for novel substrate materials as inflection signal for innovation-cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Substrate R&D Investment | Silver-ion and PHMB-impregnated films secure preferential formulary placement in German and French hospital systems. |
| Direct-to-Patient Platform Partnership | Integration with telehealth providers captures recurring revenue streams previously dominated by retail pharmacy channels. |
| EU MDR Compliance Certification | Documented bioburden reduction capabilities unlock premium pricing in statutory health insurance reimbursement pathways. |
| Southeast Asia Manufacturing Footprint | Localized production in Indonesia and Vietnam addresses archipelago logistics constraints and BPJS Kesehaten procurement scale-up. |
| Wearable Biosensor Integration | Impedance-based hydration monitoring enables Medicare remote patient monitoring reimbursement and chronic wound surveillance. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and adhesive tape converters and secondary validation through FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis around raw material price volatility and regulatory clearance timeline scenarios informs the analytical framework. Segmentation dimensions include product substrate type, application setting, end-user facility category, and distribution channel structure. CAGRs derive from installed base expansion rates and per-capita consumption intensity trends, with inputs from aging demographic trajectories and telehealth reimbursement policy evolution.
Underlying assumptions cover sterile dressing demand elasticity, regulatory pathway stability, and supply chain continuity, with deviation risk concentrated in biocompatibility testing capacity bottlenecks and adhesive feedstock geopolitical exposure. Revision becomes warranted when FDA 510(k) substantial equivalence barriers or EU MDR clinical documentation requirements cross thresholds that freeze product launch pipelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Abdominal Compression Garments Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Microtome Knife Sharpeners Market
Medical Supplies
Medical Specialty Bags Market
Medical Supplies
Global Medical Waste Containers Market
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Nonwoven Surgical Drapes Market
Medical Supplies
Physiological Saline Market
Medical Supplies
Disposable Hospital Supplies Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
Emergency Transfer Vacuum Mattress Market
Medical Supplies
North America Surgical Glue Market
Medical Supplies
Yankauer Suction Tips Market
Medical Supplies
Endoscope Protective Barrier Covers Market
Medical Supplies
Serum Separating Tubes Market
Medical Supplies
Specimen Retrieval Bags Market