
 Wound Evacuators Market | 2026-2036
Wound Evacuators Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Evacuators Market Analytics
The EU Medical Device Regulation is rebalancing the cost-of-entry calculus for wound evacuator manufacturers seeking CE marking in Europe. Zimmer Biomet leverages its orthopedic implant ecosystem to bundle suction systems with joint replacement kits. Medtronic anchors its position through deep hospital contracting relationships across acute care networks. Becton Dickinson and Company differentiates via closed-loop manufacturing of sterile disposable canisters.
Wound evacuators are closed-suction drainage devices that apply negative pressure to surgical sites, typically operating at 80-120 mmHg to remove exudate, blood, and serous fluid while promoting tissue approximation and reducing hematoma formation. These systems comprise a suction source, collection canister, tubing, and perforated drain, with materials ranging from silicone to PVC depending on biocompatibility requirements and dwell time. Pneumatic systems dominate hospital procurement for their reliability in high-volume surgical suites, while electric models are gaining traction in ambulatory surgical centers where portability and programmable pressure settings reduce nursing intervention. Manual evacuators occupy a stable niche in cost-sensitive clinics and post-acute settings where intermittent suction suffices. Orthopedic surgery applications generate the strongest margin pools due to longer drain dwell times and higher consumable turnover per procedure.
The FDA regulates wound evacuators as Class II medical devices under 510(k) premarket notification pathways, while the EU MDR requires notified body involvement and clinical evidence for sustained negative pressure systems. Health Canada's PMRA aligns with FDA risk classifications but demands additional biocompatibility documentation for silicone formulations in long-term implants. Stakeholders must monitor evolving sterilization validation requirements and post-market surveillance obligations as regulators tighten traceability for single-use surgical accessories.
Market Dynamics
EU MDR recertification timelines are compressing supplier margins as notified body bottlenecks extend clinical evidence requirements for Class IIa suction devices. Manufacturers face a structural squeeze between escalating conformity costs and hospital procurement consolidation.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient joint replacement volumes in Germany are accelerating demand for portable electric evacuators with programmable pressure settings.
- Closed-loop sterilization mandates:Health Canada's PMRA biocompatibility documentation requirements for silicone formulations are driving premium material substitution in long-dwell orthopedic applications.
- Negative pressure wound therapy convergence:Hybrid systems integrating closed-suction drainage with NPWT protocols are expanding treatable wound categories in post-acute settings.
Market Restraints
- Silicone raw material concentration:Medical-grade silicone supply chains cluster in Northeast Asian petrochemical corridors, exposing manufacturers to input volatility and logistics disruption.
- Notified body capacity constraints:EU MDR implementation has thinned the pool of designated conformity assessment bodies, extending CE marking timelines for sustained negative pressure systems.
- Manual evacuator substitution ceiling:Cost-sensitive clinics in lower-tier markets retain preference for bulb-squeeze devices, capping electric system penetration in price-elastic segments.
Strategic Opportunities
- Home-based postoperative care:Discharge protocols in the United States are shortening hospital stays, creating demand for patient-managed portable suction with remote monitoring integration.
- Orthobiologic procedure bundling:Platelet-rich plasma and cell-based therapies require specialized low-shear evacuation, opening premium niches for biocompatible silicone systems.
- Single-use canister standardization:ISO 13485-aligned manufacturing platforms enable contract manufacturers to serve multiple OEM brands with interchangeable sterile collection components.
Industry Challenges
- Polymer engineering talent scarcity:Formulation chemists with medical-grade PVC and silicone co-extrusion expertise command premium compensation, constraining R&D throughput at mid-tier suppliers.
- Legacy pneumatic infrastructure integration:Hospital surgical suites with centralized vacuum wall systems resist electric evacuator adoption due to capital lock-in and staff retraining costs.
- Post-market surveillance data aggregation:EU MDR vigilance reporting requirements demand traceability systems that many disposable device manufacturers lack, forcing compliance infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Evacuators Market |
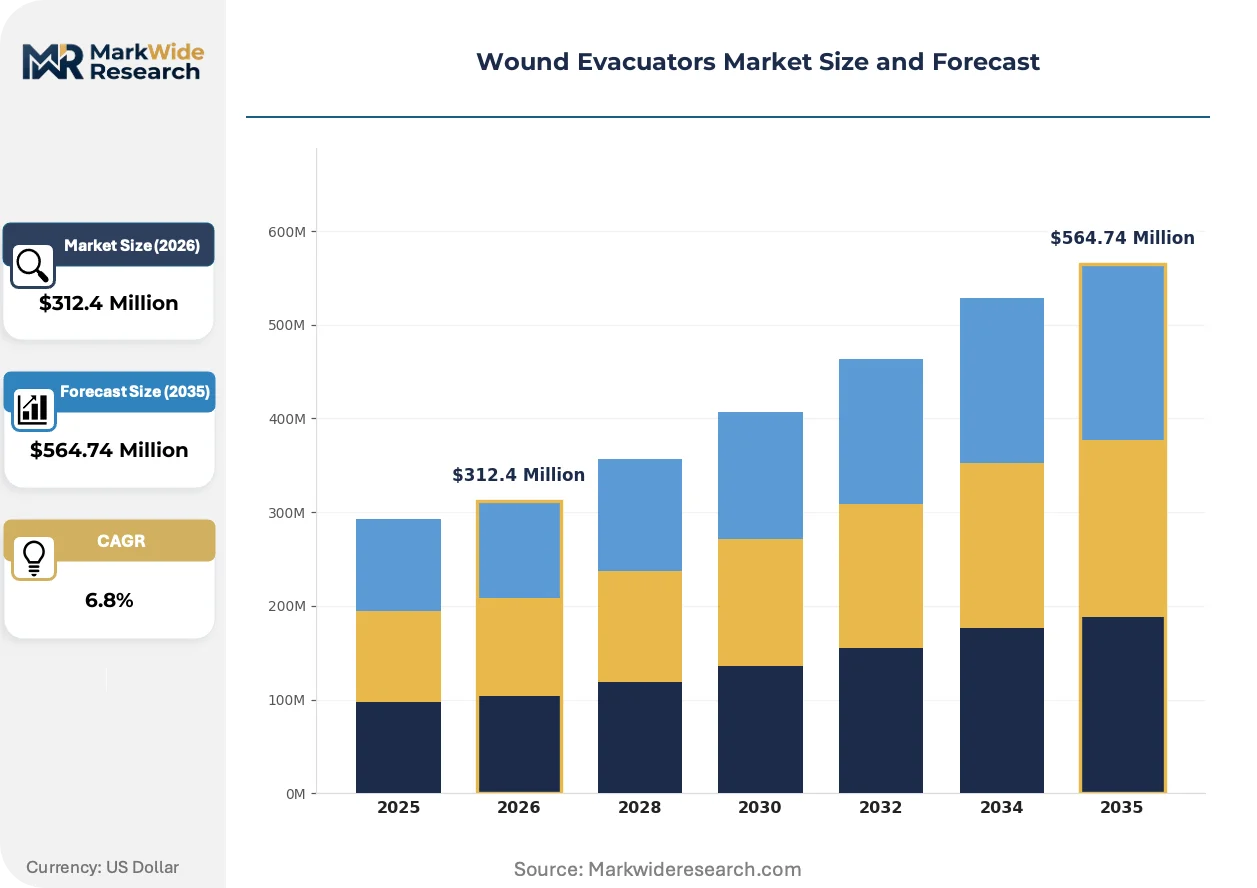
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic, Manual, Electric, Vacuum Application: Trauma Surgery, Orthopedic Surgery, General Surgery, Cosmetic Surgery End User: Hospitals, Ambulatory Surgical Centers, Clinics, Rehabilitation Centers Distribution Channel: Online, Offline, Direct Sales, Medical Supply Distributors |
| Companies Covered | Zimmer Biomet, Becton Dickinson and Company, Medline Industries, Aspen Surgical, Redax, Argon Medical Devices, Plasti-med Medikal Ürünler San. Tic. Ltd., Baxter International, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Evacuators Market Evolving Landscape
Connected suction systems with embedded pressure sensors and wireless telemetry are redefining perioperative monitoring. Device intelligence is shifting from passive drainage to active wound-state interpretation, altering how surgical teams manage postoperative fluid dynamics.
Antimicrobial-impregnated silicone drain materials are expanding into high-infection-risk procedures including colorectal and bariatric surgery. Academic medical centers in the United States are piloting these formulations for patients with compromised immune status. The technology is expanding into prophylactic applications previously served by standard silicone, compressing the addressable market for uncoated alternatives.
EU MDR Article 10 clinical evaluation requirements are forcing systematic literature reviews and PMCF studies for sustained negative pressure devices. Manufacturers must now generate procedure-specific evidence where predicate equivalence previously sufficed. German orthopedic implant suppliers are responding by embedding evacuator data collection within existing joint replacement registries.
Hospital value analysis committees are consolidating suction device purchasing across service lines, displacing surgeon-specific preference cards. Integrated delivery networks in the United States are mandating standardized canister sizes and tubing connectors to reduce SKU complexity. This concentration is most visible in multi-hospital systems where procurement centralization has eliminated redundant supplier relationships.
Wound Evacuators Market Segmentation
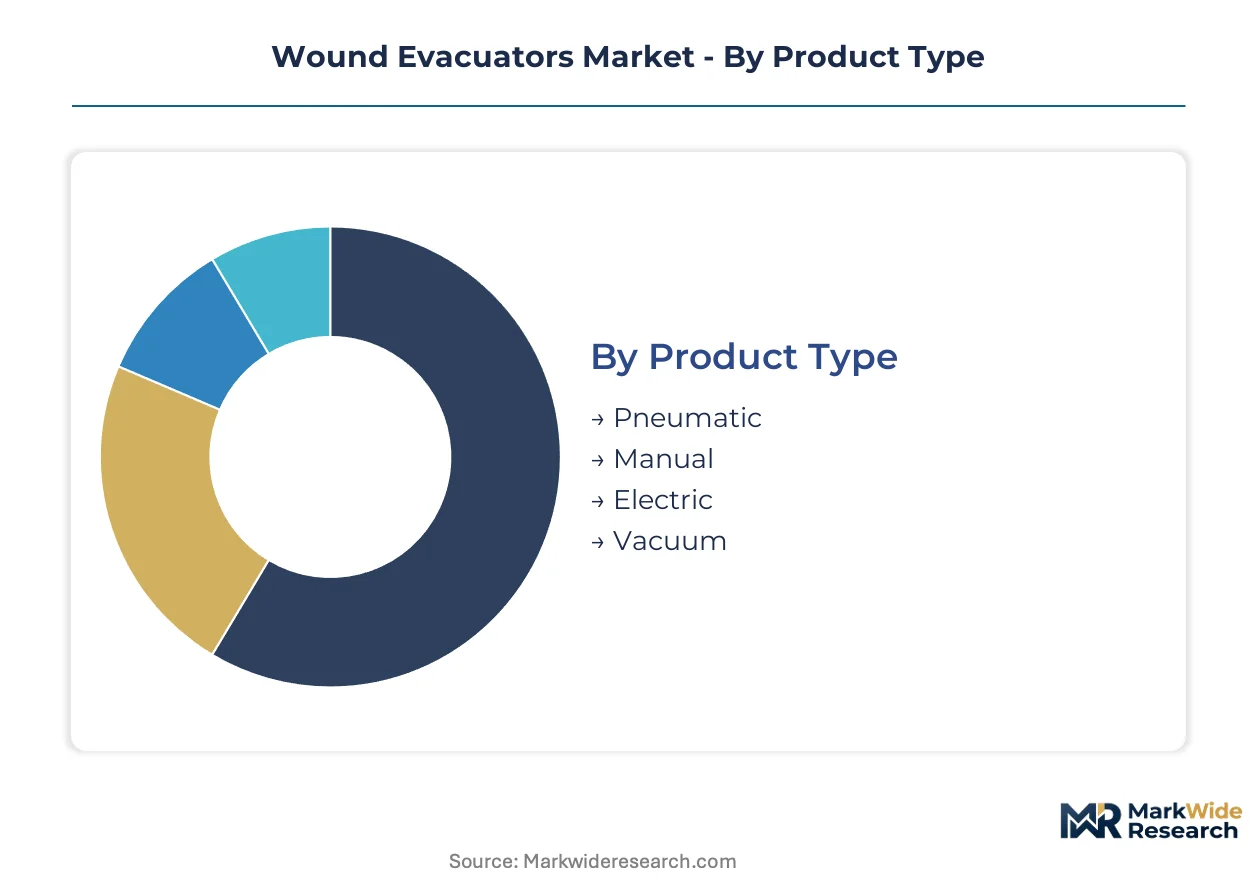
Wound evacuator procurement decisions cascade differently across surgical settings. Product specifications, procedure volumes, and reimbursement frameworks create distinct demand profiles that manufacturers must address through targeted portfolio architecture.
Product Type:
Hospital capital budgets and surgical throughput determine system selection, with reliability thresholds varying by procedure complexity.
- Pneumatic:These systems draw from centralized wall vacuum infrastructure, delivering consistent negative pressure at 80-120 mmHg for high-volume surgical suites. Demand concentrates in German hospital networks where orthopedic joint replacement volumes are expanding fastest, driven by reliability requirements in extended dwell-time procedures.
- Electric:Portable units with programmable pressure settings and battery backup address ambulatory surgical center requirements. German outpatient facilities are accelerating procurement as same-day joint replacement protocols gain reimbursement traction, though nursing staff training costs slow adoption in established hospitals.
- Manual:Bulb-squeeze and piston devices serve cost-sensitive clinics where intermittent suction suffices for minor procedures.
- Vacuum:Self-contained canister systems with integrated suction generation target home-based postoperative care and rural settings lacking infrastructure.
Pneumatic systems lead on scale; electric systems lead on momentum.
Application:
Procedure-specific fluid dynamics and dwell-time requirements shape material selection and pressure specification.
- Orthopedic Surgery:Long drain dwell times following joint replacement and spine fusion generate the strongest consumable turnover. German implant suppliers are bundling suction systems with procedure kits, locking in recurring revenue through integrated delivery network contracts.
- General Surgery:Abdominal and thoracic procedures require rapid exudate removal to prevent hematoma formation. Hospitals are standardizing canister sizes across service lines to reduce procurement complexity.
- Trauma Surgery:Emergency departments prioritize rapid-deployment pneumatic systems with universal tubing connectors.
- Cosmetic Surgery:Aesthetic procedures favor compact electric units with reduced noise profiles for outpatient clinic environments.
Orthopedic surgery dominates revenue concentration; general surgery offers the broadest installed base expansion potential.
End User:
Care setting determines regulatory compliance burden and service intensity requirements.
- Hospitals:Acute care networks with centralized sterile processing departments favor reusable components and pneumatic infrastructure. FDA 510(k) and EU MDR compliance documentation requirements concentrate purchasing authority in value analysis committees.
- Ambulatory Surgical Centers:Freestanding outpatient facilities in Germany and the United States are driving portable electric system demand as discharge protocols shorten. Remote monitoring integration is emerging as a selection criterion for patient-managed postoperative suction.
- Clinics:Cost-sensitive private practices retain preference for manual evacuators where procedure volumes do not justify capital investment.
- Rehabilitation Centers:Post-acute settings with wound care specialization are adopting hybrid closed-suction drainage systems for complex wound management.
Hospitals anchor volume commitments; ambulatory surgical centers are climbing the fastest.
Distribution Channel:
Supply chain configuration determines margin capture and customer relationship depth.
- Direct Sales:Manufacturer field representatives secure multi-year contracts with integrated delivery networks, embedding technical service and training. Health Canada PMRA biocompatibility documentation requirements favor direct relationships for silicone-intensive orthopedic applications.
- Medical Supply Distributors:Regional distributors with sterile logistics capabilities serve mid-tier hospitals and independent surgical centers, consolidating procurement across disposable categories.
- Online:E-procurement platforms are gaining traction for standardized consumables and replacement components in cost-constrained settings.
- Offline:Traditional brick-and-mortar medical supply stores retain relevance in rural markets and for emergency replenishment.
Direct sales commands the premium tier; medical supply distributors enable broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer engineers and sterilization validation specialists cluster in Germany, the United States, and Japan, anchoring wound evacuator manufacturing and regulatory compliance capabilities. These talent concentrations determine where sustained negative pressure device innovation and CE marking expertise concentrate.
Germany
Outpatient joint replacement volumes in Bavaria and North Rhine-Westphalia are accelerating demand for portable electric evacuators with programmable pressure settings. The EU MDR notified body bottleneck extends CE marking timelines for Class IIa sustained negative pressure systems. The Tübingen-Stuttgart corridor hosts orthopedic implant suppliers bundling suction systems with procedure kits.
United States
Health system value analysis committees in the Midwest and Southeast are consolidating suction device purchasing across service lines. The FDA 510(k) pathway governs Class II premarket notification for closed-suction drainage devices. The Minneapolis-St. Paul medical device cluster anchors pneumatic system manufacturing for high-volume surgical suites.
Japan
Aging demographics and spine fusion procedure growth in the Kanto region sustain demand for long-dwell silicone drain systems. The PMDA aligns risk classifications with FDA frameworks but demands additional biocompatibility documentation. The Osaka-Kobe industrial corridor concentrates medical-grade silicone formulation expertise for orthopedic applications.
United Kingdom
NHS procurement centralization in England is standardizing canister sizes and tubing connectors to reduce SKU complexity. The MHRA post-Brexit regulatory framework maintains EU MDR technical standards with UKCA marking requirements. The Cambridge-Oxford-London triangle hosts connected device startups integrating pressure sensors with wireless telemetry.
China
Domestic orthopedic procedure growth in the Yangtze River Delta is absorbing local manual evacuator production. The NMPA Class II medical device registration pathway requires clinical trials for sustained negative pressure systems. The Suzhou-Wuxi medical device manufacturing hub supplies contract sterilization services for export-oriented OEMs.
Wound Evacuators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Large medical technology holding companies leverage hospital contracting relationships and cross-selling infrastructure to anchor premium positions. Mid-tier contract manufacturers exploit ISO 13485-aligned platforms to serve multiple OEM brands with interchangeable sterile components. Regional specialists dominate cost-sensitive segments through localized distribution and simplified regulatory pathways. M&A activity concentrates among mid-cap sterilization service providers, while portfolio diversification drives incumbent expansion into connected monitoring capabilities.
Among diversified conglomerates, Zimmer Biomet and Medtronic exemplify the integrated delivery network contracting archetype, anchoring multi-year supply agreements through technical service bundling. Becton Dickinson and Company occupies a position within the closed-loop manufacturing tier, representing sterile disposable production scale. These three entities collectively illustrate how regulatory compliance depth and hospital relationship intensity separate sustainable market positions from transactional supplier roles.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Becton Dickinson and Company |
| Medline Industries |
| Aspen Surgical |
| Redax |
| Argon Medical Devices |
| Plasti-med Medikal Ürünler San. Tic. Ltd. |
| Baxter International |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone feedstock from Northeast Asian petrochemical corridors flows through three distinct pricing tiers before reaching hospital value analysis committees. Procurement consolidation across German integrated delivery networks compresses margins on standard pneumatic systems while amplifying premium capture for antimicrobial-impregnated formulations.
Pricing Analysis
Bundled procedure kits command premium positioning against unbundled component sales. Pricing stratifies across premium, standard, and economy tiers based on ISO 13485 certification grade and after-sales technical service intensity. Cost compression in economy manual evacuators intensifies because Health Canada PMRA biocompatibility documentation requirements push mid-tier buyers toward certified alternatives. Ambulatory surgical centers exhibit highest price sensitivity; orthopedic implant suppliers bundling suction systems with joint replacement kits show lowest.
Supply Chain Analysis
Reverse-logistics flows for reusable pneumatic components and refurbishment of electric system batteries create secondary supply channels alongside primary manufacturing. Component sourcing concentrates in Germany, the United States, and Japan for specialized polymer engineering. Medical-grade silicone, PVC co-extrusion materials, and sterilization packaging constitute critical input dependencies. Single-source vulnerability in Northeast Asian silicone supply exposes manufacturers to logistics disruption. Distribution runs through direct sales for premium tier hospital contracts and regional medical supply distributors for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through antimicrobial material substitution and connected monitoring capability bundling. Orthopedic procedure kit integration and remote patient monitoring software represent the premium-tier shift.
For Market Incumbents: Lock in multi-year integrated delivery network contracts before EU MDR recertification timelines extend for competitors. Deepen backward integration into medical-grade silicone formulation to offset raw material volatility. Channel control through embedded biomedical engineering technical service teams counters emerging pure-play electric system specialists. For New Entrants and Emerging Players: Launch via e-procurement platforms targeting cost-constrained rehabilitation centers and rural clinics outside German hospital network consolidation. Home-based postoperative care with patient-managed portable suction represents the most penetrable white space. Remote monitoring integration capability offers differentiated go-to-market positioning against legacy pneumatic incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance infrastructure investments exceed mid-tier revenue bases. Long-term viability favors sterilization validation specialists with ISO 13485-aligned manufacturing platforms serving multiple OEM brands. The signal to watch is notified body capacity expansion announcements indicating CE marking timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 clinical evidence requirements reshape competitive entry calculus for sustained negative pressure systems. |
| Hospital System Partnership | Integrated delivery network contracting locks in recurring revenue through technical service bundling across multi-facility footprints. |
| Software Companion Development | Connected suction systems with wireless telemetry shift perioperative monitoring from passive drainage to active wound-state interpretation. |
| Backward Integration | In-house production of antimicrobial-impregnated silicone formulations captures margin pools in high-infection-risk orthopedic applications. |
| Reimbursement Strategy | Same-day joint replacement protocol coverage in German outpatient facilities accelerates portable electric evacuator procurement cycles. |
Research Methodology
Bottom-up surgical procedure volume modeling reconciled against top-down medical device manufacturing output tracking forms the analytical core. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and orthopedic implant supplier executives combine with secondary validation from FDA 510(k) filings, EU MDR notified body databases, hospital procurement contract registries, and CMS Medicare reimbursement schedules.
Historical trendline analysis of pneumatic, electric, and manual system procurement patterns across German, United States, and Japanese acute care networks establishes baseline trajectory assumptions. Segmentation dimensions span product type, application procedure category, end-user facility class, and regional regulatory cluster. CAGRs derive from procedure volume elasticity modeling and average selling price trajectory analysis, with negative pressure wound therapy convergence rates and ambulatory surgical center expansion velocity as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body capacity constraints and medical-grade silicone supply disruption scenarios. Practitioners should monitor EU MDR designation expansion announcements and German outpatient joint replacement reimbursement policy adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Wound Healing Nutrition Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
US Burn Care Centers Market
Wound Care
Wound Contact Layer Dressing Market
Wound Care
Wound Closure Strips Market
Wound Care
Philippines Wound Care Market
Wound Care
Advanced Wound Management Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Negative Pressure Wound Therapy Market
Wound Care
Wound Skin Care Market
Wound Care
Infectious Wound Care Management Market
Wound Care
Global Active Wound Care Market
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
Vascular Dressings Market
Wound Care
South Korea Wound Care Management Market