
 Antimicrobial Wound Dressings Market | 2026-2036
Antimicrobial Wound Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Antimicrobial Wound Dressings Market Analysis
Advanced silver-ion specification tiers is reorganizing procurement priorities across acute and post-acute care channels. Smith & Nephew leverages vertically integrated manufacturing of antimicrobial substrates to sustain consistent supply to NHS trusts and US hospital networks. Mölnlycke Health Care anchors Nordic quality benchmarks while competing aggressively in German outpatient wound clinics through specialized hydrocolloid lines. Coloplast differentiates via urology-to-wound care crossover expertise, occupying strong positions in European long-term care facilities.
Antimicrobial wound dressings comprise medical-grade substrates impregnated with biocidal agents such as silver, iodine, or polyhexamethylene biguanide, engineered to maintain moist wound environments while suppressing bacterial colonization at concentrations typically ranging from 0.5% to 1.5% active loading. Foam dressings with sustained silver release dominate margin pools in surgical wound applications where exudate management and infection prevention converge. Chronic wound indications across home healthcare channels represent the fastest-growing application segment as payer pressure shifts debridement and dressing changes away from institutional settings.
FDA 510(k) clearance pathways for antimicrobial devices require robust clinical microbiology data, while EMA MDR transition demands strengthened biocompatibility documentation for silver-containing implants. Health Canada and TGA have aligned post-market surveillance expectations with ISO 10993 cytotoxicity standards, creating compliance complexity for multi-territory suppliers. Stakeholders must monitor evolving EPA and REACH environmental assessments for silver discharge, as sustainability criteria increasingly filter into hospital purchasing committee evaluations alongside clinical performance metrics.
Market Dynamics
Silver-ion release kinetics specification tiers are reorganizing procurement priorities across acute and post-acute care channels, forcing manufacturers to demonstrate sustained antimicrobial efficacy over 7-day wear periods rather than 24-hour benchmarks.
Growth Catalysts
- MDR Transition Deadlines:EMA's strengthened biocompatibility documentation requirements for silver-containing implants are accelerating hospital system consolidation around pre-qualified suppliers with established ISO 10993 testing protocols.
- Diabetic Foot Ulcer Prevalence:Aging populations in Germany, Japan, and the United States are expanding addressable patient pools for chronic wound management protocols that mandate antimicrobial substrate integration.
- Hydrofiber Substrate Engineering:Advanced gelling fiber technologies that lock exudate away from wound beds are displacing traditional gauze in surgical closure applications across NHS trusts and US hospital networks.
Market Restraints
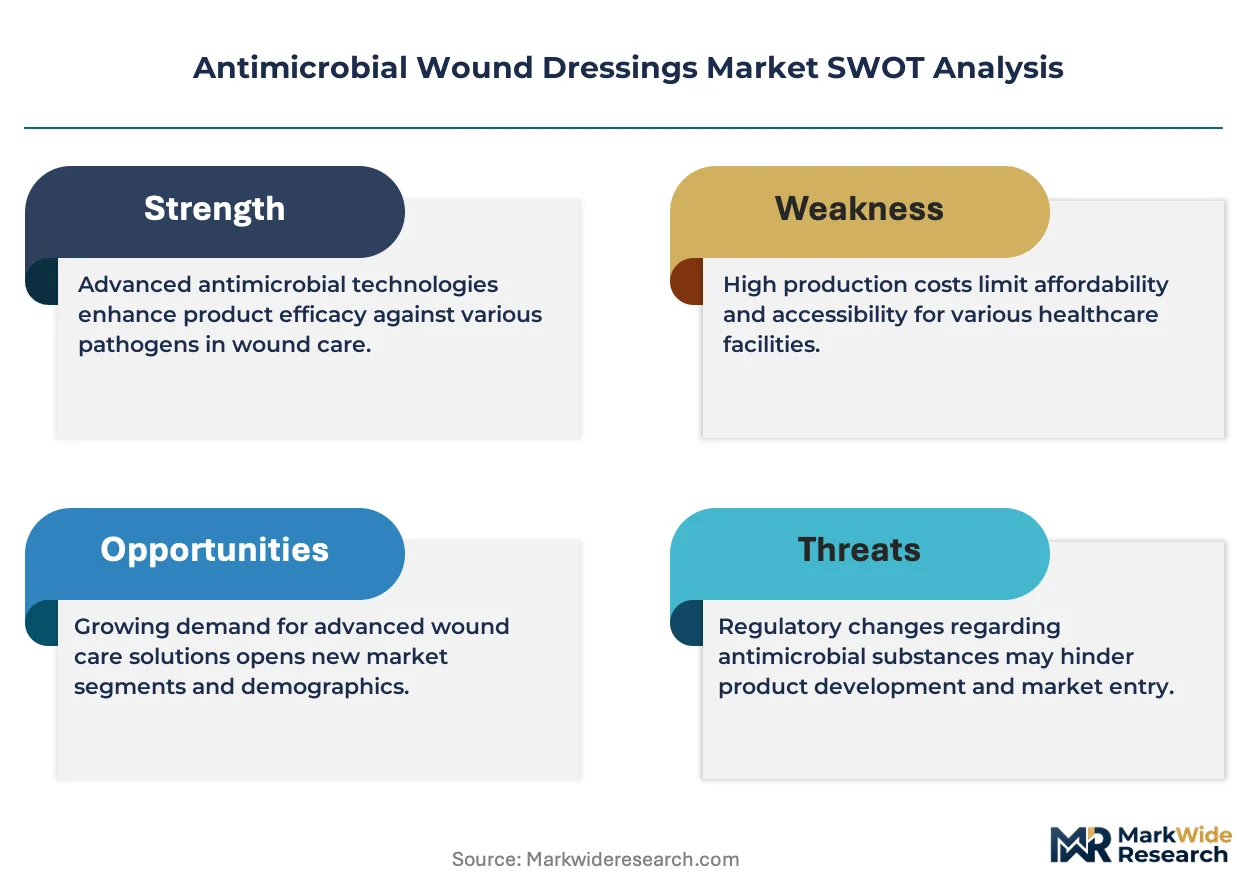
- Silver Price Volatility:Precious metal commodity fluctuations compress margin predictability for ionic silver loading at 0.5% to 1.5% active concentrations.
- Supply Concentration Risk:NHS trust and US hospital network procurement dependencies on vertically integrated substrate manufacturers create vulnerability to single-source disruptions.
- EPA Environmental Assessments:Post-market surveillance alignment with evolving discharge standards for silver-laden effluent imposes compliance cost layers on multi-territory suppliers.
Strategic Opportunities
- Home Healthcare Channel Expansion:Payer pressure shifting debridement and dressing changes away from institutional settings creates white space for extended-wear antimicrobial foam products.
- REACH Compliance Differentiation:Environmental sustainability criteria filtering into hospital purchasing committee evaluations rewards suppliers with documented low-discharge silver formulations.
- Iodine-Polymer Convergence:Cadexomer iodine matrix technologies paired with sustained-release hydrogels address methicillin-resistant Staphylococcus aureus colonization in outpatient wound clinics.
Industry Challenges
- Clinical Microbiology Talent Scarcity:FDA 510(k) clearance pathways demand robust bioburden reduction data that requires specialized microbiology laboratory capacity.
- Legacy System Integration Friction:Electronic health record compatibility for antimicrobial dressing change tracking protocols complicates hospital system adoption workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimicrobial Wound Dressings Market |
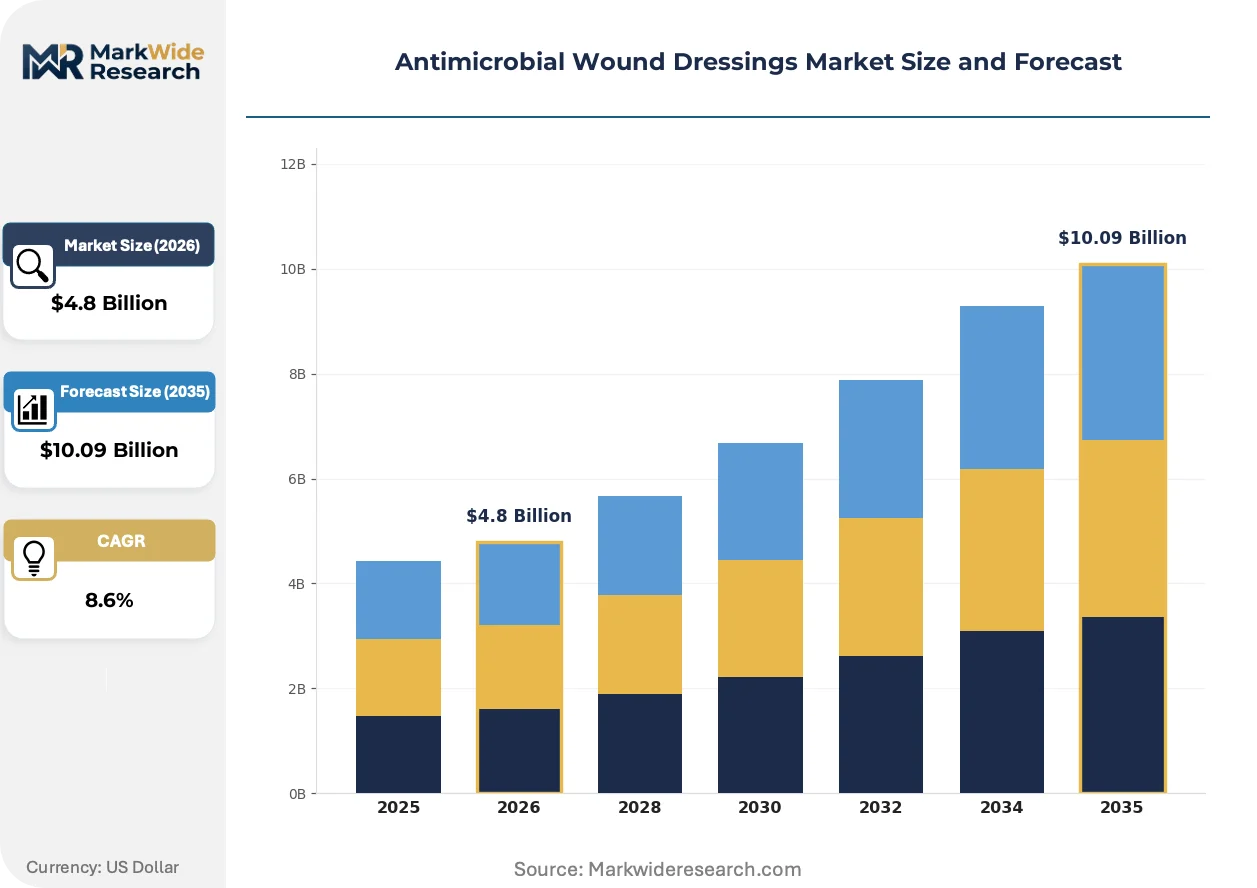
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Dressings, Hydrocolloid Dressings, Alginate Dressings, Film Dressings End User: Hospitals, Clinics, Home Healthcare, Long-term Care Facilities Delivery Mode: Topical, Continuous, Localized, Systemic Application: Chronic Wounds, Surgical Wounds, Burn Wounds, Traumatic Wounds |
| Companies Covered | Smith & Nephew, 3M, ConvaTec, Mölnlycke Health Care, Coloplast, B. Braun, Cardinal Health, Medline Industries, McKesson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimicrobial Wound Dressings Market Emerging Trajectories
Active loading precision and release profile engineering are compressing the gap between prophylactic and therapeutic antimicrobial claims, forcing substrate manufacturers to invest in real-time ion concentration monitoring capabilities.
Electrospun nanofiber matrices with embedded silver nanoparticles deliver tunable pore sizes for exudate management while maintaining moist wound environments. Outpatient wound clinics in Germany and post-acute facilities in Japan are adopting these substrates for partial-thickness burn protocols. The technology is miniaturizing delivery systems from hospital-grade rolls to pre-cut shapes that integrate with negative pressure wound therapy devices.
REACH environmental assessments for silver discharge are tightening substantiation requirements for clinical efficacy claims alongside sustainability criteria. Multi-territory suppliers face compliance complexity as Health Canada and TGA align post-market surveillance expectations with ISO 10993 cytotoxicity standards. European long-term care facilities are prioritizing dressing suppliers with documented biodegradability pathways for used product streams.
Hospital purchasing committees are unbundling dressing procurement from wound care service contracts, creating direct price transparency between substrate manufacturers and acute care buyers. This disintermediation concentrates volume with suppliers capable of just-in-time delivery to centralized sterile processing departments. The United States exhibits the most visible shift, with integrated delivery networks negotiating multi-year antimicrobial dressing agreements independent of distributor markups.
Antimicrobial Wound Dressings Market Segmentation
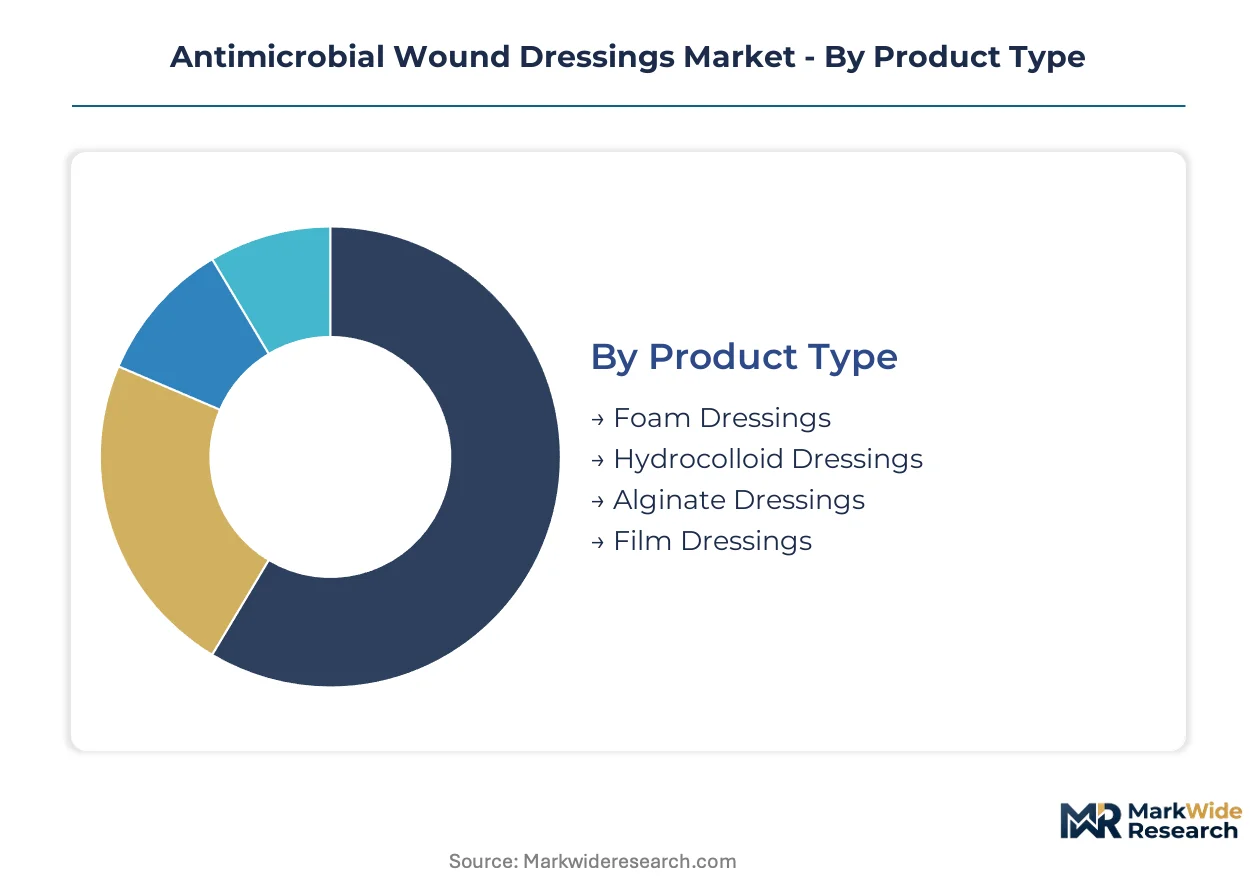
Antimicrobial wound dressing procurement decisions fragment across clinical setting, wound etiology, and delivery mechanism. Manufacturers must align substrate specifications with distinct efficacy benchmarks and reimbursement pathways governing each segment cluster.
Product Type:
Foam and hydrocolloid substrates face intensifying substitution pressure from advanced gelling fiber technologies that lock exudate away from wound beds.
- Foam Dressings:Polyurethane substrates impregnated with ionic silver deliver sustained antimicrobial release over 7-day wear periods. Demand concentrates in US hospital surgical wards where exudate management and infection prevention converge under bundled payment protocols.
- Hydrocolloid Dressings:Gel-forming carboxymethylcellulose matrices with iodine or PHMB loading maintain moist healing environments for partial-thickness wounds. German outpatient wound clinics favor these for diabetic foot ulcer protocols where patient mobility between visits matters.
- Alginate Dressings:Calcium-sodium seaweed-derived fibers with silver ion integration absorb heavy exudate in cavity wounds.
- Film Dressings:Semi-permeable polyurethane membranes with antimicrobial surface coatings protect superficial wounds with minimal exudate.
Foam dressings anchor the volume base while alginate formulations gain share at the steepest rate in home healthcare channels.
End User:
Cost tier stratification separates acute institutional buyers with centralized sterile processing from decentralized home healthcare purchasers prioritizing ease of application.
- Hospitals:Integrated delivery networks negotiate multi-year antimicrobial dressing agreements independent of distributor markups, concentrating volume with suppliers capable of just-in-time delivery to centralized sterile processing departments in the United States.
- Home Healthcare:Extended-wear antimicrobial foam products address payer pressure shifting debridement and dressing changes away from institutional settings, with NHS trusts in the United Kingdom piloting remote monitoring integration.
- Clinics:Outpatient wound centers require rapid antimicrobial action for debrided chronic wounds with high bioburden.
- Long-term Care Facilities:European facilities prioritize dressing suppliers with documented biodegradability pathways for used product streams under tightening environmental assessments.
Hospitals dominate absolute procurement value while home healthcare expands most quickly as reimbursement shifts toward site-neutral payment models.
Delivery Mode:
Application precision requirements vary sharply between prophylactic surface coverage and targeted antimicrobial intervention in colonized wounds.
- Topical:Direct substrate-to-wound contact remains the standard of care across all settings, with silver-ion concentration specifications tightening under FDA 510(k) microbiology data requirements.
- Localized:Antimicrobial-impregnated beads and pastes address deep cavity wounds and sinus tracts where standard dressings conform poorly.
- Continuous:Sustained-release formulations integrated with negative pressure wound therapy devices deliver antimicrobial action over extended intervals.
- Systemic:Adjunctive topical antimicrobial protocols complement intravenous antibiotic regimens in severely infected wounds.
Topical delivery anchors clinical practice while localized modalities climb fastest in post-acute surgical wound management.
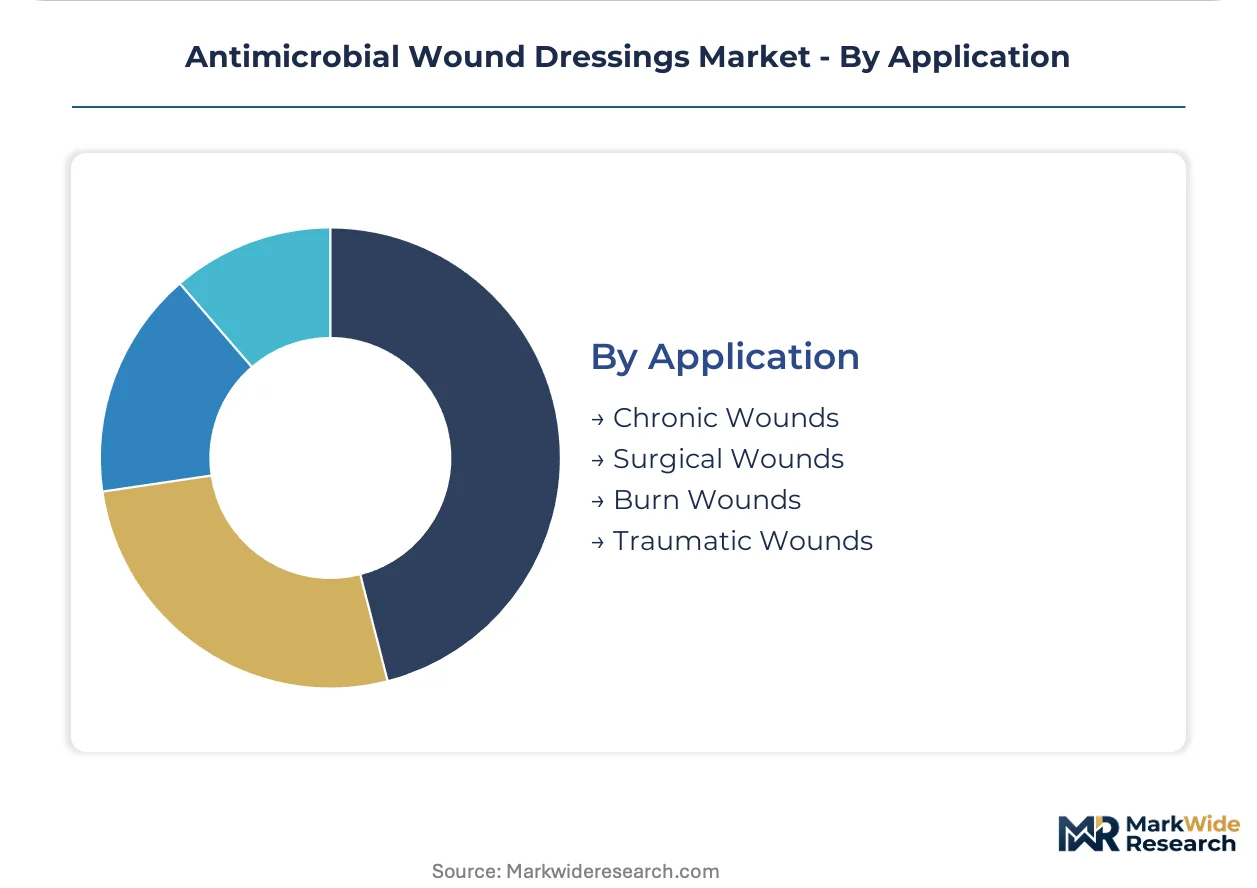
Application:
Wound etiology determines antimicrobial loading thresholds, with chronic colonized wounds demanding higher active concentrations than prophylactic surgical coverage.
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries with persistent bioburden drive demand for silver and iodine matrices in Germany, Japan, and the United States where aging populations expand addressable patient pools.
- Surgical Wounds:Incisional site prophylaxis with antimicrobial foam dominates margin pools where exudate management and infection prevention converge in acute care settings.
- Burn Wounds:Partial-thickness thermal injuries require antimicrobial substrates that maintain moist environments while permitting drainage of heavy exudate.
- Traumatic Wounds:Acute injuries with contamination risk utilize antimicrobial dressings as interim coverage before definitive closure.
Chronic wound applications command the steepest expansion trajectory as prevalence rises and care shifts toward outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in antimicrobial wound dressings favor net-importing health systems with aging demographics. Germany and Japan run structural trade deficits in advanced silver-ion substrates. The United States balances domestic manufacturing capacity against specialized alginate imports from Nordic suppliers.
United States
Integrated delivery networks consolidate procurement through multi-year antimicrobial dressing agreements independent of distributor markups. FDA 510(k) clearance pathways demand robust clinical microbiology data for silver-containing devices. Boston and Minneapolis medical device clusters anchor substrate engineering capabilities serving hospital networks nationwide.
Germany
Outpatient wound clinics in Bavaria and North Rhine-Westphalia drive hydrocolloid demand for diabetic foot ulcer protocols. EMA MDR transition deadlines accelerate hospital system consolidation around pre-qualified suppliers with ISO 10993 testing protocols. The Tübingen-Stuttgart medical technology corridor hosts specialized dressing manufacturers competing on REACH-compliant low-discharge formulations.
Japan
PMDA post-market surveillance alignment with cytotoxicity standards creates compliance complexity for foreign suppliers entering the market. METI reimbursement policies favor extended-wear antimicrobial foam products reducing hospitalization days. The Kansai region around Osaka concentrates domestic manufacturing of iodine-polymer matrix technologies.
United Kingdom
NHS trusts pilot remote monitoring integration for home healthcare channels shifting debridement away from institutional settings. MHRA regulatory pathways mirror EMA biocompatibility documentation requirements under post-Brexit alignment mechanisms. Yorkshire and Greater Manchester manufacturing bases supply foam dressings to centralized sterile processing departments.
Australia
TGA post-market surveillance expectations align with ISO 10993 standards, filtering multi-territory supplier entry. State health procurement frameworks in New South Wales and Victoria prioritize suppliers with documented biodegradability pathways. Sydney and Melbourne medical research institutes conduct clinical validation studies for sustained-release silver formulations.
Antimicrobial Wound Dressings Market Vendor Landscape
Concentration sits with diversified medical device conglomerates commanding hospital network procurement relationships. Three to five manufacturers capture disproportionate volume through vertically integrated substrate production and established regulatory dossiers. Strategic archetypes separate integrated wound care specialists, diversified hygiene-to-medical converters, and distribution-heavy health service conglomerates. Competitive moves center on M&A for substrate technology access and capacity expansion in silver-ion loading facilities.
Among UK-listed wound care specialists, Smith & Nephew exemplifies the integrated substrate-to-distribution archetype with NHS trust penetration. Mölnlycke Health Care represents Nordic quality-benchmark positioning competing in German outpatient channels. Coloplast occupies a crossover position leveraging urology-to-wound care expertise in European long-term care facilities.
| Leading Market Players |
|---|
| Smith & Nephew |
| 3M |
| ConvaTec |
| Mölnlycke Health Care |
| Coloplast |
| B. Braun |
| Cardinal Health |
| Medline Industries |
| McKesson Corporation |
| Others |
Supply Flow & Price Mechanics
Hydrofiber substrate substitution for traditional gauze and foam is redrawing procurement geography while compressing margin structures across acute and post-acute channels. NHS trusts and US hospital networks now source advanced gelling fibers from specialized manufacturers in Sweden and the United Kingdom, forcing legacy foam suppliers to absorb silver-ion loading cost volatility or surrender volume to integrated substrate producers.
Pricing Analysis
Integrated delivery network buyers anchor contract-based long-term offtake structures that lock in multi-year antimicrobial dressing agreements independent of distributor markups. Price differentiation separates ISO 10993-certified suppliers with documented biocompatibility dossiers from uncertified competitors, while volume scale and just-in-time delivery capability to centralized sterile processing departments command premium positioning. Cost compression in standard-tier foam dressings is intensifying because precious metal commodity fluctuations compress margin predictability for ionic silver loading. Home healthcare purchasers exhibit highest price sensitivity due to site-neutral reimbursement pressure, whereas surgical ward procurement committees prioritize sustained-release efficacy over unit cost.
Supply Chain Analysis
Container availability constraints on trans-Atlantic trade lanes from Nordic ports to US East Coast distribution hubs are extending lead times for alginate and hydrofiber raw material shipments. Manufacturing concentration clusters in Sweden, the United Kingdom, and Germany supply advanced silver-ion substrates, while calcium-sodium seaweed-derived alginate fibers draw from captive Nordic harvesting operations. Single-source vulnerability pervades vertically integrated substrate manufacturers serving NHS trust and US hospital network procurement dependencies. Distribution runs through health service conglomerates and specialized medical device distributors to hospital sterile processing departments and home healthcare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimicrobial wound dressing procurement is evolving into a service-attach opportunity where remote monitoring integration and dressing change protocol consulting expand recurring revenue faster than substrate hardware sales. Hospital systems increasingly unbundle clinical service contracts from product supply, creating whitespace for suppliers capturing ongoing patient outcome data streams.
For Market Incumbents: Shield market position by deepening backward integration into electrospun nanofiber manufacturing capabilities and securing ISO 10993 testing capacity ahead of EMA MDR transition deadlines. Cadexomer iodine matrix technologies from emerging Nordic specialists threaten silver-ion dominance in outpatient wound clinics, necessitating defensive patent portfolio expansion around sustained-release hydrogel formulations. For New Entrants and Emerging Players: Lead with REACH-compliant low-discharge silver formulations that satisfy European long-term care facility biodegradability requirements, penetrating the white space left by legacy suppliers lacking environmental documentation. Home healthcare channels shifting debridement away from institutional settings represent the most penetrable segment, accessible through direct-to-patient digital platforms paired with remote monitoring integration. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors substrate technology specialists with established regulatory dossiers and NHS trust penetration. Five-to-ten year viability hinges on suppliers capturing extended-wear antimicrobial foam volume as payer pressure accelerates site-neutral reimbursement. Watch for EPA environmental assessment rulings on silver-laden effluent discharge as the inflection signal determining which formulation technologies achieve sustainable procurement preference.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Testing Protocol Investment | EMA MDR transition deadlines accelerate hospital consolidation around pre-qualified biocompatibility dossiers. |
| REACH-Compliant Formulation Development | European long-term care facilities prioritize suppliers with documented low-discharge silver biodegradability pathways. |
| Home Healthcare Channel Partnership | NHS trusts pilot remote monitoring integration for site-neutral reimbursement models shifting care away from hospitals. |
| Electrospun Nanofiber Capacity Expansion | German outpatient wound clinics and Japanese post-acute facilities adopt tunable pore substrates for partial-thickness burns. |
| FDA 510(k) Clinical Microbiology Data Investment | Robust bioburden reduction studies secure clearance for silver-ion release kinetics claims over 7-day wear periods. |
Methodological Framework
The analysis maps foam, hydrocolloid, alginate, and film dressing sub-sectors, each validated through hospital purchasing committee interviews, biomedical engineer consultations, GPO contracts managers, and home healthcare procurement leads. Primary fieldwork combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, NHS trust procurement records, and hospital sterile processing department spend data. Bottom-up substrate volume estimates triangulated against top-down chronic wound prevalence models across the United States, Germany, and Japan.
Consistency checks validated volume and value outputs against external benchmarks including Medicare reimbursement rate trajectories, silver commodity price indices, and hospital supply chain disclosure filings. Segmentation dimensions modeled encompass product substrate type, wound etiology application, end-user setting, and delivery mechanism complexity across the projection horizon. CAGRs derived from patient population growth curves, procedure volume shifts, and technology substitution elasticities for iodine-polymer convergence against legacy silver formulations.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EMA regulatory alignment, silver price volatility containment, and REACH environmental assessment stability would require recalibration. Forecasts reflect documented assumptions regarding chronic wound prevalence trajectories, payer reimbursement policy continuity, and supply chain concentration persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Venous Skin Ulcer Treatment Market
Wound Care
Wound Care Biologics Market
Wound Care
North America Wound Care Management Market
Wound Care
Enzymatic Wound Debridement Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
South Korea Wound Care Market
Wound Care
Global Diabetic Foot Ulcers Market
Wound Care
Bioactive Wound Dressing Market
Wound Care
Animal Wound Care Market
Wound Care
South Korea Wound Care Management Market
Wound Care
Topical Wound Agents Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Single-Use Negative Pressure Wound Therapy Devices Market
Wound Care
Decubitus Ulcer Treatment Products Market
Wound Care
Next Generation Wound Closure Device Market