
 Intra-Amniotic Infection Treatment Market | 2026-2036
Intra-Amniotic Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Intra-Amniotic Infection Treatment Market Foresight
Supply base consolidation from single-source API reliance toward qualified multi-source procurement is shifting procurement dynamics across the intra-amniotic infection treatment landscape. Pfizer Inc. leverages its vertically integrated cephalosporin manufacturing network to secure cost positions in hospital formulary contracts. Cipla Limited anchors its competitive stance through backward integration into active pharmaceutical ingredient production for emerging market tenders. GlaxoSmithKline plc sustains brand loyalty among obstetricians through sustained clinical education programs targeting labor-and-delivery protocols.
Intra-amniotic infection treatment encompasses pharmacological and surgical interventions targeting microbial invasion of the amniotic cavity, typically involving broad-spectrum beta-lactam antibiotics administered intravenously with anaerobic coverage to prevent maternal sepsis and neonatal complications. The pharmacological therapy segment dominates current revenue pools due to standardized hospital protocols for chorioamnionitis, while the monitoring and assessment category captures expanding margin as continuous fetal heart rate surveillance and biomarker-based early detection systems displace reactive treatment paradigms. Hospitals command the largest end-user share by patient acuity and regulatory mandate, though outpatient surgery centers represent the fastest-growing site of care as same-day obstetric procedures expand.
The US FDA's pregnancy labeling system and antimicrobial stewardship requirements shape product development priorities and prescribing patterns for intra-amniotic infection therapies. EMA's pediatric investigation plans and REACH compliance obligations for excipient safety govern market access trajectories for European launches. Stakeholders must track evolving pharmacovigilance mandates across jurisdictions while calibrating R&D portfolios toward narrow-spectrum alternatives that satisfy intensified resistance-management scrutiny.
Market Dynamics
Antimicrobial stewardship mandates from the US FDA and EMA are compressing prescriber discretion and forcing formulary committees toward narrow-spectrum alternatives, fundamentally restructuring competitive positioning around resistance-management credentials rather than clinical efficacy alone.
Growth Catalysts
- Cesarean protocol standardization:Tertiary hospital maternity wards in the United States are mandating prophylactic antibiotic administration prior to incision, creating institutional demand pull for IV beta-lactam formulations with anaerobic coverage.
- EMA pediatric investigation plans:European regulatory requirements for neonatal safety data are accelerating clinical trial investment in perinatal antibiotic pharmacokinetics, expanding the addressable evidence base for obstetric indications.
- Biomarker-based detection systems:Continuous fetal heart rate surveillance combined with maternal inflammatory markers is unifying diagnostic and therapeutic workflows, reducing time-to-treatment in labor-and-delivery units.
Market Restraints
- API supply concentration:Cephalosporin active pharmaceutical ingredient production concentrates in Chinese and Indian chemical manufacturing clusters, exposing formulators to import tariff volatility and geopolitical disruption.
- REACH excipient compliance:European chemical safety obligations for intravenous formulation components are extending registration timelines and elevating toxicology study costs for market entrants.
- Narrow-spectrum substitution:Rising resistance surveillance data favors carbapenem-sparing regimens, threatening revenue durability for broad-spectrum antibiotic portfolios lacking microbiome-sparing claims.
Strategic Opportunities
- Outpatient surgery center expansion:Same-day obstetric procedures in ambulatory settings are creating demand for abbreviated antibiotic protocols with rapid infusion profiles and minimal monitoring requirements.
- US antimicrobial stewardship incentives:Hospital reimbursement adjustments tied to resistance-reduction metrics are creating procurement preference for agents with demonstrated microbiome preservation in neonatal populations.
- Real-time molecular diagnostics:Convergence of polymerase chain reaction platforms with electronic health record integration is enabling pathogen-directed therapy selection within two hours of amniocentesis.
Industry Challenges
- Neonatal pharmacokinetic expertise scarcity:Labor-and-delivery units lack specialized pharmacy staff capable of dosing adjustment for preterm populations, creating liability exposure and protocol deviation.
- Legacy electronic health record integration:Antibiotic decision-support modules require costly customization to interface with obstetric workflow software, delaying stewardship program deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intra-Amniotic Infection Treatment Market |
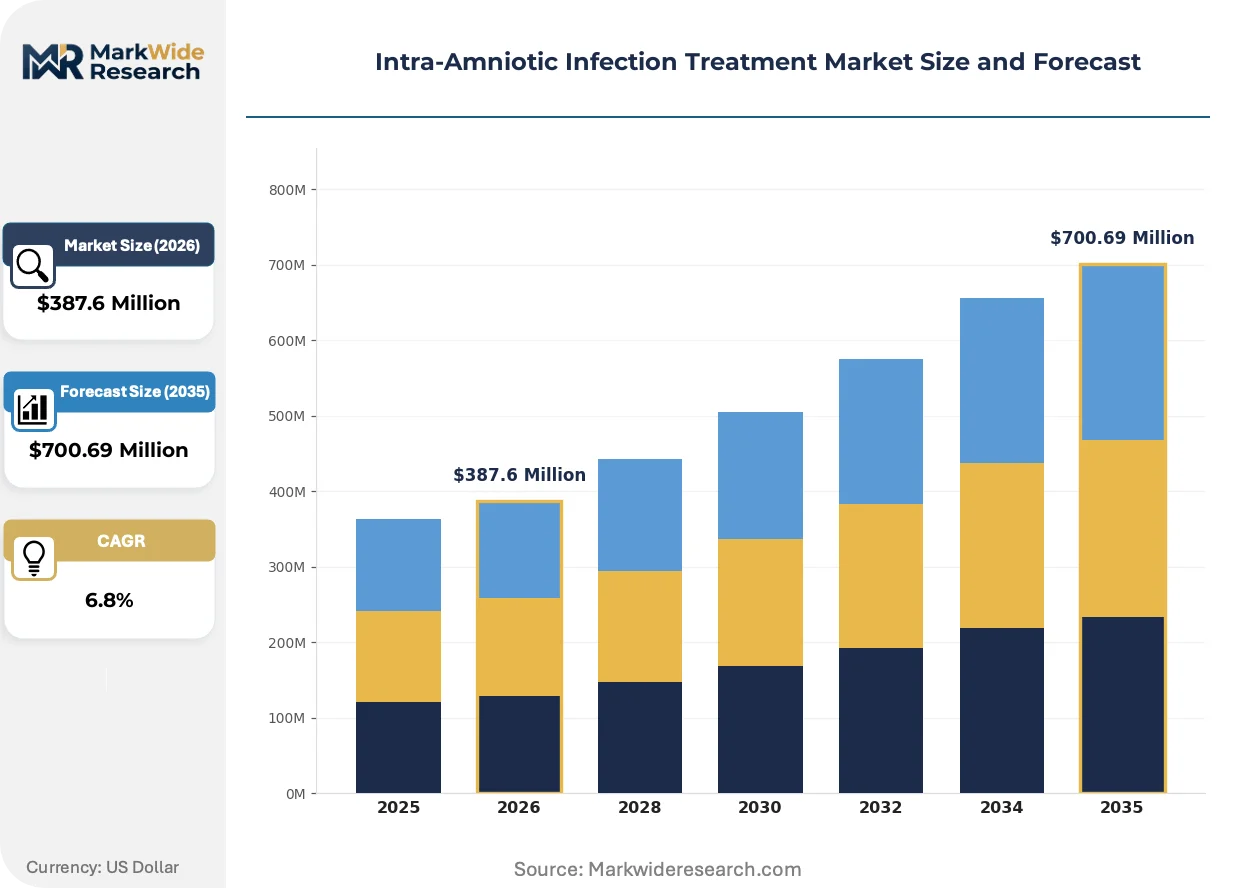
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antimicrobials, Anti-inflammatories, Supportive Care End User: Hospitals, Clinics, Outpatient Surgery Centers, Maternity Wards Application: Labor and Delivery, Preterm Birth, Infection Management, Surgical Procedures Treatment Approach: Pharmacological Therapy, Surgical Intervention, Monitoring and Assessment, Palliative Care |
| Companies Covered | Pfizer Inc., Cipla Limited, Zydus Cadila Healthcare Ltd, Aristopharma Ltd, Akums (Maxcure Drugs and Pharmaceuticals), ACS Dobfar S.p.A., Apotex Inc., GlaxoSmithKline plc, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intra-Amniotic Infection Treatment Market Shifts & Advancements
Perinatal care is converging on predictive rather than reactive infection management, with technology investments prioritizing early detection infrastructure and automated therapeutic decision support over conventional antimicrobial development.
Continuous biomarker monitoring platforms are unifying maternal vital signs, fetal heart rate variability, and inflammatory marker trajectories into single-dashboard surveillance systems. Tertiary hospital labor-and-delivery units in the United States are deploying these integrated platforms at accelerating rates. This convergence is compressing the diagnostic-to-treatment interval and displacing standalone fetal monitoring hardware.
REACH compliance obligations for excipient safety are extending toxicology study requirements for intravenous antibiotic formulations entering European markets. Formulators are reformulating buffer systems and stabilizing agents to satisfy ECHA substance-of-very-high-concern screening. Pediatric investigation plan mandates from EMA are most affecting neonatal indication expansions, with sponsors prioritizing pharmacokinetic studies in preterm cohorts.
Hospital procurement committees are consolidating antibiotic purchasing through centralized formulary contracts that bundle multiple infection indications. Group purchasing organizations are displacing individual hospital pharmacy negotiations in the United States, compressing price differentiation between originator and multi-source products. This concentration is most visible in tertiary academic medical centers with established obstetric intensive care infrastructure.
Intra-Amniotic Infection Treatment Market Segmentation
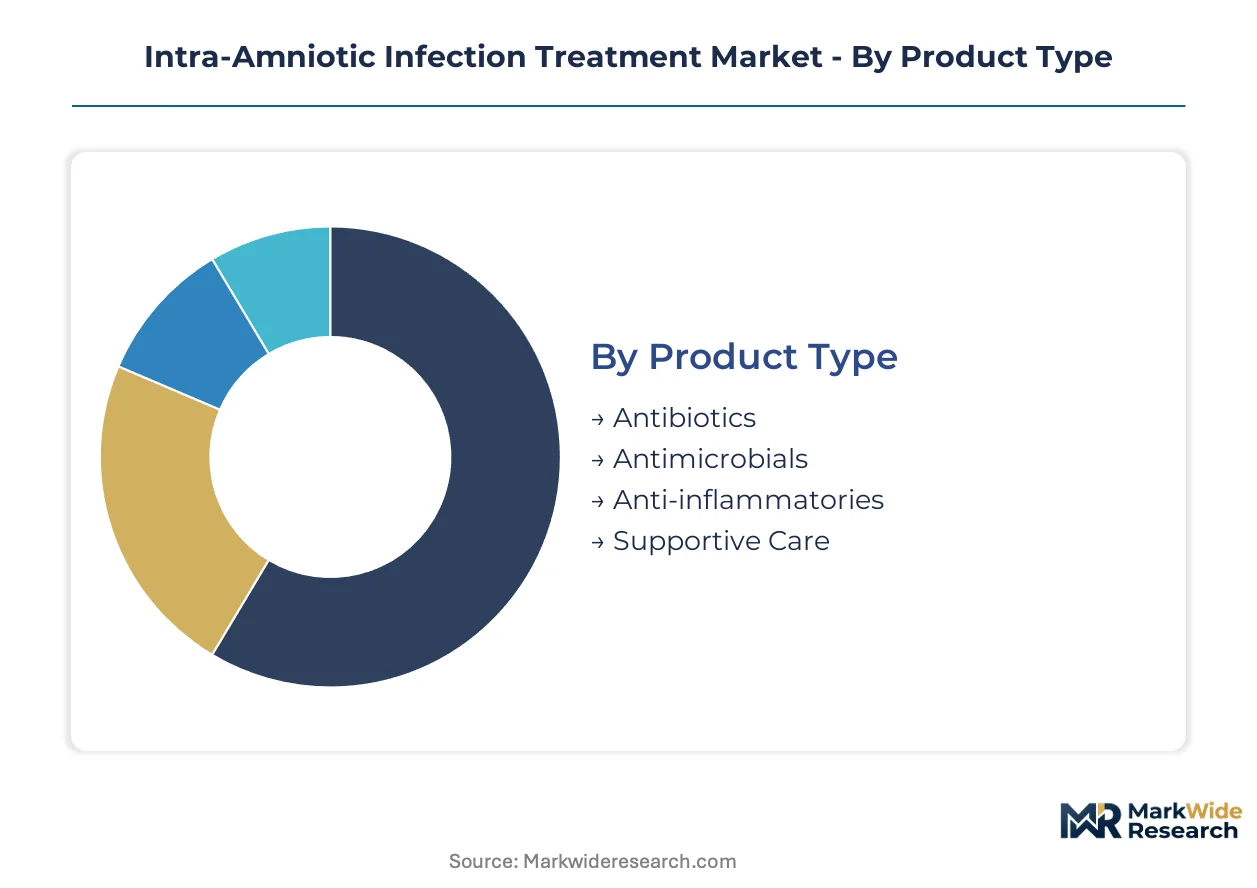
Intra-amniotic infection treatment markets fragment across therapeutic modality, care setting, and clinical application. Each segmentation axis reveals distinct procurement patterns, reimbursement pathways, and technology adoption velocities that shape competitive strategy.
Product Type:
Standardization dominates antibiotic and antimicrobial formulations, while customization pressures intensify for supportive care combinations tailored to maternal comorbidity profiles.
- Antibiotics:Intravenous beta-lactam formulations with anaerobic coverage constitute the clinical standard for chorioamnionitis protocols. Hospital formulary committees in the United States prioritize agents with established neonatal safety profiles and resistance-management credentials.
- Antimicrobials:Broad-spectrum coverage including gram-negative and anaerobic pathogens addresses polymicrobial intra-amniotic infections. Demand concentrates in tertiary maternity wards with established obstetric intensive care infrastructure.
- Anti-inflammatories:Adjunctive corticosteroid protocols reduce fetal inflammatory response syndrome.
- Supportive Care:Fluid management and tocolytic combinations customize to gestational age and maternal status.
Most installed capacity flows through antibiotics. Expansion is steepest in supportive care.
End User:
Patient acuity gradients across care settings determine equipment requirements, staffing ratios, and regulatory compliance burdens.
- Hospitals:Tertiary academic medical centers with labor-and-delivery units command the largest patient volume and most complex case mix. These facilities maintain 24-hour pharmacy coverage and obstetric anesthesia services required for emergency cesarean protocols.
- Maternity Wards:Dedicated obstetric units within larger hospital systems standardize prophylactic antibiotic administration prior to incision. Same-day procedure expansion is compressing length-of-stay metrics.
- Clinics:Prenatal screening and low-risk delivery sites refer complicated infections upward.
- Outpatient Surgery Centers:Ambulatory settings with abbreviated protocols gain share for scheduled procedures.
Most installed capacity flows through hospitals. Outpatient surgery centers are gaining share fastest.
Application:
Clinical urgency varies from emergent infection control to scheduled prophylaxis, reshaping inventory and staffing models.
- Labor and Delivery:Active intrapartum chorioamnionitis requires immediate IV antibiotic initiation with continuous fetal monitoring. Tertiary units in the United States deploy standardized order sets reducing time-to-treatment.
- Infection Management:Postpartum endometritis and wound infection protocols extend antibiotic duration. These cases concentrate in facilities with established antimicrobial stewardship programs.
- Preterm Birth:Cervical insufficiency and premature rupture of membranes trigger distinct therapeutic algorithms.
- Surgical Procedures:Elective and emergency cesarean prophylaxis drives institutional purchasing volume.
Most installed capacity flows through labor and delivery. Infection management shows the steepest expansion trajectory.
Treatment Approach:
Technology intensity separates high-intervention pharmacological and surgical segments from monitoring-dependent categories.
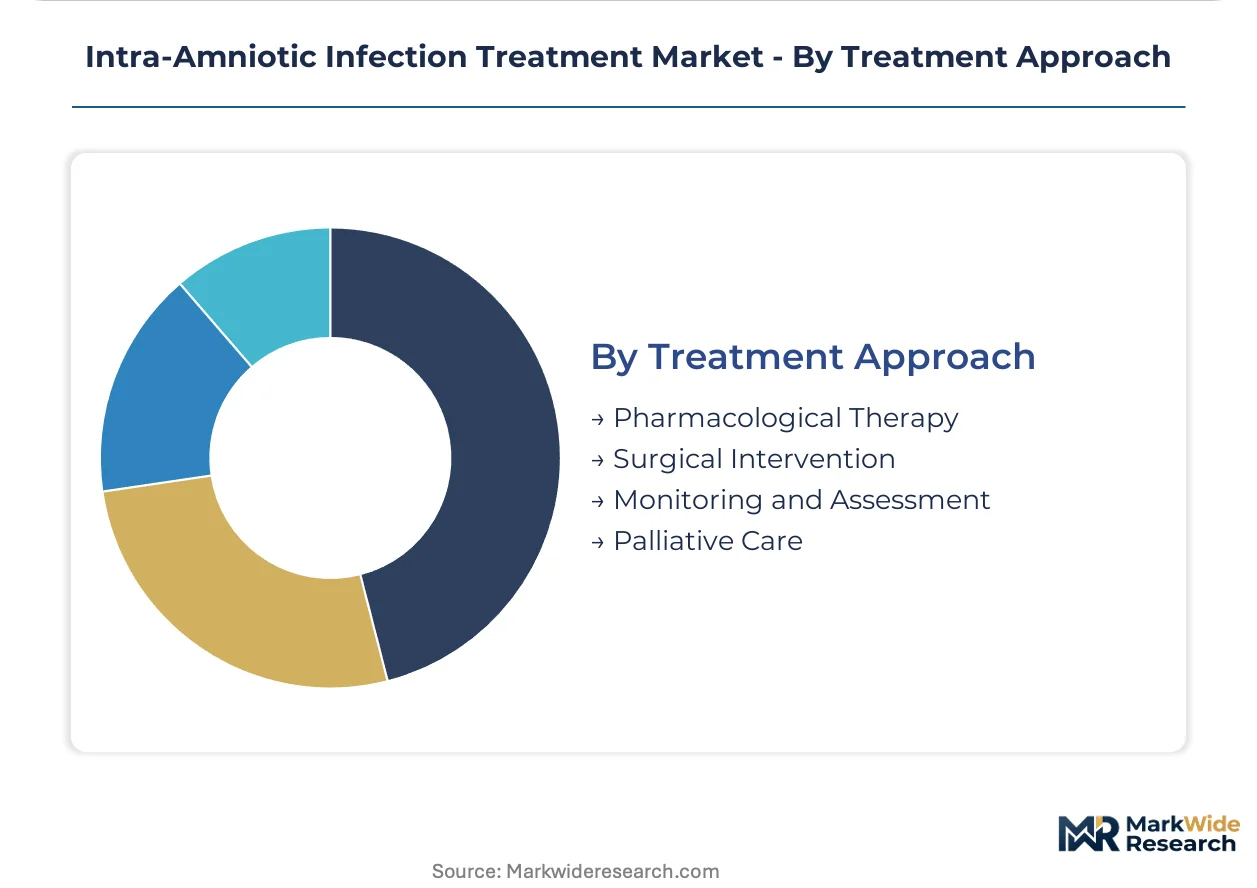
- Pharmacological Therapy:Systemic antibiotic administration with pathogen-directed escalation remains the revenue core. Formulary contracts bundle multiple agents across maternal and neonatal indications.
- Monitoring and Assessment:Continuous fetal heart rate surveillance combined with maternal inflammatory biomarker tracking displaces reactive paradigms. Integrated platform deployment accelerates in United States tertiary centers.
- Surgical Intervention:Emergency cesarean delivery and amniocentesis for diagnostic culture require operating room availability.
- Palliative Care:Perinatal hospice and comfort-focused protocols address non-viable presentations.
Most installed capacity flows through pharmacological therapy. Monitoring and assessment climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States tertiary hospital networks concentrate the highest-value procurement for intra-amniotic infection protocols, with institutional purchasing power reshaping competitive dynamics across North America, Europe, and Asia-Pacific.
United States
Cesarean delivery rates exceeding 30% sustain institutional demand for prophylactic antibiotic protocols, while the FDA's antimicrobial stewardship mandates compress formulary discretion toward narrow-spectrum alternatives. Hospital procurement committees in tertiary academic medical centers bundle multi-indication antibiotic contracts through group purchasing organizations.
Germany
EMA pediatric investigation plans accelerate neonatal pharmacokinetic studies, expanding the evidence base for obstetric antibiotic indications. REACH compliance obligations for intravenous excipient safety extend registration timelines for new market entrants. Chemical manufacturing clusters in North Rhine-Westphalia supply cephalosporin active pharmaceutical ingredients to European formulators.
India
Domestic tender procurement for public hospital maternity wards drives volume demand for cost-optimized beta-lactam formulations. CDSCO post-market surveillance requirements for perinatal antibiotics intensify pharmacovigilance obligations for manufacturers. API production concentrates in Gujarat and Maharashtra chemical manufacturing zones serving global formulators.
China
NMPA reform of drug registration pathways streamlines clinical trial requirements for obstetric indications, accelerating domestic product launches. Dual carbon goals pressure chemical manufacturers to decarbonize cephalosporin synthesis processes. Yangtze River Delta pharmaceutical clusters supply intermediate compounds to international antibiotic producers.
United Kingdom
NHS England's obstetric care standardization programs mandate prophylactic antibiotic administration prior to cesarean incision across maternity networks. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for perinatal therapeutics. London-based hospital trusts deploy integrated fetal monitoring platforms combining biomarker surveillance with electronic health record integration.
Intra-Amniotic Infection Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue microbiome-sparing formulations and rapid-infusion delivery systems. Market structure consolidates around vertically integrated cephalosporin manufacturers with captive API supply and generic specialists competing on tender pricing. Three archetypes dominate: multinational pharmaceutical corporations with hospital formulary relationships, regional generic manufacturers with backward integration into API production, and specialty injectable formulators with abbreviated regulatory pathways. Competitive moves center on procurement contract consolidation through group purchasing organization alignment and capacity expansion in Indian and Chinese chemical manufacturing clusters.
Among North American and European pharmaceutical corporations, Pfizer Inc. and GlaxoSmithKline plc occupy positions anchored by institutional formulary presence and sustained clinical education investments. Cipla Limited represents the regional generic archetype with manufacturing scale serving emerging market tender procurement. These three entities exemplify the tiered competitive structure where originator brand loyalty in tertiary hospitals coexists with cost-optimized alternatives in price-sensitive procurement environments.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Cipla Limited |
| Zydus Cadila Healthcare Ltd |
| Aristopharma Ltd |
| Akums (Maxcure Drugs and Pharmaceuticals) |
| ACS Dobfar S.p.A. |
| Apotex Inc. |
| GlaxoSmithKline plc |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Cephalosporin API spot price indices cascade through formulator cost structures into three distinct procurement tiers. Hospital formulary committees in the United States leverage group purchasing organization scale to compress originator premiums, while Indian tender procurement absorbs cost volatility through multi-source generic substitution.
Pricing Analysis
Input-cost pass-through from cephalosporin active pharmaceutical ingredient fluctuations stratifies pricing across premium originator, standard multi-source, and economy tender tiers. Price differentiation hinges on FDA pregnancy labeling tier and neonatal safety certification status, with tertiary academic medical centers least sensitive and Indian public hospital procurement most sensitive. Pricing pressure stems from antimicrobial stewardship mandates favoring narrow-spectrum alternatives with microbiome-preservation claims. Cost compression in the economy tier intensifies because of backward integration advantages among Gujarat and Maharashtra API producers.
Supply Chain Analysis
CEP certification and FDA establishment inspection status gate entry into United States hospital formulary contracts, filtering qualified suppliers to a narrow tier. Cephalosporin API production concentrates in China, India, and Italy, with intermediate synthesis feeding from Yangtze River Delta and North Rhine-Westphalia chemical clusters. Raw material dependencies include 7-aminocephalosporanic acid, acetic anhydride, and specialty fermentation media. Single-source vulnerability in Chinese chemical manufacturing exposes formulators to geopolitical disruption. Distribution runs through group purchasing organization contracts and direct hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where antimicrobial stewardship incentives reward microbiome-sparing formulations with procurement preference. Demand is shifting toward premium specifications that demonstrate neonatal pharmacokinetic safety and resistance-management credentials.
For Market Incumbents: Deepen backward integration into cephalosporin API production to defend margin position against Indian tender competitors. Secure captive supply of 7-aminocephalosporanic acid from Yangtze River Delta or Gujarat chemical clusters. Invest in EMA pediatric investigation plan completion to anchor formulary loyalty against narrow-spectrum substitutes. For New Entrants and Emerging Players: Rapid-infusion delivery system technology offers a technology-first wedge into United States outpatient surgery center expansion. Target ambulatory obstetric settings with abbreviated antibiotic protocols requiring minimal monitoring infrastructure. Pursue 505(b)(2) regulatory pathways leveraging existing neonatal safety databases to accelerate market entry. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty injectable formulators possessing abbreviated regulatory pathways and microbiome-sparing formulation pipelines. Long-term viability centers on perinatal therapeutic franchises with demonstrated stewardship compliance. The signal to watch is FDA guidance evolution on perinatal antimicrobial resistance metrics as procurement inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pediatric Investigation Plan Completion | Neonatal pharmacokinetic data expands addressable evidence base for obstetric antibiotic indications. |
| Backward Integration into API Production | Gujarat and Maharashtra chemical clusters enable cost positions in emerging market tender procurement. |
| Microbiome-Sparing Formulation Development | Antimicrobial stewardship incentives reward agents with demonstrated neonatal microbiome preservation. |
| Real-Time Molecular Diagnostic Integration | PCR platform convergence with EHR systems enables pathogen-directed therapy selection within two hours. |
| Outpatient Surgery Center Protocol Design | Abbreviated antibiotic regimens with rapid infusion profiles capture same-day obstetric procedure expansion. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with obstetric pharmacy directors, formulary committee members, GPO contract managers, and perinatal antibiotic development executives combined with secondary validation from FDA pregnancy labeling databases, EMA pediatric investigation plan registries, ClinicalTrials.gov obstetric protocol listings, and Indian CDSCO tender award disclosures. Triangulation between demand-side procurement patterns and supply-side manufacturing capacity anchors volume and value estimates.
Historical trendline analysis of cesarean protocol standardization rates and antimicrobial stewardship program penetration established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated treatment approach, care setting acuity, regional regulatory cluster, and neonatal indication expansion potential. CAGRs derived from regression analysis of protocol adoption curves and formulary contract renewal patterns, calibrated against API price elasticity and hospital reimbursement adjustment timelines.
The model holds under stable antimicrobial stewardship regulatory trajectories; deviation in FDA resistance-management guidance or EMA excipient safety reclassification would shift forecast parameters. A model refresh is warranted upon material change in perinatal antibiotic procurement tied to neonatal microbiome preservation metrics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Community Acquired Pneumonia (CAP) Market
Infection Control
Sterility Indicators Market
Infection Control
Sterilization Equipment and Disinfectant Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Germicidal UV Lamp Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Global Sepsis Therapeutics Market
Infection Control
Global Disinfection Robots Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Denture Disinfectants Market
Infection Control
Medical Washer Disinfector Market
Infection Control
Alcohol Wipes Market
Infection Control
Australia Healthcare Surface Disinfectant Wipes Market
Infection Control
Patient Hygiene Aids Market
Infection Control
North America Hand Sanitizer Market