
 Global Vaccine Contract Manufacturing Market | 2026-2036
Global Vaccine Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vaccine Contract Manufacturing Market Foresight
Swiss bulk manufacturing capacity is hardening into a strategic bottleneck as pandemic-era expansion slows and new molecular formats strain existing infrastructure. Lonza Group AG leverages its Visp campus to anchor global cell-and-gene therapy supply chains, while Samsung Biologics Co., Ltd. competes through successive capacity additions at its Songdo mega-site. Thermo Fisher Scientific Inc. extends its position via integrated analytical services that reduce technology transfer friction for client programs.
Vaccine contract manufacturing encompasses the outsourced production, fill-finish, and release testing of immunological products under client-owned licenses, typically requiring biosafety level containment, cold-chain validation, and aseptic processing compliant with pharmacopeial sterility assurance levels. The activity serves pharmaceutical and biotech sponsors seeking to avoid capital-intensive facility construction while preserving speed-to-regulatory-submission. mRNA vaccine type segments command premium pricing due to lipid nanoparticle formulation complexity and limited qualified supplier pools, whereas bulk manufacturing services dominate volume throughput as clients retain proprietary fill-finish capabilities. Protein subunit modalities occupy mature, cost-competitive territory with established downstream purification protocols.
FDA current good manufacturing practice enforcement and EMA's evolving guidance on genetically modified organism containment establish baseline compliance costs that filter out subscale operators. WHO prequalification pathways and national regulatory authority mutual recognition agreements determine market access for products destined to Gavi-eligible countries. Stakeholders must monitor how emerging platform technologies alter facility design specifications and whether regulator convergence on continuous manufacturing standards accelerates obsolescence risk in legacy batch infrastructure.
Market Dynamics
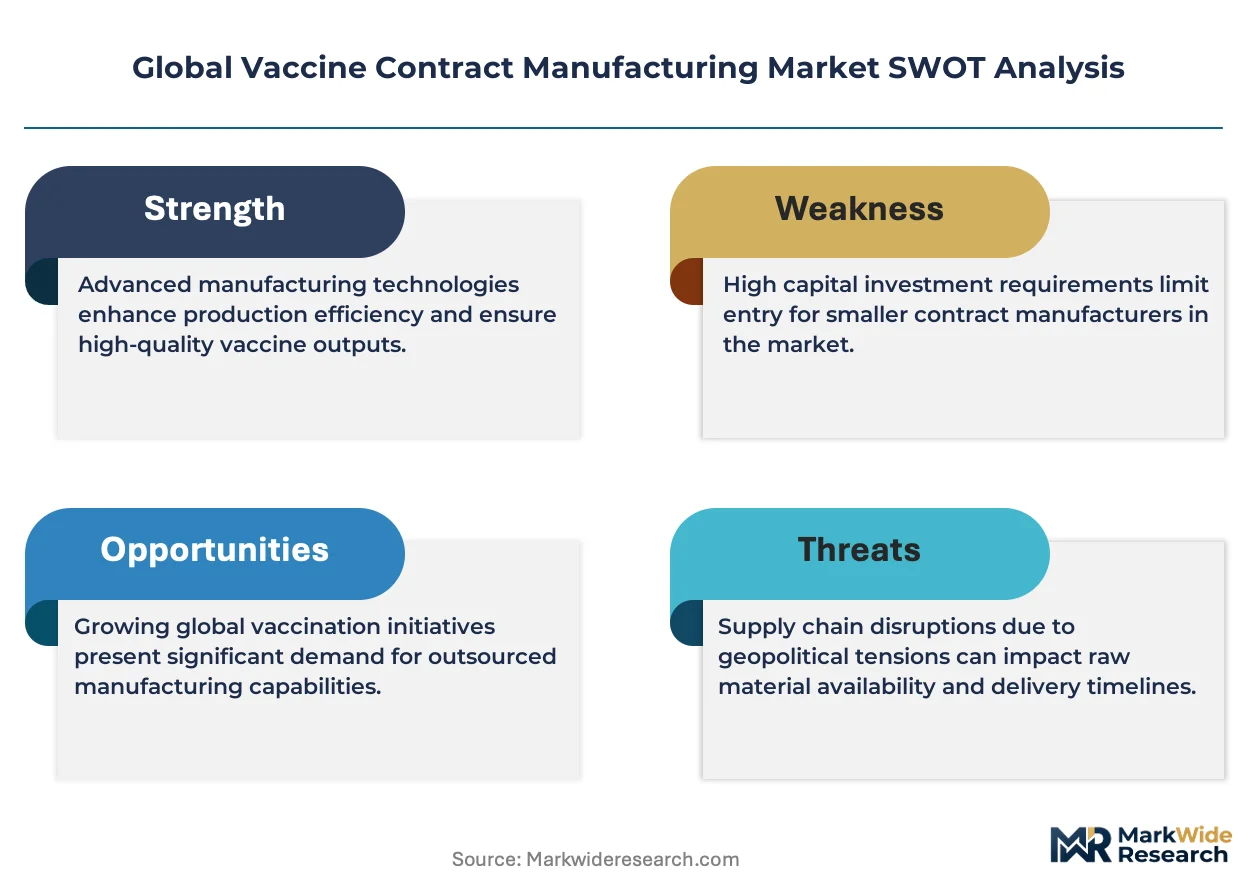
mRNA platform complexity has outpaced in-house biotech capabilities, forcing sponsors toward outsourced production partnerships that concentrate supply risk among qualified contract manufacturers with specialized containment and lipid nanoparticle formulation expertise.
Growth Catalysts
- EMA's evolving GMP standards for novel modalities:Accelerated qualification pathways for cell-and-gene therapy facilities are compressing client onboarding timelines for contract partners with pre-validated infrastructure.
- Biotech pipeline expansion:Venture-backed immunotherapy developers lack capital for captive manufacturing, creating sustained demand pull for outsourced bulk production and aseptic fill-finish services.
- Switzerland-South Korea capacity clustering:Specialized biologics hubs in Visp and Songdo have attracted multibillion-dollar infrastructure investments that anchor regional supply chains for global vaccine distribution.
Market Restraints
- Single-source lipid supplier concentration:Ionizable lipid production for mRNA formulations depends on a narrow qualified vendor base, exposing programs to input volatility and force majeure disruption.
- FDA current good manufacturing practice enforcement:Inspection intensity and data integrity requirements have lengthened remediation cycles for facilities with legacy quality management systems.
- Batch processing infrastructure lock-in:Sunk capital in stainless steel bioreactor trains creates technical debt that slows adoption of continuous manufacturing platforms requiring modular single-use architectures.
Strategic Opportunities
- India's emerging CDMO corridor:Hyderabad and Bangalore infrastructure investments are positioning domestic manufacturers to capture WHO prequalification pathways for Gavi-eligible country supply.
- Integrated analytical services bundling:Contract partners combining release testing with manufacturing are reducing technology transfer friction and accelerating client program timelines.
- Dual-use pandemic preparedness mandates:Government stockpiling programs for rapid-response mRNA platforms are creating dedicated capacity reservation contracts with preferential pricing terms.
Industry Challenges
- Aseptic processing technician scarcity:Qualified operators for isolator-based fill-finish operations command premium wages that compress contract manufacturing margins.
- Technology transfer timeline compression:Client pressure for accelerated IND-enabling batches strains validation documentation rigor and risks regulatory query delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vaccine Contract Manufacturing Market |
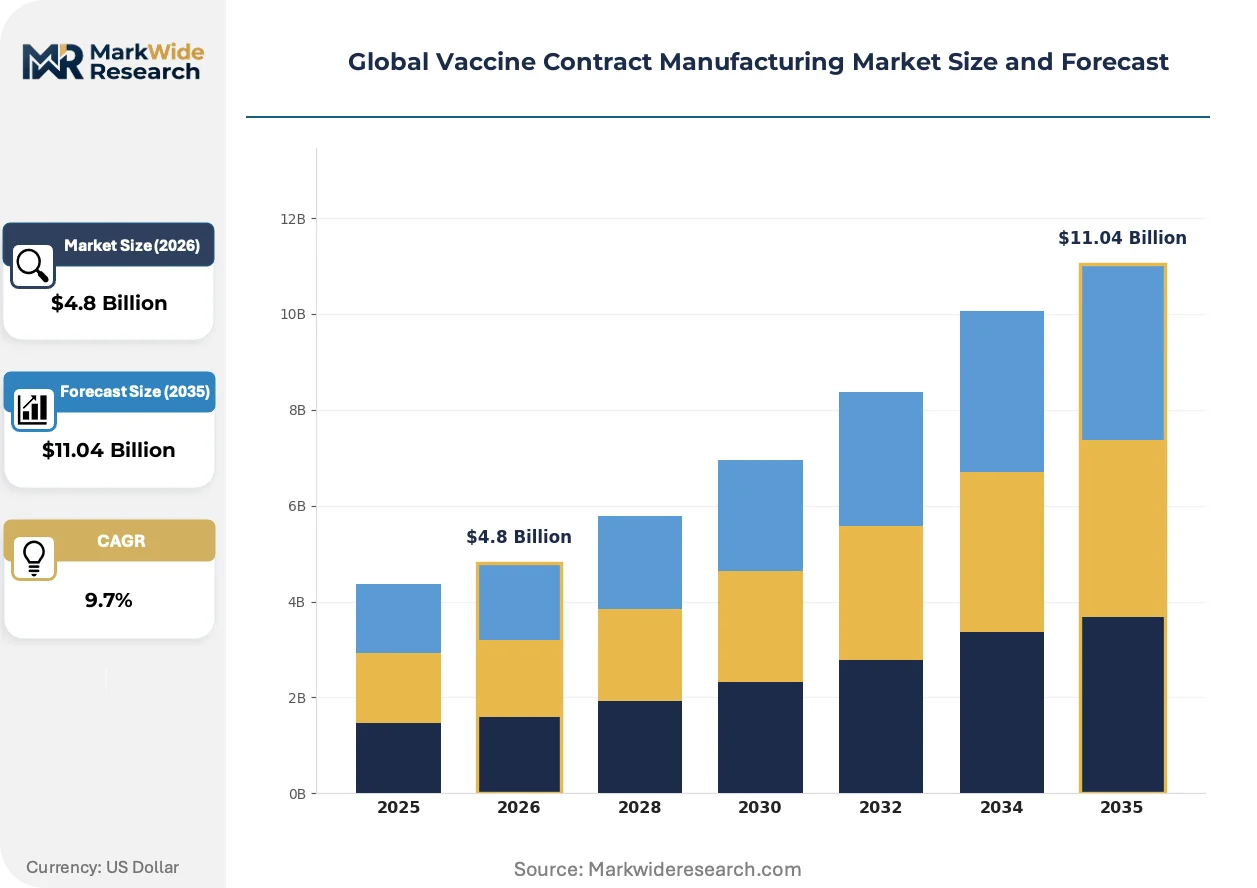
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Bulk Manufacturing, Formulation & Filling, Packaging, Labeling, Quality Testing Vaccine Type: mRNA, Viral Vector, Protein Subunit, Inactivated Virus, DNA End User: Pharmaceutical Companies, Biotech Firms, Research Organizations, Government Agencies Production Scale: Small Scale, Pilot Scale, Commercial Scale, Large Scale, Clinical Trial Batch |
| Companies Covered | Lonza Group AG, Catalent, Inc., Thermo Fisher Scientific Inc., Samsung Biologics Co., Ltd., WuXi Biologics, FUJIFILM Diosynth Biotechnologies, IDT Biologika GmbH, Charles River Laboratories International Inc., Emergent BioSolutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vaccine Contract Manufacturing Market Shifts & Advancements
Platform standardization and modular facility design are compressing the traditional build-validate-operate cycle for vaccine manufacturing infrastructure, while regulatory convergence on continuous processing standards is reshaping capital deployment priorities across the contract manufacturing base.
Single-use bioreactor systems are unifying upstream cell culture and downstream purification workflows into integrated continuous processing trains. Mid-sized biotech sponsors are adopting these platforms for Phase III commercial readiness, reducing cross-contamination risk between multi-product campaigns. The technology is unifying batch record complexity and enabling faster facility repurposing for emerging viral vector programs.
EMA's Annex 1 revision on sterile product manufacturing is mandating barrier isolation technology and enhanced environmental monitoring for aseptic processing suites. Contract manufacturers are retrofitting legacy cleanroom infrastructure to meet the 2023 enforcement timeline, diverting capital from greenfield expansion. European facilities with pre-existing isolator capabilities are capturing client migrations from open-filling operations facing compliance gaps.
Biotech procurement teams are consolidating supplier relationships around integrated CDMO partnerships that span drug substance through commercial packaging. Small and mid-cap sponsors are displacing fragmented vendor models with single-accountability contracts that transfer release testing and regulatory filing support to manufacturing partners. This concentration is most visible among US and European sponsors with limited internal CMC capabilities and accelerated approval pathway designations.
Global Vaccine Contract Manufacturing Market Segmentation
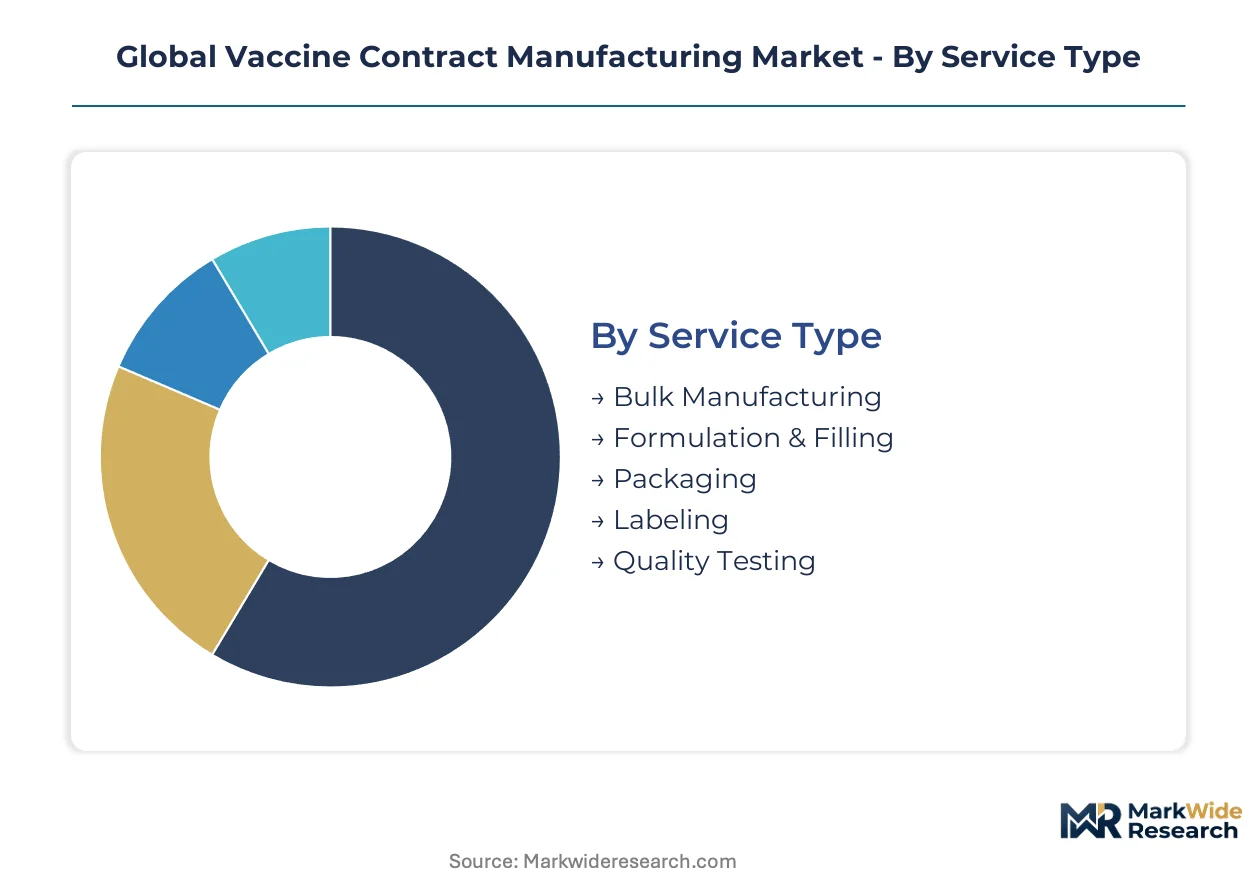
Vaccine contract manufacturing segments reflect divergent capital deployment requirements, with lipid nanoparticle infrastructure commanding multibillion-dollar investments while packaging services operate at fractionally lower asset intensity. Understanding these structural cost tiers illuminates where capacity bottlenecks concentrate and which service lines attract specialized entrants versus integrated incumbents.
Service Type:
Bulk manufacturing absorbs the heaviest upfront capital burden, with stainless steel bioreactor trains and downstream purification suites requiring decade-long depreciation cycles before margin contribution.
- Bulk Manufacturing:Upstream cell culture and microbial fermentation at kilogram-to-tonne scales demands biosafety level containment and dedicated viral clearance validation. Demand clusters around Swiss and South Korean mega-sites where Lonza and Samsung Biologics have sunk multibillion-dollar investments into single-use and stainless steel capacity.
- Formulation & Filling:Lipid nanoparticle encapsulation for mRNA platforms requires precision microfluidic mixing and cold-chain sterile filtration. Aseptic isolator technology mandated under EMA's Annex 1 revision is driving client migrations toward European facilities with pre-validated barrier systems.
- Packaging:Secondary packaging and kit assembly for multidose vials operates at lower regulatory complexity but requires serialization compliance for FDA track-and-trace mandates.
- Labeling:Multilingual booklet insertion and country-specific regulatory text adaptation serves distributed clinical trial supply and commercial launch sequences.
- Quality Testing:Release assays, sterility validation, and stability protocol execution often bundle with manufacturing contracts to compress technology transfer timelines.
Most installed capacity flows through Bulk Manufacturing. Expansion is steepest in Formulation & Filling.
Vaccine Type:
Platform maturity determines whether sponsors retain in-house production or outsource entirely, with novel modalities forcing external partnership while established formats sustain hybrid models.
- mRNA:Synthetic biology-dependent platforms requiring enzymatic in vitro transcription and lipid nanoparticle encapsulation. Qualified supplier scarcity in ionizable lipids concentrates manufacturing partnerships among CDMOs with dedicated containment suites.
- Viral Vector:Adeno-associated and lentiviral production for gene therapy applications demands helper virus-free packaging cell lines and extensive adventitious agent testing. Capacity constraints in HEK293 suspension culture are extending client waitlists at specialized facilities.
- Protein Subunit:Recombinant antigen expression with established downstream purification protocols operates in cost-competitive territory where yield optimization determines contract awards.
- Inactivated Virus:Egg-based and cell culture-derived whole virus formulations retain significant share in influenza and polio supply chains, particularly for WHO prequalified products.
- DNA:Plasmid manufacturing for genetic vaccination platforms leverages bacterial fermentation infrastructure with lower complexity than mammalian cell systems.
Protein Subunit retains the largest manufacturing footprint. mRNA is climbing the fastest as pandemic preparedness programs reserve dedicated capacity.
End User:
Internal CMC capability gaps determine outsourcing depth, with capital-constrained developers surrendering entire manufacturing workflows while majors retain strategic control.
- Pharmaceutical Companies:Multinational sponsors with captive manufacturing selectively outsource overflow capacity and novel modality production where internal expertise lags platform evolution.
- Biotech Firms:Venture-backed immunotherapy developers lacking facility capital rely entirely on contract partners for IND-enabling batches through commercial supply, creating sustained demand pull for integrated CDMO relationships.
- Research Organizations:Academic and nonprofit vaccine institutes contract fill-finish and release testing for investigator-initiated trials and early-phase translational programs.
- Government Agencies:BARDA, HHS, and equivalent national preparedness bodies negotiate capacity reservation contracts with preferential pricing for rapid-response surge manufacturing.
Biotech Firms drive the majority of new contract initiations. Government Agencies are expanding fastest through pandemic preparedness mandates.
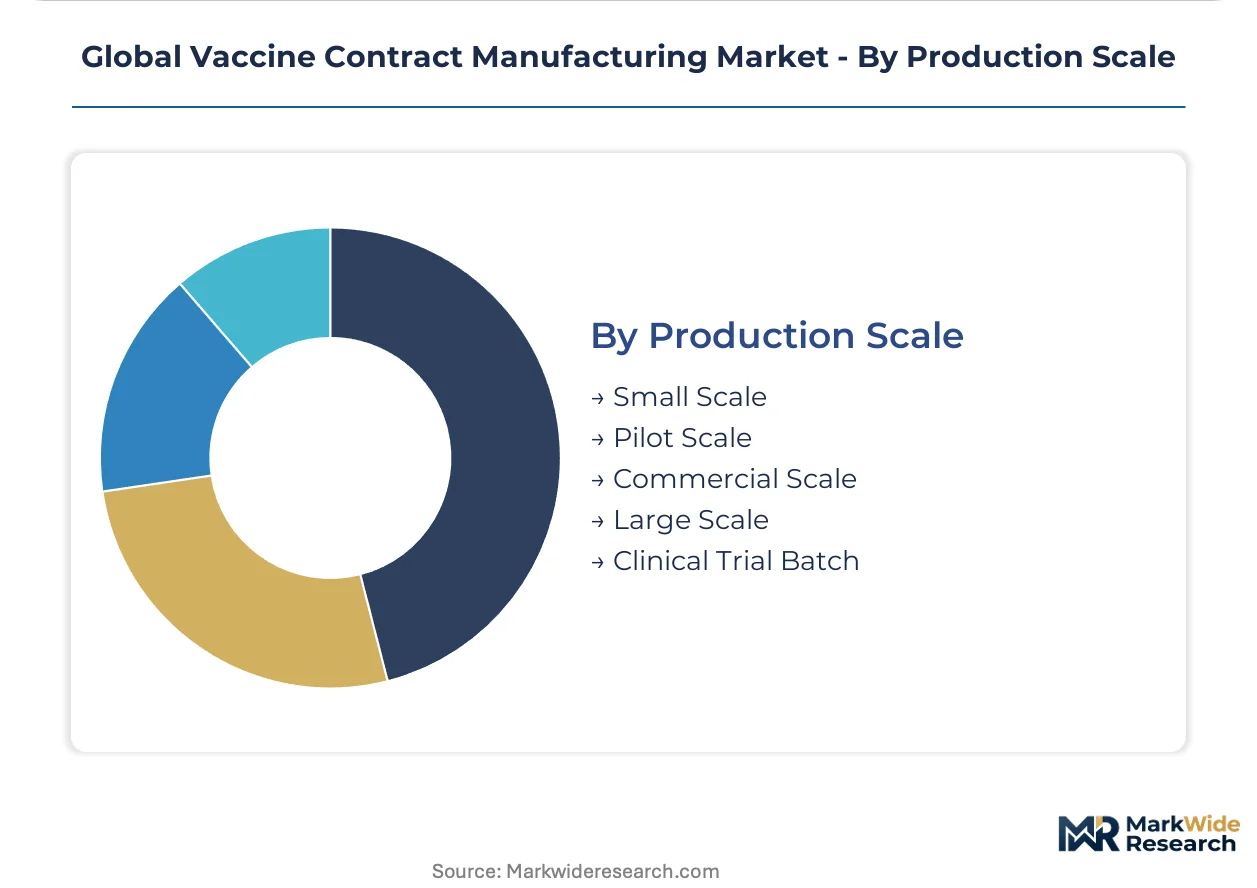
Production Scale:
Facility design specifications diverge sharply across scale tiers, with clinical batch suites requiring rapid changeover flexibility and commercial trains optimizing for monoclonal campaign efficiency.
- Commercial Scale:Multi-tonne bioreactor operations with dedicated downstream trains and automated buffer preparation systems. FDA and EMA inspection history becomes decisive in sponsor selection criteria.
- Pilot Scale:Engineering batch production for process validation and PPQ sequence execution bridges development and commercial readiness.
- Clinical Trial Batch:Flexible single-use suites with accelerated changeover protocols serve Phase I through Phase III material supply with abbreviated validation timelines.
- Large Scale:Pandemic surge capacity and government stockpiling programs operate at maximum throughput with simplified product portfolios.
- Small Scale:Early-phase toxicology and first-in-human material production at gram-to-kilogram scales.
Commercial Scale commands the greatest absolute capacity investment. Clinical Trial Batch is gaining share fastest as biotech pipeline density accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing vaccine manufacturing capacity toward jurisdictions where FDA and EMA compliance costs diverge from emerging-market qualification pathways. Sponsors now site bulk production in high-standard jurisdictions while reserving fill-finish and secondary packaging for lower-cost regions with mutual recognition agreements.
United States
BARDA capacity reservation contracts and HHS pandemic preparedness mandates are securing dedicated mRNA surge capacity at domestic CDMOs. FDA current good manufacturing practice enforcement intensity has lengthened remediation cycles for legacy facilities. The Boston-Cambridge biotech corridor anchors demand for clinical trial batch services as venture-backed immunotherapy developers outsource IND-enabling production.
Switzerland
Swissmedic oversight and EMA centralized marketing authorization procedures attract sponsors seeking streamlined European access. The Visp biologics cluster concentrates multibillion-dollar investments in cell-and-gene therapy infrastructure. Lonza Group AG leverages this site to anchor global supply chains for novel modalities requiring biosafety level containment.
South Korea
MFDS accelerated approval pathways and government biotech industrial policy are compressing facility qualification timelines for contract partners. The Songdo mega-site anchors regional supply chains through successive capacity additions. Samsung Biologics Co., Ltd. competes via integrated drug substance-to-fill-finish offerings that reduce technology transfer friction.
India
CDSCO manufacturing licensing and WHO prequalification pathways position domestic CDMOs to supply Gavi-eligible countries at cost-competitive terms. Hyderabad and Bangalore infrastructure investments are attracting multi-product biologics facilities. Local manufacturers are capturing overflow demand from Western sponsors seeking to avoid capital-intensive facility construction.
Germany
EMA Annex 1 sterile manufacturing revisions and national pharmaceutical regulator inspections are mandating isolator-based aseptic processing retrofits. The Frankfurt-Rhine-Main biotech corridor concentrates viral vector production expertise for gene therapy applications. IDT Biologika GmbH occupies a position within this ecosystem serving European sponsors with limited internal CMC capabilities.
Global Vaccine Contract Manufacturing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated analytical services and pandemic preparedness capacity reservation contracts. The vendor base stratifies across Swiss and South Korean mega-sites with multibillion-dollar infrastructure, mid-scale European specialists with isolator capabilities, and emerging Indian CDMOs targeting WHO prequalification. Three archetypes dominate: integrated platform providers bundling drug substance through commercial packaging, modality specialists concentrating in mRNA or viral vectors, and government-contracted surge capacity operators. Competitive moves center on capacity expansion in high-standard jurisdictions and strategic partnerships securing ionizable lipid supply.
Within the integrated platform tier, Lonza Group AG and Thermo Fisher Scientific Inc. exemplify archetypes combining bulk manufacturing with release testing to compress client timelines. Samsung Biologics Co., Ltd. represents the scale-driven Asian competitor capturing government-backed pandemic preparedness contracts. These three occupy positions that span the premium-to-standard service spectrum, with geographic differentiation reflecting regulatory-arbitrage strategies rather than capability gaps.
| Leading Market Players |
|---|
| Lonza Group AG |
| Catalent, Inc. |
| Thermo Fisher Scientific Inc. |
| Samsung Biologics Co., Ltd. |
| WuXi Biologics |
| FUJIFILM Diosynth Biotechnologies |
| IDT Biologika GmbH |
| Charles River Laboratories International Inc. |
| Emergent BioSolutions Inc. |
| Others |
Supply & Pricing Matrix
EMA Annex 1 sterile manufacturing revisions gate qualified supply access and premium-tier pricing for aseptic processing contracts, as facilities lacking pre-validated isolator infrastructure face exclusion from high-margin mRNA formulation programs while bearing accelerated compliance retrofit costs.
Pricing Analysis
Direct-to-sponsor contract structures dominate vaccine manufacturing, bypassing distributor markups to capture long-term offtake agreements. Pricing stratifies across GMP certification tiers, with FDA-inspected facilities commanding premiums over WHO-prequalified alternatives, and volume scale driving economies in bulk manufacturing. Cost compression in protein subunit services intensifies due to yield optimization competition among established players. Biotech sponsors exhibit highest price sensitivity for early-phase clinical batches, while government agencies accept premium reservation terms for pandemic surge capacity.
Supply Chain Analysis
EMA and FDA certification requirements concentrate qualified ionizable lipid supply in Switzerland, South Korea, and the United States, creating gating bottlenecks for mRNA platform sponsors. Manufacturing inputs draw from specialized cell culture media, single-use bioreactor consumables, and lipid nanoparticle formulation reagents. Single-source dependency on ionizable lipid vendors exposes programs to force majeure disruption. Distribution runs through cold-chain validated logistics networks with temperature-controlled warehousing at regional hub facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as sponsor procurement shifts toward integrated CDMO partnerships bundling analytical services and regulatory filing support, elevating premium-tier specifications over transactional cost competition.
For Market Incumbents: Acquire specialized viral vector production assets to defend against emerging modality specialists capturing gene therapy manufacturing demand. Consolidate ionizable lipid supply through backward integration or exclusive offtake agreements with qualified vendors. Expand isolator-based aseptic capacity in Switzerland and South Korea to anchor EMA and FDA compliance leadership.
For New Entrants and Emerging Players: Launch via WHO prequalification pathways targeting Gavi-eligible country supply from Hyderabad and Bangalore infrastructure investments. Capture overflow demand from Western sponsors seeking cost-competitive clinical trial batch production. Position around rapid technology transfer capabilities and abbreviated validation timelines for Phase I through Phase III material supply.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale European CDMOs with pre-validated isolator capabilities because EMA Annex 1 compliance gaps are forcing client migrations from legacy open-filling operations. Long-term viability centers on facilities with inspection history across FDA and EMA jurisdictions. Watch for government pandemic preparedness mandate acceleration as inflection signal for surge capacity valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Retrofit | EMA Annex 1 compliance mandates barrier isolation for aseptic processing suites by enforcement deadlines. |
| Ionizable Lipid Supply Agreement | Exclusive offtake contracts with qualified vendors reduce force majeure exposure for mRNA programs. |
| Integrated Analytical Services Bundling | Release testing and regulatory filing support compress technology transfer timelines for biotech sponsors. |
| Capacity Reservation Contract | Government stockpiling programs secure dedicated surge manufacturing with preferential pricing terms. |
| Continuous Manufacturing Platform Adoption | Single-use bioreactor trains enable faster facility repurposing for emerging viral vector programs. |
Research Methodology
Direct dialogue with contract manufacturing executives, regulatory affairs leads, biotech procurement managers, and CDMO quality directors grounds qualitative findings, cross-referenced with FDA inspection databases, EMA marketing authorization submissions, WHO prequalification listings, and clinical trial manufacturing disclosures. Bottom-up capacity modeling triangulates against top-down sponsor pipeline analysis.
Bottom-up facility capacity assessments and top-down sponsor demand projections anchor the analytical framework across the analysis window. Segmentation dimensions span service type, vaccine platform modality, end-user CMC capability tier, and production scale tier. CAGRs derive from capacity utilization trajectories and sponsor outsourcing depth assumptions, incorporating pandemic preparedness mandate intensity and regulatory qualification timeline compression as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under single-source lipid supply disruption or accelerated continuous manufacturing platform adoption. Forecasts reflect documented assumptions regarding regulatory inspection intensity and sponsor capital constraint persistence. A model refresh is warranted upon material change in government pandemic preparedness funding authorization or EMA-FDA regulatory convergence timeline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Adenosine Market
Pharmaceuticals
Conjunctivitis Drugs Market
Pharmaceuticals
Periodontal Therapeutics Market
Pharmaceuticals
Skin Cancer Drugs Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
US Generic Injectables Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Roflumilast API Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
Germany Pneumococcal Vaccines Market
Pharmaceuticals
Acne Drugs Market
Pharmaceuticals
Global Interstitial Cystitis Drugs Market