
 Saudi Arabia Automotive Fuels Market | 2026-2036
Saudi Arabia Automotive Fuels Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Automotive Fuels Market Insights
The gap between premium high-octane gasoline and standard-grade commodity fuel is consolidating as refiners optimize yield structures for diverging vehicle fleets. Saudi Aramco leverages its integrated refining-petrochemical complex to control feedstock costs across both tiers. Aldrees Petroleum and Transport Services Company anchors its position through a dense retail station network spanning eastern and central provinces. TotalEnergies differentiates via European-standard fuel formulations targeting imported vehicle warranties.
Automotive fuels are refined petroleum products formulated to specific volatility, octane, cetane, and sulfur parameters that enable controlled combustion in internal combustion engines; gasoline typically carries Reid Vapor Pressure limits and aromatic content ceilings to prevent engine knock and evaporative emissions. Diesel for commercial trucks dominates volume throughput due to freight intensity along the Riyadh-Jeddah corridor, while LPG gains structural share in fleet services where dual-fuel retrofits reduce per-kilometer energy costs. Retail stations capture the largest margin pool through convenience-store cross-subsidies, though fleet services represent the fastest-growing channel as corporate buyers centralize procurement.
SFDA oversees fuel additive safety approvals, while the Saudi Standards, Metrology and Quality Organization enforces sulfur content and octane labeling standards that determine import eligibility and domestic refinery certification. The General Authority for Competition monitors wholesale pricing transparency to prevent downstream margin manipulation. Stakeholders must track how Euro 5-equivalent specifications propagate from Riyadh to secondary cities and whether domestic refinery upgrades outpace import dependency for specialty grades.
Market Dynamics
Saudi Aramco's downstream integration and the Saudi Standards, Metrology and Quality Organization's tightening sulfur specifications are compressing refinery margins while forcing wholesale buyers toward long-term offtake contracts.
Growth Catalysts
- Logistics corridor expansion:Commercial trucking fleets along the Riyadh-Jeddah-Dammam triangle are expanding diesel procurement volumes as port connectivity and warehouse clustering intensify freight density.
- Euro 5-equivalent mandates:The Saudi Standards, Metrology and Quality Organization's sulfur content ceilings are accelerating refinery upgrade cycles and creating import substitution opportunities for domestic specialty-grade production.
- Dual-fuel retrofit adoption:Fleet operators are installing LPG conversion kits to reduce per-kilometer energy costs, expanding addressable demand beyond conventional gasoline and diesel pools.
Market Restraints
- Crude feedstock volatility:Refining economics swing with Brent-linked crude differentials, compressing margin visibility for independent fuel marketers without integrated upstream assets.
- Refinery concentration:Saudi Aramco controls the majority of domestic refining capacity, limiting third-party access to feedstock and constraining wholesale market liquidity.
- Octane specification divergence:Imported vehicle warranties requiring European-standard formulations create parallel inventory requirements that strain distributor working capital.
Strategic Opportunities
- Secondary city penetration:Euro 5-equivalent specifications are propagating from Riyadh toward Tabuk and Hail, opening underpenetrated retail station development corridors.
- Fleet services centralization:Corporate buyers are consolidating fuel procurement through dedicated bunkering contracts, bypassing retail margin pools and capturing volume-based pricing.
- Convenience-store cross-subsidy models:Retail operators are expanding non-fuel revenue streams to offset regulated pump margins, replicating European forecourt economics.
Industry Challenges
- Refinery certification timelines:Domestic upgrades to meet tightening sulfur and octane benchmarks require extended capital deployment cycles before SFDA and SASO approvals.
- Dual-fuel technician scarcity:LPG retrofit installation and maintenance demand specialized training that outpaces current vocational pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Automotive Fuels Market |
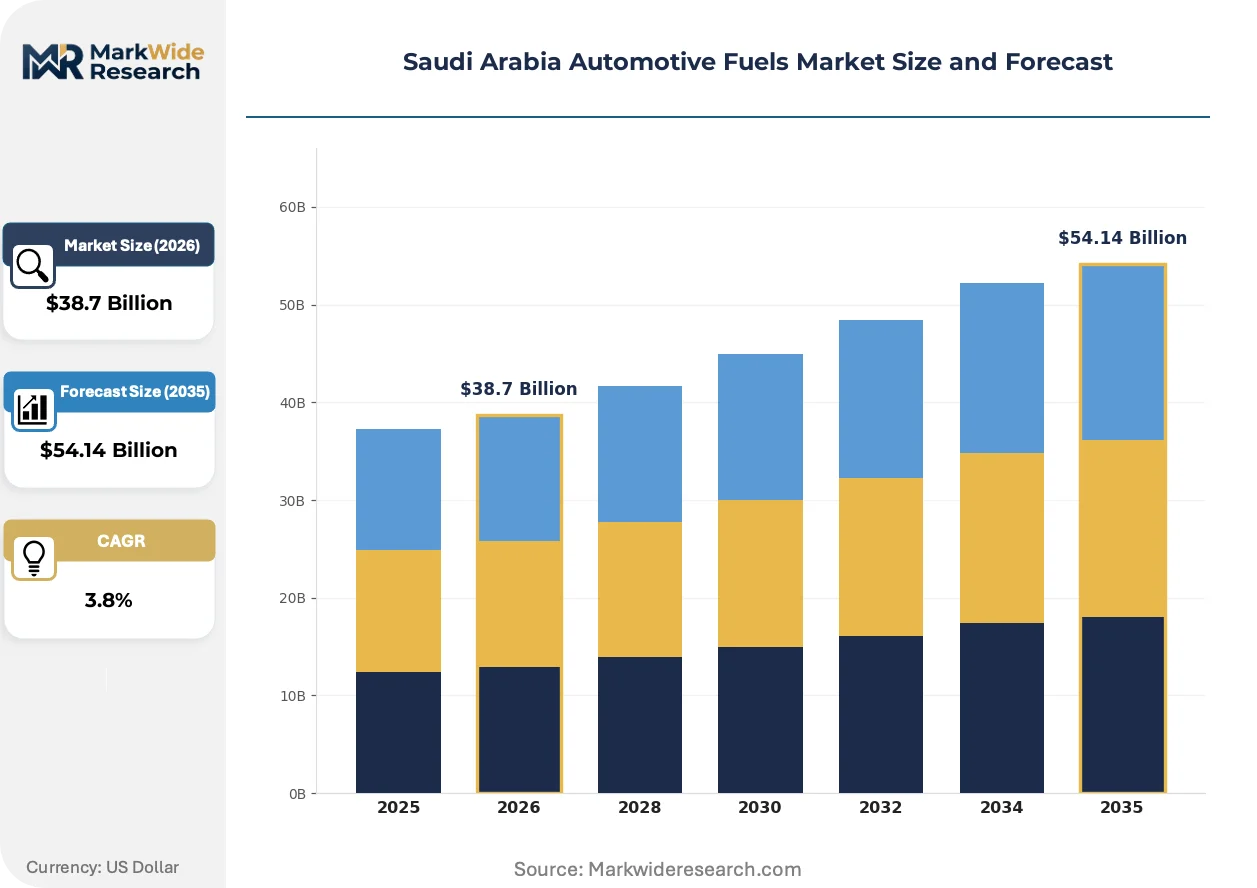
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $54.14 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Gasoline, Diesel, LPG, Ethanol End User: Passenger Vehicles, Commercial Trucks, Buses, Motorcycles Distribution Channel: Retail Stations, Wholesale, Online, Fleet Services Certification: ISO 9001, ASTM, API, Others |
| Companies Covered | Saudi Aramco, Aldrees Petroleum and Transport Services Company, Saudi Automotive Services Co., Petromin Corporation, J-Oil, Mazaya Fuel, TotalEnergies, ADNOC Distribution, NAFT Services Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Automotive Fuels Market Trends and Innovations
Digital fuel management platforms and alternative drivetrain penetration are fragmenting traditional volume-based business models while compressing the gasoline-diesel demand split.
Distributed refueling infrastructure is decentralizing last-mile fuel delivery. Mobile bunkering units and on-site fleet tanks are capturing share from fixed retail stations among logistics operators with predictable route density. This compression of the traditional station network is enabling smaller fuel marketers to bypass capital-intensive real estate requirements.
SASO's sulfur content and octane labeling standards are tightening import eligibility criteria. Domestic refiners must achieve certification benchmarks before supplying specialty grades, while wholesale buyers face inventory segregation requirements. The commercial trucking segment bears the highest compliance burden as fleet operators validate cetane ratings across mixed supplier bases.
Corporate procurement centralization is consolidating fuel buying decisions. Large fleet operators are negotiating direct refinery offtake agreements, displacing fragmented retail purchasing. This channel migration is most visible along the Jeddah-Dammam corridor where logistics density supports dedicated bunkering infrastructure.
Saudi Arabia Automotive Fuels Market Segmentation
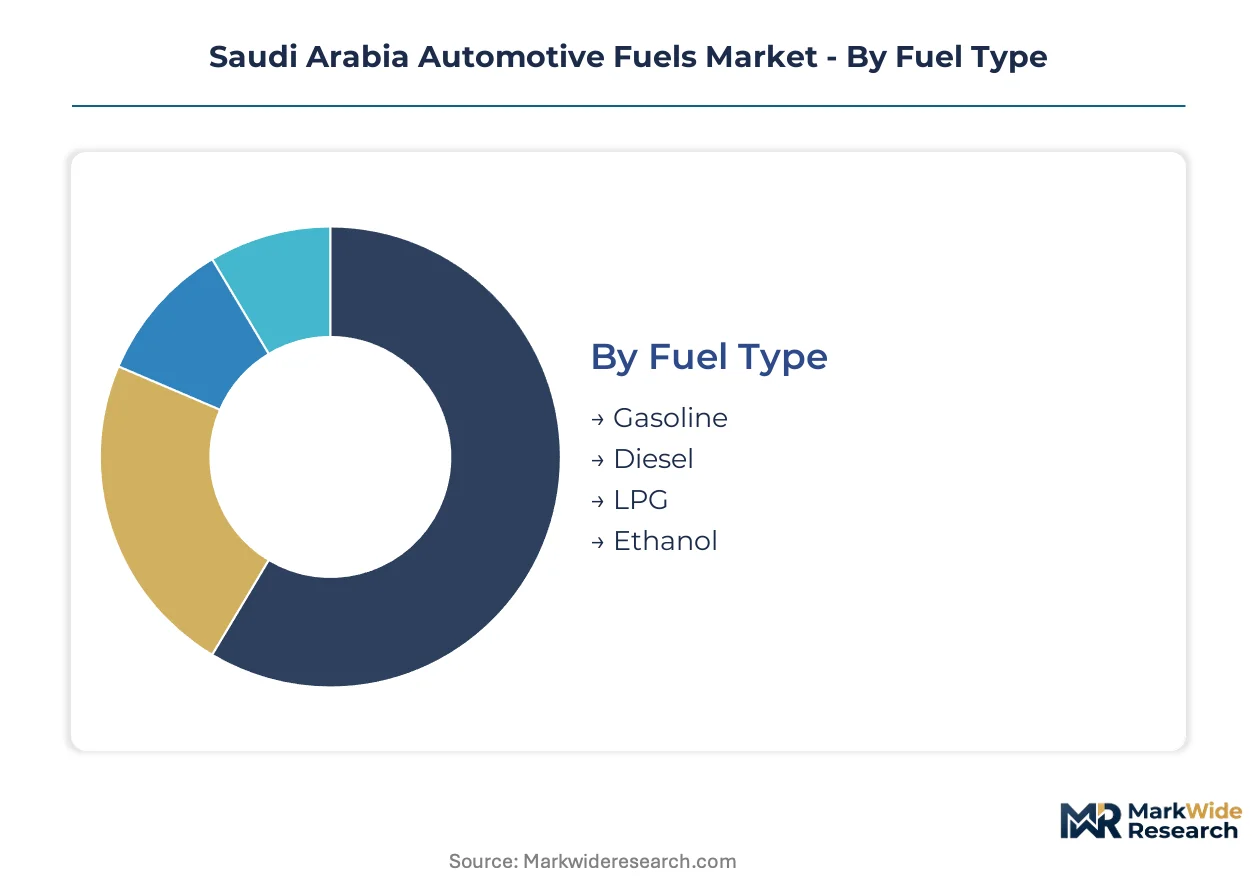
Fuel specification divergence across vehicle fleets and distribution channel fragmentation are forcing suppliers to maintain parallel inventory systems. Segmentation reveals where margin pools concentrate and which certification barriers protect incumbent positions.
Fuel Type:
Refinery yield optimization concentrates supply-side investment around transport fuels with the clearest demand visibility and regulatory protection.
- Gasoline:Refined petroleum product with Reid Vapor Pressure limits and aromatic content ceilings to prevent engine knock and evaporative emissions. Riyadh-Jeddah-Dammam urban corridors concentrate demand as vehicle registrations cluster around port connectivity and commercial density.
- Diesel:Middle-distillate fuel with cetane rating specifications determining combustion efficiency in compression-ignition engines. Commercial trucking fleets along logistics corridors expand procurement volumes as freight intensity deepens across the Kingdom.
- LPG:Liquefied petroleum gas serving dual-fuel retrofits where fleet operators reduce per-kilometer energy costs through propane-butane blends.
- Ethanol:Oxygenate additive blended at low concentrations to meet volatility specifications, constrained by domestic production capacity and import logistics.
Today's leader: Diesel. Tomorrow's challenger: LPG.
End User:
Vehicle fleet composition determines octane and cetane specification requirements that refiners must certify against SASO benchmarks.
- Passenger Vehicles:Light-duty gasoline and diesel engines requiring Euro 5-equivalent sulfur content for warranty compliance. Eastern and central provinces concentrate registrations where Aldrees Petroleum maintains dense retail coverage.
- Commercial Trucks:Heavy-duty diesel powertrains dominating freight movement along the Riyadh-Jeddah corridor. Fleet operators centralize procurement through bunkering contracts that bypass retail margin structures.
- Buses:Municipal and intercity transport fleets with predictable route density enabling dedicated refueling infrastructure.
- Motorcycles:Two-wheeler segment with lower per-vehicle consumption but high unit volume in urban last-mile delivery services.
Commercial trucks anchor volume throughput. Passenger vehicles drive specification complexity.
Distribution Channel:
Channel selection determines working capital intensity and margin capture mechanisms for fuel marketers with varying upstream integration.
- Retail Stations:Fixed-site infrastructure capturing margin pools through convenience-store cross-subsidies. Eastern and central provinces concentrate network development where real estate access determines competitive position.
- Fleet Services:Dedicated bunkering and mobile refueling contracts serving logistics operators with predictable route density. This channel is expanding most quickly as corporate buyers consolidate procurement decisions.
- Wholesale:Bulk supply agreements to independent marketers and industrial consumers requiring ISO 9001-certified handling protocols.
- Online:Digital procurement platforms enabling price transparency and contract management for corporate accounts.
Retail stations defend current margin pools. Fleet services command the steepest expansion trajectory.
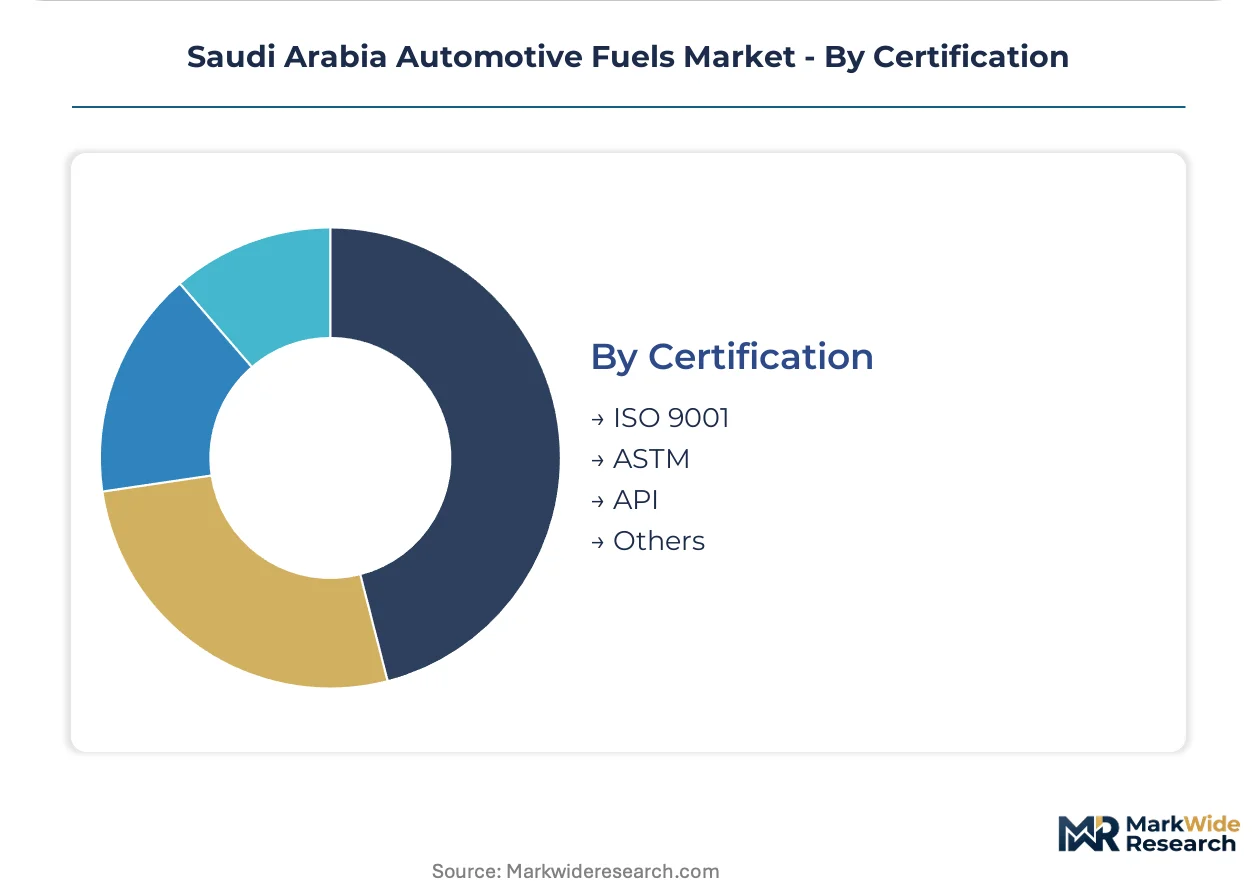
Certification:
Standard compliance determines import eligibility and domestic refinery offtake authorization under SASO enforcement frameworks.
- ISO 9001:Quality management system certification required for wholesale supply contracts and corporate procurement qualification.
- ASTM:American Society for Testing and Materials specifications governing fuel volatility and combustion performance parameters for imported formulations.
- API:American Petroleum Institute standards for lubricant and fuel quality benchmarks referenced in vehicle warranty documentation.
- Others:Supplementary certifications including SFDA additive safety approvals and SASO sulfur content labeling requirements.
ISO 9001 anchors operational credibility. ASTM specifications determine import market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical engineering talent clusters along the Gulf coast anchor downstream fuel production capacity. Refinery workforce density concentrates in the Eastern Province, while logistics specialists populate the Riyadh-Jeddah corridor. Distribution networks follow these human capital formations.
Eastern Province
Refinery complexes in Jubail and Ras Tanura process crude into gasoline and diesel for domestic distribution. SASO sulfur content mandates require continuous facility upgrades to maintain certification. The Dammam metropolitan area serves as the primary consolidation point for wholesale fuel movements westward toward Riyadh and the Red Sea coast.
Riyadh
Vehicle registration density in the capital region drives gasoline demand for passenger fleets and commercial light-duty vehicles. The Saudi Standards, Metrology and Quality Organization enforces octane labeling standards at retail stations across the metropolitan area. Corporate fleet operators in the Riyadh industrial zones negotiate direct bunkering contracts that bypass traditional retail channels.
Western Region
Jeddah's port connectivity attracts diesel-intensive logistics operations serving Red Sea trade routes. SFDA additive safety approvals determine which fuel formulations enter the market through import channels. The King Abdullah Economic City corridor hosts dedicated refueling infrastructure for long-haul trucking fleets operating between Jeddah and Dammam.
Tabuk
Euro 5-equivalent specifications propagate northward from Riyadh, opening retail station development opportunities in secondary urban centers. Domestic refinery certification timelines determine when specialty-grade fuels become available outside core demand zones. The Tabuk logistics corridor connects to the NEOM development zone, where construction equipment fleets require high-volume diesel procurement.
Saudi Arabia Automotive Fuels Market Competitive Landscape
Top-tier vendors anchor integrated refining and retail operations, while mid-tier distributors compete on station network density and fleet service contracts. The market structure concentrates around state-linked upstream players with captive feedstock access and independent marketers with geographic specialization. Two strategic archetypes dominate: vertically integrated refiners controlling yield structures and retail-focused operators capturing convenience-store cross-subsidies. Competitive moves center on secondary city station expansion and corporate bunkering contract capture.
Within the integrated refiner archetype, Saudi Aramco occupies a position exemplifying captive upstream-downstream coordination. Among independent retail specialists, Aldrees Petroleum and Transport Services Company and Petromin Corporation represent network-density competitors focused on eastern and central province coverage. TotalEnergies anchors the import-formulation tier, occupying a position tied to European-standard fuel certifications for warranty-compliant vehicle fleets.
| Leading Market Players |
|---|
| Saudi Aramco |
| Aldrees Petroleum and Transport Services Company |
| Saudi Automotive Services Co. |
| Petromin Corporation |
| J-Oil |
| Mazaya Fuel |
| TotalEnergies |
| ADNOC Distribution |
| NAFT Services Co. |
| Others |
Pricing and Supply Chain Analysis
Euro 5-equivalent sulfur mandates from the Saudi Standards, Metrology and Quality Organization gate qualified supply access and premium-tier pricing power. Refiners achieving SASO certification capture structural premiums while non-certified suppliers face inventory segregation costs and wholesale margin compression.
Pricing Analysis
Bundled fleet services versus unbundled retail pump sales define the pricing architecture. Three-tier pricing structure across premium, standard, and economy levels reflects octane certification grade and volume commitment scale. Cost compression in standard-grade gasoline intensifies because Saudi Aramco's integrated yield optimization floods the commodity tier. Fleet operators with bunkering contracts demonstrate lowest price sensitivity; independent retail buyers face highest exposure to pump-price volatility.
Supply Chain Analysis
Petrochemical engineering talent scarcity in Saudi Arabia's Eastern Province and skilled technician shortages in the Riyadh-Jeddah corridor constrain domestic specialty-grade production scaling. Crude feedstock draws from Saudi Aramco's captive upstream assets, while LPG blending components and fuel additive packages hinge on import channels. Single-source vulnerability concentrates around Saudi Aramco's refinery complex dominance. Distribution runs through wholesale consolidation points at Dammam and Jeddah before last-mile retail or fleet direct delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through convenience-store cross-subsidy replication and fleet service centralization capturing volume-based pricing premiums.
For Market Incumbents: Cement bunkering contract exclusivity along the Jeddah-Dammam logistics corridor to lock in freight-density volumes. Expand retail station networks into Tabuk and Hail before Euro 5-equivalent specifications fully propagate, securing real estate positions ahead of specialty-grade demand maturation.
For New Entrants and Emerging Players: SASO's tightening sulfur content ceilings in Saudi Arabia open a window for import-formulation specialists targeting European-standard vehicle warranty compliance. Target secondary cities with mobile bunkering units to bypass capital-intensive fixed-station requirements, leveraging technician partnerships for LPG retrofit service bundling.
For Investors and Strategic Acquirers: Roll-up economics work for regional retail station networks because fragmented independent operators lack SASO certification investment capacity. Mid-term viability centers on convenience-store revenue diversification and fleet channel migration. Watch for Saudi Aramco wholesale term sheet revisions as the inflection signal for independent marketer margin pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Retail Station Network Expansion | Dense eastern and central province coverage captures convenience-store cross-subsidy economics ahead of competitor entry. |
| Fleet Bunkering Contract Capture | Direct refinery offtake agreements with logistics operators displace fragmented retail purchasing along freight corridors. |
| LPG Dual-Fuel Infrastructure Buildout | Retrofit installation capacity addresses technician scarcity while locking in per-kilometer energy cost savings for fleet clients. |
| Euro 5-Equivalent Certification Investment | SASO compliance enables premium-tier pricing access and import substitution opportunities for domestic specialty-grade production. |
| Mobile Refueling Unit Deployment | On-site fleet tanks and distributed bunkering bypass fixed retail station capital requirements in secondary urban centers. |
Research Methodology
Bottom-up fuel consumption modeling reconciled against top-down refinery throughput tracking forms the analytical core of this study. Primary interviews with fuel procurement managers at commercial trucking fleets, retail station network operators, and Saudi Aramco downstream planners combined with secondary validation from SASO regulatory filings, customs import records, and vehicle registration databases. Triangulation across stakeholder inputs and statistical sources ensures segment-level accuracy.
Historical trendline analysis of diesel and gasoline demand patterns across fuel type, end user, and distribution channel dimensions established baseline growth trajectories. CAGRs were derived from regression-adjusted consumption projections incorporating logistics corridor freight intensity, Euro 5-equivalent specification propagation timelines, and LPG retrofit adoption curves. Forecast inputs include refinery upgrade completion schedules and corporate fleet procurement centralization rates.
Revisions become necessary when SASO regulatory enforcement intensity shifts, Saudi Aramco wholesale pricing term structures change, or alternative drivetrain penetration accelerates beyond baseline assumptions. Forecasts reflect documented modeling parameters and scenario-weighted probability assessments. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Diesel Fuel Water Separator Market
Fuels
Bituminous Coal Market
Fuels
North America LNG Bunkering Market
Fuels
Gasoline Market
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Oil Dispensing Stations Market
Fuels
United Kingdom Chemical Logistics Market
Fuels
Oil & Gas Lubricants Market
Fuels
Global Methane Hydrate Market
Fuels
United States Bunker Fuel Market
Fuels
India Liquified Petroleum Gas (LPG) Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Middle-East and Africa Bunker Fuel Market
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
Fuel Oxygenate Market