
 Middle-East and Africa Defense Aircraft Aviation Fuel Market | 2026-2036
Middle-East and Africa Defense Aircraft Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Defense Aircraft Aviation Fuel Market Foresight
Saudi Arabia's upstream refinery expansion along the Red Sea coast is reshaping regional supply topology for defense-grade aviation fuel. Saudi Arabian Oil Co anchors production scale through its Yanbu and Jubail complexes, while TotalEnergies SE leverages its downstream partnerships to secure long-term offtake agreements with air force procurement divisions. Shell plc competes on logistics density, operating dedicated military fuel terminals that sustain just-in-time delivery to dispersed airbases across the Arabian Peninsula.
Middle-East and Africa defense aircraft aviation fuel denotes refined kerosene-based formulations meeting strict flash point, freeze point, and thermal stability specifications for turbine-powered military aircraft, primarily serving propulsion and aerial refueling operations. Jet A-1 dominates volume flows given its universal NATO interoperability and superior cold-weather performance relative to Jet A, while fighter jet applications command premium margin pools due to combat-readiness storage requirements and accelerated consumption rates during sortie-intensive training cycles. Transport aircraft segments occupy stable demand territory, though UAV fueling infrastructure represents an emerging growth corridor as uncrewed platforms proliferate across reconnaissance and strike missions.
SFDA certification mandates and MOHAP fuel quality directives are tightening sulfur content thresholds and trace metal limits, compelling suppliers to upgrade hydrotreating capacity or risk exclusion from national defense tenders. REACH-aligned substance disclosure requirements, though originating in Europe, are influencing procurement specifications for multinational joint operations based in the region. Stakeholders must monitor how sovereign localization policies interact with international fuel standards, as domestic blending mandates could fragment procurement pools and reshape supplier qualification criteria without formal regulatory change.
Market Dynamics
Sovereign fuel localization mandates across Gulf Cooperation Council air forces are restructuring procurement hierarchies, with national oil companies capturing previously open tender volumes through domestic blending requirements and strategic stockpile obligations.
Growth Catalysts
- Fighter Jet Fleet Modernization:Aging Mirage and F-5 platforms across Gulf air forces are accelerating replacement cycles, with new acquisitions carrying stricter fuel specification clauses that favor certified Jet A-1 suppliers.
- SFDA Certification Tightening:Saudi Arabia's fuel quality protocols now mandate sub-30 ppm sulfur thresholds, disqualifying legacy suppliers and consolidating procurement pools around upgraded hydrotreating capacity.
- Aerial Refueling Infrastructure:Tanker fleet expansions in the UAE and Qatar are extending operational range requirements, creating dedicated demand streams for high-thermal-stability formulations.
Market Restraints
- Crude Slate Volatility:Middle Eastern sour crude differentials directly compress refining margins for defense-grade kerosene, exposing suppliers to feedstock cost swings without pass-through mechanisms in fixed military contracts.
- Refinery Concentration Risk:Over 70% of regional Jet A-1 production clusters along Saudi Arabia's Red Sea coast, creating single-point vulnerability for supply security planning across multiple air forces.
- Synthetic Fuel Substitution:Power-to-liquid and Fischer-Tropsch synthetic kerosene pathways are attracting R&D capital from sovereign wealth funds, threatening long-term demand capture for conventional refiners.
Strategic Opportunities
- East African Airbase Expansion:Djibouti and Kenya are hosting multinational expeditionary forces with limited indigenous fuel infrastructure, opening terminal and storage concession opportunities for logistics specialists.
- UAV Fueling Infrastructure:Uncrewed combat air vehicle proliferation across UAE and Saudi strike squadrons is creating demand for dispersed, automated refueling systems absent legacy tanker dependencies.
- MOHAP Green Procurement Incentives:The UAE's health and safety regulator is embedding carbon intensity metrics into defense fuel tenders, rewarding suppliers with integrated carbon capture or renewable blending capabilities.
Industry Challenges
- Specialized Storage Engineering:Combat-readiness fuel requires nitrogen blanketing and temperature-controlled underground caverns, demanding scarce civil-military construction expertise and extended commissioning timelines.
- Cross-Border Certification Alignment:NATO STANAG 3747 interoperability requirements conflict with emerging national blending mandates, forcing suppliers to maintain parallel quality management systems for joint operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Defense Aircraft Aviation Fuel Market |
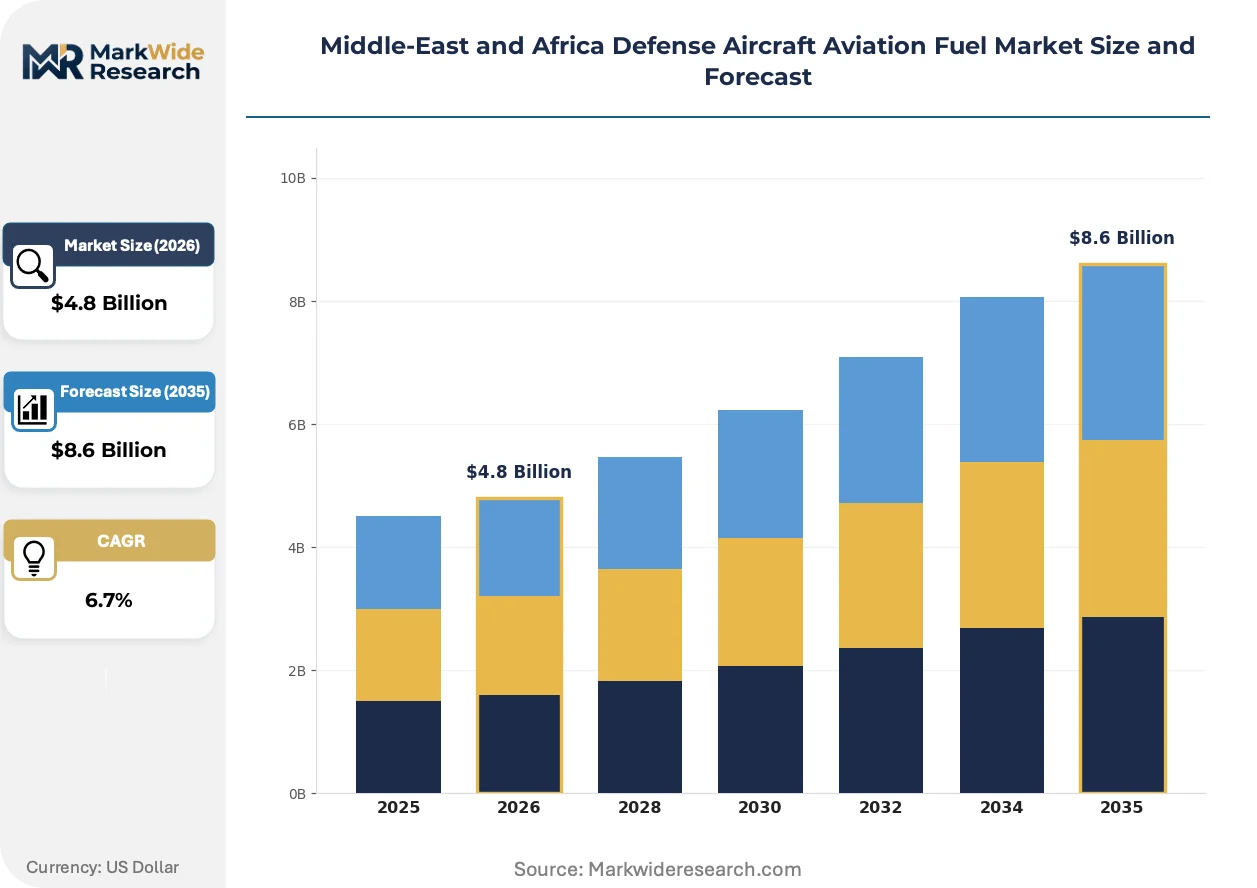
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Jet B, TS-1 Usage Type: Commercial, Military, Cargo, Aerial Refueling Distribution Channel: Direct Supply, Retail, Reseller, B2B Aircraft Type: Fighter Jets, Transport Aircraft, Helicopters, UAVs |
| Companies Covered | Abu Dhabi National Oil Company, World Fuel Services Corp, BP plc, Emirates National Oil Co Ltd, Saudi Arabian Oil Co, Shell plc, TotalEnergies SE, Chevron Corporation, Exxon Mobil Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Defense Aircraft Aviation Fuel Market Shifts & Advancements
Defense aviation fuel formulation is converging with adjacent energy sectors, as military procurement specifications absorb sustainability metrics and digital traceability requirements previously confined to commercial aviation.
Advanced hydrotreating catalysts are hybridizing conventional kerosene refining with bio-based feedstock co-processing. Saudi Aramco's Riyadh research center is piloting algae-derived lipids in Jet A-1 blends, targeting 10% renewable content without cold-flow degradation. This hybridizing approach preserves existing infrastructure while satisfying MOHAP's emerging low-carbon procurement criteria.
REACH-aligned substance disclosure protocols are migrating into Gulf defense procurement frameworks. SFDA now requires full material composition reporting for fuel additives and lubricity improvers, mirroring ECHA's SCIP database obligations. Suppliers without European compliance infrastructure face exclusion from multinational joint operation tenders based in the region.
Air force procurement divisions are consolidating fuel contracts under sovereign wealth fund vehicles. The UAE's Tawazun Council is bundling aviation fuel, ground vehicle diesel, and marine gasoil into single-source agreements with volume commitments spanning decade-long horizons. This concentration compresses supplier margins while demanding integrated logistics capabilities across multiple fuel grades and delivery modalities.
Middle-East and Africa Defense Aircraft Aviation Fuel Market Segmentation
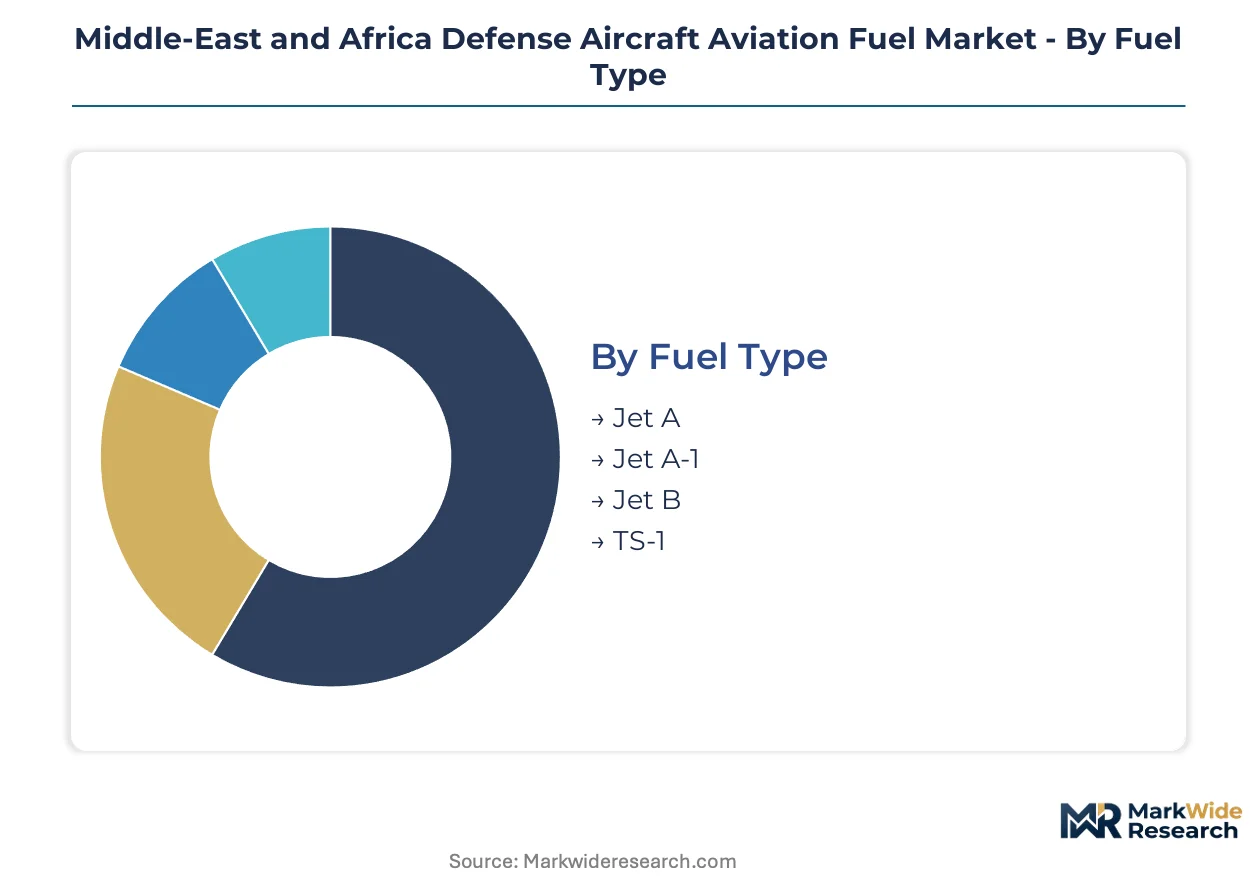
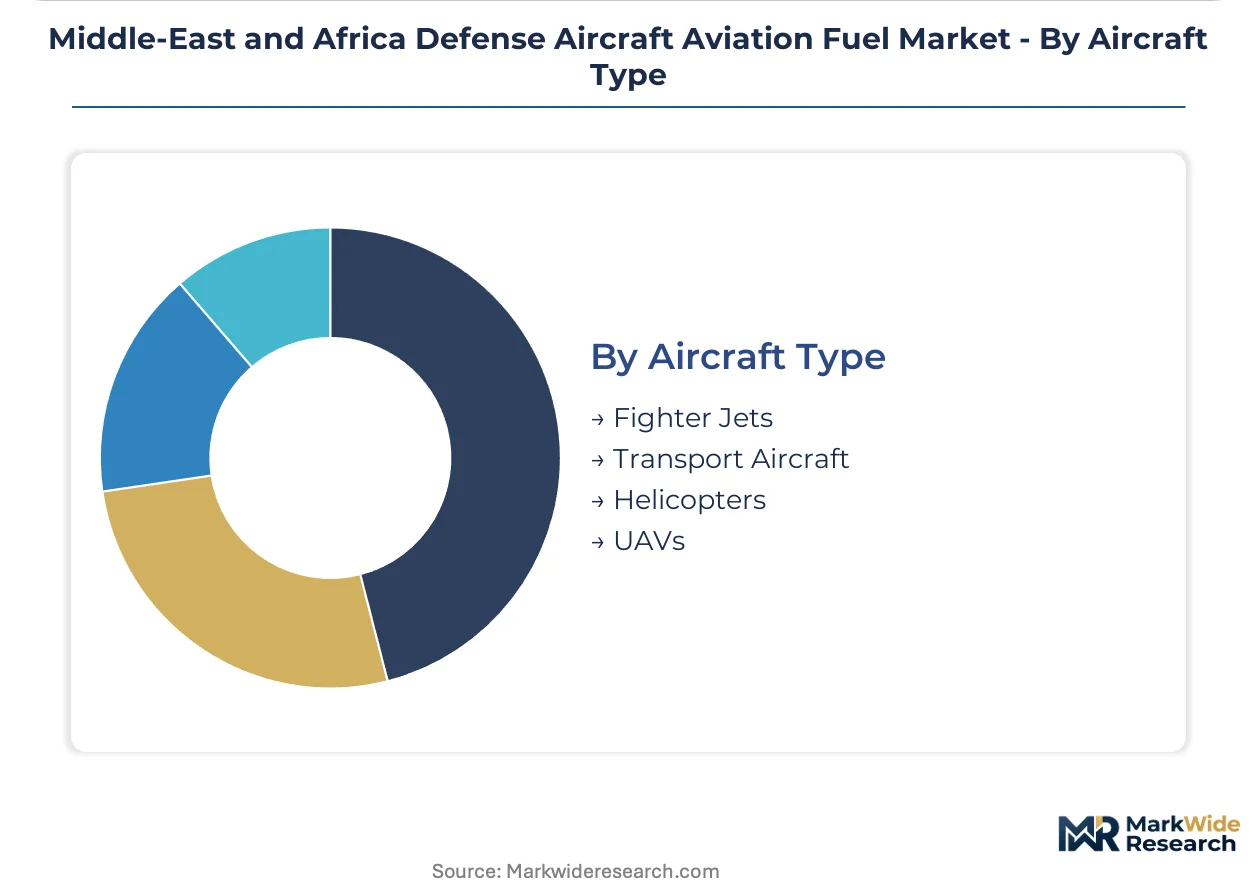
Military aviation fuel procurement in the Middle-East and Africa fragments across specification grades, operational applications, and supply modalities. Each dimension carries distinct margin profiles and certification burdens that reshape supplier qualification and contract structuring.
Fuel Type:
Specification grade determines NATO interoperability thresholds, cold-weather performance, and sulfur content compliance across regional air forces.
- Jet A-1:Refined kerosene with maximum freeze point of -47°C dominates Gulf Cooperation Council procurement. Saudi Arabia's SFDA mandates sub-30 ppm sulfur content, consolidating supply around Yanbu and Jubail hydrotreating capacity.
- Jet A:Higher freeze point of -40°C limits deployment to temperate zones. Egyptian and Moroccan air forces maintain blended stockpiles for domestic training sorties where thermal extremes are less severe.
- Jet B:Wide-cut gasoline-kerosene blend serves helicopter turboshaft engines in high-altitude operations. Limited volumes flow to Jordanian and Lebanese mountain-based rotary wings.
- TS-1:Russian-origin specification persists in Algerian and Iranian legacy fleets. Compatibility gaps with NATO aerial refueling infrastructure constrain joint operation deployment.
Jet A-1 commands the established base. The steepest expansion runs through TS-1 as former Soviet bloc operators modernize blending capacity.
Usage Type:
Operational application shapes storage engineering requirements, consumption velocity, and contract duration.
- Military:Combat-readiness mandates nitrogen-blanketed underground caverns with temperature control. UAE and Saudi fighter squadrons drive premium-margin procurement through accelerated training cycle intensity.
- Aerial Refueling:Tanker fleet expansions in Qatar and the UAE demand high-thermal-stability formulations for extended loiter operations. Dedicated demand streams bypass commercial aviation scheduling conflicts.
- Cargo:Transport aircraft segments occupy stable demand territory with predictable sortie patterns. Strategic airlift contracts favor multi-year volume commitments.
- Commercial:Dual-use military-civil infrastructure at Dubai and Jeddah creates shared storage economics. Defense procurement divisions leverage commercial terminal access for cost efficiency.
Military applications anchor procurement volume. Aerial refueling climbs fastest as regional tanker capabilities extend operational reach.
Distribution Channel:
Supply modality determines working capital intensity, certification custody transfer points, and logistics integration depth.
- Direct Supply:National oil companies deliver from refinery gate to airbase storage. Saudi Aramco and ADNOC capture sovereign volumes through domestic blending mandates.
- B2B:Integrated logistics providers bundle aviation fuel with ground vehicle diesel and marine gasoil. Tawazun Council consolidated contracts compress margins while demanding multi-grade capability.
- Reseller:Independent traders fill supply gaps in East African expeditionary bases. Djibouti and Kenya host concessionaires with limited indigenous infrastructure.
- Retail:Civil aviation terminal access supports dispersed training locations. Secondary airfields in Oman and Bahrain rely on commercial apron fueling.
Direct supply dominates sovereign procurement. B2B channels expand most quickly under wealth fund consolidation.
Aircraft Type:
Platform characteristics dictate fuel consumption rates, storage security tiers, and refueling infrastructure automation.
- Fighter Jets:High-thrust turbofans burn premium-grade Jet A-1 at accelerated rates during afterburner deployment. Combat-readiness storage requirements and sortie-intensive training cycles command margin premiums.
- UAVs:Uncrewed combat air vehicle proliferation across UAE and Saudi strike squadrons creates demand for dispersed automated refueling. Legacy tanker dependencies erode as drone-specific infrastructure deploys.
- Transport Aircraft:Strategic airlifters operate on predictable schedules with bulk storage efficiency. C-130 and A400M fleets stabilize demand forecasting.
- Helicopters:Rotary-wing platforms in mountainous Jordan and Lebanon require Jet B for cold-start reliability. Volume concentration remains fragmented across small-unit deployments.
Fighter jets anchor procurement value. UAV infrastructure gains share fastest as autonomous platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jet A-1 production clusters along Saudi Arabia's Red Sea coast supply over seventy percent of regional defense aviation fuel, creating geographic concentration that shapes procurement security calculations across Gulf Cooperation Council air forces.
Saudi Arabia
Fighter jet fleet modernization under Vision 2030 drives sovereign fuel procurement at scale. SFDA certification mandates now require sub-30 ppm sulfur thresholds, disqualifying legacy suppliers without upgraded hydrotreating capacity. Yanbu and Jubail refinery complexes anchor production scale for domestic and export defense volumes.
United Arab Emirates
Tanker fleet expansions and UAV proliferation create diversified demand streams for high-thermal-stability formulations. MOHAP fuel quality directives are embedding carbon intensity metrics into defense tenders, rewarding suppliers with integrated renewable blending capabilities. Tawazun Council consolidated contracts bundle aviation fuel with multi-grade logistics across Abu Dhabi and Dubai military infrastructure.
Qatar
Aerial refueling infrastructure investments extend operational range requirements for regional strike missions. The national oil company captures sovereign volumes through domestic blending mandates tied to strategic stockpile obligations. Al Udeid Air Base hosts multinational expeditionary forces with dedicated high-readiness fuel storage engineering.
Egypt
Legacy F-16 and Rafale fleets operate on blended Jet A stockpiles for domestic training where thermal extremes are less severe. The country's national petroleum regulator maintains parallel quality systems for NATO interoperability and national specifications. Cairo and Alexandria clusters concentrate civil-military terminal access for cost-efficient procurement.
Israel
Combat-readiness storage requirements command premium-margin procurement through accelerated training cycle intensity. The national defense procurement authority maintains strict additive disclosure protocols aligned with emerging multinational standards. Southern district airbases leverage dispersed underground cavern engineering for strategic fuel security.
Middle-East and Africa Defense Aircraft Aviation Fuel Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fuel formulation and logistics architecture. National oil companies capture previously open tender volumes through sovereign localization mandates, compressing margins for international traders. Two strategic archetypes dominate: state-backed refiners with captive upstream supply and integrated logistics providers bundling multi-grade fuel contracts. Competitive moves concentrate on long-term offtake agreements and terminal concession acquisitions in expeditionary base locations.
Within the state-backed refiner tier, Saudi Arabian Oil Co and Abu Dhabi National Oil Company represent sovereign supply anchors with integrated Red Sea and Arabian Gulf production complexes. Shell plc occupies a position among logistics-integrated multinationals operating dedicated military fuel terminals across the Peninsula. TotalEnergies SE exemplifies the downstream partnership archetype securing decade-spanning volume commitments with air force procurement divisions.
| Leading Market Players |
|---|
| Abu Dhabi National Oil Company |
| World Fuel Services Corp |
| BP plc |
| Emirates National Oil Co Ltd |
| Saudi Arabian Oil Co |
| Shell plc |
| TotalEnergies SE |
| Chevron Corporation |
| Exxon Mobil Corporation |
| Others |
Supply & Pricing Matrix
Yanbu and Jubail refinery clusters along Saudi Arabia's Red Sea coast concentrate over seventy percent of regional Jet A-1 hydrotreating capacity, granting national oil companies substantial leverage in contract negotiations with Gulf air force procurement divisions. This geographic consolidation compresses margins for international traders while enabling sovereign suppliers to enforce long-term offtake terms with limited price renegotiation windows.
Pricing Analysis
SFDA certification mandates dictate the pricing tier structure across Middle-East defense aviation fuel procurement, separating premium-grade Jet A-1 with sub-30 ppm sulfur content from standard formulations. Price differentiation hinges on certification grade and volume scale, with fighter squadron contracts commanding premiums for combat-readiness storage engineering. Cost compression in standard-tier supply is intensifying because Tawazun Council consolidated contracts bundle multi-grade logistics under decade-spanning commitments. National oil companies exhibit lowest price sensitivity due to captive upstream supply, while independent resellers serving East African expeditionary bases face acute margin pressure.
Supply Chain Analysis
Export-control regimes governing military-grade fuel additives and thermal stability improvers limit technology flows to qualified suppliers with NATO STANAG 3747 compliance infrastructure. Geographic supply concentration centers on Saudi Arabia, the United Arab Emirates, and Qatar, where national oil companies draw from captive crude slates and integrated hydrotreating assets. Raw material dependencies rest on Middle Eastern sour crude differentials, specialized hydrotreating catalysts, and nitrogen blanketing equipment for underground cavern engineering. Single-source vulnerability pervades the Red Sea production corridor. Distribution runs through direct refinery-to-airbase pipelines, B2B integrated logistics contracts, and commercial terminal access at dual-use civil-military facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of civil-military construction expertise for nitrogen-blanketed underground fuel caverns constrains supply-side expansion regardless of capital availability. This capability gap rewards early movers who secure engineering partnerships before competitor lock-in.
For Market Incumbents: Entrench market position by securing exclusive terminal concessions at Djibouti and Kenyan expeditionary bases before infrastructure gaps close. Deepen backward integration into hydrotreating catalyst supply through partnerships with specialty chemical producers. Synthetic fuel substitution threats from sovereign wealth fund R&D programs demand accelerated renewable blending pilot programs to maintain certification relevance. For New Entrants and Emerging Players: Establish a beachhead in UAV automated refueling infrastructure across UAE and Saudi strike squadrons, where legacy tanker dependencies are eroding fastest. Target East African reseller channels serving multinational expeditionary forces with limited indigenous storage capacity. A go-to-market angle emphasizing REACH-aligned additive disclosure protocols opens multinational joint operation tenders previously closed to non-compliant suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-capture play because fuel logistics integration depth determines contract renewals under wealth fund consolidation. Acquisition targets should display integrated multi-grade capability spanning aviation fuel, ground diesel, and marine gasoil. The signal to watch is MOHAP carbon intensity metric adoption velocity, which would force conventional refiner write-downs and reward early renewable blenders.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreating Capacity Upgrade | SFDA sub-30 ppm sulfur mandates disqualify legacy suppliers without refinery investment. |
| East African Terminal Concession | Djibouti and Kenya host expeditionary forces with limited indigenous fuel infrastructure. |
| Renewable Blending Pilot Program | MOHAP carbon intensity metrics reward suppliers with integrated bio-kerosene capabilities. |
| UAV Automated Refueling Infrastructure | Dispersed autonomous platforms across UAE and Saudi squadrons erode legacy tanker dependencies. |
| REACH-Aligned Compliance Infrastructure | Additive disclosure protocols open multinational joint operation tenders to qualified suppliers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and refinery capacity disclosures through bottom-up and top-down triangulation. Primary interviews engaged fuel supply specialists at national oil companies, air force procurement officers, terminal operations managers, and hydrotreating catalyst technical directors. Secondary validation drew from SFDA certification bulletins, MOHAP fuel quality directives, NATO STANAG documentation, and sovereign wealth fund R&D disclosures. Cross-referencing procurement contract terms with production capacity data ensured volume estimates align with documented offtake commitments.
Forecast inputs incorporate fuel type segmentation by specification grade, usage type by operational application, distribution channel by supply modality, and aircraft type by platform characteristics across the analysis window. CAGRs derive from trend extrapolation of fleet modernization cycles, certification tightening trajectories, and aerial refueling infrastructure deployment schedules. Industry-specific inputs include fighter jet replacement timelines, UAV proliferation rates, and synthetic fuel substitution R&D capital flows from sovereign wealth funds.
Sensitivities concentrate around crude slate volatility, refinery concentration risk along the Red Sea corridor, and synthetic fuel pathway commercialization timelines. Forecasts reflect assumptions regarding SFDA and MOHAP regulatory stability, NATO interoperability requirement continuity, and sovereign localization policy persistence. Material shifts in sulfur content thresholds, carbon intensity procurement criteria, or aerial refueling infrastructure investment priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Saudi Arabia Chemical Logistics Market
Fuels
Carbonizers Market
Fuels
Coal Briquette Box Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
Middle-East and Africa Bunker Fuel Market
Fuels
Industrial Fuel Filter Market
Fuels
Europe Coal Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
Canada Bunker Fuel Market
Fuels
United States Coal Market
Fuels
Solid Recovered Fuel Market
Fuels
No.4 Fuel Oil Market
Fuels
Italy Automotive Engine Oils Market
Fuels
Global Wood Gas Generator Market
Fuels
Turbine Drip Oil Market