
 North America Wood Pellet Market | 2026-2036
North America Wood Pellet Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wood Pellet Market Analytics
Residential heating is hardening as the dominant end-use vertical, displacing traditional fossil fuel systems across rural and semi-urban communities. Enviva Partners LP leverages its deep-water terminal network to anchor Atlantic Coast export flows. Drax Group PLC sustains utility-scale procurement relationships through long-term offtake structures. Lignetics Inc. specializes in retail-bagged distribution, controlling shelf presence across home improvement channels.
Wood pellets are densified biomass fuel cylinders, typically six to eight millimeters in diameter and ten to thirty millimeters in length, manufactured through hammer-milling, drying, and extrusion under high mechanical pressure. They serve as a drop-in combustion fuel for stoves, boilers, and industrial furnaces requiring standardized calorific output and low moisture content. Industrial pellets lead volume throughput, while premium pellets command higher margin pools due to stricter ash and moisture specifications. Heating pellets occupy mature residential channels, and power generation represents the fastest-growing application as utilities phase down coal firing.
The US EPA regulates residential wood heater emissions under New Source Performance Standards, while Canada's CSA B415.1 standard governs pellet stove efficiency and safety certification. State-level renewable portfolio standards in Maine, New Hampshire, and Vermont create direct procurement incentives for biomass thermal systems. Stakeholders must monitor how evolving federal biomass carbon accounting rules reshape power generation eligibility under clean energy procurement frameworks.
Market Dynamics
The US EPA's New Source Performance Standards for residential wood heaters are compressing particulate emissions thresholds, forcing stove manufacturers and fuel suppliers into simultaneous equipment and formulation upgrades across cold-climate states.
Growth Catalysts
- Fuel-switching mandates:State renewable portfolio standards in Maine, New Hampshire, and Vermont create direct procurement incentives for biomass thermal systems displacing oil-fired infrastructure.
- CSA B415.1 certification:Canada's efficiency and safety standard for pellet stoves accelerates retail channel penetration by reducing consumer purchase friction through verified performance claims.
- Deep-water terminal access:Atlantic Coast port infrastructure enables cost-competitive export flows to European utility buyers seeking coal displacement feedstock.
Market Restraints
- Sawdust supply concentration:Pellet production depends on residuals from lumber milling concentrated in the US Southeast, exposing feedstock costs to housing construction cyclicality.
- Natural gas substitution:Pipeline expansion in the US Northeast threatens residential heating pellet demand where gas distribution reaches rural and semi-urban communities.
- Moisture specification limits:Premium pellet certification requires sub-ten-percent moisture content, constraining production economics for smaller mills lacking advanced drying capacity.
Strategic Opportunities
- Underpenetrated Canadian Prairies:Manitoba and Saskatchewan heating markets remain dominated by propane and electric resistance, creating white space for pellet stove retail expansion.
- Industrial co-firing contracts:US utilities facing coal phase-down deadlines seek long-term offtake agreements for utility-grade pellets meeting strict grindability and ash specifications.
- Bagged retail channel innovation:Home improvement and farm supply chains represent underdeveloped distribution for premium heating pellets outside existing Northeast strongholds.
Industry Challenges
- Combustion engineering talent scarcity:Stove manufacturers face recruitment gaps for emissions control specialists capable of meeting EPA Phase III certification timelines.
- Production scale-up capital intensity:Greenfield pellet plants require drying and densification equipment investments that strain mid-cap producer balance sheets.
- Federal biomass carbon accounting uncertainty:Pending rulemaking from US EPA on biogenic CO2 measurement threatens power generation eligibility under state clean energy procurement frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wood Pellet Market |
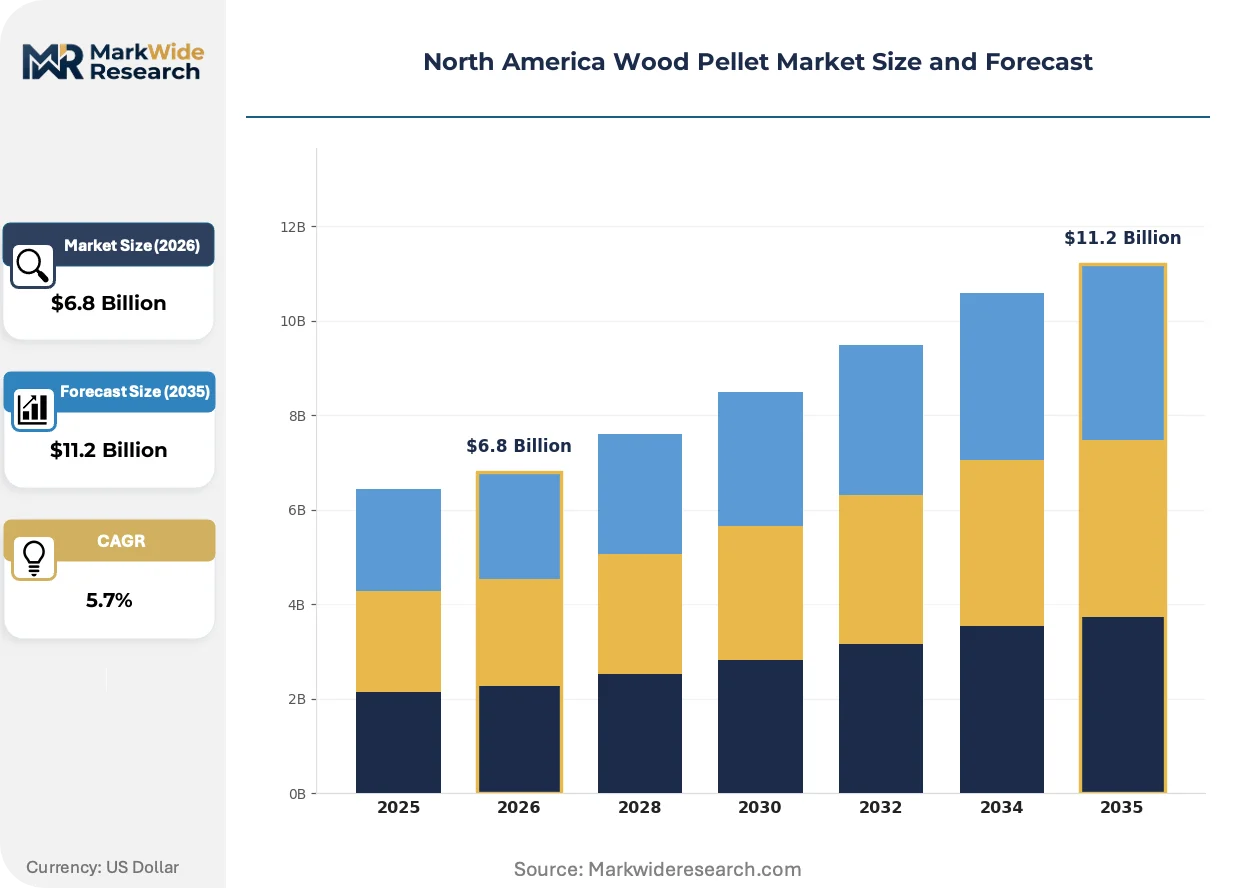
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heating Pellets, Animal Bedding Pellets, Industrial Pellets, Premium Pellets Distribution Channel: Retail, Wholesale, E-commerce, Direct Sales End User: Residential Users, Commercial Users, Industrial Facilities, Power Generation Application: Heating, Bioenergy, Manufacturing, Animal Feed |
| Companies Covered | Enviva Partners LP, Drax Group PLC, AS Graanul Invest, Fram Renewable Fuels LLC, Lignetics Inc., The Westervelt Company Inc., Highland Pellets LLC, Pinnacle Renewable Energy, Energy Pellets of America LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wood Pellet Market Evolving Landscape
Torrefaction and advanced densification processes are reshaping fuel quality hierarchies, while regulatory pressure on residential emissions intensifies stove technology turnover.
Pellet stove automation is converging with smart home energy management platforms. Manufacturers now integrate WiFi-enabled combustion controls that optimize burn rates against real-time electricity pricing. Residential adopters in Vermont and New Hampshire are deploying these systems at accelerating rates. The technology is converging with utility demand-response programs, compressing the payback period for high-efficiency stove investments.
The US EPA's New Source Performance Standards Phase III tightens particulate emissions limits for cordwood and pellet appliances. Stove manufacturers must redesign combustion chambers and catalytic after-treatment systems to achieve sub-two-gram-per-hour outputs. The residential heating segment faces the steepest compliance burden, with certification timelines extending eighteen to twenty-four months for new model introductions.
Homeowners are consolidating fuel purchasing around certified premium grades with guaranteed ash and moisture specifications. Bulk delivery subscriptions are displacing seasonal bagged purchases in established Northeast markets. This pattern concentrates most visibly in Maine, where heating degree-day exposure and existing oil boiler infrastructure create favorable economics for pellet central heating conversions.
North America Wood Pellet Market Segmentation
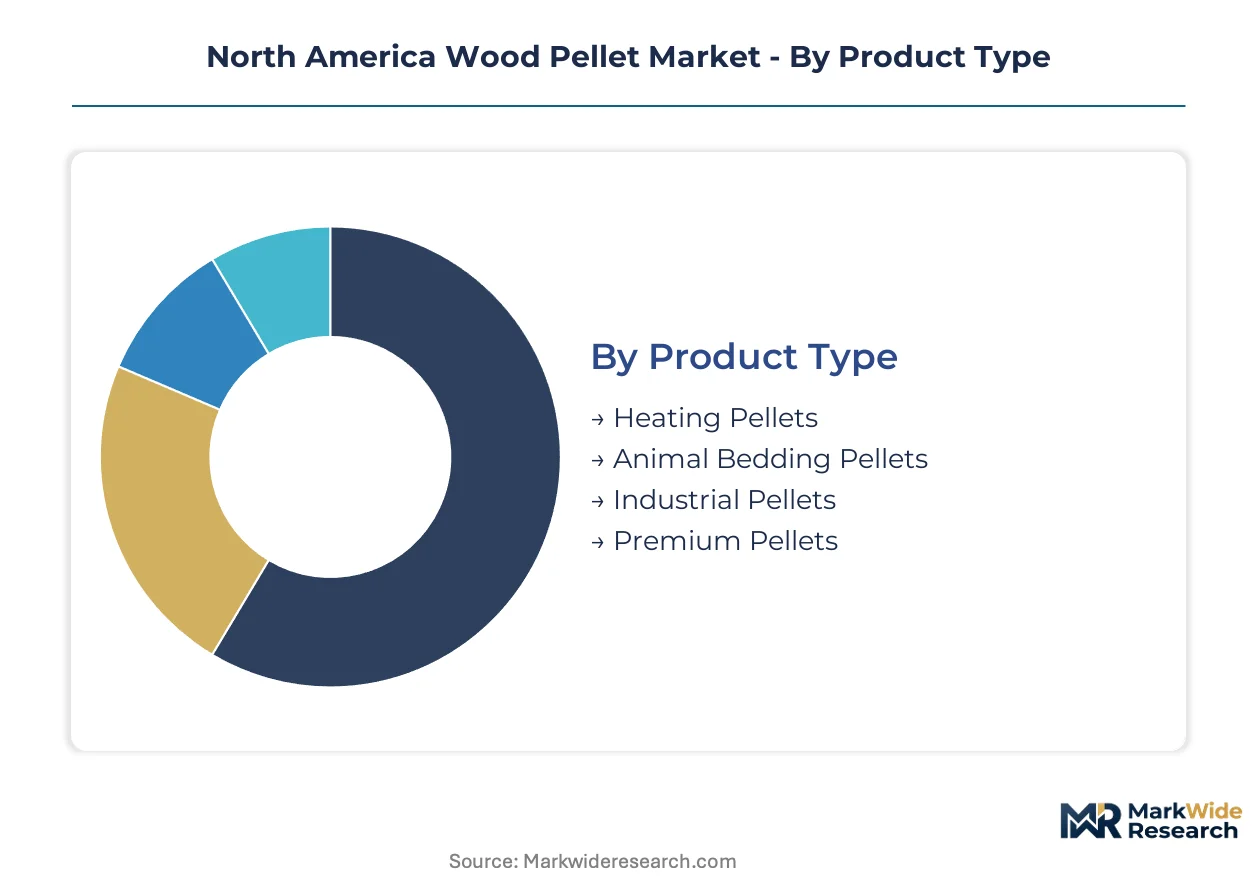
Wood pellet segmentation reveals divergent capital requirements across production tiers. Drying equipment, densification presses, and certification testing create steep barriers that concentrate supply among scale-capable operators while leaving niche segments fragmented.
Product Type:
Capital intensity peaks with moisture-control infrastructure and certification laboratory investments, separating industrial-scale producers from regional mills.
- Industrial Pellets:Utility-grade cylinders manufactured to strict grindability and ash specifications for co-firing and dedicated biomass power. Drax Group and Enviva anchor procurement in the US Southeast and Atlantic Canada, where deep-water terminals enable European export flows. This segment demands the heaviest upfront investment in rotary dryers and automated densification lines.
- Premium Pellets:Sub-ten-percent moisture content fuel certified for low-ash, high-calorific residential and commercial heating. Maine, New Hampshire, and Vermont households drive demand through bulk delivery subscriptions displacing oil-fired systems. Mills lacking advanced drying capacity cannot meet certification thresholds.
- Heating Pellets:Standard-grade residential fuel distributed through retail bagged channels across cold-climate states.
- Animal Bedding Pellets:Absorbent, low-dust formulations serving equine and poultry operations in agricultural regions.
Industrial pellets absorb the bulk of installed capacity; premium pellets are expanding most quickly as heating-degree-day exposure and fuel-switching economics harden in the Northeast.
Distribution Channel:
Channel selection determines working capital intensity and customer acquisition cost structures, with bulk logistics favoring integrated operators over independent brands.
- Wholesale:Bulk truck and rail delivery to central heating distributors, agricultural supply cooperatives, and utility fuel yards. The US Northeast and Canadian Maritimes concentrate volume through established heating oil infrastructure conversion. Long-term offtake contracts reduce price volatility exposure for mill operators.
- Retail:Bagged product placement across home improvement chains, farm supply stores, and independent hearth dealers. Lignetics controls shelf presence through dedicated retail partnerships, capturing consumer preference for verified CSA B415.1 stove compatibility. Working capital demands concentrate in inventory carrying costs and promotional slotting fees.
- Direct Sales:Mill-to-consumer bulk delivery subscriptions bypassing intermediary margins in established heating markets.
- E-commerce:Emerging channel for specialty grades and stove accessories with limited tonnage penetration.
Wholesale channels dominate volume throughput; direct sales are climbing the fastest as subscription models consolidate fuel purchasing in Maine and Vermont.
End User:
User segmentation maps to equipment investment cycles and regulatory compliance burdens, with utilities facing the steepest procurement standard evolution.
- Power Generation:Utility-scale biomass plants and coal co-firing facilities procuring under long-term supply agreements. US EPA biogenic carbon accounting uncertainty threatens eligibility under state renewable portfolio standards, compressing contract tenors. Drax maintains offtake structures through dedicated terminal access.
- Residential Users:Single-family and multi-family households converting oil-fired boilers to pellet central heating or installing standalone stoves. Vermont and New Hampshire lead penetration rates as electricity pricing volatility and EPA Phase III stove standards accelerate equipment turnover.
- Industrial Facilities:Manufacturing plants deploying biomass thermal for process heat and space conditioning.
- Commercial Users:Schools, hospitals, and municipal buildings utilizing pellet boilers for district heating.
Residential users command the largest installed base; power generation shows the steepest expansion trajectory as coal phase-down deadlines approach.
Application:
Application segmentation tracks calorific requirement intensity and feedstock specification divergence, with bioenergy demanding the most uniform fuel quality.
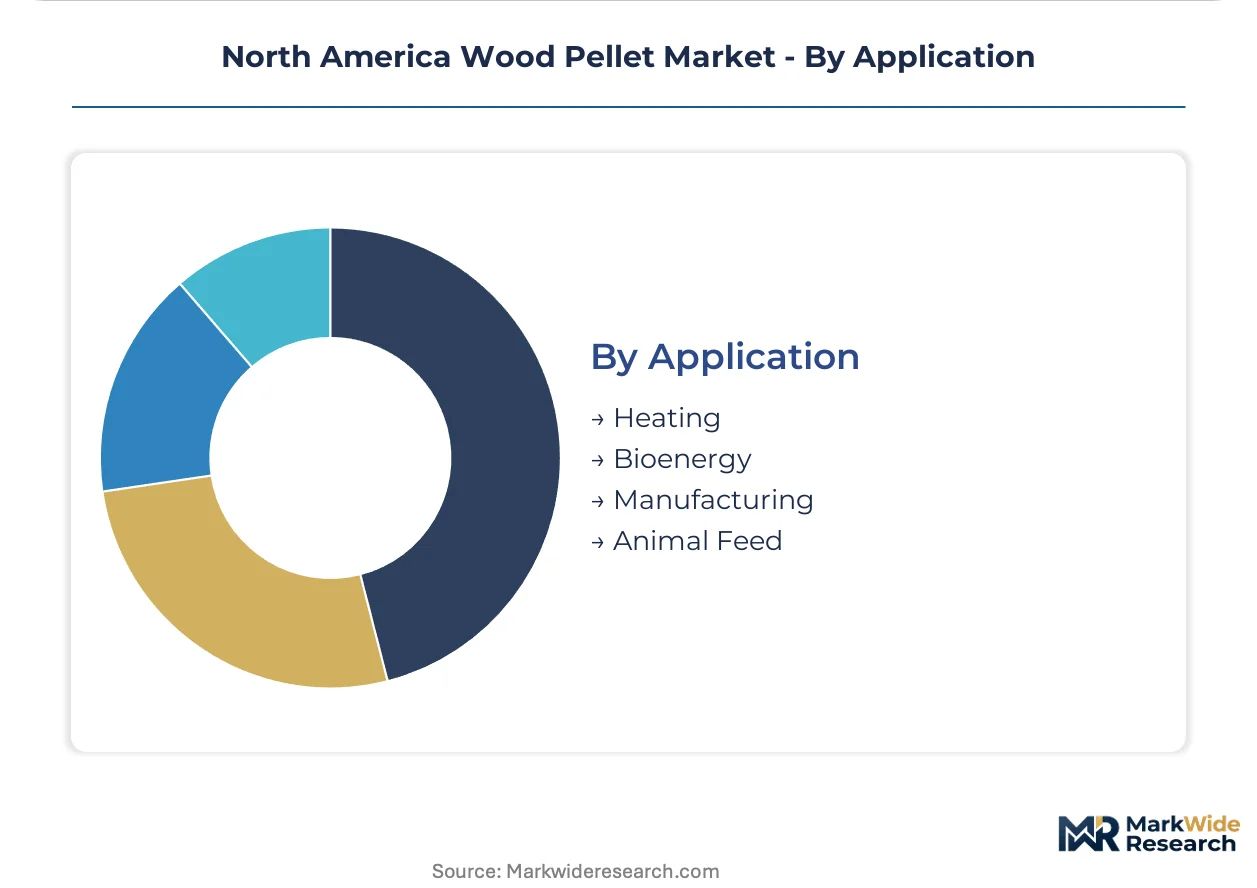
- Heating:Space conditioning and domestic hot water production across residential, commercial, and institutional buildings. The US Northeast and Canadian cold-climate provinces concentrate demand where heating degree-day exposure exceeds three thousand annually. Bulk delivery infrastructure and automated stove controls are compressing payback periods for system conversions.
- Bioenergy:Electricity generation and combined heat-and-power applications requiring grindability-standardized fuel for pulverized coal injection compatibility. European utility buyers drive Atlantic Coast export demand through coal displacement mandates. Torrefaction and advanced densification processes are reshaping fuel quality hierarchies for this segment.
- Manufacturing:Process heat for lumber drying, food processing, and other industrial thermal applications.
- Animal Feed:Nutritional pellet formulations for livestock and aquaculture using distinct feedstock bases.
Heating applications anchor current demand; bioenergy is gaining share fastest as torrefaction technology matures and export terminal capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomass energy zones in the US Southeast and Canadian Maritimes concentrate production capacity through targeted tax abatements and renewable energy credits. State-level renewable portfolio standards and provincial carbon pricing frameworks are reshaping demand geography across the continent.
United States
Maine, New Hampshire, and Vermont households drive residential heating conversions as heating oil prices and electricity volatility harden fuel-switching economics. The US EPA's New Source Performance Standards Phase III tightens particulate emissions thresholds for pellet stoves. The US Southeast concentrates industrial pellet milling around lumber residuals, with deep-water terminal access enabling Atlantic Coast export flows.
Canada
British Columbia and Quebec anchor utility-grade pellet production through abundant forestry residuals and established Pacific and Atlantic export corridors. CSA B415.1 certification standards govern pellet stove efficiency and safety, accelerating retail channel penetration. The Prairie Provinces of Manitoba and Saskatchewan remain underpenetrated heating markets where propane and electric resistance dominate.
Mexico
Industrial process heat applications in northern border states are testing biomass thermal systems as natural gas price volatility compresses manufacturing margins. The country's national energy regulator oversees renewable energy certificate frameworks that could include biomass thermal eligibility. Sonora and Chihuahua industrial corridors house pilot pellet boiler installations at food processing and lumber drying facilities.
North America Wood Pellet Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated terminal operators commanding utility procurement while regional mills serve retail heating channels. The market structures around three tiers: deep-water terminal operators with European offtake relationships, mid-cap producers with regional wholesale networks, and specialty bagged-product distributors. Strategic moves concentrate on terminal access negotiations, long-term utility contracting, and retail shelf-space expansion.
Among Atlantic Coast terminal operators, Enviva Partners LP and Drax Group PLC exemplify the integrated utility-supply archetype through dedicated export infrastructure. Lignetics Inc. occupies a position within the retail-specialist tier, anchoring bagged-product distribution across home improvement channels. These three entities represent divergent scale and channel strategies without implying specific market share or operational metrics.
| Leading Market Players |
|---|
| Enviva Partners LP |
| Drax Group PLC |
| AS Graanul Invest |
| Fram Renewable Fuels LLC |
| Lignetics Inc. |
| The Westervelt Company Inc. |
| Highland Pellets LLC |
| Pinnacle Renewable Energy |
| Energy Pellets of America LLC |
| Others |
Value Network & Pricing Analysis
Torrefaction technology maturation is compressing production economics for premium-grade fuel while simultaneously concentrating supply among mills with capital-intensive drying infrastructure. This dual effect hardens price stratification between certified premium pellets and standard heating grades across North American markets.
Pricing Analysis
Short lead-time premiums dominate spot procurement dynamics, with bulk subscription contracts commanding five to fifteen percent discounts against emergency winter deliveries. Three-tier pricing structure across premium, standard, and economy levels reflects moisture certification thresholds and ash content guarantees. Price differentiation rests on CSA B415.1 stove compatibility verification and guaranteed sub-ten-percent moisture specification. Residential buyers in Vermont and New Hampshire show highest price sensitivity due to heating oil parity calculations, while European utility offtake agreements demonstrate lowest sensitivity given coal displacement mandates.
Supply Chain Analysis
CSA B415.1 and EPA New Source Performance Standards certification gating restricts qualified supplier pools to mills with laboratory testing partnerships and emissions-verified stove relationships. Sawdust feedstock concentrates in the US Southeast, British Columbia, and Quebec where lumber milling residuals anchor production. Raw material dependencies center on housing construction cyclicality, timber harvest schedules, and pulp mill competition for residuals. Single-source vulnerability runs through deep-water terminal access for Atlantic Coast export flows. Distribution runs through bulk truck and rail networks to heating distributors, with bagged retail placement commanding higher working capital intensity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced drying capacity scarcity props pricing power for certified premium producers while constraining supply response to demand surges in cold-climate heating markets.
For Market Incumbents: Anchor terminal access negotiations through long-term European utility offtake structures before competing Atlantic Coast capacity comes online. Defend margin position by backward integration into sawdust preprocessing and captive drying infrastructure. EPA Phase III stove certification timelines create eighteen-month product development windows that favor established R&D programs over mid-cap challengers. For New Entrants and Emerging Players: Agricultural supply cooperatives in Manitoba and Saskatchewan represent an underserved buyer archetype with propane displacement economics and limited existing pellet stove penetration. White space concentrates in farm supply channel bagged distribution outside established Northeast strongholds. Pursue private-label manufacturing partnerships with regional heating oil distributors converting infrastructure to biomass thermal systems. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap producers possessing rotary dryer assets and uncontracted capacity given CSA B415.1 certification scarcity and European export demand growth. Five-to-ten-year viability favors integrated operators with terminal-adjacent milling locations. Watch EPA biogenic carbon accounting rulemaking as the inflection signal for utility-scale power generation contract tenors.| Strategic Initiative | Industry Significance |
|---|---|
| Deep-Water Terminal Access Negotiation | Atlantic Coast port contracts enable cost-competitive European utility offtake through Drax and Enviva procurement structures. |
| CSA B415.1 Certification Investment | Verified stove compatibility reduces consumer purchase friction and commands retail shelf placement premiums. |
| Backward Integration into Sawdust Preprocessing | Captive feedstock supply insulates margin pressure from housing construction cyclicality in US Southeast. |
| Bulk Delivery Subscription Platform | Direct mill-to-consumer models bypass intermediary margins and consolidate fuel purchasing in Maine and Vermont. |
| Torrefaction Technology Licensing | Advanced densification processes reshape fuel quality hierarchies for bioenergy applications requiring grindability standardization. |
Research Methodology
Document review covered EIA biomass consumption data, FERC utility fuel procurement filings, and CSA B415.1 certification registries, complemented by interviews with pellet mill operations directors, heating oil distributor procurement leads, EPA emissions compliance officers, and European utility fuel buyers. Secondary validation drew from customs export records, state renewable portfolio standard filings, and lumber industry production surveys. Bottom-up capacity modeling triangulated against top-down demand segmentation across the projection horizon.
Market sizing outputs segmented by product grade tier, end-use application, distribution channel structure, and regional regulatory framework throughout the forecast period. CAGRs derived from regression analysis against heating degree-day exposure, oil-to-gas price spreads, and coal phase-down policy trajectories. Key inputs included EPA Phase III certification timeline assumptions and European biomass sustainability criteria evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to federal biomass carbon accounting rulemaking and natural gas pipeline expansion in rural Northeast communities. Projections reflect assumptions regarding sawdust supply availability and terminal capacity utilization. A model refresh is warranted upon material change in EPA biogenic CO2 measurement methodology or Atlantic Coast port infrastructure commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Industrial Fuel Filter Market
Fuels
Turbine Drip Oil Market
Fuels
Diesel Fuel Water Separator Market
Fuels
Aviation Fuel Additives Market
Fuels
Oil Dispensing Stations Market
Fuels
China Coal Market
Fuels
Global Turbine Oil Market
Fuels
Tire Derived Fuel Market
Fuels
Gas Pooling Mechanism Market
Fuels
Fuel Oxygenate Market
Fuels
South America Aviation Fuel Market
Fuels
Chafing Fuel Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Fuel Conditioning System Market
Fuels
Gas to Liquid (GTL) Market
Fuels
Bituminous Coal Market