
 City Gas Distribution Market | 2026-2036
City Gas Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
City Gas Distribution Market Outlook
Maintenance and metering service contracts are shifting from one-time installation revenue to recurring subscription models across city gas distribution networks. Enbridge Inc. leverages its pipeline integrity management programs to secure long-term operational contracts in North American urban centers. Gujarat Gas Limited anchors its competitiveness through captive LNG terminal access and compressed natural gas station density across western India. Adani Total Gas Ltd. differentiates via smart city integration and digital customer platforms in emerging Indian metropolitan regions.
City gas distribution encompasses the construction and operation of localized pipeline networks that deliver compressed natural gas and piped natural gas to end consumers at pressures typically ranging from 4 to 16 bar for residential supply and up to 300 bar for vehicle refueling. These systems function as the final delivery infrastructure connecting national transmission grids to industrial boilers, household kitchens, and transportation fleets. Pipeline distribution services currently generate the largest revenue pool given the capital intensity of network buildout, while smart meter technology represents the fastest-expanding segment as utilities deploy advanced metering infrastructure to reduce commercial losses and enable time-of-use pricing. Metering services concentrate margin pools through software-defined analytics and remote diagnostics capabilities.
The Petroleum and Natural Gas Regulatory Board in India mandates minimum work program obligations and infrastructure rollout timelines for licensed city gas distribution entities. China's National Development and Reform Commission enforces dual carbon targets that redirect industrial coal consumption toward natural gas through municipal pipeline obligations. Stakeholders must monitor how evolving methane emissions standards from the EPA reshape compressor station specifications and leak detection investment requirements across operating territories.
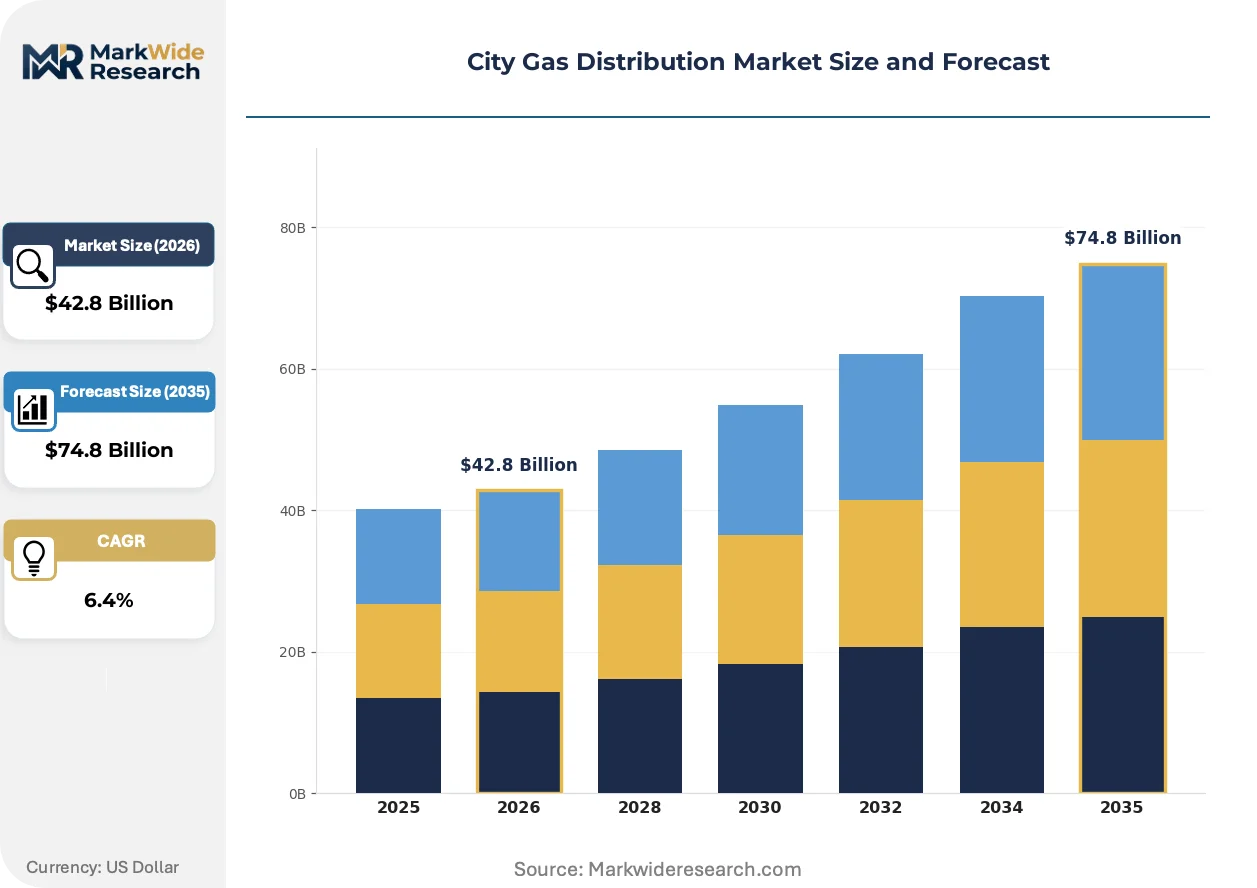
Market Dynamics
The transition from capital-heavy pipeline construction to recurring revenue from metering and maintenance services is restructuring competitive economics across city gas distribution networks.
Growth Catalysts
- India's Petroleum and Natural Gas Regulatory Board mandates:Minimum work program obligations force licensed entities to accelerate infrastructure rollout timelines, locking in decade-long expansion commitments.
- Industrial coal-to-gas switching:China's dual carbon policy enforcement redirects factory boiler fuel consumption toward piped natural gas through municipal pipeline obligations.
- Smart city integration:Digital customer platforms and advanced metering infrastructure are capturing operational efficiency gains in emerging Indian metropolitan regions.
Market Restraints
- Steel and polymer input cost volatility:Pipeline construction materials face commodity price swings that compress project margins during network buildout phases.
- Specialized welding and trenching equipment concentration:European and East Asian manufacturers dominate critical machinery supply, creating procurement bottlenecks.
- Electrification of transport fleets:Battery-electric vehicle adoption in passenger and light commercial segments threatens long-term compressed natural gas demand at refueling stations.
Strategic Opportunities
- Leak detection and methane monitoring services:EPA emissions standards are creating compliance-driven demand for continuous monitoring technology integration.
- Residential smart meter penetration:Time-of-use pricing enablement through advanced metering infrastructure opens recurring software revenue streams.
- Small-scale LNG satellite terminals:Captive terminal access in underserved western Indian districts allows bypass of national transmission grid constraints.
Industry Challenges
- Pipeline integrity assessment expertise shortage:Specialized technicians for inline inspection and cathodic protection management command premium wages, constraining expansion velocity.
- Legacy SCADA system integration complexity:Municipal utilities struggle to overlay digital monitoring platforms atop decades-old control architectures without service interruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | City Gas Distribution Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $74.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Residential, Commercial, Industrial, Transportation Service Type: Pipeline Distribution, Metering, Maintenance, Installation End User: Households, Businesses, Factories, Power Plants Technology: Smart Meters, SCADA Systems, Gas Treatment, Compression |
| Companies Covered | Enbridge Inc., Dominion Energy Inc., TC Energy Corporation, Southern Co., Indraprastha Gas Limited, Gujarat Gas Limited, GAIL Gas Limited, Mahanagar Gas Limited, Adani Total Gas Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
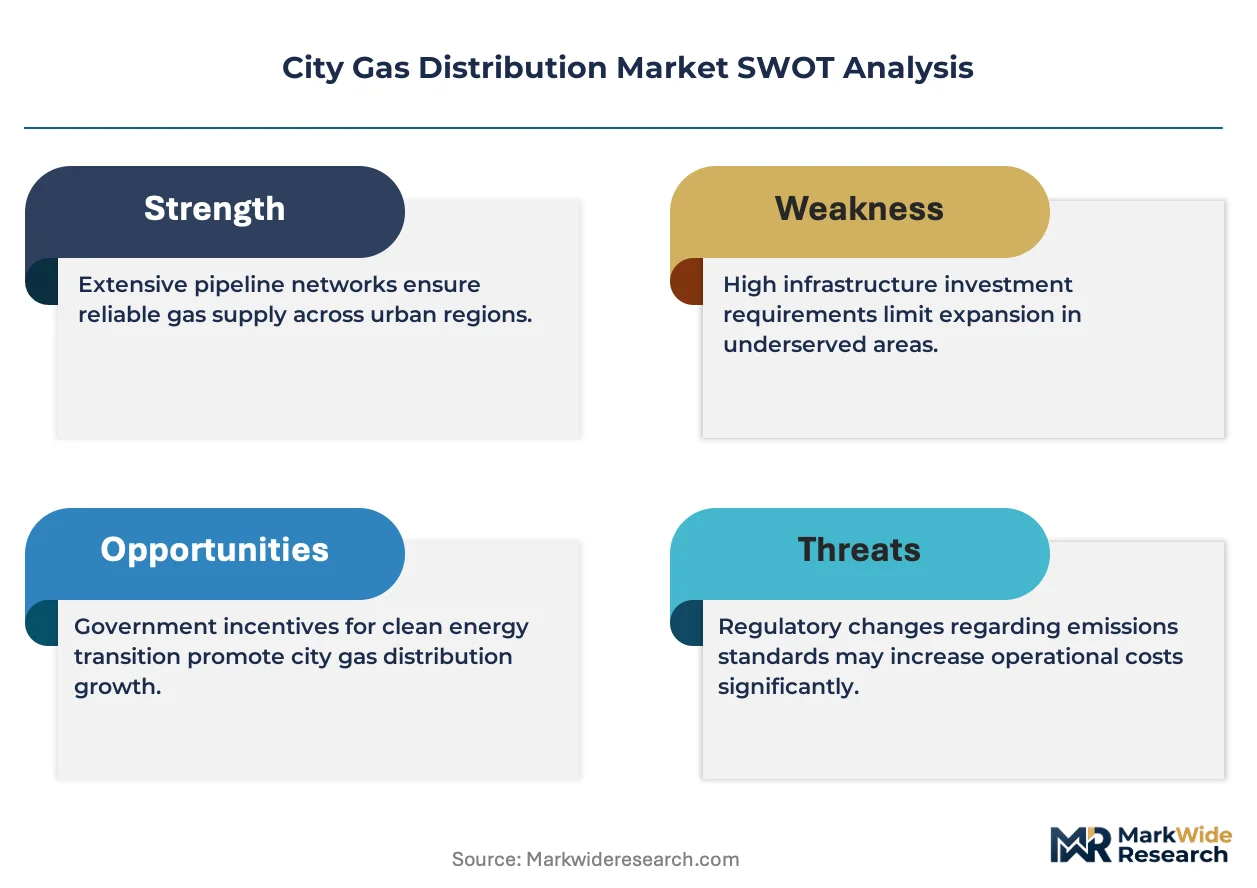
City Gas Distribution Market Strategic Shifts
Digital infrastructure layers are overlaying physical pipeline networks, compressing operational response times and enabling predictive maintenance models that reshape capital allocation priorities.
Advanced metering infrastructure is absorbing commercial loss reduction mandates across distribution territories. Utilities in Gujarat and Maharashtra are deploying smart meters at residential connection points to eliminate manual reading errors and theft. The technology is absorbing margin pressure from regulated tariff ceilings by shifting revenue toward data analytics and remote diagnostic subscriptions.
China's National Development and Reform Commission enforces municipal pipeline obligations that bind industrial zones to natural gas offtake commitments. The policy compresses coal consumption permits in manufacturing clusters while mandating compressor station specifications. Indian industrial corridors face parallel pressure as the Petroleum and Natural Gas Regulatory Board tightens emission monitoring requirements for licensed entities.
Service contract unbundling is fragmenting traditional engineering-procurement-construction relationships. Industrial buyers in chemical and textile clusters are separating pipeline construction from decade-long maintenance agreements, forcing contractors to compete on operational metrics rather than upfront capital efficiency. This pattern concentrates in western Indian states where Gujarat Gas Limited and Adani Total Gas Ltd. operate overlapping territories.
City Gas Distribution Market Segmentation
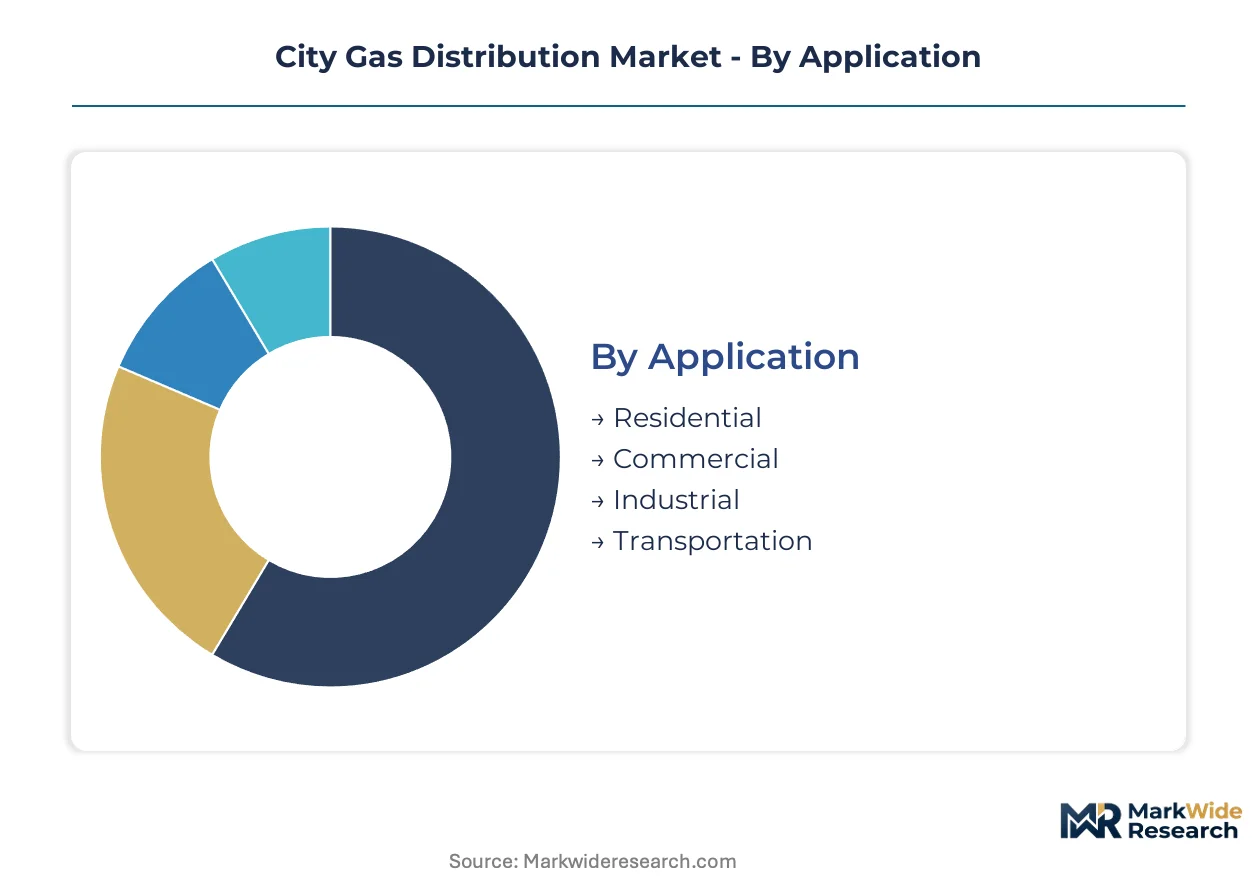
City gas distribution networks serve heterogeneous demand profiles that require distinct infrastructure specifications, pricing mechanisms, and operational protocols. Segmentation clarity enables utilities to optimize capital deployment across residential density zones, industrial load centers, and transportation corridors with divergent pressure requirements and consumption patterns.
Application:
Volume concentration in industrial offtake contrasts with premium-margin residential subscriptions across licensed distribution territories.
- Residential:Piped natural gas delivery to apartment complexes and standalone dwellings operates at 4-16 bar pressure through polyethylene or steel service lines. Demand clusters in Gujarat and Maharashtra urban agglomerations where PNG connections displace liquefied petroleum gas cylinders under Petroleum and Natural Gas Regulatory Board mandates. Tariff ceilings compress margins, forcing cross-subsidization from commercial and industrial segments.
- Industrial:High-volume offtake from textile dyeing, ceramics firing, and chemical processing facilities anchors revenue stability for distribution entities. China's National Development and Reform Commission binds manufacturing clusters to municipal pipeline obligations, redirecting coal boiler capacity toward natural gas. Load factors exceed 80% in designated industrial corridors, amortizing pipeline fixed costs across predictable demand baselines.
- Commercial:Hotels, restaurants, and institutional kitchens require medium-pressure supply with seasonal demand volatility. Metering infrastructure captures consumption granularity for time-of-use pricing experiments in smart city pilots.
- Transportation:Compressed natural gas refueling for bus fleets and light commercial vehicles competes with battery-electric alternatives. Station density determines market penetration in metropolitan regions with air quality enforcement.
Today's leader: Industrial. Tomorrow's challenger: Residential smart meter penetration.
Service Type:
Capital intensity separates one-time construction revenue from recurring operational income streams.
- Pipeline Distribution:Buried steel and polyethylene networks constitute the foundational asset base requiring decade-long depreciation schedules. Trenching, welding, and cathodic protection installation absorb 60-70% of licensed entity capital expenditure under minimum work program obligations.
- Metering:Advanced metering infrastructure with remote data transmission and tamper detection is gaining share fastest in residential connection programs. Software-defined analytics subscriptions offset regulated tariff compression through recurring revenue models.
- Maintenance:Pipeline integrity management, compressor station servicing, and leak detection contracts are unbundling from engineering-procurement-construction agreements. Operational metrics now determine contractor selection in western Indian industrial clusters.
- Installation:Initial connection services for household kitchens and commercial kitchens face margin pressure from standardized pricing. Volume throughput depends on regulatory-mandated connection targets.
Construction intensity dominates current revenue; metering services claim expanding margin pools.
End User:
Consumption scale and price elasticity diverge sharply across customer categories.
- Households:Price-sensitive residential subscribers with seasonal cooking and heating demand patterns. Smart meter deployment in Gujarat and Maharashtra eliminates manual reading costs and theft losses.
- Businesses:Commercial establishments with predictable baseload and willingness to accept interruptible supply contracts for tariff discounts. Demand concentrates in hospitality and food service clusters.
- Factories:Process heat requirements in ceramics, textiles, and chemicals anchor volume throughput. China's dual carbon policy enforcement accelerates coal-to-gas switching in designated industrial zones.
- Power Plants:Combined cycle gas turbine facilities requiring high-pressure supply with stringent reliability standards. Grid balancing obligations create peak demand volatility.
Factories anchor volume; households drive connection growth velocity.
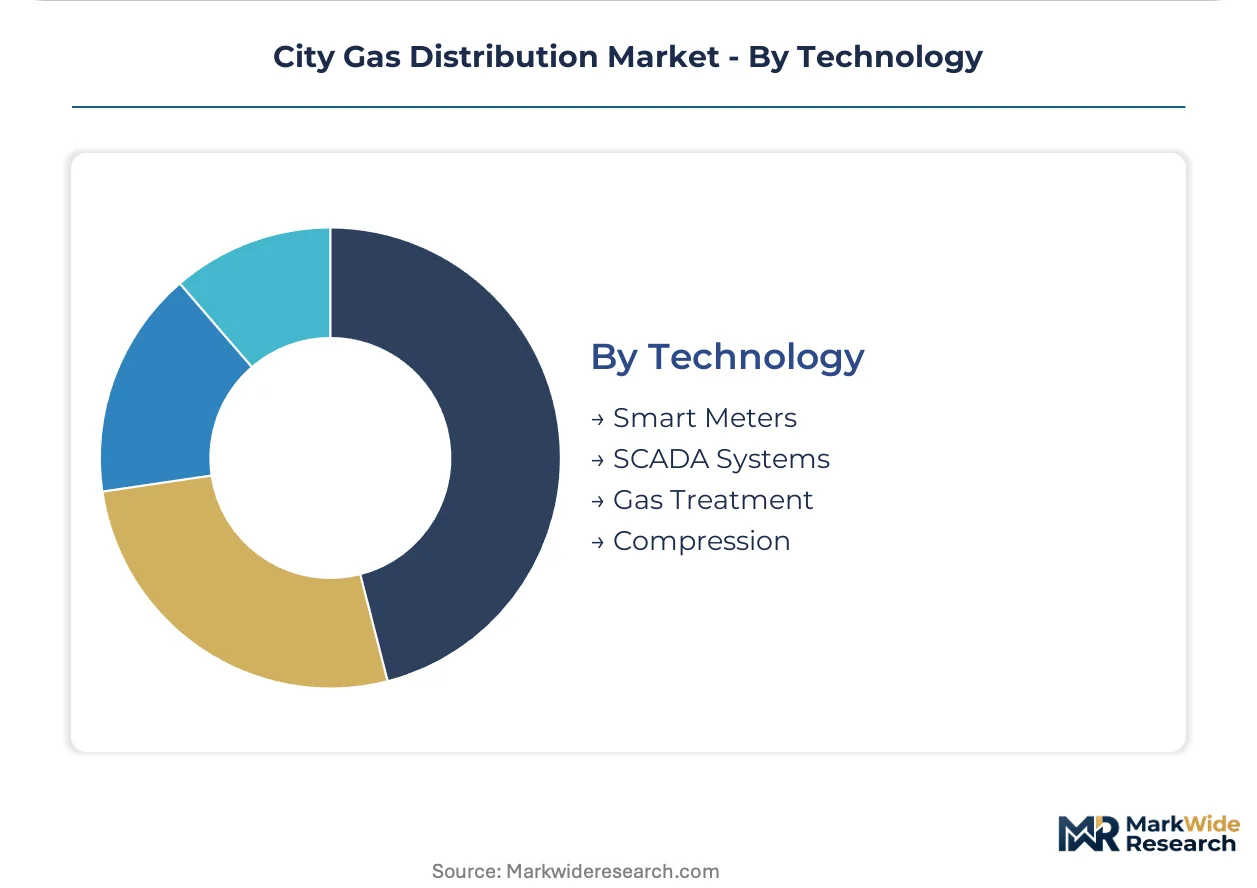
Technology:
Digital overlay layers are compressing operational response times atop physical infrastructure.
- Smart Meters:Advanced metering infrastructure with two-way communication enables time-of-use pricing and remote disconnect capability. Deployment accelerates in Indian metropolitan regions under commercial loss reduction mandates.
- SCADA Systems:Supervisory control and data acquisition platforms monitor pressure, flow, and leak indicators across distribution networks. Legacy system integration complexity constrains municipal utility upgrade timelines.
- Gas Treatment:Odorization, dehydration, and filtration systems ensure pipeline integrity and safety compliance. Specification requirements tighten under evolving methane emissions standards.
- Compression:Compressor stations maintain pressure gradients for CNG refueling and industrial supply. Equipment procurement concentrates among European and East Asian manufacturers.
SCADA systems command current investment; smart meters capture fastest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Petroleum and Natural Gas Regulatory Board mandates accelerate network buildout faster than China's National Development and Reform Commission enforces municipal pipeline obligations, creating divergent compliance timelines across Asia's two largest distribution markets.
India
Industrial clusters in Gujarat and Maharashtra drive compressed natural gas station density and piped natural gas connections. The Petroleum and Natural Gas Regulatory Board mandates minimum work program obligations that lock licensed entities into decade-long infrastructure rollouts. Gujarat Gas Limited and Adani Total Gas Ltd. operate overlapping territories in western Indian states where factory boiler conversions proceed fastest.
China
Manufacturing zones in the Yangtze River Delta and Pearl River Delta redirect coal consumption toward natural gas through municipal pipeline obligations. The National Development and Reform Commission enforces dual carbon targets that compress coal consumption permits in designated industrial corridors. State-backed pipeline operators bind chemical and textile clusters to long-term offtake commitments.
United States
Urban centers across the Midwest and Northeast leverage pipeline integrity management programs to secure operational contracts. The EPA's evolving methane emissions standards reshape compressor station specifications and leak detection investment requirements. Enbridge Inc. anchors long-term service agreements in North American metropolitan regions through integrity management offerings.
Canada
TC Energy Corporation extends distribution infrastructure across Ontario and Quebec population corridors. The national pipeline network connects to localized distribution systems serving industrial boilers and residential heating loads. Cold climate heating demand concentrates volume throughput in Toronto and Montreal metropolitan zones.
Germany
Ruhr industrial heritage zones and Bavarian manufacturing clusters face municipal heating decarbonization mandates. The EU Green Deal redirects district heating systems toward natural gas bridging fuels while hydrogen infrastructure planning proceeds. Specialized welding equipment procurement concentrates among domestic engineering fabricators serving trenching and cathodic protection installation.
City Gas Distribution Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pipeline construction services consolidating around capital-intensive entities while metering and maintenance fragment into subscription-based specialists. Three archetypes dominate: integrated pipeline operators with captive infrastructure assets, smart meter technology specialists capturing recurring software revenue, and regional distribution licensees holding exclusive geographic concessions. Competitive moves concentrate on service contract unbundling and operational metric-based contractor selection.
Within the integrated pipeline operator tier, Enbridge Inc. and TC Energy Corporation exemplify capital-heavy infrastructure owners that anchor long-term operational contracts through integrity management programs. Among India-based distribution licensees, Gujarat Gas Limited and Adani Total Gas Ltd. occupy positions reflecting divergent strategic emphases—captive LNG terminal access versus smart city integration. Indraprastha Gas Limited and Mahanagar Gas Limited represent metropolitan concession holders concentrated in Delhi-NCR and Mumbai respectively.
| Leading Market Players |
|---|
| Enbridge Inc. |
| Dominion Energy Inc. |
| TC Energy Corporation |
| Southern Co. |
| Indraprastha Gas Limited |
| Gujarat Gas Limited |
| GAIL Gas Limited |
| Mahanagar Gas Limited |
| Adani Total Gas Ltd. |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed pipeline operators anchor capital deployment cycles that compress pricing discipline across construction phases while amplifying margin capture in operational service contracts. State-owned entities in China and India feed procurement concentration into long-term offtake agreements that lock industrial buyers into regulated tariff bands.
Pricing Analysis
Capacity additions in India are reshaping price floors for pipeline construction services as the Petroleum and Natural Gas Regulatory Board mandates accelerate licensed entity rollout obligations. Contract-based long-term offtake agreements dominate industrial supply, with price differentiation resting on volume scale and geographic delivery cost to remote industrial corridors. Cost compression in residential connection programs is intensifying because standardized installation pricing eliminates margin buffers. Factory buyers demonstrate lowest price sensitivity given process heat requirements, while household subscribers resist tariff increases beyond regulated ceilings.
Supply Chain Analysis
Refurbishment flows for inline inspection tools and cathodic protection equipment concentrate maintenance capacity among specialized service providers in Germany, Japan, and the United States. Pipeline construction draws from steel plate, polyethylene resin, and specialized welding consumables sourced from Chinese and South Korean mills. Single-source vulnerability in European and East Asian trenching machinery manufacturers creates procurement bottlenecks during network buildout surges. Distribution runs through engineering-procurement-construction contractors that unbundle decade-long maintenance agreements from initial capital deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The city gas distribution market functions as a stable compounder anchored by regulatory-mandated infrastructure rollout obligations that guarantee decade-long revenue visibility for licensed entities.
For Market Incumbents: Anchor defensibility through captive LNG terminal access in western Indian districts and pipeline integrity management program certification that locks industrial buyers into operational contracts. Battery-electric vehicle adoption threatens compressed natural gas station throughput, demanding accelerated smart meter penetration to capture recurring software revenue streams that offset refueling margin erosion. For New Entrants and Emerging Players: Municipal utilities with legacy SCADA architectures represent the most penetrable customer segment for digital overlay platform vendors offering predictive maintenance analytics without service interruption. Target smart city integration mandates in emerging Indian metropolitan regions where Adani Total Gas Ltd. has established digital customer platform precedent. Pursue leak detection technology licensing agreements with EPA-regulated compressor station operators facing methane emissions compliance deadlines. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distribution licensees holding exclusive geographic concessions with minimum work program obligations already satisfied. The five-to-ten-year viability window favors meter technology specialists capturing recurring SaaS revenue from advanced metering infrastructure deployment. Monitor EPA methane emissions standard enforcement velocity as inflection indicator for compliance-driven monitoring technology demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Meter Infrastructure Deployment | Advanced metering infrastructure in Gujarat and Maharashtra eliminates manual reading costs and theft losses while enabling time-of-use pricing experiments. |
| Pipeline Integrity Management Certification | Enbridge Inc. anchors long-term operational contracts in North American urban centers through cathodic protection and inline inspection program offerings. |
| Small-Scale LNG Terminal Development | Captive terminal access in underserved western Indian districts allows distribution entities to bypass national transmission grid constraints and supply industrial clusters directly. |
| Digital Customer Platform Integration | Adani Total Gas Ltd. differentiates in emerging Indian metropolitan regions through smart city integration and mobile-first customer service interfaces. |
| Methane Monitoring Technology Licensing | EPA emissions standards reshape compressor station specifications and create compliance-driven demand for continuous leak detection system integration across operating territories. |
Study Parameters
Multiple input streams — primary interviews with distribution utility planning officers, EPC contractor project directors, and industrial procurement leads; secondary validation against Petroleum and Natural Gas Regulatory Board licensing records, EPA emissions compliance filings, and pipeline construction customs data — were reconciled through bottom-up and top-down triangulation to establish market sizing and growth trajectory estimates.
Data-stream reconciliation across the projection horizon applied segment-level modeling for application type, service category, end-user scale tier, and technology deployment stage. CAGRs were derived from infrastructure rollout obligation timelines, industrial coal-to-gas switching velocity under dual carbon enforcement, and smart meter penetration curves in designated metropolitan regions. Forecast inputs incorporated minimum work program commitment schedules, municipal pipeline obligation binding rates in Chinese manufacturing clusters, and compressor station specification upgrade cycles under evolving methane standards.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery-electric vehicle adoption rates in passenger and light commercial segments, steel and polymer commodity price volatility, and specialized welding technician wage inflation. Practitioners should monitor EPA methane rulemaking progression, Indian Petroleum and Natural Gas Regulatory Board licensing auction velocity, and Chinese National Development and Reform Commission dual carbon enforcement intensity for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Hydrogen Fuel Tanks Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
Compressed Natural Gas Market
Fuels
Carbonizers Market
Fuels
Gasoline Market
Fuels
Bunker Fuel Market
Fuels
Oil Dispensing Stations Market
Fuels
Europe Aviation Fuel Market
Fuels
Wood Pellet Market
Fuels
Aviation Fuel Additives Market
Fuels
Storage Tank Market
Fuels
Global Methane Hydrate Market
Fuels
India LNG Market
Fuels
North America Commercial Aircraft Aviation Fuel Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
India Bunker Fuel Market