
 LNG Fueling Station Market | 2026-2036
LNG Fueling Station Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Fueling Station Market Foresight
Station deployment partnerships between equipment vendors and fuel retailers is reshaping how LNG infrastructure reaches end users. Shell Plc leverages its integrated energy network to secure long-term offtake agreements at major transport hubs. Chart Industries anchors North American manufacturing capacity through cryogenic equipment specialization. Cryostar competes on liquefaction system efficiency for mid-scale station formats.
An LNG fueling station compresses, stores, and dispenses liquefied natural gas at cryogenic temperatures near minus 162 degrees Celsius to vehicles and vessels requiring reduced-emission fuel alternatives. Permanent stations dominate capital deployment due to higher throughput capacity and grid-connected power reliability, while mobile units address remote construction sites and temporary fleet operations. Heavy-duty vehicles lead application demand, though marine transport segments attract accelerating investment as port authorities enforce emission control area compliance.
The EPA regulates station venting and leak detection standards under Clean Air Act methane provisions, while the EU F-Gas Regulation governs refrigerant systems in liquefaction equipment. China's MIIT enforces GB standards for pressure vessels and dispensing accuracy, creating compliance cost layers for imported equipment. Stakeholders must weigh regulatory timeline certainty against infrastructure payback periods when committing capital to multi-fuel retail formats.
Market Dynamics
EU Green Deal emission ceilings are compressing payback periods for LNG infrastructure investments across European freight corridors. Logistics operators now face binding CO2 reduction mandates that accelerate fleet conversion timelines and concentrate demand around high-throughput permanent station formats.
Growth Catalysts
- EU Fit for 55 framework:Binding CO2 reduction mandates for road transport force heavy-duty fleet operators to secure alternative fuel contracts. Germany's Rhine-Alpine freight corridor anchors this demand concentration.
- Port emission control areas:Marine transport segments attract accelerating investment as port authorities enforce compliance standards for vessel bunkering operations at coastal hubs.
- Cryogenic storage efficiency:Advances in vacuum-insulated tank systems reduce boil-off losses during extended holding periods, improving station economics for remote deployment formats.
Market Restraints
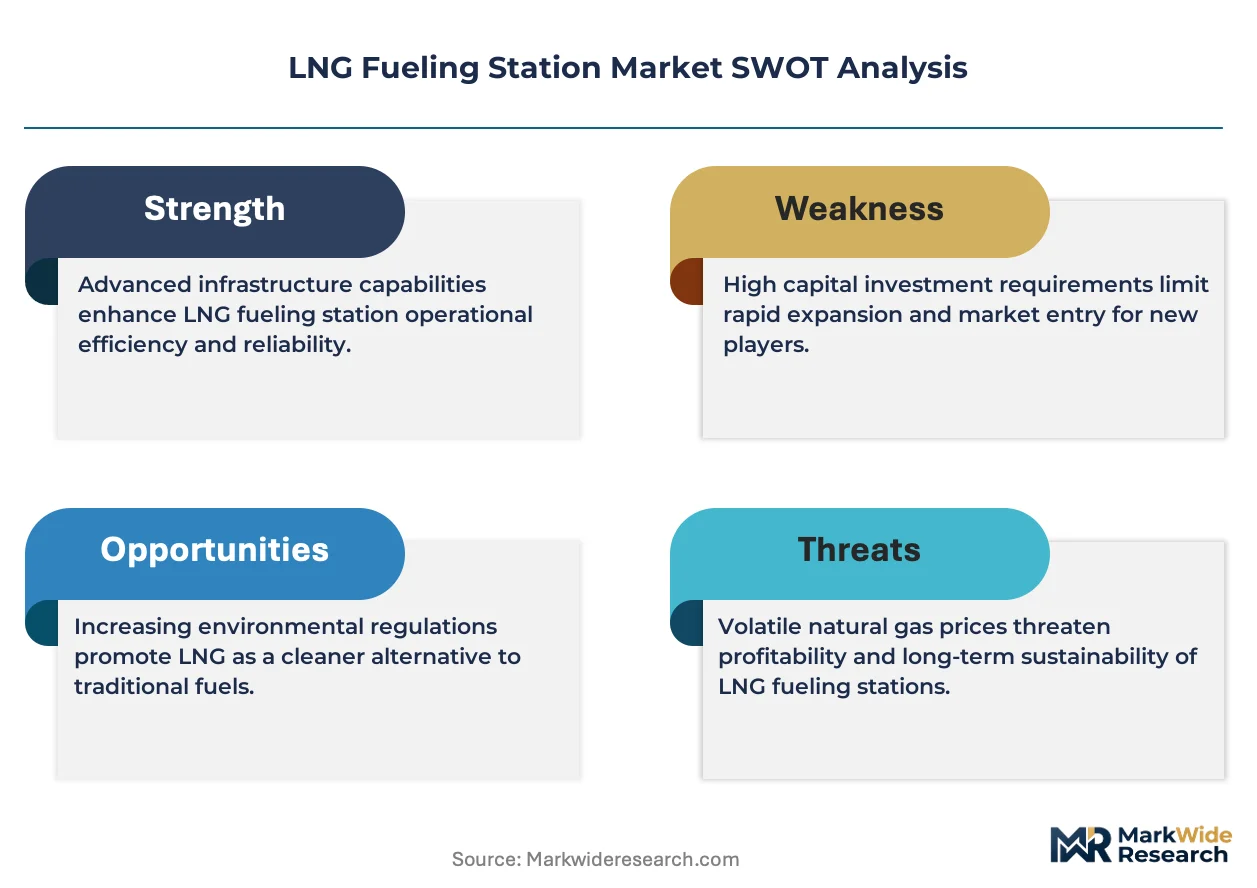
- Natural gas price volatility:Input cost swings undermine long-term offtake contract pricing stability and deter multi-year infrastructure commitments from risk-averse fleet operators.
- Equipment import compliance layers:China's MIIT enforcement of GB pressure vessel standards creates certification bottlenecks for European and North American equipment vendors seeking market entry.
- Electric drivetrain substitution:Battery-electric heavy-duty platforms from manufacturers like Scania and Daimler capture municipal and regional route segments previously targeted for LNG conversion.
Strategic Opportunities
- India's National Hydrogen Mission spillover:LNG stations positioned as bridge fuel infrastructure along Delhi-Mumbai Industrial Corridor freight routes capture early-mover positioning before hydrogen scale-up.
- Small-scale liquefaction convergence:Modular liquefaction units paired with biomethane upgrading facilities enable closed-loop fuel production at agricultural and waste processing sites.
- EU Alternative Fuels Infrastructure Regulation:Binding deployment targets for member states create guaranteed demand pools for station developers securing corridor concession agreements.
Industry Challenges
- Cryogenic technician scarcity:Specialized training requirements for minus 162-degree Celsius system maintenance outpace vocational program output across European engineering labor markets.
- Multi-fuel retail integration complexity:Existing diesel and CNG dispensing infrastructure at transport hubs requires costly reconfiguration to accommodate LNG cryogenic storage and vaporization systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Fueling Station Market |
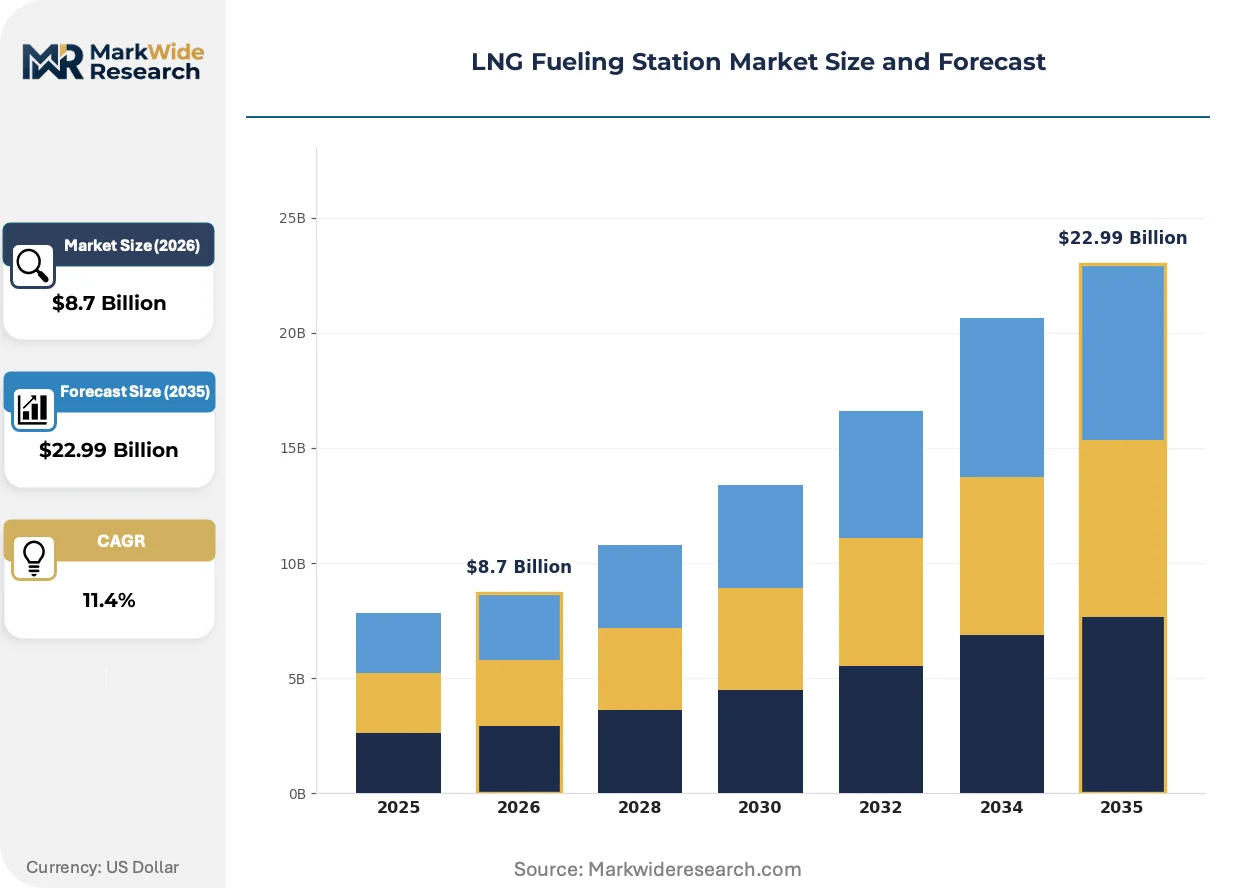
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Station Type: Public, Private, Mobile, Permanent End User: Commercial Fleets, Logistics Providers, Municipalities, Industrial Users Application: Heavy-Duty Vehicles, Marine Transport, Power Generation, Rail Transport Technology: Compression, Storage, Dispensing, Monitoring |
| Companies Covered | CNPC, Shell Plc, Chart Industries, Jereh Oil & Gas Engineering Corporation, Westfalen, Axegaz T&T, Cryonorm Group, Cryostar, INOX India Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Fueling Station Market Shifts & Advancements
Modular station architectures are compressing deployment timelines and enabling rapid capacity scaling at evolving transport nodes. Equipment vendors now prioritize plug-and-play cryogenic systems that minimize civil works and grid connection dependencies.
Small-scale liquefaction technology is collapsing the economic threshold for distributed LNG production at non-pipeline locations. Regional logistics operators in Poland and the Czech Republic deploy containerized liquefaction units to bypass wholesale supply contracts. This distributed model compresses fuel cost structures and reduces exposure to transmission tariff volatility.
The EU F-Gas Regulation is tightening refrigerant system requirements for liquefaction equipment, forcing equipment redesigns toward lower-global-warming-potential alternatives. Vendors face compressed certification timelines as the regulation phases down hydrofluorocarbon quotas through 2030. Marine bunkering applications experience the steepest compliance cost adjustments due to larger refrigerant charge volumes.
Fleet procurement patterns are consolidating around long-term fuel supply agreements rather than spot-market purchasing. Large German and Dutch logistics groups negotiate multi-year station access contracts that bundle infrastructure investment commitments with volume guarantees. This contractual shift compresses competitive differentiation toward balance-sheet capacity and integrated energy network reach rather than equipment specifications alone.
LNG Fueling Station Market Segmentation
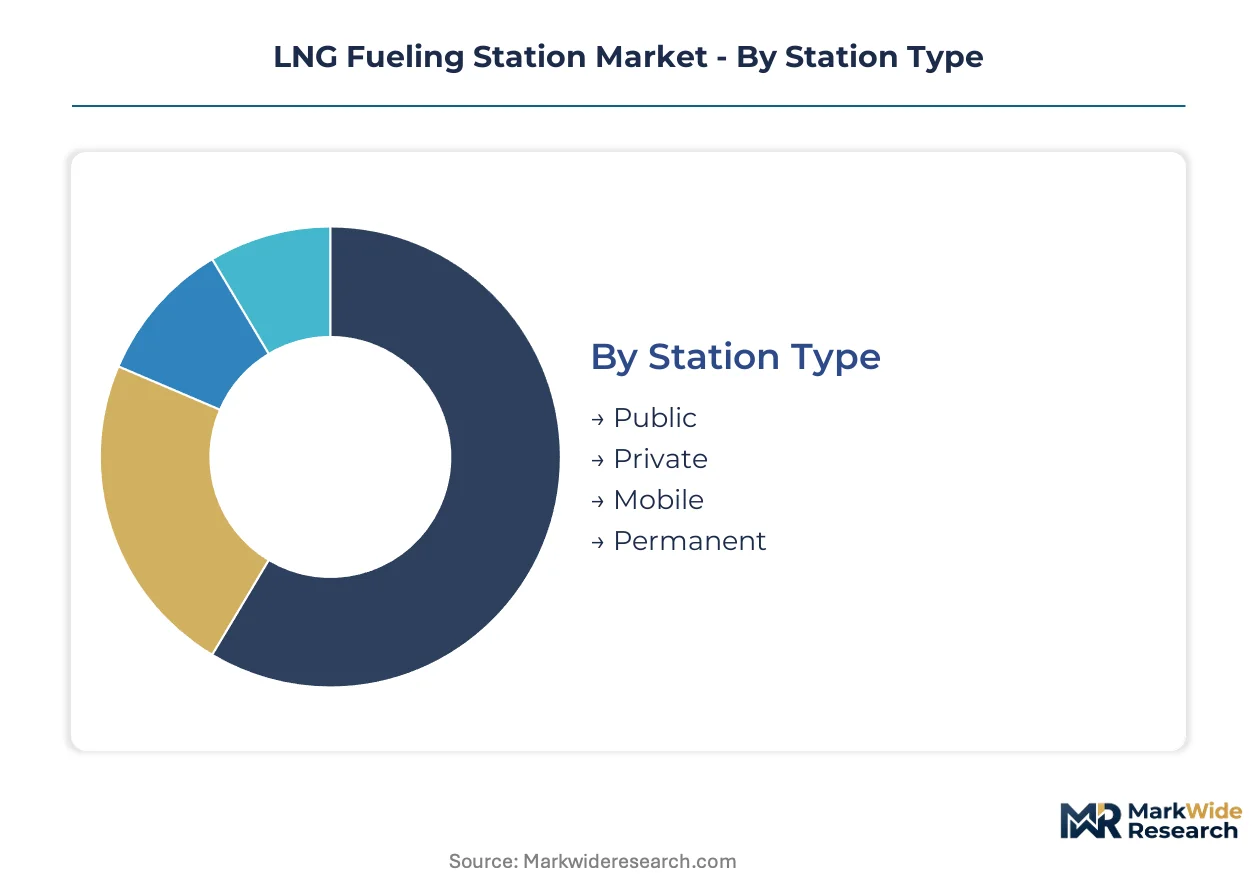
LNG fueling stations serve distinct operational profiles across transport modes and ownership structures. Station format, user category, application, and technology stack each create divergent investment thresholds and regulatory exposure for infrastructure developers.
Station Type:
Station formats span from open-access retail infrastructure to captive fleet installations, with mobility and permanence determining capital intensity and grid dependency.
- Public:Open-access retail stations serve multiple fleet operators at high-throughput transport corridors. Germany's Rhine-Alpine freight corridor concentrates demand here as EU Fit for 55 mandates force CO2 reductions across fragmented logistics operators lacking captive infrastructure capital.
- Permanent:Fixed installations with grid-connected power and high-capacity cryogenic storage dominate capital deployment. These anchor major freight hubs where Shell Plc secures long-term offtake agreements through integrated energy network positioning.
- Private:Captive stations serve single-fleet or closed-user groups with dedicated supply contracts. Industrial users and large logistics groups favor this format to lock in fuel cost predictability amid natural gas price volatility.
- Mobile:Containerized or trailer-mounted units address remote construction sites and temporary fleet operations. Polish and Czech regional operators deploy these to bypass wholesale supply contracts and transmission tariff exposure.
Established volume favors Permanent; emerging adoption favors Mobile.
End User:
Customer archetypes range from price-sensitive municipal procurement to integrated logistics networks with balance-sheet capacity for infrastructure co-investment.
- Commercial Fleets:Heavy-duty trucking operators with predictable route structures anchor base-load demand. Large German and Dutch logistics groups now negotiate multi-year station access contracts bundling infrastructure commitments with volume guarantees.
- Logistics Providers:Third-party operators serving fragmented shipper demand concentrate around corridor nodes. These users prioritize network coverage over single-station specifications, reshaping competitive differentiation toward integrated energy reach.
- Municipalities:Public transit and waste collection fleets drive procurement through tender processes with strict emission compliance requirements. Budget constraints limit these users to public station access or modest private installations.
- Industrial Users:Mining, construction, and manufacturing sites with captive vehicle fleets favor on-site liquefaction and closed-loop fuel production. Agricultural and waste processing sites pair modular liquefaction with biomethane upgrading for distributed supply.
Procurement consolidation favors Logistics Providers; policy mandates favor Municipalities.
Application:
Use cases divide between established road transport demand and emerging marine and rail segments with distinct compliance timelines.
- Heavy-Duty Vehicles:Long-haul trucking constitutes the dominant demand base with proven engine technology and established maintenance networks. Battery-electric platforms from Scania and Daimler now capture municipal and regional routes, compressing LNG's addressable market to corridor-length haulage.
- Marine Transport:Coastal and inland vessel bunkering attracts accelerating investment as port authorities enforce emission control area compliance. EU F-Gas Regulation refrigerant requirements impose steepest cost adjustments here due to larger liquefaction system charge volumes.
- Power Generation:Remote and backup power applications utilize LNG where grid extension is uneconomic. These installations favor small-scale liquefaction convergence with localized production models.
- Rail Transport:Locomotive fueling remains nascent with limited route electrification alternatives driving pilot deployments. Cryogenic storage efficiency advances reduce boil-off losses that previously undermined rail yard economics.
Technology maturity favors Heavy-Duty Vehicles; regulatory enforcement favors Marine Transport.
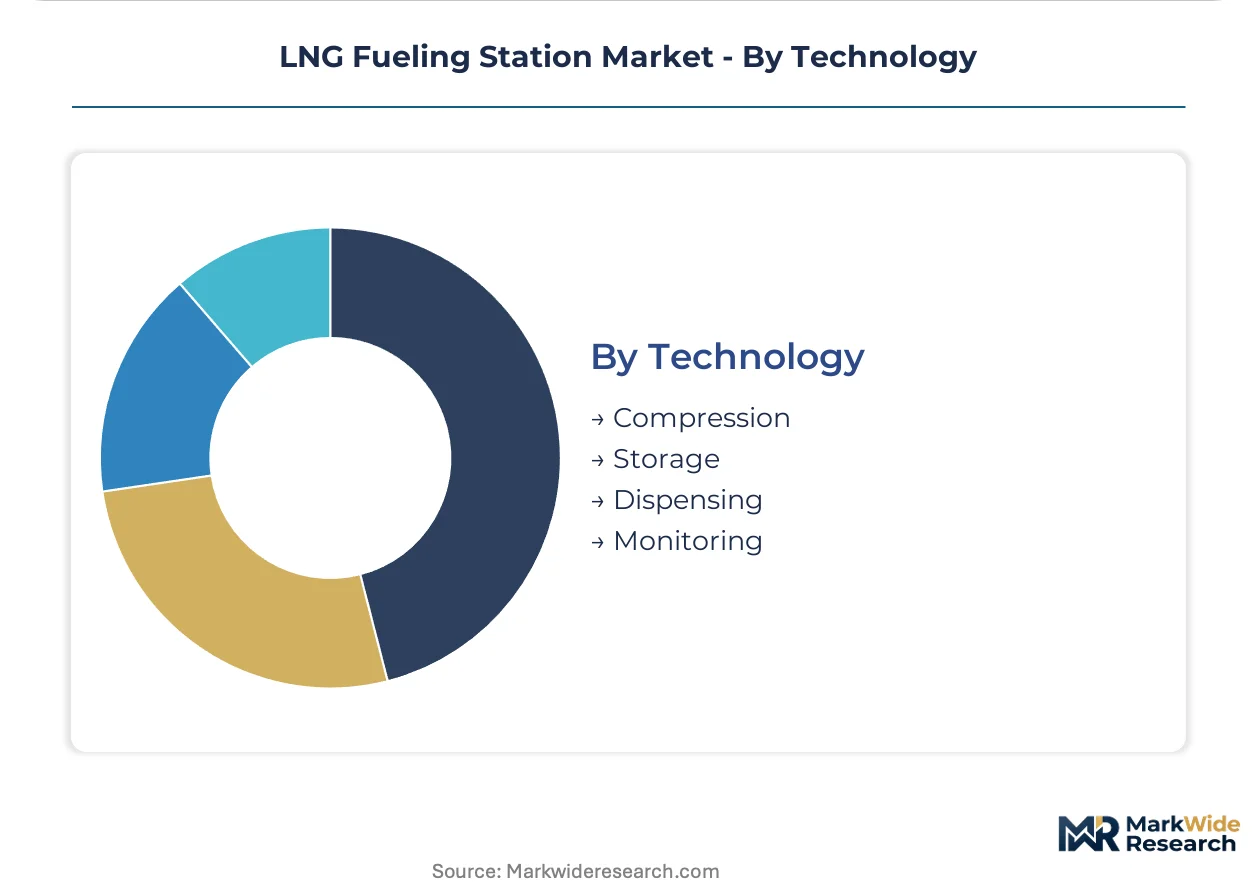
Technology:
System components span gas handling, thermal management, and operational control with diverging specialization requirements.
- Storage:Vacuum-insulated cryogenic tanks operating at minus 162 degrees Celsius determine holding efficiency and boil-off rates. Chart Industries anchors North American manufacturing capacity through specialization in these systems.
- Compression:Gas compression systems prepare feedstock for liquefaction or direct vehicle dispensing. Cryostar competes on liquefaction system efficiency for mid-scale station formats requiring modular throughput scaling.
- Dispensing:Cryogenic fuel transfer systems must maintain temperature integrity while meeting China's MIIT GB standards for pressure vessels and metering accuracy. Certification bottlenecks delay European and North American vendor market entry.
- Monitoring:Leak detection and venting control systems face EPA Clean Air Act methane provisions in the US and EU F-Gas Regulation refrigerant tracking requirements. These systems compress station deployment timelines through pre-certified plug-and-play architectures.
Capital concentration favors Storage; modular innovation favors Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's Trans-European Transport Network corridors anchor LNG station deployment across freight-intensive economies. Pipeline interconnections and port bunkering infrastructure determine each market's conversion timeline and station format preference.
Germany
Rhine-Alpine freight corridor traffic drives permanent station investments from Shell Plc and Westfalen. The EU Fit for 55 framework imposes binding CO2 reduction mandates on logistics operators. Hamburg and Bremen port clusters enforce emission control area compliance for marine bunkering operations.
United States
Interstate highway freight density supports heavy-duty fleet conversion programs. EPA Clean Air Act methane provisions regulate station venting and leak detection standards. California's San Pedro Bay port complex mandates zero-emission vessel fueling alternatives at marine terminals.
China
Beijing-Tianjin-Hebei freight corridors concentrate demand under national dual carbon goals. MIIT enforces GB standards for pressure vessels and dispensing accuracy. Sichuan-Chongqing shale gas basins enable distributed small-scale liquefaction for regional logistics operators.
Netherlands
Rotterdam-Antwerp port range bunkering volumes attract marine-focused station developers. EU Alternative Fuels Infrastructure Regulation creates binding deployment targets for member states. Randstad logistics hubs consolidate multi-year fuel supply agreements from integrated energy networks.
India
Delhi-Mumbai Industrial Corridor freight routes position LNG as bridge fuel before hydrogen scale-up. The National Hydrogen Mission timeline influences early-mover infrastructure commitments. Gujarat's Hazira port cluster develops coastal vessel bunkering capacity under emission reduction programs.
LNG Fueling Station Market Competitive Landscape
On the supply side, the industry is consolidating around integrated energy networks with balance-sheet capacity for multi-year infrastructure commitments. Equipment vendors and fuel retailers form deployment partnerships that reshape corridor access strategies. Two archetypes dominate: cryogenic system specialists and vertically integrated energy majors. Competitive moves concentrate on long-term offtake agreements and modular station architecture standardization.
Within the integrated energy tier, Shell Plc anchors European corridor positioning through network reach and concession agreements. Chart Industries represents North American manufacturing capacity in vacuum-insulated cryogenic storage systems. Cryostar occupies a position among liquefaction efficiency specialists serving mid-scale station formats.
| Leading Market Players |
|---|
| CNPC |
| Shell Plc |
| Chart Industries |
| Jereh Oil & Gas Engineering Corporation |
| Westfalen |
| Axegaz T&T |
| Cryonorm Group |
| Cryostar |
| INOX India Limited |
| Others |
Supply & Pricing Matrix
Natural gas price volatility determines both tier spreads between permanent and mobile station formats and supply chain shape across wholesale contract versus distributed liquefaction models. Fleet operators facing input cost swings compress procurement timelines and favor suppliers with captive upstream control over cryogenic equipment manufacturing.
Pricing Analysis
Volume-discount tiering structures separate large logistics groups negotiating multi-year offtake agreements from municipal fleets purchasing through public tender processes. Price differentiation centers on throughput guarantees and integrated maintenance bundling, with permanent stations commanding premium positioning over mobile units. Cost compression in mid-scale formats intensifies as Cryostar and Chart Industries compete on liquefaction efficiency. Municipal procurement teams exhibit highest price sensitivity due to fixed budget constraints, while integrated energy networks demonstrate lowest sensitivity through balance-sheet capacity for infrastructure co-investment.
Supply Chain Analysis
Tariff exposure between China and European equipment vendors dominates supply chain risk as MIIT GB standards create certification bottlenecks for pressure vessel imports. Manufacturing concentrates in Germany, China, and the United States, with vacuum-insulated tank production anchored in North American facilities. Raw material dependencies span nickel-alloy cryogenic steels, specialized refrigerants, and precision metering components. Distribution runs through equipment vendor-fuel retailer partnerships that reshape corridor access strategies rather than traditional component wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies early-cycle expansion positioning as EU Fit for 55 mandates force fleet conversion timelines before battery-electric platforms achieve corridor-length haulage viability.
For Market Incumbents: Harden long-term offtake contract structures against natural gas price volatility through indexed pricing mechanisms and captive liquefaction capacity. Deepen backward integration into cryogenic storage manufacturing to offset equipment import compliance layers from Chinese regulatory enforcement. Prioritize corridor concession agreements along Rhine-Alpine and Rotterdam-Antwerp nodes before EU Alternative Fuels Infrastructure Regulation deployment targets saturate prime locations. For New Entrants and Emerging Players: Establish a beachhead in mobile station formats serving Polish and Czech regional operators bypassing wholesale supply contracts. Target agricultural and waste processing sites for small-scale liquefaction convergence with biomethane upgrading facilities. Pursue marine bunkering applications at secondary port clusters where emission control area compliance creates demand without incumbent saturation. For Investors and Strategic Acquirers: EU F-Gas Regulation refrigerant phase-downs reshape the acquisition landscape toward vendors with lower-global-warming-potential system redesigns already in certification. Long-term viability hinges on bridge-fuel positioning through hydrogen scale-up timelines rather than permanent LNG infrastructure lock-in. Monitor India's National Hydrogen Mission spillover effects as the critical signal for early-mover LNG station valuations along Delhi-Mumbai corridor routes.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Station Architecture Standardization | Compresses deployment timelines for Poland and Czech regional operators seeking rapid capacity scaling. |
| Small-Scale Liquefaction Convergence | Enables closed-loop fuel production at agricultural sites pairing biomethane upgrading with containerized units. |
| Marine Bunkering Infrastructure Buildout | Captures Rotterdam-Antwerp port range volumes under EU emission control area enforcement timelines. |
| Multi-Fuel Retail Integration | Requires costly diesel and CNG infrastructure reconfiguration at German transport hubs for cryogenic compatibility. |
| Cryogenic Technician Training Program Investment | Addresses specialized labor scarcity across European engineering markets for minus 162-degree system maintenance. |
Research Methodology
Desk research of customs trade data, EU regulatory filings, and equipment vendor technical specifications preceded structured interviews with cryogenic system engineers, fleet procurement directors, port authority fueling coordinators, and LNG station project developers. Primary fieldwork captured deployment timeline constraints, offtake contract structuring practices, and regulatory compliance cost layering across Germany, Netherlands, China, and India. Secondary validation drew from EPA Clean Air Act enforcement records, EU F-Gas Regulation implementation guidance, and MIIT GB standard certification databases. Bottom-up station deployment counts triangulated against top-down freight corridor demand modeling.
Assumptions held fixed include EU Fit for 55 mandate enforcement timelines, natural gas price corridor ranges, and battery-electric heavy-duty platform commercialization schedules across the projection horizon. Variable assumptions encompassed hydrogen infrastructure scale-up pacing, refrigerant technology substitution rates, and China-EU equipment trade flow stability. Segmentation dimensions modeled span station format, end-user archetype, application mode, and technology stack. CAGRs derived from volume trajectory analysis against infrastructure payback period thresholds, with cryogenic storage efficiency advances and small-scale liquefaction cost curves as primary industry-specific inputs.
Sensitivities concentrate around natural gas price volatility swings, electric drivetrain substitution acceleration, and regulatory timeline slippage for EU Alternative Fuels Infrastructure Regulation targets. Forecasts reflect documented assumptions regarding fleet conversion pacing and corridor concession availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Global Butane Gas Cartridges Market
Fuels
Marine Fuel Filter Market
Fuels
LPG Tanker Market
Fuels
Europe Black and Wood Pellets Market
Fuels
Smart Gas Solutions Market
Fuels
Singapore Bunker Fuel Market
Fuels
Renewable Heating Fuels Market
Fuels
Mobile Fuel Delivery Market
Fuels
Wood Pellet Market
Fuels
Middle-East and Africa Bunker Fuel Market
Fuels
South America Aviation Fuel Market
Fuels
Coal to Liquid Fuel (CTL) Market
Fuels
Global Chemical Logistics Market
Fuels
Mobile Fuel Storage Tank Market
Fuels
LPG Gas Cylinder Market
Fuels
Hydrogen Fuel Tanks Market