
 South America Defense Aircraft Aviation Fuel Market | 2026-2036
South America Defense Aircraft Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
South America Defense Aircraft Aviation Fuel Market Analytics
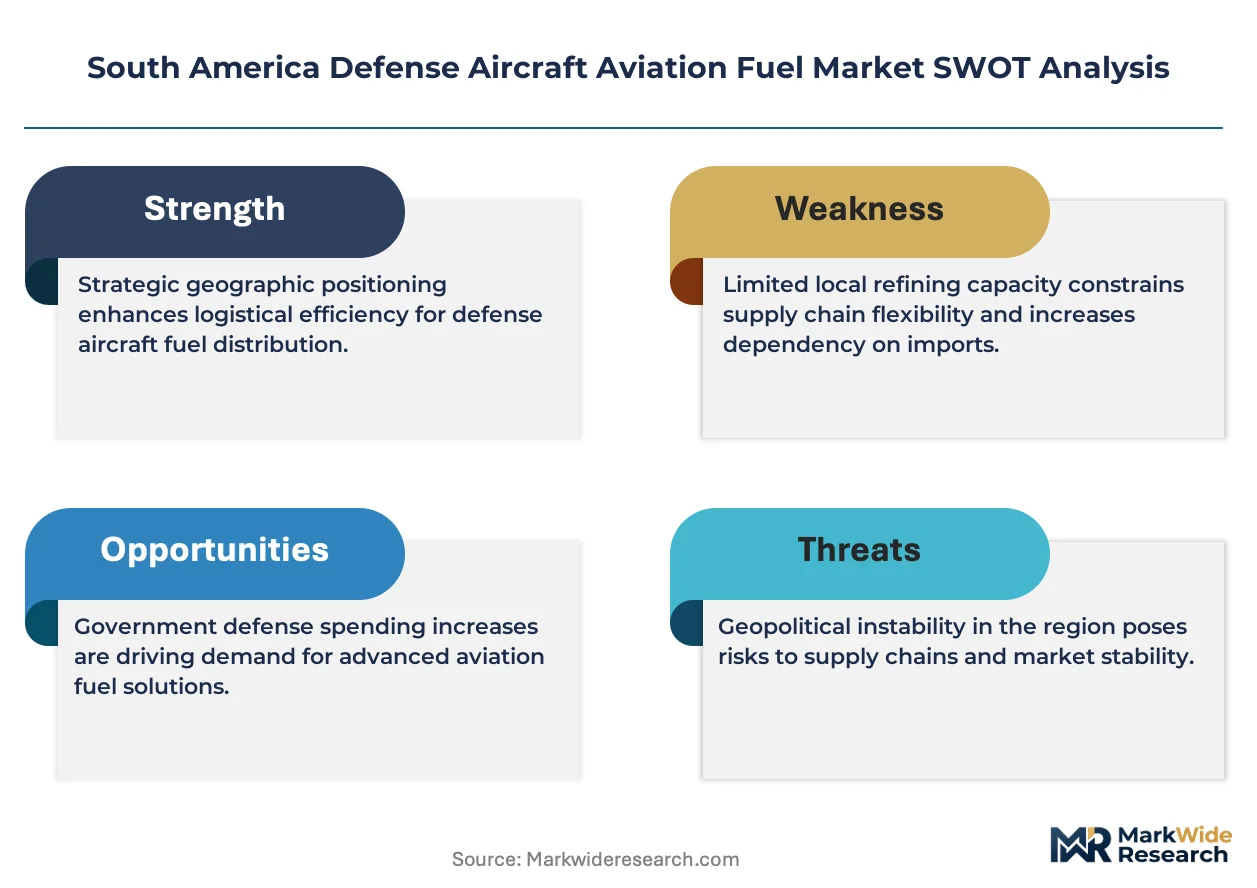
Brazilian refiners is pivoting toward higher jet fuel yields to meet defense procurement schedules. Petróleo Brasileiro S.A. leverages its integrated upstream-downstream network to secure military offtake contracts. YPF anchors Argentine supply through its Luján de Cuyo refinery complex. Shell PLC competes via strategic storage terminals along key Atlantic air corridors.
South America Defense Aircraft Aviation Fuel denotes kerosene-based turbine fuel meeting NATO F-34 or ASTM D1655 specifications, with flash points above 38°C and freeze points below -47°C for high-altitude combat operations. Its primary purpose is sustaining thrust output across variable thermal regimes in military propulsion systems. Jet A-1 dominates procurement volumes due to interoperability with NATO-standard platforms operated by regional air forces. Combat Aircraft applications generate premium margin pools given mission-critical purity requirements and specialized additive packages. Transport Aircraft segments sustain baseline volumes through predictable logistics scheduling.
Brazil's ANP, Argentina's Secretariat of Energy, and Chile's SEC collectively enforce sulfur caps, trace metal limits, and carbon disclosure protocols that reshape refinery investment priorities. These frameworks elevate compliance costs for importers while creating preferential access for domestic producers achieving certification. Stakeholders must track evolving biofuel blending mandates and their compatibility with legacy turbine engine warranties.
Market Dynamics
Brazil's ANP carbon intensity benchmarks are compressing refinery investment timelines while forcing specification upgrades across military fuel contracts. Argentine import substitution policies and Chilean SEC disclosure rules add layered compliance burdens that reshape competitive positioning among regional suppliers.
Growth Catalysts
- Fleet Modernization Cycles:Brazilian Air Force F-39 Gripen integration and Chilean F-16 Block 70 upgrades drive Jet A-1 procurement volumes. Combat aircraft sustainment programs anchor long-term offtake agreements with domestic refiners.
- ANP Specification Tightening:Brazil's national petroleum regulator mandates sulfur caps below 0.30% and aromatic limits that favor hydroprocessed kerosene streams. These standards create preferential procurement windows for certified domestic producers.
- Logistics Infrastructure Expansion:Strategic storage terminals along the Atlantic corridor reduce lead times for forward-deployed squadrons. Argentine pipeline reversals and Brazilian coastal bunkering networks improve supply security for rapid-response missions.
Market Restraints
- Crude Slate Volatility:Regional refiners process predominantly heavy-sour Latin American crudes with variable naphthenic content. Jet fuel yield optimization requires costly hydrocracker investments that strain mid-cap refinery balance sheets.
- Import Dependency Concentration:Bolivia and Paraguay lack indigenous refining capacity and rely on Brazilian or Argentine supply corridors. Pipeline capacity constraints and customs friction create vulnerability during operational surges.
- Additive Package Fragmentation:Military specifications require corrosion inhibitors, static dissipators, and icing suppressants with incompatible chemistries across NATO F-34, ASTM D1655, and national variants. Blending complexity elevates working capital requirements.
Strategic Opportunities
- Colombian Defense Expansion:Colombian Air Force Kfir replacement programs and new maritime patrol aircraft acquisitions open procurement channels previously dominated by U.S. supply arrangements. Local distribution partnerships with Ecopetrol create first-mover positioning.
- Synthetic Fuel Pathways:Fischer-Tropsch synthetic paraffinic kerosene from biomass gasification offers drop-in compatibility with legacy turbine warranties. ANP biofuel blending mandates toward 2030 establish offtake certainty for pilot plant investments.
- Digital Fuel Tracking:Blockchain-anchored provenance systems from wellhead to wingtip address SEC carbon disclosure requirements. Smart contracts automate compliance documentation for cross-border military logistics.
Industry Challenges
- Specialized Blending Expertise Scarcity:Military additive formulation requires chemists trained in MIL-DTL-83133 specifications. Regional universities produce petroleum engineers oriented toward commercial aviation rather than defense-grade purity requirements.
- Certification Timeline Compression:New fuel chemistries require 18-24 months of turbine engine OEM testing before warranty acceptance. Pratt & Whitney and General Electric validation queues create bottlenecks for sustainable aviation fuel introductions.
- Legacy System Integration Friction:Cold War-era storage tanks and pipeline coatings degrade when exposed to ultra-low-sulfur kerosene streams. Base infrastructure refurbishment competes with operational budgets for scarce defense funding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Defense Aircraft Aviation Fuel Market |
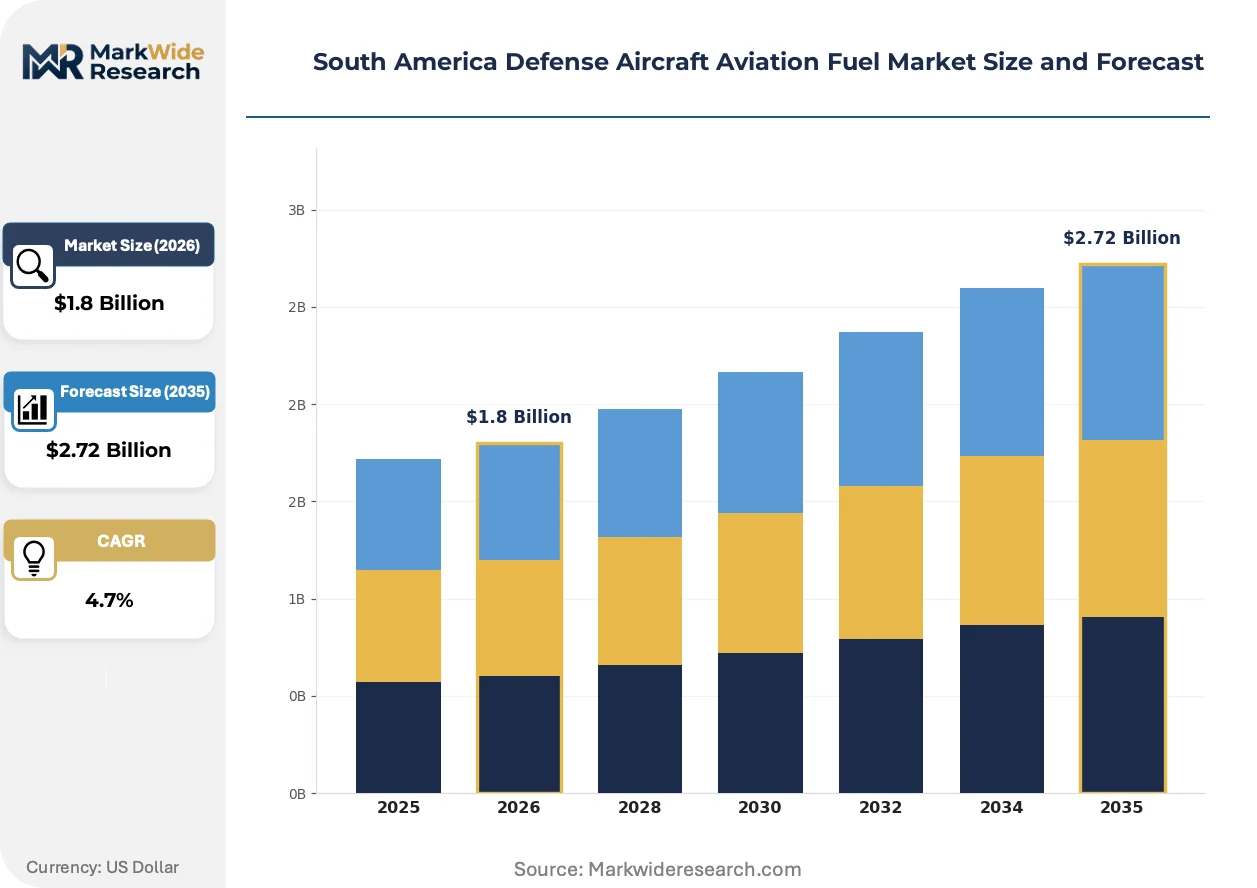
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, JP-5, JP-8 End User: Military Aviation, Government Agencies, Contractors, Defense Corporations Application: Combat Aircraft, Transport Aircraft, Reconnaissance Platforms, Training Aircraft Distribution Channel: Direct Sales, Online Platforms, Distributors, Retail |
| Companies Covered | Petróleo Brasileiro S.A., BP PLC, Repsol S.A., TotalEnergies SE, Shell PLC, Exxon Mobil Corporation, Pan American Energy S.L., YPF, Chevron Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Defense Aircraft Aviation Fuel Market Evolving Landscape
Electrification of ground support equipment and auxiliary power units is reshaping fuel consumption patterns at military airfields. Digital traceability systems and sustainable fuel pathways are converging to redefine procurement specifications across the continent.
Biomass-derived synthetic paraffinic kerosene is electrifying refinery investment priorities in Brazil. Petrobras pilots hydroprocessed esters and fatty acids co-processing at its Paulínia facility to meet ANP biofuel mandates. Defense procurement officers are electrifying contract terms to include carbon intensity scoring alongside traditional performance metrics.
Chile's SEC environmental disclosure protocols now require Scope 3 emissions reporting from military fuel suppliers. This regulatory pressure forces Argentine and Brazilian refiners to implement mass-balance certification systems for blended sustainable aviation fuels. Transport aircraft operators face the steepest compliance costs given higher annual consumption volumes compared to combat fleets.
Long-term offtake agreements are displacing spot market purchases as the dominant procurement modality. Brazilian Air Force multi-year contracts with Petrobras establish price bands indexed to international jet fuel benchmarks rather than domestic posted prices. This structural shift concentrates buyer power among defense ministries while squeezing margins for independent importers serving smaller air forces.
South America Defense Aircraft Aviation Fuel Market Segmentation
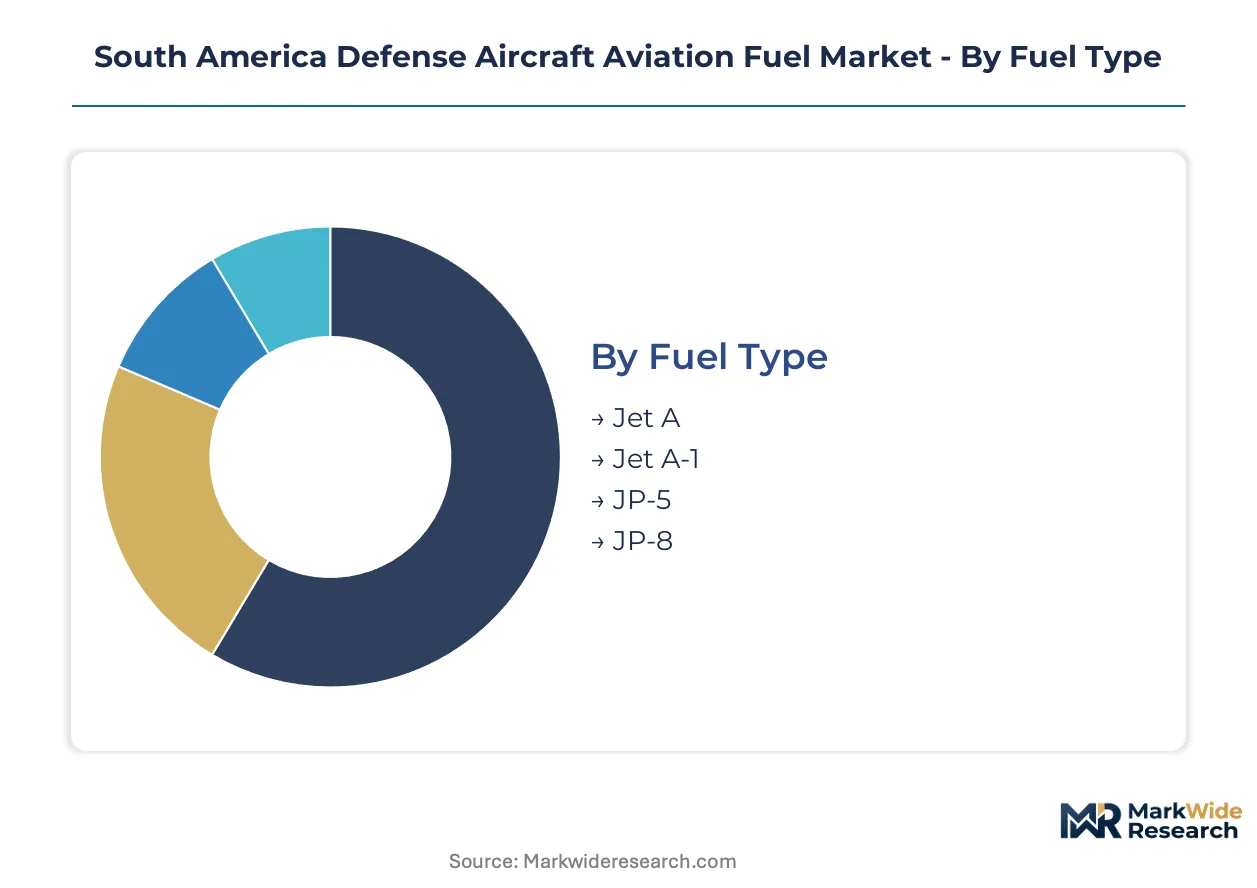
Defense aviation fuel procurement in South America operates through rigid certification hierarchies that determine supplier eligibility and contract value. Each segment carries distinct specification burdens, from NATO F-34 compliance for combat fleets to national variants for training aircraft, creating tiered vendor qualification barriers.
Fuel Type:
Certification requirements stratify sharply across fuel grades, with military specifications demanding additive packages and purity thresholds beyond commercial aviation standards.
- Jet A:Lower freeze point specification (-40°C) limits deployment to medium-altitude transport missions. Brazilian Air Force cargo squadrons favor this grade for domestic logistics routes where extreme cold weather performance is non-critical, though ANP aromatic caps are compressing available supply streams.
- Jet A-1:NATO F-34 interchangeability and -47°C freeze point specification dominate regional procurement. Chilean F-16 Block 70 upgrades and Brazilian Gripen integration anchor demand concentration, with ANP sulfur mandates below 0.30% forcing hydroprocessed refinery investments.
- JP-5:Flash point above 60°C and low-volatility formulation designed for carrier-based operations. Limited South American naval aviation requirements restrict procurement to Argentine and Brazilian maritime patrol squadrons with specialized storage infrastructure.
- JP-8:MIL-DTL-83133 specification with corrosion inhibitor and icing suppressant packages. Forward-deployed NATO cooperation missions drive intermittent demand, though regional stockpiling remains minimal due to additive incompatibility with legacy turbine warranties.
Jet A-1 sits at the top of the volume ranking, with JP-8 climbing the fastest through multinational exercise commitments.
End User:
Procurement authority concentration determines contract scale, with centralized defense ministries wielding price-setting power over fragmented contractor demand.
- Military Aviation:National air forces operate through multi-year offtake agreements indexed to international benchmarks. Brazilian Air Force contracts with Petrobras establish regional pricing bands, while Chilean and Argentine squadrons negotiate volume commitments against strategic storage access.
- Government Agencies:Presidential transport detachments and border patrol aviation units procure through civilian-military hybrid specifications. ANP disclosure requirements and SEC carbon protocols add compliance layers absent from pure military contracts.
- Contractors:Third-party logistics providers serving forward operating bases operate on spot-market exposure with elevated working capital requirements.
- Defense Corporations:Embraer and similar OEMs maintain test-flight fuel inventories with specialized additive blending for prototype certification.
Military Aviation commands the dominant procurement volume, with Contractors expanding most quickly through privatized base support arrangements.
Application:
Mission-criticality dictates purity premiums, with combat platforms tolerating zero specification deviation against transport fleet operational flexibility.
- Combat Aircraft:Afterburner thermal stability and high-g maneuver fuel system demands require MIL-DTL-83133E compliance. Colombian Kfir replacements and Peruvian MiG-29 sustainment programs concentrate demand for corrosion-inhibited, static-dissipative formulations.
- Transport Aircraft:Predictable consumption profiles and lower thermal stress permit broader supplier qualification. Brazilian KC-390 logistics and Argentine C-130 Hercules fleets sustain baseline refinery throughput through scheduled maintenance windows.
- Reconnaissance Platforms:High-altitude endurance missions demand exceptional thermal stability and low-temperature viscosity performance.
- Training Aircraft:Subsonic turboprop and jet trainer fleets operate on relaxed aromatic limits with cost-optimized procurement.
Transport Aircraft anchor procurement tonnage, with Reconnaissance Platforms gaining share fastest through maritime surveillance expansion.
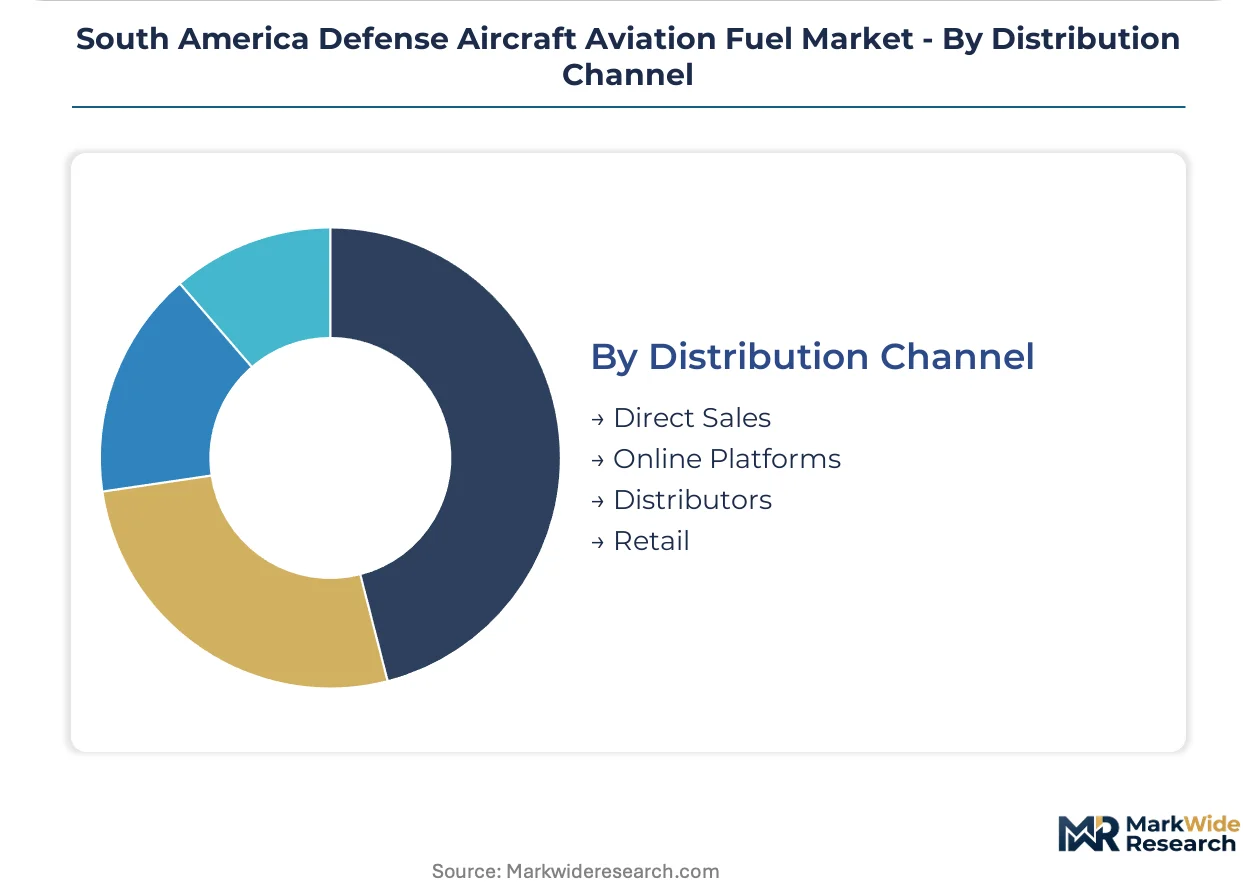
Distribution Channel:
Supply security requirements favor direct relationships over intermediated channels, with strategic storage access determining competitive positioning.
- Direct Sales:Petrobras and YPF supply defense ministries through dedicated military product streams with segregated storage and quality documentation. Long-term contracts incorporate force majeure clauses for operational surge scenarios.
- Distributors:Regional fuel traders with Atlantic corridor terminal access serve smaller air forces lacking direct refinery relationships. Bolivian and Paraguayan import dependency flows through this channel despite customs friction vulnerabilities.
- Online Platforms:Digital procurement portals for non-critical ground support equipment and lubricants remain marginal for bulk aviation fuel.
- Retail:Commercial airport FBO networks handle incidental military detachments on civilian airfields with specification bridging protocols.
Direct Sales dominates contract value, with Distributors showing the steepest expansion trajectory through Andean corridor infrastructure development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands procurement volumes that dwarf Argentine throughput, yet Chilean specification tightening is compressing supplier margins more aggressively than anywhere else on the continent. Regional demand concentrates along Atlantic corridor refining clusters, with ANP mandates and SEC disclosure protocols reshaping investment priorities across national boundaries.
Brazil
Embraer defense programs and FAB operational tempo anchor continental procurement volumes. ANP sulfur caps below 0.30% and aromatic limits force hydroprocessed kerosene investments at Paulínia and other coastal refineries. Rio de Janeiro and São Paulo states concentrate strategic storage infrastructure serving forward-deployed squadrons.
Argentina
YPF's Luján de Cuyo refinery complex sustains military offtake through import substitution frameworks. The Secretariat of Energy enforces trace metal limits that elevate compliance costs for cross-border suppliers. Buenos Aires province hosts presidential transport detachments with hybrid civilian-military procurement specifications.
Chile
F-16 Block 70 upgrades drive Jet A-1 procurement concentration in Santiago and Antofagasta regions. SEC carbon disclosure protocols now mandate Scope 3 emissions reporting from military fuel suppliers. Northern mining corridor infrastructure supports maritime patrol aviation logistics scheduling.
Colombia
Kfir replacement programs and new maritime patrol acquisitions open procurement channels beyond traditional U.S. supply arrangements. The national petroleum regulator enforces sulfur benchmarks aligned with ANP standards. Bogotá and Barranquilla clusters concentrate distribution partnerships with Ecopetrol for defense-grade product streams.
Peru
MiG-29 sustainment programs sustain demand for corrosion-inhibited formulations in Andean operational environments. Import dependency flows through Brazilian and Argentine supply corridors with customs friction vulnerabilities. Lima and Callao metropolitan areas anchor strategic storage access for rapid-response missions.
South America Defense Aircraft Aviation Fuel Market Competitive Landscape
Brazilian producers anchor the integrated refinery tier; European and North American trading specialists hold storage and distribution positions along Atlantic corridors. Market structure concentrates around national oil companies with captive upstream-downstream networks, supplemented by international majors with terminal access. Two archetypes dominate: integrated state-controlled refiners with military offtake contracts, and multinational traders with strategic storage assets. Competitive moves center on long-term contract indexing to international benchmarks and infrastructure partnerships for forward logistics.
Among Brazil-based integrated suppliers, Petróleo Brasileiro S.A. exemplifies the state-controlled archetype with captive refinery capacity and defense ministry relationships. YPF represents Argentine supply concentration through its Luján de Cuyo complex. Shell PLC occupies a position among Atlantic corridor specialists with storage terminal networks serving smaller air forces lacking direct refinery access.
| Leading Market Players |
|---|
| Petróleo Brasileiro S.A. |
| BP PLC |
| Repsol S.A. |
| TotalEnergies SE |
| Shell PLC |
| Exxon Mobil Corporation |
| Pan American Energy S.L. |
| YPF |
| Chevron Corporation |
| Others |
Value Network & Pricing Analysis
Platts Singapore Jet Kerosene assessments cascade through Brazilian coastal refineries into three distinct procurement tiers. ANP sulfur mandates and hydroprocessed yield premiums compress distributor margins while elevating direct-contract pricing power for Petrobras and YPF.
Pricing Analysis
Distributor margins absorb the steepest compression as ANP certification costs and additive blending complexity elevate working capital requirements. Long-term offtake agreements indexed to international benchmarks dominate procurement for Brazilian and Chilean air forces, while spot-market exposure concentrates among Bolivian and Paraguayan importers lacking direct refinery relationships. Price differentiation hinges on NATO F-34 certification tier and strategic storage access, with transport aircraft operators exhibiting highest sensitivity due to predictable volume scheduling against combat fleet mission-critical premiums.
Supply Chain Analysis
Heavy-sour Latin American crude supply rests on Venezuelan, Colombian, and Brazilian upstream production with variable naphthenic content. Hydrocracker investments, corrosion inhibitor formulations, and icing suppressant packages constitute critical input dependencies. Single-source vulnerability concentrates in Brazilian coastal refining clusters serving Atlantic corridor demand. Distribution runs through dedicated military product streams with segregated storage and quality documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in hydroprocessed kerosene streams as ANP aromatic limits and carbon intensity benchmarks elevate premium-tier procurement. Synthetic fuel pathway investments offer downstream cost control against crude slate volatility.
For Market Incumbents: Cement defense ministry relationships through multi-year offtake agreements with force majeure clauses for operational surge scenarios. Lock in strategic storage partnerships along Atlantic corridors to preempt emerging traders from capturing Andean corridor expansion. Prioritize hydrocracker yield optimization investments at Paulínia and Luján de Cuyo complexes to defend position against import substitution pressures.
For New Entrants and Emerging Players: Digital procurement portals for non-critical ground support equipment offer lowest barrier entry before bulk fuel qualification. Target Colombian Kfir replacement programs and Peruvian MiG-29 sustainment channels where Ecopetrol partnerships remain underdeveloped. Pursue mass-balance certification systems for blended sustainable aviation fuels to capture ANP biofuel mandate premiums.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap refiners lack hydrocracker capacity to meet ANP sulfur caps below 0.30 percent. Acquisition candidates include Argentine and Chilean terminal operators with SEC disclosure protocol compliance infrastructure. Watch for Pratt & Whitney and General Electric synthetic fuel warranty acceptance as inflection signal for pilot plant investment viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocracker Capacity Expansion | ANP sulfur mandates below 0.30% force yield optimization investments at coastal refineries. |
| Long-term Military Offtake Agreement | Multi-year contracts indexed to international benchmarks concentrate buyer power among defense ministries. |
| Synthetic Fuel Pilot Plant Investment | Fischer-Tropsch biomass gasification offers drop-in compatibility with legacy turbine warranties. |
| Strategic Storage Partnership | Atlantic corridor terminal access reduces lead times for forward-deployed squadrons. |
| Mass-Balance Certification Program | Blockchain-anchored provenance systems automate SEC carbon disclosure compliance documentation. |
Research Methodology
Multiple input streams — refinery operations data, defense procurement records, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary interviews with fuel supply specialists, ANP compliance officers, defense ministry procurement directors, and strategic storage terminal operators informed demand modeling assumptions. Secondary validation drew from ANP regulatory bulletins, SEC environmental disclosure protocols, customs and trade flow databases, and refinery capacity utilization reports.
Data-stream reconciliation across supply-side capacity, demand-side fleet modernization schedules, and regulatory compliance timelines anchored the analytical framework. Segmentation dimensions modeled include fuel grade certification tier, end-user procurement authority concentration, mission-criticality application tier, and distribution channel structure. CAGRs were derived from volume trajectory analysis against fleet integration timelines and hydroprocessed yield expansion curves.
The model assumes a particular technology adoption path; alternative pathways for synthetic paraffinic kerosene commercialization would alter the outlook. Forecasts reflect assumptions regarding ANP biofuel mandate enforcement timing and NATO F-34 specification harmonization across regional air forces. Material deviation in turbine engine OEM warranty acceptance queues or crude slate availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
India City Gas Distribution (CGD) Market
Fuels
India Retail Fuel Market
Fuels
CNG Dispenser Market
Fuels
Industrial Fuel Filter Market
Fuels
Coal Briquettes Market
Fuels
Coal Gasification Market
Fuels
China LNG Market
Fuels
United States Coal Market
Fuels
Marine Fuel Filter Market
Fuels
Turbine Drip Oil Market
Fuels
High-Temperature Industrial Burner Market
Fuels
Emulsified Fuel Market
Fuels
Solid Fuel Tablet Market
Fuels
Mobile Gas Pumping System Market
Fuels
Aviation Fuel Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market