
 Methane Market | 2026-2036
Methane Market Size, Share, and Industry Trends Forecast 2026-2036
Methane Market Outlook
Chemical feedstock demand is realigning the Methane Market as petrochemical complexes expand ethylene and ammonia output. Shell plc leverages integrated LNG-to-chemicals pathways across its Qatari and Australian assets. BP plc anchors its position through biomethane ventures in the United States and Brazil. Exxon Mobil Corporation competes on large-scale steam cracker feedstock contracts in the Gulf Coast corridor.
Methane is a colorless, odorless hydrocarbon gas with chemical formula CH₄ and boiling point minus 161.5 degrees Celsius, serving primarily as a combustion fuel and chemical building block for hydrogen, methanol, and ammonia synthesis. The electricity generation segment dominates volume offtake through combined-cycle gas turbine installations, though chemical feedstock applications capture superior margins tied to ethylene and fertilizer economics. Biogas upgrading technology is expanding fastest in Europe and North America as landfill and agricultural waste streams convert to pipeline-quality biomethane.
The EPA enforces methane emission standards across US oil and gas infrastructure under updated Greenhouse Gas Reporting Program rules, while the EU Methane Regulation mandates satellite monitoring and leak detection protocols for imported gas. China's Ministry of Ecology and Environment imposes fugitive emission controls on coalbed methane and shale gas operations. Stakeholders must weigh regulatory compliance costs against feedstock contract durations when committing to new supply agreements.
Market Dynamics
The Methane Market is being restructured by the EU Methane Regulation's satellite monitoring mandate, which forces infrastructure operators to deploy continuous leak detection systems across transmission networks and import terminals.
Growth Catalysts
- Coal-to-gas switching policies:China's Ministry of Ecology and Environment enforces fuel substitution targets that sustain LNG import growth through coastal regasification terminals.
- Biogas upgrading technology:Anaerobic digester operators in Germany and the Netherlands deploy membrane separation and pressure swing adsorption to produce pipeline-quality biomethane.
- Petrochemical feedstock demand:Ethylene crackers in South Korea and Saudi Arabia expand naphtha-to-ethane flexibility, tightening spot market liquidity for methane-rich feedstock.
Market Restraints
- Upstream supply concentration:Qatar and Australia control over half of flexible LNG export capacity, creating price volatility during unplanned outages.
- Fugitive emission liability:The EPA's updated Greenhouse Gas Reporting Program imposes measurement-based penalties that inflate operating costs for Permian Basin producers.
- Renewable hydrogen substitution:Electrolyzer projects in Spain and Chile threaten methane-based steam methane reforming for ammonia and methanol synthesis.
Strategic Opportunities
- Certified low-methane gas:The EU Methane Regulation's import standards create premium pricing tiers for verified low-emission supply from Norwegian and Algerian fields.
- Agricultural waste valorization:Dairy clusters in California's Central Valley and Denmark's Jutland peninsula convert manure streams to biomethane through covered lagoon digesters.
- Small-scale LNG:Bunkering infrastructure at the Port of Singapore and Rotterdam enables marine fuel substitution for container and cruise vessels.
Industry Challenges
- Optical gas imaging expertise:Field technicians qualified to operate thermal cameras for leak detection remain scarce in emerging production basins.
- Legacy pipeline integrity:Cast iron distribution networks in older European cities require billion-dollar replacement programs to meet tightness standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methane Market |
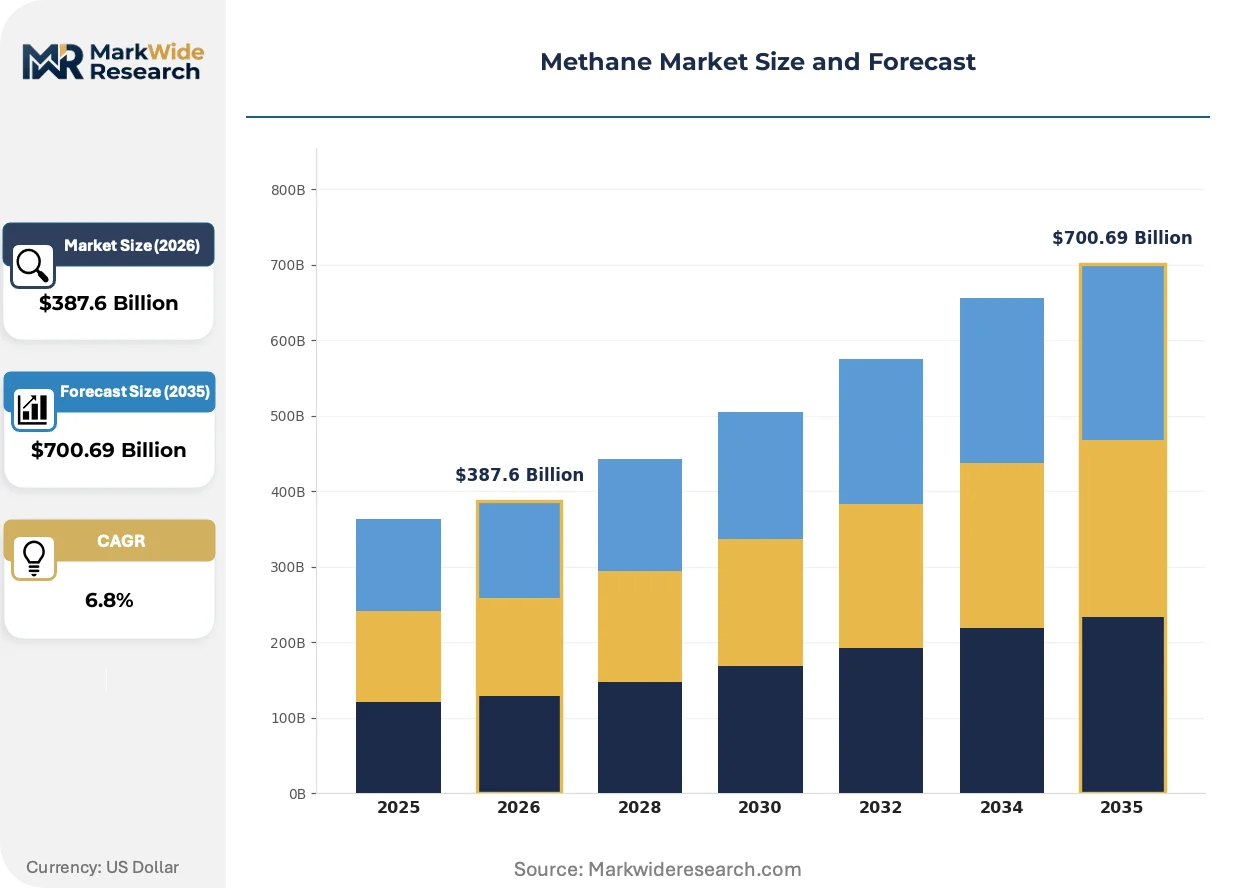
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Electricity Generation, Transportation Fuels, Chemical Feedstock, Residential Heating Technology: Biogas Upgrading, Methanation, Steam Reforming, Pyrolysis End User: Utilities, Industrial Sector, Commercial Buildings, Households Delivery Mode: Pipelines, LNG, CNG, Truck Transport |
| Companies Covered | BP plc, Shell plc, China National Petroleum Corporation, Exxon Mobil Corporation, Chevron Corporation, TotalEnergies SE, Linde plc, Air Liquide SA, Air Products and Chemicals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methane Market Strategic Shifts
Measurement technology and certification protocols are reshaping how methane is produced, traded, and consumed across power generation, chemical synthesis, and transport fuel applications.
Distributed optical fiber sensing is decentralizing leak detection architecture across transmission pipelines. Midstream operators in the United States and Norway embed fiber-optic cables along pipeline rights-of-way to detect temperature and acoustic anomalies indicating gas escape. This distributed approach reduces reliance on periodic aerial surveys and enables real-time alert generation to control centers.
The EU Methane Regulation mandates satellite-based monitoring of upstream production sites supplying the European market. Operators must submit empirical measurement data rather than engineering estimates for emission inventories. This transparency requirement accelerates investment in continuous monitoring hardware at Algerian and Norwegian export facilities.
Chemical buyers are consolidating procurement through long-term index-linked contracts rather than spot market exposure. Ethylene producers in South Korea and Belgium negotiate fifteen-year supply agreements with price collars to hedge against Henry Hub and TTF volatility. This contract structure shifts volume risk to producers while securing feedstock for cracker expansion projects.
Methane Market Segmentation
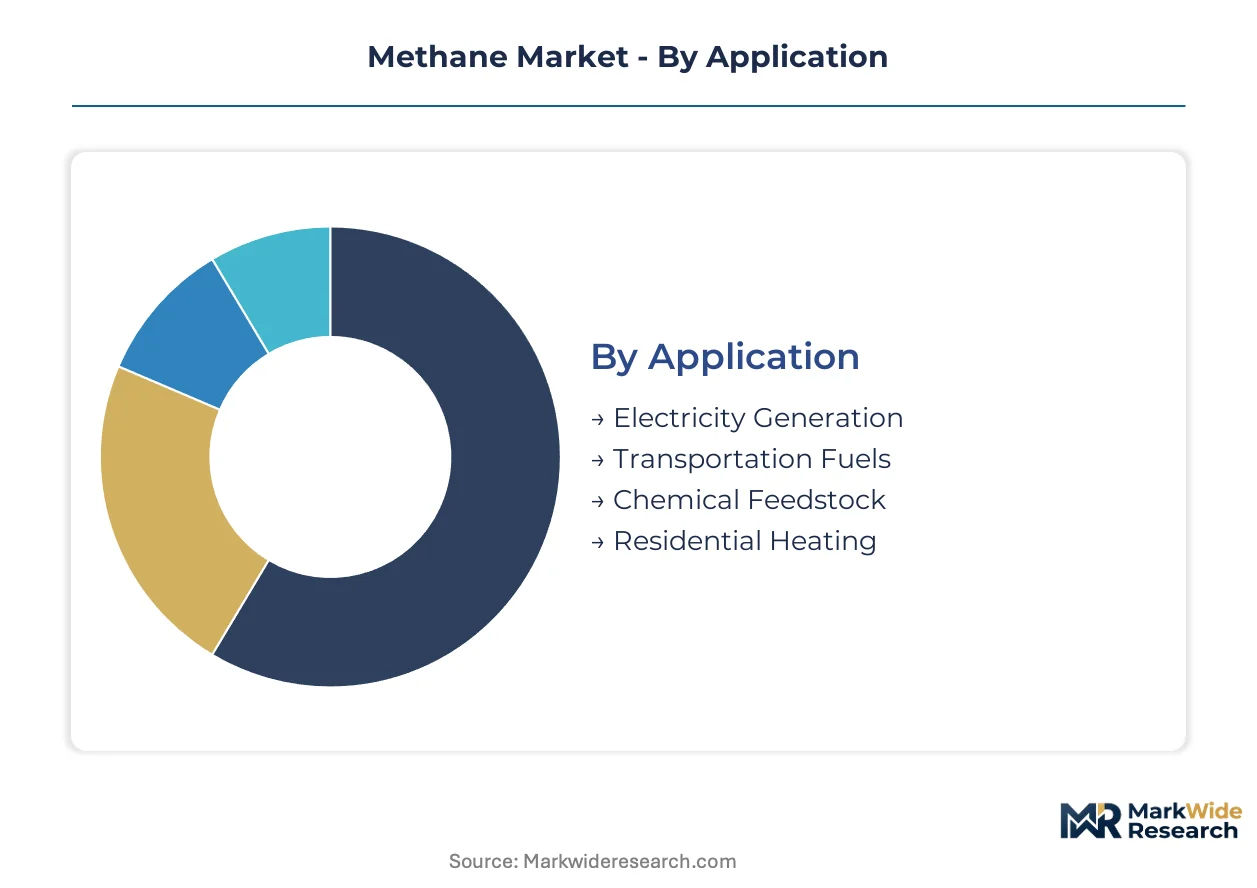
Methane market segmentation reveals how production technology, delivery infrastructure, and end-use applications create distinct competitive arenas. Each axis carries different margin profiles, regulatory exposure, and capital intensity requirements that reshape supplier positioning.
Application:
Chemical synthesis pathways and combustion technologies define specification requirements across methane consumption clusters.
- Electricity Generation:Combined-cycle gas turbines dominate volume offtake, with utilities in Texas and Gujarat prioritizing baseload dispatch flexibility. Grid balancing requirements sustain demand despite renewable penetration.
- Chemical Feedstock:Ethylene crackers and ammonia synthesis units demand pipeline-grade methane with tight sulfur and CO₂ specifications. South Korean petrochemical complexes anchor procurement through fifteen-year index-linked contracts.
- Transportation Fuels:Marine bunkering at Singapore and Rotterdam drives LNG-fuelled vessel adoption. Stringent IMO sulfur caps accelerate dual-fuel engine retrofits.
- Residential Heating:District heating networks in Denmark and Netherlands convert from coal to gas-fired cogeneration. Seasonal demand peaks strain storage injection capacity.
Chemical Feedstock leads on scale; Transportation Fuels leads on momentum.
Technology:
Conversion pathways span biological, catalytic, and thermal processes with divergent carbon intensity profiles.
- Steam Reforming:Dominates hydrogen and syngas production through nickel-catalyst tube reactors operating at 800-900°C. Gulf Coast refineries integrate reforming units with carbon capture retrofits to meet EPA emission thresholds.
- Biogas Upgrading:Membrane separation and pressure swing adsorption purify landfill and agricultural digester output to pipeline specifications. German anaerobic digester clusters deploy covered lagoon systems across Lower Saxony dairy operations.
- Methanation:Catalytic hydrogenation of CO₂ produces synthetic methane for grid injection. Danish power-to-gas pilots validate electrolyzer-integrated systems at scale.
- Pyrolysis:Thermal decomposition of organic waste yields methane-rich syngas alongside biochar. Japanese municipal solid waste facilities deploy plasma arc reactors in Osaka and Yokohama.
Steam Reforming leads on scale; Biogas Upgrading leads on momentum.
End User:
Contract structures and procurement sophistication vary sharply across customer scale and sector.
- Utilities:Vertically integrated gas-electric portfolios in Florida and Alberta negotiate long-term supply agreements with price collars. Load forecasting accuracy determines storage contracting strategy.
- Industrial Sector:Fertilizer and petrochemical producers prioritize feedstock security over price optimization. Saudi Arabian ethylene crackers secure dedicated LNG offtake from Qatari export trains.
- Commercial Buildings:Cogeneration installations in hospitals and data centers require interruptible supply contracts. Tokyo district cooling networks anchor distributed generation demand.
- Households:Price-regulated distribution tariffs constrain supplier margins. Italian and Polish residential markets exhibit highest seasonal demand volatility.
Utilities lead on scale; Industrial Sector leads on momentum.
Delivery Mode:
Transport economics and infrastructure lock-in determine market access and pricing power.
- Pipelines:High-capacity transmission networks connect production basins to demand centers. Permian-to-Gulf Coast corridors and Russian-European trunklines represent highest throughput arteries.
- LNG:Liquefaction and regasification terminals enable intercontinental arbitrage. Qatar and Australia control dominant export capacity positions.
- CNG:Compressed gas serves fleet vehicle refueling and stranded industrial loads. Indian city gas distribution networks expand CNG station coverage under PNGRB licensing.
- Truck Transport:Cryogenic and compressed tube trailers supply off-grid industrial sites. California dairy biogas projects rely on trucked biomethane for pipeline injection.
Pipelines lead on scale; LNG leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin anchors North American methane supply expansion, while Qatari and Australian export terminals reshape intercontinental trade flows. Regulatory divergence across major demand centers is fragmenting procurement strategies. Infrastructure investment concentrates in coastal regasification corridors serving chemical and power generation clusters.
United States
Gulf Coast ethylene crackers and hydrogen hubs drive feedstock demand from Louisiana to Texas. The EPA enforces measurement-based emission penalties under updated Greenhouse Gas Reporting Program rules. Permian Basin producers deploy optical gas imaging across Delaware and Midland sub-basins to satisfy leak detection mandates.
China
Coal-to-gas substitution targets sustain LNG import growth through Guangdong and Fujian terminals. The Ministry of Ecology and Environment imposes fugitive emission controls on coalbed methane and shale gas operations. Yangtze River Delta chemical complexes anchor long-term procurement contracts with Qatari suppliers.
Germany
Anaerobic digester clusters in Lower Saxony convert agricultural waste to pipeline-quality biomethane. The EU Methane Regulation mandates satellite monitoring and empirical measurement for all imported gas. Industrial demand concentrates in Ludwigshafen and Leverkusen chemical corridors seeking low-emission feedstock certification.
Qatar
North Field expansion trains cement flexible LNG export dominance serving Asian and European buyers. National regulators align measurement protocols with EU import standards ahead of 2027 compliance deadlines. Ras Laffan Industrial City integrates carbon capture retrofits with liquefaction infrastructure.
Australia
Pluto and Wheatstone trains supply Japanese and South Korean utility and industrial buyers under long-term contracts. The National Greenhouse and Energy Reporting Scheme tightens upstream emission quantification requirements. Western Australia offshore platforms deploy continuous monitoring systems across Carnarvon and Browse basins.
Methane Market Competitive Environment
Capacity expansion dominates the current landscape as integrated majors and national oil companies commit liquefaction trains and carbon capture retrofits. The market structure concentrates around state-linked exporters controlling flexible supply and integrated majors with downstream chemical integration. Two strategic archetypes prevail: vertically integrated LNG-to-chemicals operators and pure-play upstream exporters with cost-advantaged resource bases. Competitive positioning hinges on low-emission certification access and long-term contract tenor security.
Among European-integrated majors, BP plc and Shell plc exemplify divergent strategic vectors within the competitive set. BP plc anchors its positioning through biomethane venture exposure across North American and Brazilian agricultural waste streams. Shell plc occupies the integrated LNG-to-chemicals archetype through Qatari and Australian asset control. Exxon Mobil Corporation represents the Gulf Coast feedstock security model, competing on large-scale steam cracker contract volumes.
| Leading Market Players |
|---|
| BP plc |
| Shell plc |
| China National Petroleum Corporation |
| Exxon Mobil Corporation |
| Chevron Corporation |
| TotalEnergies SE |
| Linde plc |
| Air Liquide SA |
| Air Products and Chemicals Inc. |
| Others |
Value Chain & Pricing Dynamics
The EU Methane Regulation's satellite monitoring mandate gates qualified supply access and premium-tier pricing for verified low-emission cargoes. Buyers in Germany and Belgium now pay certification-linked premiums for Norwegian and Algerian supply while spot discounts widen for unverified sources.
Pricing Analysis
Distributor margins on LNG cargoes compress under long-term index-linked contract structures favored by South Korean ethylene crackers. Pricing stratifies across certified low-methane, standard pipeline-grade, and unverified spot tiers based on emission measurement rigor and carbon intensity scores. Cost compression in the spot tier intensifies as Qatari and Australian export concentration limits alternative sourcing. Chemical feedstock buyers exhibit lowest price sensitivity due to cracker margin economics, while municipal utilities face highest sensitivity from regulated tariff caps.
Supply Chain Analysis
Feedstock supply rests on Qatari North Field expansion trains, Australian Pluto and Wheatstone facilities, and Permian Basin shale gas operations. Key inputs include cryogenic liquefaction hardware, specialized membrane separation units for biogas upgrading, and continuous optical gas imaging systems. Single-source vulnerability concentrates in Qatari flexible export capacity controlling marginal supply pricing. Distribution runs through long-term offtake contracts to Asian regasification terminals, with spot cargoes clearing at Rotterdam and Singapore trading hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Methane Market functions as a stable compounder anchored by irreplaceable chemical feedstock demand from ethylene and ammonia synthesis pathways.
For Market Incumbents: Lock in fifteen-year index-linked supply contracts with South Korean and Belgian chemical complexes before renewable hydrogen electrolyzer projects reach scale. Secure backward integration into carbon capture retrofits at Gulf Coast reforming facilities to defend margin position against EPA measurement-based penalties. Prioritize certification investment for EU Methane Regulation compliance to access premium pricing tiers. For New Entrants and Emerging Players: Capture agricultural waste valorization opportunities in California's Central Valley and Denmark's Jutland peninsula through covered lagoon digester projects. The biogas upgrading segment offers lowest competitive density and fastest regulatory tailwinds. Lead with power-to-gas pilot partnerships with German district heating utilities seeking synthetic methane grid injection. For Investors and Strategic Acquirers: Roll-up economics work for regional biomethane developers because fragmented dairy and landfill feedstock sources resist single-asset scale. Five-to-ten year viability hinges on EU import standard enforcement breadth. Watch for satellite monitoring data disclosure deadlines as inflection indicators for certified supply scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | Gulf Coast reforming units integrate capture to satisfy EPA emission thresholds and preserve feedstock contracts. |
| Biogas Upgrading Scale-Up | German anaerobic digester clusters deploy membrane systems to capture EU biomethane injection premiums. |
| Long-term Supply Agreement | South Korean crackers secure Qatari LNG offtake with price collars hedging Henry Hub volatility. |
| Certification Program | Algerian and Norwegian export facilities adopt empirical measurement protocols for EU import compliance. |
| Joint Venture | California dairy clusters partner with midstream operators to monetize manure-to-biomethane pathways. |
Study Parameters
Direct dialogue with LNG trading desk heads, petrochemical procurement managers, biogas project developers, and regulatory compliance officers grounded qualitative findings. Secondary validation drew from EIA natural gas data, IEA methane tracker reports, FERC infrastructure filings, and EU regulatory impact assessments. Bottom-up project databases triangulated against top-down trade flow analysis to verify volume estimates.
Segment-level value outputs derived from modeling across application clusters, technology pathways, delivery modes, and end-user contract structures. CAGRs emerged from production capacity buildout schedules, demand elasticity estimates for chemical feedstock substitution, and regulatory compliance cost trajectories. Key inputs included Qatari and Australian export train commissioning timelines and EU Methane Regulation enforcement phase-in assumptions.
Upstream supply disruption, renewable hydrogen cost parity acceleration, and EU import standard delay or dilution are the dominant revision risks. Forecasts embed assumptions around satellite monitoring technology deployment rates and carbon border adjustment mechanism coverage scope. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Wood Charcoal Market
Fuels
Marine Fuel Filter Market
Fuels
LNG As a Fuel Market
Fuels
North America Wood Pellet Market
Fuels
Bunker Fuel Market
Fuels
Canada Coal Market
Fuels
Refuse Derived Fuel Market
Fuels
LPG Tanker Market
Fuels
United States LNG Bunkering Market
Fuels
United Arab Emirates Fuel Station Market
Fuels
Germany Bunker Fuel Market
Fuels
India Coal Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Saudi Arabia Automotive Fuels Market
Fuels
UAE Chemical Logistics Market