
 Composite Overwrapped Pressure Vessels (Copvs) Market | 2026-2036
Composite Overwrapped Pressure Vessels (Copvs) Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Overwrapped Pressure Vessels (Copvs) Market Insights
Performance-based leasing for hydrogen refueling infrastructure is repositioning how COPV suppliers monetize asset lifecycles. Hexagon Composites ASA leverages its integrated liner manufacturing to control quality through the full stack. Luxfer Holdings PLC anchors its position in aerospace actuation through sustained R&D on aluminum-lined hybrids. Worthington Industries dominates industrial gas storage with manufacturing scale across multiple continents.
Composite overwrapped pressure vessels are cylindrical pressure containers comprising a metallic or polymeric liner reinforced with high-strength fiber filaments wound in precise helical and hoop patterns, typically designed to operate at pressures from 3,000 to 10,000 psi depending on service application. These vessels store compressed gases for mobility, energy, and industrial systems where weight reduction and fatigue resistance outperform all-metal alternatives. Type IV vessels, with polymer liners and full carbon fiber overwrap, command the fastest growth trajectory as hydrogen fuel cell deployment expands. Space exploration applications retain premium margin pools due to qualification rigor and low-volume, high-specification procurement. Carbon fiber material grades concentrate value capture among specialized prepreg suppliers with aerospace-certified supply chains.
The U.S. Department of Transportation's FMVSS 304 and ISO 19881 shape hydrogen storage vessel design mandates, while the EU's Pressure Equipment Directive and CE marking govern market access across European member states. Japan's METI hydrogen roadmap and associated JIS standards influence specifications for Asian supply chain integration. Stakeholders must monitor evolving certification reciprocity between DOT, ECHA, and METI frameworks as regional hydrogen corridors mature and cross-border vessel deployment accelerates.
Market Dynamics
Type IV vessel qualification timelines and carbon fiber supply concentration are compressing procurement cycles while elevating entry barriers for new fabricators. The tension between hydrogen mobility fleet expansion and certified manufacturing capacity limits is forcing buyers into multi-year offtake commitments.
Growth Catalysts
- FMVSS 304 Certification Stringency:The U.S. DOT's tightened hydrogen storage standards are filtering out marginal suppliers and concentrating orders among qualified fabricators with established testing protocols.
- South Korean Hydrogen Mobility Procurement:Government-backed fleet deployment programs are accelerating Type IV vessel orders through mandated domestic content requirements and fuel cell vehicle subsidies.
- Carbon Fiber Prepreg Advancement:T800H and T1100G fiber grades with tailored epoxy matrices are extending fatigue life beyond 15,000 cycles for heavy-duty transport applications.
Market Restraints
- Carbon Fiber Supply Concentration:Toray Industries, Mitsubishi Chemical, and Hexcel collectively control aerospace-certified fiber supply, creating input bottlenecks during demand surges.
- High-Pressure Testing Infrastructure Scarcity:Burst testing facilities capable of 10,000 psi validation cycles remain concentrated in Germany, Japan, and the United States.
- Metallic Liner Cost Volatility:Aluminum 6061-T6 and stainless steel 316L price swings directly compress margins on Type II and Type III vessel production.
Strategic Opportunities
- India Industrial Gas Distribution:The country's PLI scheme for green hydrogen and compressed natural gas vehicle conversions is opening vessel procurement channels outside traditional automotive supply chains.
- Space Exploration Qualification Transfer:Aerospace COPV specifications for satellite propulsion are migrating into terrestrial hydrogen storage through shared filament winding and non-destructive testing protocols.
- EU Hydrogen Backbone Infrastructure:The European Hydrogen Backbone initiative's storage and buffer requirements are creating demand for stationary high-pressure vessels at interconnection points.
Industry Challenges
- Filament Winding Technician Shortage:Precision pattern programming and in-situ compaction control require specialized training unavailable through standard composites education pipelines.
- Multi-Standard Certification Overlap:Simultaneous compliance with DOT FMVSS 304, ISO 19881, and UN ECE R134 creates redundant testing cycles and documentation burdens.
- Legacy Fleet Retrofit Integration:Existing CNG infrastructure requires pressure rating upgrades and nozzle compatibility modifications to accommodate hydrogen service.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Overwrapped Pressure Vessels (Copvs) Market |
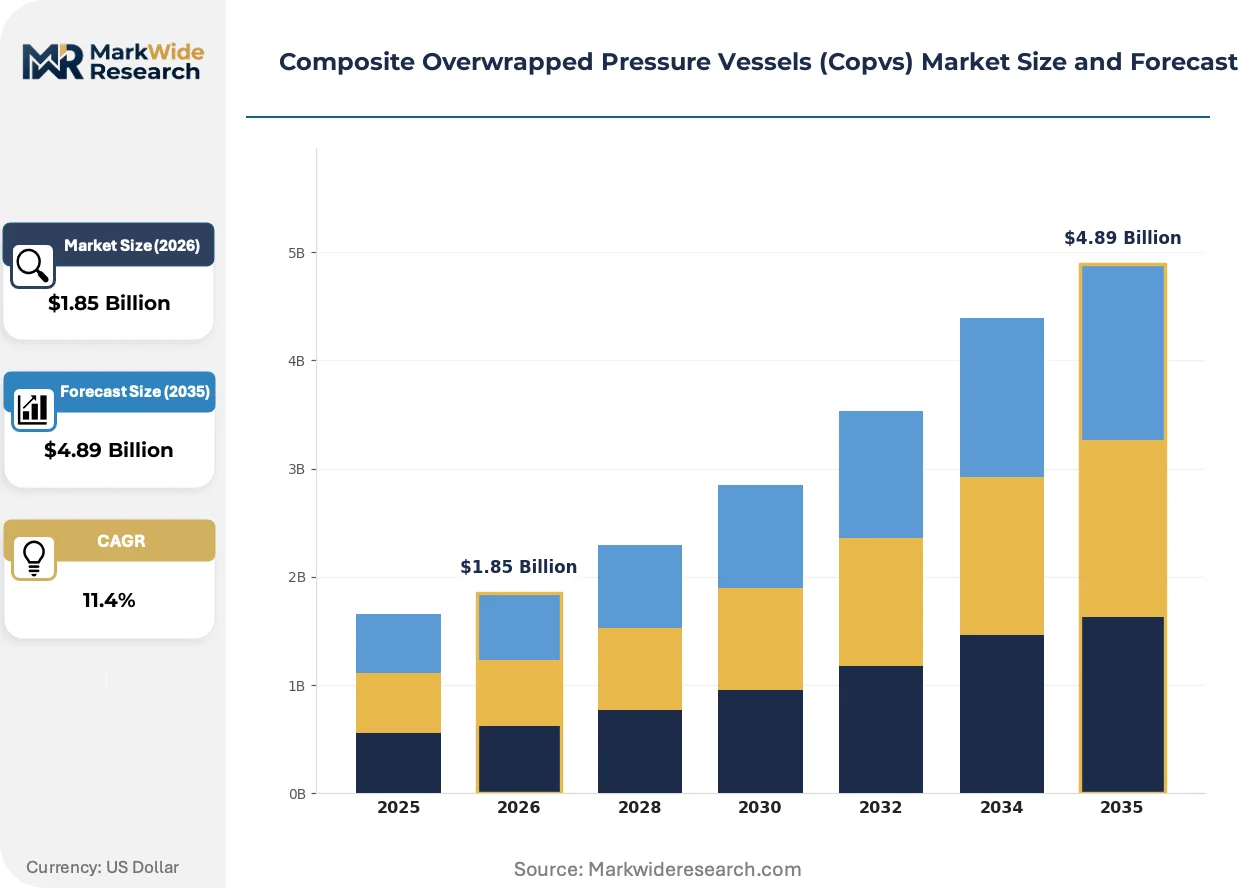
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type I, Type II, Type III, Type IV, Type V Application: Space Exploration, Fire Protection, Industrial Gas Storage, Recreational Diving, Aerospace Actuation End User: Marine Operations, Defense Forces, Energy Sector, Chemical Processing, Telecommunication Providers Material: Carbon Fiber, Glass Fiber, Aramid Fiber, Kevlar, High-Strength Steel |
| Companies Covered | Hexagon Composites ASA, Luxfer Holdings PLC, Worthington Industries, Faber Industrie SpA, NPROXX, Steelhead Composites, Quantum Fuel Systems LLC, CIMC Enric Holdings Limited, Iljin Composites Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Overwrapped Pressure Vessels (Copvs) Market Trends and Innovations
Automated fiber placement and in-situ thermoplastic consolidation are displacing conventional thermoset winding in next-generation vessel fabrication. These process shifts are compressing cycle times while enabling complex boss geometries previously unattainable through filament winding alone.
Thermoplastic resin systems with polyaryletherketone matrices are integrating into pressure vessel overwraps for hydrogen mobility applications. Hyundai Motor Group and Toyota Motor Corporation are qualifying these materials for 700-bar service to reduce autoclave cure cycles and enable welding-free liner attachment. The structural consequence is a halving of manufacturing lead times for Type IV vessels while maintaining burst safety margins.
Japan's METI hydrogen roadmap and associated JIS S 0015 standards are mandating 15-year vessel service life validation for fuel cell vehicle applications. This regulatory pressure is forcing fabricators to accelerate fatigue testing protocols and adopt real-time structural health monitoring through embedded fiber optic sensors. The heavy-duty truck segment is absorbing these compliance costs fastest due to fleet operator total-cost-of-ownership calculations.
Performance-based leasing contracts for hydrogen refueling stations are displacing outright vessel purchases among infrastructure developers. Linde plc and Air Liquide are structuring agreements where COPV suppliers retain ownership and responsibility for recertification intervals. Germany's industrial corridor along the Rhine-Ruhr region exhibits this model most prominently, with chemical processors preferring operational expenditure treatment for storage assets.
Composite Overwrapped Pressure Vessels (Copvs) Market Segmentation
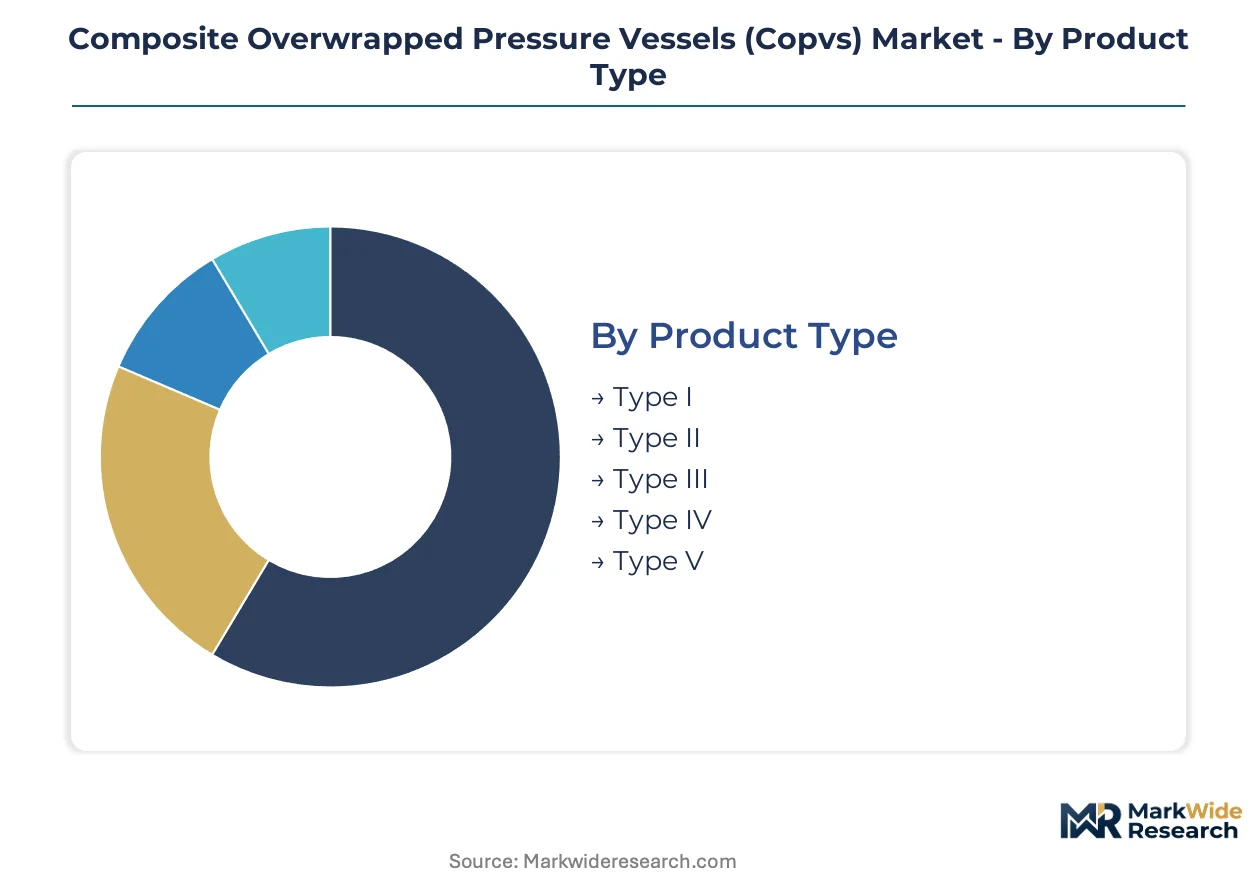
COPV procurement patterns diverge sharply between standalone storage assets and embedded propulsion systems. Segment boundaries determine certification pathways, liner material selection, and supplier qualification requirements across hydrogen mobility, aerospace, and industrial gas networks.
Product Type:
Standalone vessel categories dominate fleet procurement volumes, while embedded system configurations command premium qualification overhead.
- Type IV:Polymer-lined vessels with full carbon fiber overwrap achieve 700-bar service pressure for heavy-duty hydrogen transport. South Korean mobility fleets absorb the majority of current production through government-backed procurement mandates.
- Type III:Aluminum-lined construction with partial composite overwrap balances cost and weight for aerospace actuation systems. U.S. DOT FMVSS 304 certification requirements are filtering marginal fabricators from qualified supplier pools.
- Type I:All-metal construction serves legacy industrial gas storage where weight constraints are secondary.
- Type II:Thin metallic liners with glass fiber overwrap occupy mid-pressure CNG applications.
- Type V:Linerless all-composite designs remain developmental for satellite propulsion with extreme cycle life requirements.
Volume placements concentrate in Type III; the faster expansion belongs to Type IV.
Application:
Cost tiers separate qualification-intensive aerospace specifications from commoditized industrial gas storage.
- Industrial Gas Storage:Stationary buffer systems for hydrogen backbone infrastructure operate at 350-700 bar with simplified recertification protocols. Germany's Rhine-Ruhr chemical corridor drives demand through performance-based leasing structures.
- Space Exploration:Satellite propulsion vessels require 15,000+ cycle fatigue life and embedded fiber optic health monitoring. Toray T1100G fiber grades with tailored epoxy matrices dominate this specification tier.
- Aerospace Actuation:Emergency landing gear and flight control systems prioritize burst safety margins over cycle count.
- Fire Protection:Self-contained breathing apparatus cylinders favor lightweight Type IV construction for extended wear duration.
- Recreational Diving:Portable breathing gas storage competes on unit economics with aluminum alternatives.
Margin pools favor space exploration; volume scaling centers on industrial gas storage.
End User:
Customer procurement sophistication determines specification stringency and contract structure across vessel deployment.
- Energy Sector:Hydrogen refueling station operators prefer operational expenditure treatment through supplier-retained ownership models. Linde plc and Air Liquide structure multi-year offtake agreements with embedded recertification obligations.
- Chemical Processing:Rhine-Ruhr corridor processors retrofit gas distribution networks with high-pressure buffer storage for green hydrogen integration.
- Defense Forces:Submarine and aerospace applications mandate U.S. DOT and ISO 19881 dual certification with extended traceability documentation.
- Marine Operations:Offshore vessel fuel cell propulsion requires corrosion-resistant liner materials and specialized boss geometries.
- Telecommunication Providers:Backup power systems for remote cell towers utilize lower-pressure Type II vessels with simplified maintenance protocols.
Contract complexity peaks with defense forces; fleet standardization favors the energy sector.
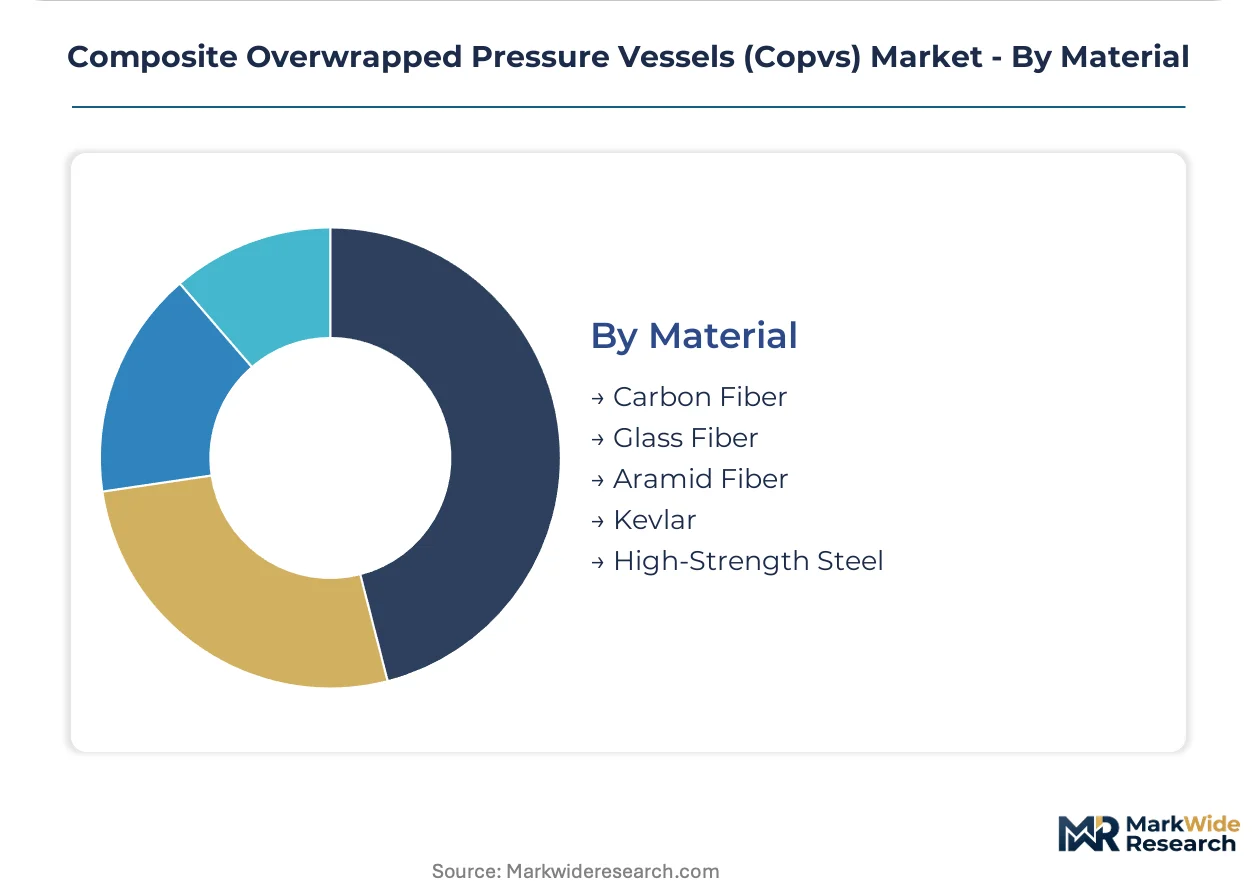
Material:
Supply concentration among aerospace-certified fiber producers shapes procurement security and pricing volatility.
- Carbon Fiber:T800H and T1100G grades with aerospace-qualified supply chains command premium positioning for Type IV hydrogen vessels. Toray Industries, Mitsubishi Chemical, and Hexcel control qualified fiber availability.
- Glass Fiber:E-glass and S-glass overwraps serve cost-sensitive CNG and industrial applications with reduced fatigue life requirements.
- Aramid Fiber:Impact-resistant intermediate layers protect carbon fiber overwraps from handling damage during transport.
- Kevlar:DuPont's para-aramid brand retains niche positioning in legacy defense specifications.
- High-Strength Steel:Wire reinforcement persists in Type I and Type II vessels for extreme-pressure industrial service.
Value capture concentrates in carbon fiber; glass fiber absorbs volume share in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr industrial corridor anchors European COPV procurement as chemical processors retrofit hydrogen distribution networks. Fleet operators in South Korea's Gyeonggi and Ulsan regions accelerate Type IV vessel deployment. The United States, Japan, and India concentrate manufacturing qualification and emerging demand respectively.
United States
Heavy-duty hydrogen trucking fleets and aerospace actuation systems drive vessel procurement across Texas and California industrial zones. NHTSA administers FMVSS 304 certification protocols that filter marginal fabricators from qualified supplier pools. Houston's energy corridor hosts burst testing facilities capable of 10,000 psi validation cycles for domestic qualification.
Germany
Rhine-Ruhr chemical processors and hydrogen backbone infrastructure developers dominate stationary storage procurement. The EU Pressure Equipment Directive and CE marking govern market access with reciprocity negotiations ongoing with METI frameworks. Bavaria's automotive supply chain integrates Type IV vessels into fuel cell vehicle platforms through performance-based leasing structures.
South Korea
Government-backed mobility fleet deployment programs accelerate Type IV vessel orders through mandated domestic content requirements. METI-aligned JIS standards influence specifications for regional supply chain integration. Ulsan's shipbuilding cluster adapts COPV specifications for offshore vessel fuel cell propulsion systems.
Japan
Fuel cell passenger vehicle and heavy-duty truck manufacturers anchor demand for 700-bar service pressure vessels. METI's hydrogen roadmap mandates 15-year vessel service life validation through JIS S 0015 standards. Nagoya's automotive engineering corridor concentrates fatigue testing protocols and real-time structural health monitoring development.
India
Compressed natural gas vehicle conversions and green hydrogen production incentives open vessel procurement channels outside traditional automotive supply chains. The PLI scheme for clean energy manufacturing attracts domestic fabrication investment. Gujarat's industrial zones host emerging filament winding capacity for industrial gas distribution networks.
Composite Overwrapped Pressure Vessels (Copvs) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the COPV value chain. Integrated liner manufacturers control quality through captive supply while specialized overwrap fabricators depend on external certification networks. Three archetypes dominate: aerospace-qualified specialists with satellite propulsion heritage, industrial gas incumbents leveraging multi-continent manufacturing scale, and hydrogen mobility pure-plays with Type IV qualification focus. Capacity expansion and strategic partnerships represent the dominant competitive moves as fleet operators lock in multi-year offtake commitments.
Among European-anchored fabricators, Hexagon Composites ASA and NPROXX occupy positions within the integrated manufacturing tier, while Luxfer Holdings PLC exemplifies the aerospace-actuation specialist archetype. These entities represent divergent strategic postures: one emphasizing backward integration into liner production, another concentrating on aluminum-lined hybrid development for sustained R&D positioning. Worthington Industries anchors the industrial gas storage segment with manufacturing presence across multiple continents. The competitive tension between these archetypes manifests in procurement negotiations where fleet operators weigh total-cost-of-ownership against qualification heritage.
| Leading Market Players |
|---|
| Hexagon Composites ASA |
| Luxfer Holdings PLC |
| Worthington Industries |
| Faber Industrie SpA |
| NPROXX |
| Steelhead Composites |
| Quantum Fuel Systems LLC |
| CIMC Enric Holdings Limited |
| Iljin Composites Corp |
| Others |
Pricing and Supply Chain Analysis
Automated fiber placement and in-situ thermoplastic consolidation are compressing manufacturing cycle times while simultaneously elevating capital requirements and concentrating production among fabricators with qualified aerospace supply chains. This process transition reshapes cost economics by reducing autoclave cure cycles for Type IV vessels, yet carbon fiber prepreg certification requirements tether pricing power to Toray Industries, Mitsubishi Chemical, and Hexcel's qualified fiber availability.
Pricing Analysis
Performance-based leasing contracts anchor value-based pricing through uptime guarantees and recertification bundling. Three-tier pricing structure across aerospace-qualified, automotive-certified, and industrial-grade vessels reflects FMVSS 304 and ISO 19881 certification overhead. Cost compression in automotive-grade Type IV production intensifies as South Korean fleet operators consolidate procurement volumes. Chemical processors in Germany's Rhine-Ruhr corridor exhibit lowest price sensitivity due to operational expenditure treatment preferences.
Supply Chain Analysis
Filament winding technician scarcity in Germany, Japan, and the United States constrains qualified manufacturing capacity expansion. Carbon fiber prepreg supply draws from Toray Industries' aerospace-certified production in Japan, Hexcel's U.S. facilities, and Mitsubishi Chemical's regional distribution networks. Single-source vulnerability pervades T800H and T1100G fiber grades for space exploration specifications. Distribution runs through direct long-term offtake agreements with hydrogen mobility fleet operators and industrial gas infrastructure developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic resin systems with polyaryletherketone matrices are displacing thermoset epoxy overwraps in next-generation vessel fabrication, compressing lead times while demanding new qualification investments. This technology transition phase rewards fabricators with integrated liner manufacturing and certified fiber placement capabilities.
For Market Incumbents: Deepen backward integration into carbon fiber prepreg supply through strategic partnerships with Toray Industries or Mitsubishi Chemical to secure qualified fiber allocation. Expand burst testing infrastructure in Houston and Nagoya to capture qualification bottlenecks. Defend margin position against thermoplastic pure-plays by accelerating JIS S 0015 and FMVSS 304 dual-certification timelines.
For New Entrants and Emerging Players: Launch via performance-based leasing contracts with India's compressed natural gas vehicle conversion programs under the PLI scheme for green hydrogen. Target industrial gas distribution networks in Gujarat's emerging manufacturing zones where certification requirements remain less stringent than automotive specifications. Pursue filament winding technician training partnerships with German technical institutes to overcome workforce scarcity.
For Investors and Strategic Acquirers: Re-rating potential sits with aerospace-qualified specialists given space exploration qualification transfer into terrestrial hydrogen storage. Long-term viability over the next decade hinges on carbon fiber supply security and multi-standard certification reciprocity between DOT, ECHA, and METI frameworks. Monitor JIS S 0015 adoption velocity across Asian supply chains as the inflection indicator for 15-year service life validation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Liner Manufacturing | Hexagon Composites ASA controls quality through captive aluminum and polymer liner production. |
| Multi-Standard Certification Investment | Dual FMVSS 304 and ISO 19881 qualification opens U.S. and European hydrogen mobility procurement channels. |
| Thermoplastic Resin System Qualification | Polyaryletherketone matrices enable Hyundai and Toyota to halve Type IV vessel manufacturing lead times. |
| Performance-Based Leasing Structure | Linde plc and Air Liquide retain vessel ownership while capturing operational expenditure treatment preference. |
| Filament Winding Technician Training | German technical institutes address precision pattern programming scarcity constraining qualified manufacturing capacity. |
Research Methodology
SEC 10-K filings, EU Pressure Equipment Directive regulatory databases, and METI hydrogen roadmap publications formed the secondary backbone. Primary interviews with COPV fabrication plant managers, hydrogen refueling station procurement leads, and aerospace actuation system engineers combined with customs trade data and filament winding equipment manufacturer disclosures. Bottom-up vessel shipment tracking and top-down hydrogen mobility fleet deployment analysis enabled triangulation across the analysis window.
Historical trendline analysis of Type III and Type IV vessel procurement volumes informed projection modeling across product type, application, end user, and material segmentation dimensions. CAGRs were derived through regression analysis of fleet deployment trajectories and certification timeline compression. Carbon fiber prepreg pricing volatility, FMVSS 304 revision cycles, and JIS S 0015 adoption curves served as industry-specific forecast inputs.
Carbon fiber supply concentration, multi-standard certification reciprocity delays, and thermoplastic resin system qualification failures are the dominant revision risks. Forecasts reflect assumptions regarding sustained hydrogen mobility fleet expansion and qualified manufacturing capacity scaling. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
LPG Gas Cylinder Market
Fuels
Australia Coal Market
Fuels
Gas Feed System Market
Fuels
LPG Vaporizer Market
Fuels
Coal Liquefaction Market
Fuels
Gas Pooling Mechanism Market
Fuels
City Gas Distribution Market
Fuels
South America Aviation Fuel Market
Fuels
South Korea LNG Bunkering Market
Fuels
Wood Charcoal Market
Fuels
Coal Briquette Box Market
Fuels
Saudi Arabia Fuel Station Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
China Coal Market
Fuels
Coal to Liquid Fuel (CTL) Market
Fuels
Carbonizers Market