
 Carbonizers Market | 2026-2036
Carbonizers Market Size, Share, and Industry Trends Forecast 2026-2036
Carbonizers Market Analytics
The EU Green Deal's carbon removal certification framework is rebalancing procurement criteria for biochar across European agricultural cooperatives. Cabot Corporation leverages its petroleum-based carbon black expertise to sustain furnace-grade dominance in tire manufacturing. Ingevity anchors specialty activated carbon supply for automotive evaporative emission controls in North America. Kuraray Co., Ltd. differentiates through coconut-shell precursor sourcing for high-iodine water treatment grades.
Carbonizers are thermal processing systems that convert carbonaceous feedstocks into stable carbon products through controlled heating in oxygen-limited environments, typically operating between 300°C and 900°C depending on target porosity and surface area. Their primary purpose is to engineer carbon structures for adsorption, conductivity, or soil amendment functions across industrial and environmental applications. Continuous carbonization technology leads operational throughput for large-scale activated carbon facilities, while hydrothermal carbonization represents the fastest-growing segment as wet biomass processors seek lower-energy pathways to biochar. Biochar commands margin concentration in agricultural certification schemes, whereas activated carbon pools sit with municipal water treatment contracts requiring NSF/EN compliance.
The EPA regulates activated carbon under the Safe Drinking Water Act for contaminant removal mandates, while the EU F-Gas Regulation phases out fluorinated gases that compete with carbon-based adsorbents in refrigeration applications. Japan's METI enforces JIS standards for carbon black in rubber reinforcement, shaping export compliance burdens for Asian producers. Stakeholders must monitor evolving soil carbon quantification protocols, as verification methodologies will determine which carbonizer outputs qualify for compliance markets versus voluntary offsets.
Market Dynamics
Continuous carbonization technology is consolidating operational control among large-scale activated carbon facilities, while hydrothermal carbonization opens lower-energy pathways for wet biomass processors seeking biochar certification under tightening EU traceability mandates.
Growth Catalysts
- PFAS Remediation Mandates:The EPA's Safe Drinking Water Act enforcement is compelling municipal water utilities in Germany and Japan to expand activated carbon procurement for contaminant removal infrastructure.
- Steel Industry Electrification:China's steelmakers are scaling furnace-grade carbon black consumption for electric arc furnace operations demanding higher-purity conductive inputs.
- EU Green Deal Certification:The carbon removal certification framework is creating compliant offtake channels for biochar producers serving agricultural cooperatives with verified soil carbon credits.
Market Restraints
- Precursor Supply Concentration:Coconut-shell activated carbon production depends on Southeast Asian agricultural residue flows vulnerable to climate-induced harvest volatility.
- Energy Cost Structure:Thermal carbonization's natural gas intensity exposes margins to European wholesale energy price spikes following supply reconfigurations.
- Zeolite Substitution:Synthetic molecular sieves are capturing select gas separation applications from activated carbon in petrochemical dehydration units.
Strategic Opportunities
- Soil Carbon Quantification Protocols:Emerging verification methodologies under ISO standards will determine which carbonizer outputs qualify for compliance carbon markets versus voluntary offsets.
- Automotive Evaporative Controls:North American emission regulations are expanding specialty activated carbon demand for canister systems in internal combustion and hybrid vehicle platforms.
- Wet Biomass Processing:Hydrothermal carbonization technology convergence with anaerobic digestion facilities is unlocking integrated bioenergy-biochar production models for agricultural processors.
Industry Challenges
- NSF/EN Certification Timelines:Municipal water treatment contracts require 18-24 month compliance validation cycles that strain working capital for carbonizer technology providers.
- Pyrolysis Equipment Integration:Retrofitting legacy rotary kiln systems with continuous feed automation demands specialized thermal engineering expertise scarce in regional equipment service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbonizers Market |
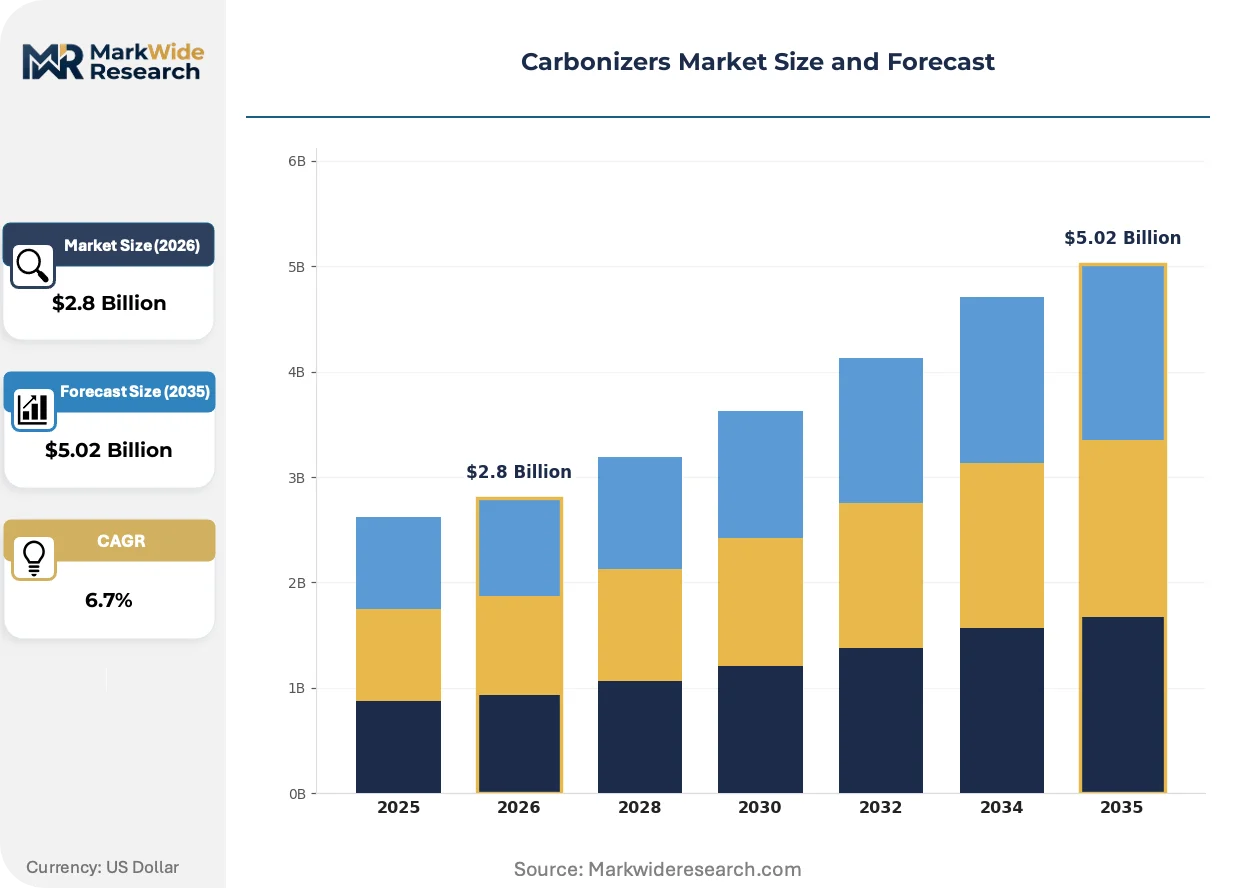
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Batch Carbonization, Continuous Carbonization, Pyrolysis, Hydrothermal Carbonization End User: Energy Sector, Chemical Industry, Agriculture, Waste Management Product Type: Biochar, Activated Carbon, Carbon Black, Charcoal Application: Soil Amendment, Water Treatment, Air Filtration, Fuel Source |
| Companies Covered | Cabot Corporation, Ingevity, Kuraray Co., Ltd., Jacobi Carbons Group, Calgon Carbon Corporation, Haycarb PLC, Kureha Corporation, TerraNova Energy GmbH, GreenPower LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbonizers Market Evolving Landscape
Carbonizer technology trajectories are bifurcating between high-throughput continuous systems for industrial activated carbon and modular hydrothermal units for distributed biochar production serving agricultural certification schemes.
Plasma-assisted carbonization is electrifying thermal processing for specialty carbon blacks requiring ultra-pure conductive grades. Tire manufacturers in Japan and South Korea are piloting these systems to meet METI-enforced JIS standards for rubber reinforcement. The technology is compressing energy intensity differentials between petroleum-based and renewable feedstock pathways.
The EU F-Gas Regulation is phasing out fluorinated refrigerants that compete with carbon-based adsorbents in cooling applications. This industrial consequence redirects commercial refrigeration OEM specification toward activated carbon molecular filtration for low-global-warming-potential systems. Cold chain logistics operators in Germany and France are accelerating compliance transitions ahead of 2027 phase-down deadlines.
Certification-driven specification is fragmenting biochar procurement into premium agricultural grades versus industrial combustion feedstocks. European cooperatives now require EU Green Deal-aligned traceability documentation that commodity traders cannot supply, displacing spot-market purchasing with long-term offtake contracts tied to soil carbon verification. Dutch and Danish agricultural clusters exhibit the most advanced contract structuring for certified biochar integration.
Carbonizers Market Segmentation
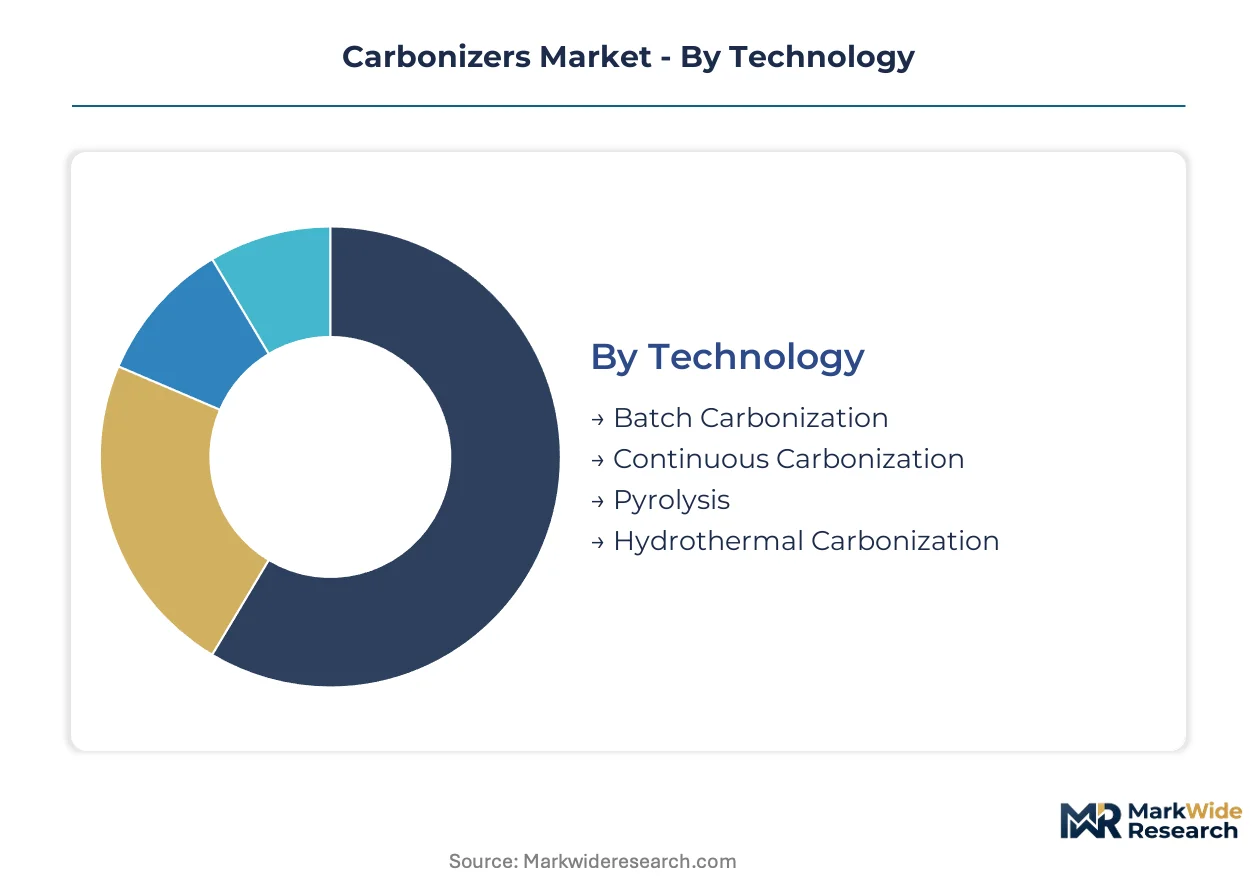
Carbonizer procurement patterns diverge sharply across thermal processing intensities, end-use compliance requirements, and feedstock moisture content. Buyers prioritize operational throughput, certification traceability, or precursor flexibility depending on their carbon product target and offtake contract structure.
Technology:
Cost tier separates municipal-scale facilities from distributed agricultural processors.
- Continuous Carbonization:Automated feed systems sustain 24-hour thermal processing cycles for activated carbon facilities serving municipal water contracts. German utilities specify these systems for PFAS remediation infrastructure requiring NSF/EN compliance validation.
- Hydrothermal Carbonization:Wet biomass processors operate below 250°C in pressurized aqueous environments, slashing energy intensity for biochar certification under EU Green Deal traceability mandates. Dutch agricultural cooperatives pilot these units alongside anaerobic digestion facilities.
- Batch Carbonization:Intermittent kiln operations serve small-scale charcoal producers and specialty carbon black manufacturers.
- Pyrolysis:Oxygen-starved thermal decomposition enables tire-derived carbon black recovery and plastic waste-to-fuel pathways.
Continuous systems anchor installed capacity; hydrothermal configurations are climbing the fastest.
End User:
Application maturity dictates margin structure and contract duration.
- Chemical Industry:Furnace-grade carbon black specifications from Japan's METI-enforced JIS standards shape procurement for tire reinforcement and conductive polymer applications. South Korean rubber manufacturers demand plasma-assisted carbonization for ultra-pure grades.
- Agriculture:Soil amendment contracts require EU Green Deal-aligned biochar with verified carbon quantification protocols. Danish cooperatives structure long-term offtake agreements displacing spot-market purchasing.
- Energy Sector:Biomass power generators consume torrefied feedstocks for co-firing compliance with national renewable portfolio standards.
- Waste Management:Municipal solid waste processors deploy carbonizers for landfill diversion credits and refuse-derived fuel production.
Chemical industry procurement leads contract values; agricultural offtake is expanding most quickly.
Product Type:
Certification tier fragments pricing into compliance-grade premiums versus commodity feedstocks.
- Activated Carbon:High-iodine coconut-shell grades from Southeast Asian precursor flows serve water treatment infrastructure in Germany and Japan. EPA Safe Drinking Water Act enforcement drives municipal procurement for contaminant removal.
- Carbon Black:Electric arc furnace operations in China's steel sector consume furnace-grade material for conductive slag conditioning. Petroleum-based and renewable feedstock pathways converge as plasma-assisted processing compresses purity differentials.
- Biochar:Agricultural certification schemes command margin premiums over industrial combustion feedstocks.
- Charcoal:Metallurgical and recreational applications sustain traditional kiln operations with limited automation.
Activated carbon dominates revenue concentration; biochar exhibits the steepest expansion trajectory.
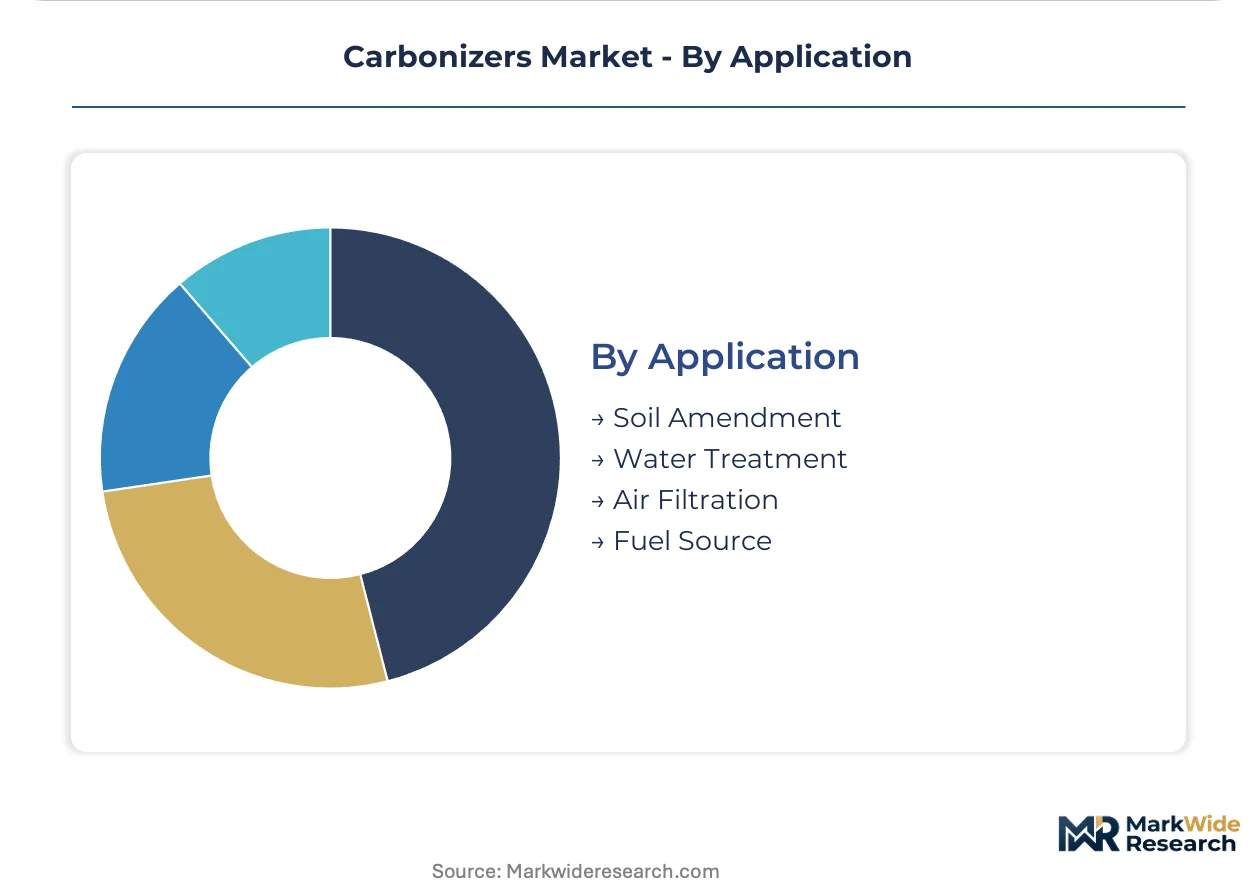
Application:
Regulatory enforcement calendars determine near-term procurement urgency.
- Water Treatment:Municipal utilities in Germany scale activated carbon filtration for PFAS remediation ahead of tightening EU Drinking Water Directive limits. NSF/EN certification timelines extend 18-24 months, locking incumbent suppliers into long-term service contracts.
- Air Filtration:EU F-Gas Regulation phase-out of fluorinated refrigerants redirects commercial refrigeration OEM specification toward activated carbon molecular filtration. Cold chain operators in France accelerate compliance transitions ahead of deadlines.
- Soil Amendment:ISO-standard soil carbon quantification protocols determine biochar eligibility for compliance markets versus voluntary offsets.
- Fuel Source:Industrial boilers and residential heating sustain charcoal and torrefied biomass consumption.
Water treatment commands procurement urgency; air filtration is gaining regulatory tailwinds fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale activated carbon production for municipal water treatment in the early twentieth century. Japanese steelmakers later commercialized furnace-grade carbon black for tire reinforcement. These historical foundations now shape divergent regional specialization across thermal carbon processing.
Germany
Municipal utilities in the Rhine-Ruhr corridor scale activated carbon procurement for PFAS remediation ahead of EU Drinking Water Directive enforcement. The EU F-Gas Regulation accelerates commercial refrigeration OEM transitions to carbon-based adsorbents. Bavarian agricultural cooperatives pilot hydrothermal carbonization alongside anaerobic digestion for certified biochar offtake.
China
Steelmakers in the Yangtze River Delta consume furnace-grade carbon black for electric arc furnace slag conditioning. The MIIT dual carbon goals tighten emissions standards for thermal processing facilities. Shandong Province hosts concentrated carbon black production serving tire manufacturers seeking higher-purity conductive grades.
Japan
Rubber manufacturers in the Kansai region demand plasma-assisted carbonization for ultra-pure carbon black meeting METI-enforced JIS standards. The country's national environmental regulator mandates activated carbon filtration for industrial wastewater treatment. Chubu industrial clusters anchor specialty carbon production for automotive evaporative emission controls.
United States
EPA Safe Drinking Water Act enforcement drives municipal procurement of high-iodine activated carbon for contaminant removal infrastructure. The IRA clean energy provisions subsidize biochar production for agricultural soil carbon sequestration. Midwest agricultural processors integrate hydrothermal carbonization with existing biogas facilities.
Netherlands
Dutch agricultural cooperatives structure long-term biochar offtake contracts requiring EU Green Deal-aligned traceability documentation. The country's national environmental agency enforces stringent soil carbon quantification protocols for compliance market eligibility. Rotterdam port logistics clusters facilitate coconut-shell activated carbon import from Southeast Asian precursor suppliers.
Carbonizers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the carbonizer supply base. Integrated petrochemical conglomerates operate captive carbon black facilities with backward integration into feedstock refining. Specialized activated carbon fabricators source coconut-shell precursors through Southeast Asian agricultural residue networks. Modular equipment providers serve distributed biochar markets with lower capital barriers. Dominant competitive moves include capacity expansion in high-purity furnace grades and strategic partnerships for wet biomass processing integration.
Among North American chemical specialists, Cabot Corporation and Ingevity occupy positions reflecting divergent feedstock strategies. Cabot's petroleum-based carbon black expertise anchors furnace-grade supply for tire reinforcement applications. Ingevity represents the specialty activated carbon tier focused on automotive evaporative emission controls. Japanese material science conglomerates exemplify integrated production models, with Kuraray Co., Ltd. sitting within the high-iodine water treatment grade segment through coconut-shell precursor sourcing.
| Leading Market Players |
|---|
| Cabot Corporation |
| Ingevity |
| Kuraray Co., Ltd. |
| Jacobi Carbons Group |
| Calgon Carbon Corporation |
| Haycarb PLC |
| Kureha Corporation |
| TerraNova Energy GmbH |
| GreenPower LTD |
| Others |
Value Network & Pricing Analysis
EU Green Deal-aligned biochar certification mandates from Dutch and Danish agricultural cooperatives are forcing procurement shifts toward long-term offtake contracts with verified traceability, compressing spot-market liquidity and elevating premiums for compliant supply.
Pricing Analysis
Contract-based long-term offtake structures dominate carbonizer procurement, with premium-mid-economy pricing differentiation separating EU-certified biochar grades from industrial combustion feedstocks. Price differentiation hinges on ISO-standard soil carbon verification and NSF/EN municipal water compliance tiers. Cost compression in furnace-grade carbon black is intensifying as plasma-assisted processing narrows petroleum-based and renewable feedstock purity gaps. Agricultural cooperatives exhibit lowest price sensitivity due to carbon credit revenue stacking, while commodity charcoal traders face acute margin pressure.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for coconut-shell activated carbon flows from Southeast Asian precursor networks. Manufacturing concentrates in China, Germany, and Japan across distinct product tiers. Feedstock supply draws from Indonesian and Philippine agricultural residue harvests, petroleum refining byproducts, and European wet biomass streams. Single-source vulnerability sits with Southeast Asian coconut-shell flows exposed to climate-induced harvest volatility. Distribution runs through specialized chemical distributors and direct municipal utility contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in carbonizer markets rest on plasma-assisted processing cost curves flattening and EU-certified biochar premiums widening under compliance market eligibility rules.
For Market Incumbents: Anticipate zeolite substitution threats in petrochemical dehydration by anchoring activated carbon specifications through NSF/EN certification lock-in with German municipal utilities. Deepen backward integration into coconut-shell precursor networks in Indonesia and the Philippines to defend feedstock security. Prioritize continuous carbonization capacity additions in the Rhine-Ruhr corridor to capture PFAS remediation procurement waves. For New Entrants and Emerging Players: Equipment finance partnerships with Dutch agricultural cooperatives unlock distributed hydrothermal carbonization deployment without capital-intensive manufacturing footprints. White-space concentration sits with wet biomass processing integration alongside existing anaerobic digestion facilities in Denmark and the Netherlands. Target automotive evaporative emission control specifications in North America through specialty activated carbon canister supply. For Investors and Strategic Acquirers: Asymmetric upside sits with modular hydrothermal equipment providers serving EU biochar certification schemes with lower capital intensity than incumbent continuous systems. Five-to-ten year viability favors technology licensors with ISO-standard soil carbon quantification protocol alignment. Monitor EU F-Gas Regulation compliance transition velocity among French and German cold chain operators as inflection signal for activated carbon molecular filtration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Cabot Corporation's petroleum feedstock control secures furnace-grade carbon black margin stability against energy price spikes. |
| Plasma-Assisted Processing Scale-Up | Kureha Corporation's electrified thermal systems meet METI-enforced JIS purity standards for Japanese tire reinforcement contracts. |
| EU Green Deal Certification Alignment | TerraNova Energy GmbH's traceability documentation unlocks Dutch cooperative offtake channels displacing spot-market biochar. |
| Hydrothermal-Anaerobic Digestion Integration | GreenPower LTD's wet biomass convergence model slashes energy intensity for agricultural processors seeking dual revenue streams. |
| Specialty Automotive Canister Supply | Ingevity's evaporative emission control grades capture IRA-subsidized North American hybrid vehicle platform specifications. |
Research Methodology
Direct dialogue with carbonizer plant managers, municipal water utility procurement leads, agricultural cooperative technical directors, and specialty chemical distribution channel partners grounded qualitative findings. Secondary validation drew from EPA Safe Drinking Water Act enforcement records, EU ECHA regulatory filings, Japan METI JIS standard documentation, and customs trade data tracking coconut-shell precursor flows. Bottom-up facility capacity assessments and top-down end-use demand modeling enabled cross-triangulation.
Segmentation outputs across technology type, product grade tier, end-use industry, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs emerged from installed capacity utilization curves, contract renewal velocity in municipal water treatment, and steel industry electric arc furnace electrification roadmaps. Forecast inputs incorporated EU F-Gas Regulation phase-down calendars and ISO soil carbon quantification protocol adoption timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to European wholesale natural gas price trajectories and Southeast Asian climate impacts on coconut harvests. Outputs reflect documented assumptions around regulatory enforcement calendars and certification scheme eligibility rules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Fuel Conditioning System Market
Fuels
Liquid Propellants Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
Marine Fuel Optimization Market
Fuels
Fuel Oxygenate Market
Fuels
Gas Pooling Mechanism Market
Fuels
Defense Aircraft Aviation Fuel Market
Fuels
Pyrolysis Gas Market
Fuels
Gas Feed System Market
Fuels
Coal Liquefaction Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
Biobutanol Market
Fuels
Turbine Drip Oil Market
Fuels
Global Chemical Logistics Market
Fuels
Composite Overwrapped Pressure Vessels (Copvs) Market
Fuels
South America Aviation Fuel Market