
 Boiler Refractory Material Market | 2026-2036
Boiler Refractory Material Market Size, Share, and Industry Trends Forecast 2026-2036
Boiler Refractory Material Market Analysis
India's refractory manufacturing corridor is rewriting supply dynamics for Asian boiler operators. Saint-Gobain leverages its fused-cast technology leadership to anchor premium positions in utility-scale installations. RHI Magnesita GmbH sustains broad geographic coverage through integrated magnesite sourcing from European and Asian deposits. Shinagawa Refractories specializes in monolithic formulations for Japanese power producers seeking extended campaign life.
Boiler refractory material encompasses thermally stable ceramic and mineral compositions engineered to withstand temperatures exceeding 1,500°C while resisting thermal shock, slag corrosion, and mechanical abrasion in combustion chambers and process vessels. Alumina-silica and magnesia-based formulations predominate, with bulk density and cold crushing strength serving as critical quality parameters for lining integrity. Castable products dominate installation volumes across power generation applications where monolithic placement reduces joint failure risk compared to traditional brick construction. Brick formats retain margin concentration in chemical processing environments requiring precise dimensional stability during cyclic thermal loading. Zirconia-bearing materials represent the fastest-growing material category for ultra-high temperature metal production zones where slag resistance determines refractory consumption rates.
India's Central Electricity Authority mandates minimum boiler efficiency standards that accelerate refractory upgrade cycles for state-owned thermal assets. China's Ministry of Ecology and Environment enforces emission intensity thresholds that force older boiler installations toward comprehensive lining replacements rather than patch repairs. The EU F-Gas Regulation indirectly shapes refractory specification through linked boiler efficiency requirements in combined heat and power systems. Stakeholders must monitor how tightening particulate emission limits across multiple jurisdictions redirect procurement toward longer-service refractory chemistries with higher upfront unit costs.
Market Dynamics
India's Central Electricity Authority efficiency mandates are compressing refractory replacement cycles for state-owned thermal assets, forcing procurement toward higher-performance alumina-magnesia formulations with extended campaign life guarantees.
Growth Catalysts
- Stricter emission intensity thresholds:China's Ministry of Ecology and Environment enforcement is compelling steelmakers to undertake comprehensive blast furnace lining replacements rather than incremental patch repairs.
- Supercritical boiler expansion:Indian power generation utilities are accelerating installations under CEA guidelines, generating concentrated demand for fused-cast and monolithic refractory systems.
- Zirconia-bearing material adoption:Ultra-high temperature metal production zones in Japan are specifying advanced slag-resistant chemistries to reduce refractory consumption rates in cyclic thermal environments.
Market Restraints
- Magnesite supply concentration:European and Asian deposit dependency creates vulnerability to export restriction policies and freight cost volatility.
- Technical service life limitations:Traditional alumina-silica formulations face hard thermal shock resistance ceilings above 1,600°C, constraining application in next-generation combustion chambers.
- F-Gas Regulation linkage:EU boiler efficiency requirements in combined heat and power systems indirectly restrict refractory specification flexibility, extending approval timelines.
Strategic Opportunities
- Underpenetrated industrial corridors:Vietnam and Indonesia are expanding coal-fired capacity without established local refractory supply infrastructure, creating import substitution windows.
- Carbon capture integration:Boiler retrofits for amine-based CO2 absorption systems require specialized corrosion-resistant lining chemistries not yet standardized.
- Digital thermal monitoring convergence:IoT sensor deployment is hybridizing with predictive maintenance contracts to enable outcome-based refractory performance guarantees.
Industry Challenges
- Specialized installation technician scarcity:Monolithic castable placement demands certified gunning and ramming expertise that outpaces vocational training program output.
- Legacy brick inventory stranding:Utilities with substantial pre-positioned shaped refractory stock face write-down pressure as monolithic formats displace traditional construction.
- Multi-jurisdiction certification complexity:Manufacturers serving both EU and Indian markets must maintain parallel testing protocols under REACH and BIS frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boiler Refractory Material Market |
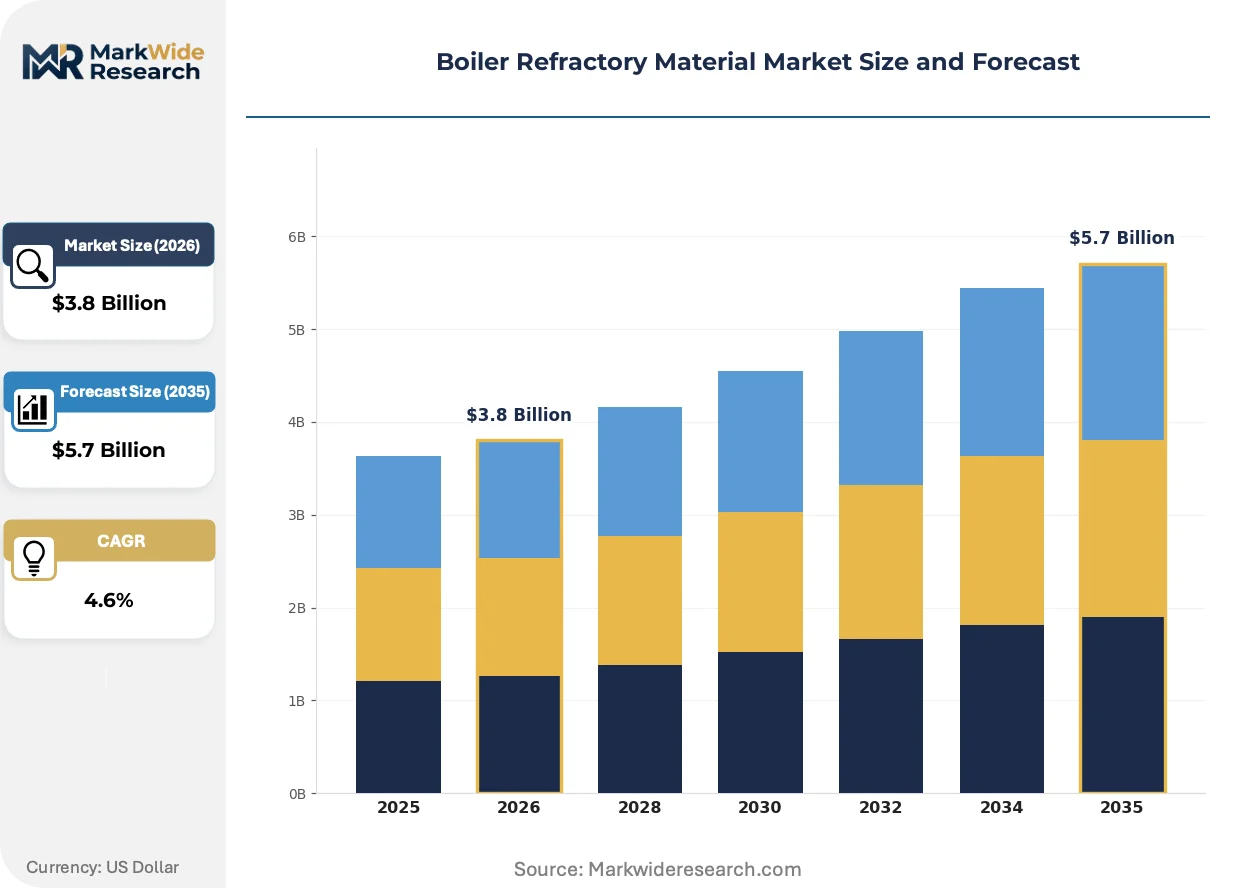
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Castable, Brick, Plastic, Gunning Application: Power Generation, Cement Industry, Chemical Processing, Metal Production Material: Silica, Alumina, Magnesia, Zirconia Installation Method: Pre-cast, Monolithic, Shotcrete, Trowel |
| Companies Covered | Saint-Gobain, Krosaki Harima Corporation, RHI Magnesita GmbH, Shinagawa Refractories, Morgan Advanced Materials, Vesuvius Plc, Imerys S.A., Refratechnik Holding, HarbisonWalker International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boiler Refractory Material Market Emerging Trajectories
Material science advances are compressing the performance gap between castable and brick formats while digital tools are reconfiguring how end-users specify and procure refractory systems. These shifts are redrawing competitive boundaries between formulation specialists and installation service providers.
Nano-engineered alumina-spinel castables are hybridizing conventional monolithic placement speed with brick-like dimensional stability under cyclic thermal loading. Japanese power producers are specifying these systems for ultra-supercritical boiler waterwall applications where thermal shock resistance determines campaign life. The technology is compressing the traditional trade-off between installation labor efficiency and lining longevity that has segmented the market for decades.
China's Ministry of Ecology and Environment emission intensity thresholds are forcing older boiler installations toward comprehensive lining replacements rather than patch repairs. Steelmakers in Hebei and Shandong provinces face accelerated retrofit timelines that favor turnkey refractory service contracts over material-only procurement. The policy is redirecting specification authority from plant maintenance departments toward central engineering procurement functions with consolidated technical standards.
After-sales thermal performance monitoring is displacing traditional tonnage-based purchasing in European combined heat and power installations. End-users in Germany and the Netherlands are unbundling material supply from installation and commissioning services, then rebundling with remote temperature profiling and residual thickness prediction. This restructuring is most visible in biomass co-firing boiler operators where fuel variability accelerates unpredictable refractory wear patterns.
Boiler Refractory Material Market Segmentation
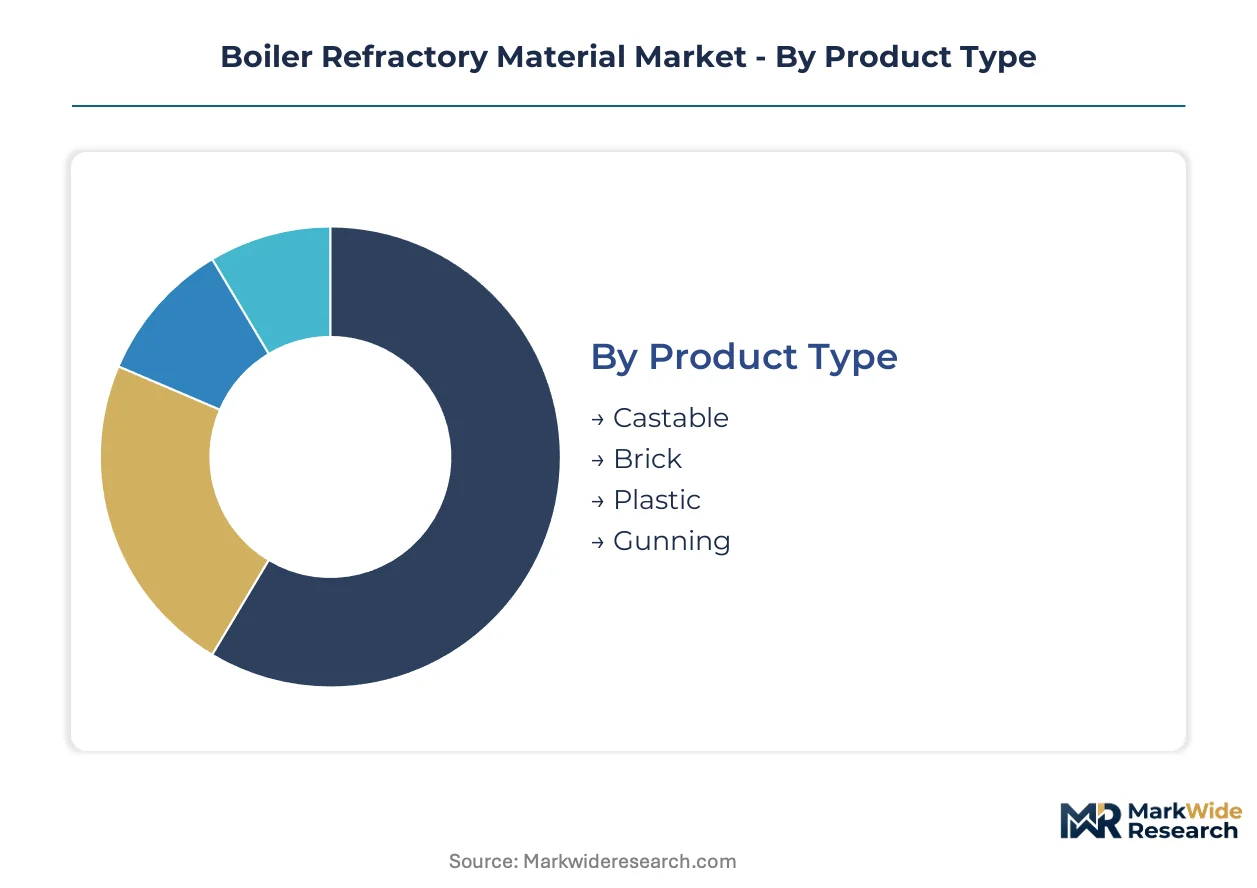
Boiler refractory procurement decisions hinge on thermal cycling intensity, slag chemistry, and installation accessibility. Segment boundaries blur as nano-engineered formulations compress traditional performance gaps between monolithic and shaped products.
Product Type:
Castable products turn over fastest in high-cycling utility boilers where thermal shock drives 3-5 year replacement intervals. Brick formats command longest campaign life in stable-temperature chemical vessels with predictable duty cycles.
- Castable:Pumpable and gunnable monolithic formulations eliminate joint failure points through continuous placement. Indian supercritical boiler installations under CEA mandates specify high-alumina low-cement castables for waterwall and burner throat applications where rapid heat-up protocols reduce outage duration.
- Brick:Fired shaped refractories deliver dimensional precision under sustained mechanical load. Chemical processing facilities in Germany and the Netherlands maintain substantial shaped refractory inventories for reactor vessels where thermal cycling remains moderate and geometric tolerances are tight.
- Plastic:Ramming-grade moist compositions suit manual placement in irregular geometries and emergency repairs. Steel mill maintenance crews in Hebei province deploy phosphate-bonded plastics for taphole patching where speed outweighs ultimate service life.
- Gunning:Dry-spray formulations enable remote application in hazardous access zones. Biomass co-firing boiler operators specify gunning mixes for economizer hoppers where fuel variability accelerates unpredictable wear patterns.
Brick dominates installed base. Castable is where expansion concentrates.
Application:
Power generation absorbs the highest absolute tonnage through centralized procurement by state-owned utilities. Metal production commands premium unit economics through severe slag conditions that consume refractory rapidly.
- Power Generation:Ultra-supercritical boilers in Japan and India specify advanced alumina-spinel systems for waterwall protection. CEA efficiency mandates compress replacement cycles for state-owned thermal assets across Maharashtra and Gujarat.
- Cement Industry:Rotary kiln burning zones require magnesia-spinel formulations resisting clinker liquid phase attack. Southeast Asian capacity expansion in Vietnam and Indonesia drives import demand without established local supply infrastructure.
- Chemical Processing:FCCU reactor vessels and ethylene cracking furnaces prioritize thermal shock resistance. European combined heat and power operators unbundle material supply from installation services under F-Gas Regulation-linked efficiency requirements.
- Metal Production:Blast furnace hearths and BOF vessels consume zirconia-bearing materials for slag line protection. Chinese steelmakers in Shandong province face accelerated retrofit timelines under MEE emission intensity thresholds.
Power generation commands volume concentration. Metal production captures margin expansion.
Material:
Alumina formulations balance cost and performance across the broadest temperature range. Zirconia chemistries occupy narrow ultra-high temperature niches with steep price premiums.
- Silica:Super-duty fireclay and silica brick serve coke ovens and glass tank regenerators where thermal stability under sustained load matters more than slag resistance.
- Alumina:Tabular and fused alumina aggregates anchor the industry's workhorse formulations. Low-cement castables with 70-80% alumina content dominate Indian utility boiler contracts under stricter CEA efficiency standards.
- Magnesia:Dead-burned and fused magnesia provide basic slag resistance in steel and cement applications. RHI Magnesita and European competitors maintain integrated sourcing from Austrian and Slovakian deposits.
- Zirconia:Partially-stabilized zirconia and zirconia-mullite composites deliver unmatched slag corrosion resistance. Japanese specialty steel producers specify these chemistries for vacuum degassing vessels where refractory consumption directly limits campaign economics.
Alumina spans the widest application footprint. Zirconia is climbing the fastest.
Installation Method:
Monolithic placement reduces labor hours and joint count versus pre-cast alternatives. Shotcrete access enables repairs in confined geometries that exclude conventional forming.
- Pre-cast:Factory-cured shapes accelerate field assembly in standardized boiler configurations. German power producers specify pre-cast burner quarls and roof segments to minimize critical path outage duration.
- Monolithic:In-situ casting and gunning eliminate shape inventory and dimensional constraints. Indian utilities expanding supercritical capacity favor monolithic waterwall linings under compressed construction schedules.
- Shotcrete:Wet-spray application penetrates complex geometries without formwork. Cement kiln nose rings and cooler bullnoses in Indonesia rely on shotcrete for access-limited maintenance.
- Trowel:Hand-placed mortars and coatings finish joints and protect structural steel. Chemical processing maintenance departments deploy trowel-grade plastics for vessel lining touch-ups between major turnarounds.
Monolithic commands new construction preference. Pre-cast retains retrofit and standard-design dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Indian utilities prioritize rapid-installation monolithics under compressed outage windows. Japanese steelmakers specify ultra-premium chemistries for extended campaign economics. European operators unbundle material supply from digital monitoring services.
China
Steelmakers in Hebei and Shandong provinces drive blast furnace lining replacements under MEE emission intensity thresholds. The Ministry of Ecology and Environment enforcement compels comprehensive retrofits rather than patch repairs. Tangshan steel cluster operators favor turnkey service contracts consolidating specification authority.
India
State-owned thermal assets across Maharashtra and Gujarat compress refractory cycles under CEA efficiency mandates. The Central Electricity Authority standards accelerate procurement toward alumina-magnesia formulations with extended guarantees. Mundra and Hazira industrial corridors concentrate supercritical boiler construction.
Japan
Specialty steel producers specify zirconia-bearing materials for vacuum degassing vessels. METI efficiency guidelines shape ultra-supercritical boiler specifications for thermal shock resistance. Nagoya and Kobe metal production zones prioritize slag-resistant chemistries reducing consumption rates.
Germany
Combined heat and power operators unbundle material supply from installation under F-Gas Regulation-linked efficiency requirements. Biomass co-firing facilities in the Ruhr region deploy remote thermal monitoring for unpredictable wear patterns. Rhine industrial corridor utilities rebundle procurement with predictive maintenance contracts.
United States
Chemical processing facilities maintain shaped refractory inventories for reactor vessels under EPA emission compliance timelines. Gulf Coast petrochemical clusters specify thermal shock-resistant formulations for ethylene cracking furnaces. Texas and Louisiana process operators balance cyclic loading demands with geometric tolerance requirements.
Boiler Refractory Material Market Vendor Landscape
Capability concentration sits with formulation specialists commanding premium chemistry expertise; scale advantage sits with integrated miners controlling magnesite deposit access. The market structures around three archetypes: fused-cast technology leaders, vertically integrated magnesia miners, and monolithic installation specialists. Consolidation pressure runs through magnesite supply security and digital service bundling.
Within the integrated mining tier, RHI Magnesita GmbH and Saint-Gobain anchor positions through captive raw material control. Shinagawa Refractories occupies a specialist position in monolithic formulations. These three exemplify how geographic deposit access and installation expertise segment competitive positioning across Asian utility markets.
| Leading Market Players |
|---|
| Saint-Gobain |
| Krosaki Harima Corporation |
| RHI Magnesita GmbH |
| Shinagawa Refractories |
| Morgan Advanced Materials |
| Vesuvius Plc |
| Imerys S.A. |
| Refratechnik Holding |
| HarbisonWalker International |
| Others |
Supply Flow & Price Mechanics
Shanghai-Rotterdam container freight corridors transmit magnesite ore cost volatility directly into alumina-magnesia castable price spreads, amplifying differentiation between European-integrated suppliers and Asian importers dependent on spot mineral markets.
Pricing Analysis
Geographic price spreads between Austrian-sourced fused magnesia and Chinese dead-burned alternatives exceed forty percent at mill gate, with quality grade and captive mine access as the primary differentiation drivers. Contract-based long-term offtake dominates procurement by Indian utilities under CEA-mandated efficiency timelines, compressing spot market liquidity. Cost compression in standard alumina-silica formulations is intensifying because Vietnamese and Indonesian buyers lack established local supply infrastructure. Cement producers exhibit highest price sensitivity due to fuel-pass-through economics, while Japanese specialty steelmakers prioritize slag resistance over unit cost.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for magnesia-based formulation producers. Raw material sourcing draws from Austrian, Slovakian, and Chinese magnesite deposits, with fused alumina aggregates anchored in Indian bauxite refining corridors. Single-source vulnerability concentrates in high-purity zirconia feedstock, where limited ex-China refining capacity constrains alternative sourcing. Distribution runs through regional blending plants co-located with utility-scale boiler construction clusters in Gujarat and Shandong provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical boiler retrofits under India's CEA mandates and China's MEE emission intensity thresholds constitute a high-growth disruption, compressing refractory replacement cycles and redirecting procurement toward performance-guaranteed formulations.
For Market Incumbents: Insulate premium positioning by deepening captive magnesite control through Austrian and Slovakian deposit expansion, countering Chinese export restriction vulnerability. Accelerate BIS and REACH certification parallelism to compress multi-jurisdiction approval timelines threatened by diverging regulatory frameworks.
For New Entrants and Emerging Players: Vietnam's coal-fired capacity expansion without established local refractory supply infrastructure offers the most penetrable white-space target for import substitution plays. Target turnkey service contracts bundling monolithic installation with digital thermal monitoring, displacing material-only procurement in Indonesian cement and power generation corridors.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized refractory divisions lacking standalone digital service capabilities. Five-to-ten year viability hinges on carbon capture retrofit chemistry development and IoT-enabled outcome-based contracting penetration. Watch for amine-based CO2 absorption system standardization as the inflection signal redirecting R&D allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnesite Mining | Captive Austrian and Slovakian ore access secures formulation cost stability against Chinese export policy shifts. |
| Digital Thermal Monitoring Convergence | IoT sensor deployment enables outcome-based performance guarantees for Indian CEA-mandated utility contracts. |
| Carbon Capture Lining Chemistry Development | Amine-resistant formulations address unstandardized corrosion requirements in European CHP retrofit pipelines. |
| Regional Blending Plant Expansion | Co-location with Mundra and Hazira industrial corridors reduces freight exposure and outage response times. |
| Multi-Jurisdiction Certification Investment | Parallel BIS and REACH testing protocols compress approval timelines for manufacturers serving both Indian and EU markets. |
Methodological Framework
Operator-level perspectives from power plant maintenance directors, steel mill procurement leads, refractory installation contractors, and cement kiln operations managers anchored the qualitative base. Secondary validation drew from Central Electricity Authority circulars, Ministry of Ecology and Environment enforcement notices, EU F-Gas Regulation implementation guidance, and trade flow data through Shanghai and Rotterdam corridors. Bottom-up unit economics modeling triangulated against top-down sector absorption estimates across power generation, cement, chemical processing, and metal production end-uses.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, application intensity, material chemistry tier, and installation method complexity. CAGRs derived from fitted growth curves applied to utility-scale boiler installation pipelines and steelmaker retrofit timelines. Industry-specific inputs included CEA-mandated efficiency compliance deadlines and MEE emission intensity threshold enforcement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese state-owned mining conglomerates or rapid standardization of carbon capture lining specifications would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
China Ceramic Tiles Market
Ceramics
Global Industrial Clay Market
Ceramics
Glazed Ceramic Tile Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
Quartz Powder Market
Ceramics
Co-Fired Ceramic Market
Ceramics
Refractories Market
Ceramics
Optical Ceramics Market
Ceramics
Ceramic Armor Materials Market
Ceramics
China Ceramic Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
Ceramic Frit Market
Ceramics
Saudi Arabia Ceramic Tiles Market
Ceramics
Advanced Sintering Technologies Market
Ceramics
Nanoceramic Powder Market
Ceramics
Ceramic Pigments Market