
 Transparent Ceramics Market | 2026-2036
Transparent Ceramics Market Size, Share, and Industry Trends Forecast 2026-2036
Transparent Ceramics Market Intelligence
ISO 9001 certification for advanced ceramic supply chains is reorganizing vendor qualification in defense and aerospace procurement. CeramTec GmbH leverages its European manufacturing footprint to sustain long-term contracts with German automotive and industrial clients. CoorsTek Inc. anchors North American production through vertically integrated alumina and sapphire facilities in Colorado and Arkansas. Surmet Corporation dominates transparent armor and infrared window segments through specialized spinel processing capabilities.
Transparent ceramics are polycrystalline materials engineered for optical transmission in wavelengths from ultraviolet through mid-infrared, typically achieving in-line transmittance exceeding 80 percent through controlled grain-boundary elimination during densification. These materials serve critical functions where single-crystal sapphire fails on cost or scale, particularly in large-area armor panels and high-temperature optical systems. Sapphire leads product type demand through established semiconductor and LED substrate consumption, while spinel records the fastest growth trajectory driven by military infrared sensor and transparent armor programs. Hot isostatic pressing commands premium positioning in technology segmentation due to its capacity to eliminate residual porosity in complex geometries, whereas tape casting occupies cost-sensitive lighting and electronics display applications.
FDA regulations govern transparent ceramic components in medical imaging and surgical devices, while EAR and ITAR frameworks restrict international transfer of armor-grade materials and processing knowledge. EPA emissions standards shape sintering furnace operations and chemical vapor deposition waste management protocols for domestic manufacturers. Stakeholders must monitor evolving defense export controls and clean-energy manufacturing incentives as these frameworks increasingly determine which production technologies achieve commercial scale.
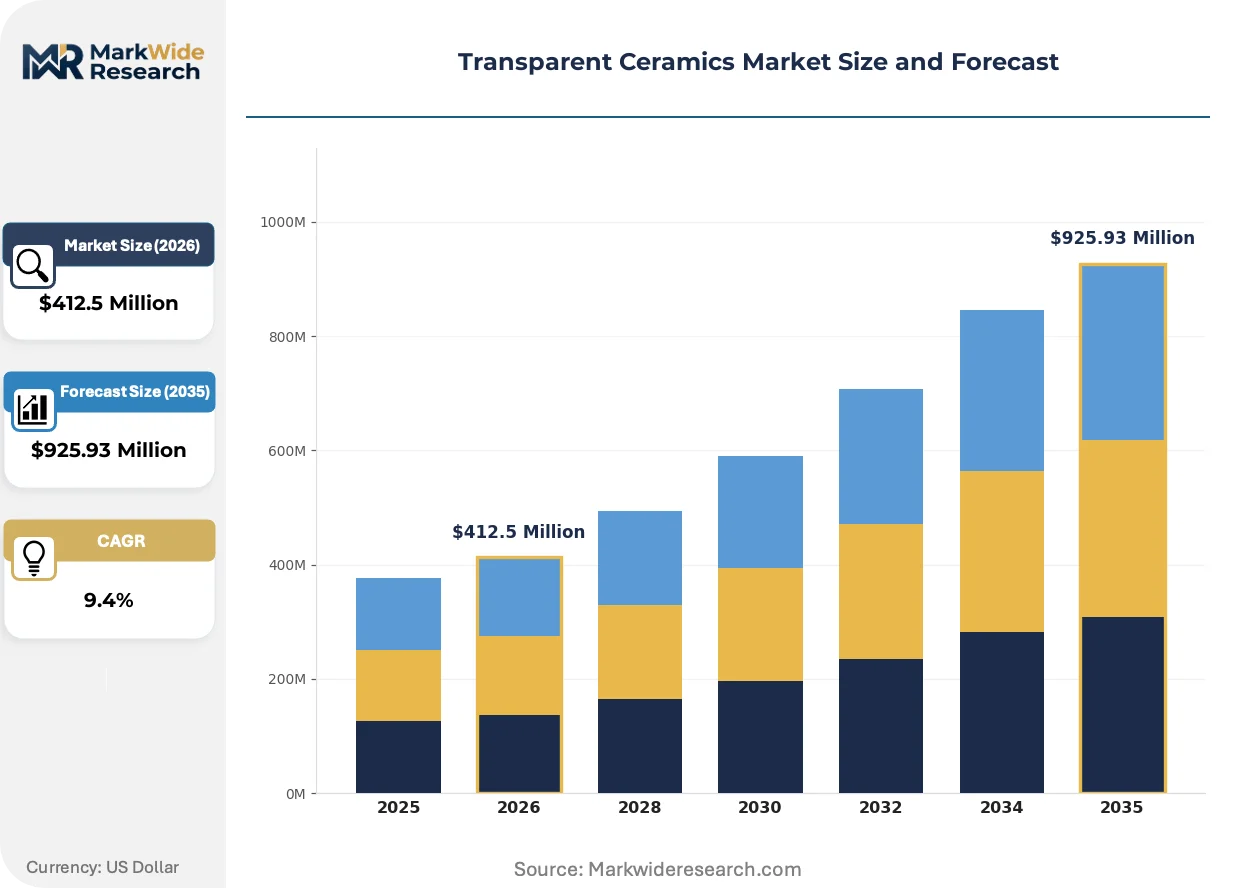
Market Dynamics
Defense procurement acceleration in the United States is compressing qualification timelines for transparent armor suppliers while simultaneously tightening ITAR compliance requirements. Hot isostatic pressing capacity constraints are creating supply bottlenecks for military-grade spinel.
Growth Catalysts
- ITAR-compliant domestic sourcing mandates:Pentagon transparent armor programs require U.S.-based processing facilities, redirecting contract flows toward domestic hot isostatic pressing operations.
- LED substrate demand:Semiconductor fabrication expansion in East Asia sustains sapphire wafer consumption for solid-state lighting applications.
- Infrared sensor proliferation:Military electro-optical systems drive spinel window procurement for thermal imaging platforms operating in harsh environments.
Market Restraints
- High-purity precursor scarcity:Magnesia and alumina feedstock price volatility constrains spinel and sapphire production economics.
- Equipment concentration in Japan and Germany:Hot isostatic pressing unit supply depends on a limited installed base of specialized furnace manufacturers.
- Single-crystal sapphire substitution:Czochralski-grown alternatives retain cost advantages for small-diameter optical components.
Strategic Opportunities
- India defense modernization:Indigenous transparent armor programs under the Make in India initiative create qualification pathways for foreign ceramic processors.
- Automotive LiDAR integration:Autonomous vehicle sensor housings demand thermally stable infrared-transparent windows.
- EU Green Deal manufacturing incentives:Clean-energy sintering technology investments reduce carbon intensity for European ceramic producers.
Industry Challenges
- ISO 9001 certification timelines:Defense and aerospace vendor qualification cycles extend 18-24 months, delaying revenue recognition for new entrants.
- Hot isostatic pressing capex intensity:Furnace installations require $15-25 million capital commitments with 5-7 year depreciation schedules.
- ITAR technical data restrictions:Export-controlled processing knowledge limits cross-border engineering collaboration and talent mobility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transparent Ceramics Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $925.93 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Yttria, Spinel, Sapphire, Magnesium Oxide Technology: Sintering, Hot Isostatic Pressing, Chemical Vapor Deposition, Sol-Gel, Tape Casting Application: Optical Lenses, Armor, Electronics Displays, Infrared Sensors, Lighting End User Industry: Aerospace, Defense, Consumer Electronics, Telecommunications, Scientific Instruments |
| Companies Covered | CeramTec GmbH, CeraNova, CoorsTek Inc., Brightcrystals Technology Inc., AGC Inc., Schott AG, Konoshima Chemical Co., Ltd., KYOCERA Corporation, Surmet Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transparent Ceramics Market Strategic Shifts & Innovations
Processing technology divergence is fragmenting the competitive landscape into defense-qualified specialists and commercial-scale commodity producers. Regulatory pressure on supply chain transparency is accelerating certification investments.
Hot isostatic pressing is bifurcating the transparent ceramics market into premium military-grade spinel and cost-optimized commercial alumina segments. Defense contractors in the United States absorb extended lead times for ITAR-compliant processing, while lighting and display manufacturers migrate toward tape-cast alternatives. This technological schism is compressing margins for mid-tier processors lacking either defense qualifications or commercial scale.
REACH substance restrictions in Europe are forcing reformulation of chemical vapor deposition precursors and sintering aid chemistries. Ceramic manufacturers serving medical imaging and industrial laser markets must document supply chain compliance through SCIP database entries. German and French producers face the steepest transition costs due to legacy reliance on boron-based densification additives.
Defense procurement consolidation is compressing supplier qualification cycles while extending contract durations. Prime contractors in the United States now bundle transparent armor with platform-level systems integration, displacing component-level vendors. This pattern concentrates procurement decision-making within Pentagon program offices and tier-one integrators.
Transparent Ceramics Market Segmentation
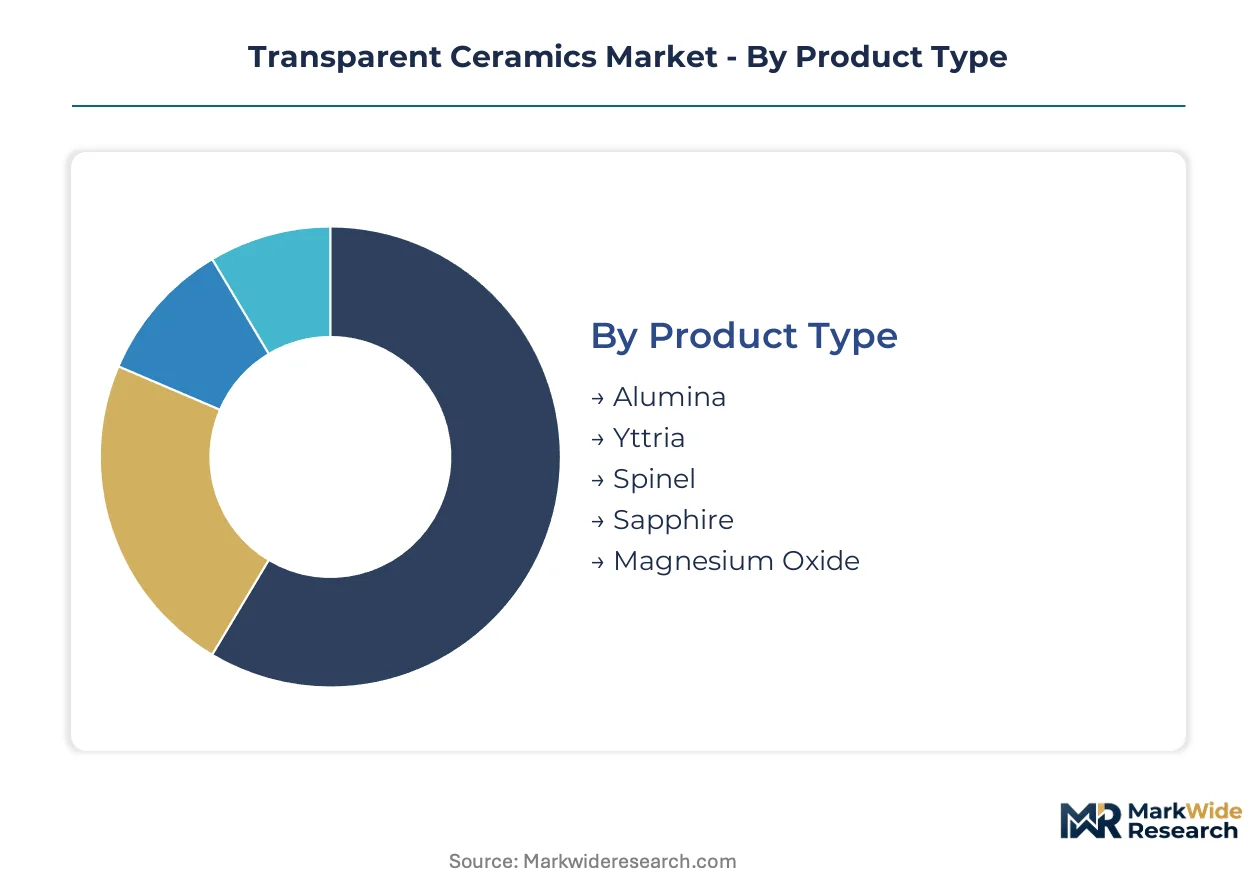
Transparent ceramics demand fragments across distinct procurement channels. Defense program offices source through ITAR-qualified processors. Commercial electronics buyers prioritize scale and cost predictability.
Product Type:
Defense contractors source spinel and sapphire through specialized hot isostatic pressing channels. Consumer electronics buyers procure alumina via high-volume tape casting distributors.
- Sapphire:Single-crystal and polycrystalline variants achieve optical transmission exceeding 80 percent in ultraviolet through mid-infrared wavelengths. Semiconductor fabrication in East Asia sustains wafer demand for LED substrates and optical windows.
- Spinel:Magnesium aluminate composition delivers superior mechanical strength and broadband infrared transparency compared to sapphire at equivalent thicknesses. Pentagon transparent armor programs and thermal imaging sensor housings in the United States absorb the majority of qualified supply.
- Alumina:Cost-optimized polycrystalline alumina serves lighting diffusers and electronic substrates through tape casting supply chains.
- Yttria:Rare-earth oxide composition provides plasma-resistant properties for semiconductor processing equipment and high-temperature optical systems.
- Magnesium Oxide:High-purity MgO substrates support thin-film deposition applications in scientific instrumentation and specialized optical coatings.
Sapphire dominates installed base. Spinel is where expansion concentrates.
Technology:
Cost tiers separate premium military-grade processing from commodity commercial methods. Furnace capex requirements create stark margin differentiation.
- Hot Isostatic Pressing:Gas-pressure densification at elevated temperatures eliminates residual porosity in complex geometries, achieving optical clarity thresholds required for armor and infrared windows. Equipment concentration in Japan and Germany constrains capacity expansion for defense-qualified suppliers.
- Sintering:Conventional pressureless and pressure-assisted methods dominate high-volume alumina production for lighting and electronics applications where optical specifications permit controlled grain-boundary scattering.
- Chemical Vapor Deposition:Vapor-phase precursor delivery enables conformal coating and near-net-shape fabrication for specialized optical components and protective layers.
- Sol-Gel:Colloidal processing routes offer lower-temperature densification for thin films and coatings where thermal budget constraints apply.
- Tape Casting:Continuous slurry deposition methods serve cost-sensitive display and lighting markets requiring large-area planar substrates.
Sintering commands volume share. Hot isostatic pressing captures value concentration.
Application:
Customer type determines specification stringency. Military buyers impose qualification cycles extending 18-24 months. Commercial buyers prioritize throughput and price stability.
- Armor:Transparent vehicle and personnel protection panels demand large-area spinel and sapphire with ballistic-grade mechanical properties. ITAR-compliant domestic sourcing mandates in the United States restrict supplier pools to qualified domestic processors.
- Infrared Sensors:Thermal imaging and electro-optical system windows require broadband infrared transmission combined with environmental durability for harsh operational conditions.
- Optical Lenses:Precision optical systems utilize sapphire and spinel for ultraviolet and infrared applications where thermal stability exceeds glass limitations.
- Electronics Displays:Transparent ceramic substrates enable high-brightness LED and emerging micro-LED architectures through controlled thermal management.
- Lighting:High-temperature lamp envelopes and solid-state lighting components leverage alumina transparency in visible wavelengths.
Armor absorbs premium capacity. Infrared sensors are climbing the fastest.
End User Industry:
Geography shapes procurement patterns. Defense concentration in the United States contrasts with electronics manufacturing clustering in East Asia.
- Defense:Pentagon program offices and tier-one integrators bundle transparent armor with platform-level systems, compressing component vendor access. ITAR technical data restrictions limit cross-border engineering collaboration.
- Aerospace:Commercial and military aircraft window and sensor applications demand lightweight, thermally stable optical materials qualified to FAA and military airworthiness standards.
- Consumer Electronics:Smartphone camera lenses and wearable device windows sustain sapphire demand through established supply relationships with fabrication facilities in Japan and South Korea.
- Telecommunications:Optical fiber components and laser system housings utilize transparent ceramics for thermal and mechanical stability in signal transmission infrastructure.
- Scientific Instruments:Research and analytical equipment manufacturers source specialized substrates through qualified scientific supply distributors with documented traceability.
Defense anchors qualification-intensive supply. Consumer electronics drive volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement mandates and clean-energy manufacturing incentives are redirecting transparent ceramics investment toward qualified domestic processing facilities across major industrial economies.
United States
Pentagon transparent armor programs and ITAR-compliant sourcing requirements sustain demand for military-grade spinel. The Department of Defense compresses supplier qualification timelines while extending contract durations. Colorado and Arkansas host vertically integrated alumina and sapphire production facilities serving defense and commercial markets.
Germany
Automotive LiDAR sensor development and industrial laser applications drive demand for thermally stable optical substrates. REACH substance restrictions force reformulation of chemical vapor deposition precursors and sintering aid chemistries. Bavaria and Baden-Württemberg concentrate European manufacturing footprint for long-term automotive and industrial contracts.
Japan
Semiconductor fabrication expansion and solid-state lighting applications sustain sapphire wafer consumption. METI industrial policy supports advanced ceramics supply chain resilience. Konoshima Chemical and KYOCERA anchor established sapphire substrate operations in Osaka and Kyoto prefectures.
China
Domestic LED substrate manufacturing and emerging transparent armor programs absorb polycrystalline alumina and spinel capacity. MIIT technology roadmaps prioritize optical materials self-sufficiency. Yangtze River Delta fabrication clusters concentrate tape-casting capacity for cost-sensitive display and lighting markets.
India
Indigenous transparent armor initiatives under the Make in India initiative create qualification pathways for foreign ceramic processors. BIS standards alignment and defense procurement localization requirements reshape vendor selection. Maharashtra and Gujarat host emerging sintering operations targeting automotive and defense applications.
Transparent Ceramics Market Key Industry Players
Player mix skews toward defense-qualified specialists and commercial-scale commodity producers. Market structure concentrates premium military-grade capacity within ITAR-compliant domestic facilities while fragmenting cost-optimized commercial supply across Asian tape-casting operations. Two strategic archetypes dominate: vertically integrated processors controlling precursor through finished component production, and specialized spinel fabricators focused on infrared window and transparent armor niches. Competitive moves center on hot isostatic pressing capacity expansion and strategic partnerships for defense program bundling.
Among German-based fabricators, CeramTec GmbH exemplifies the European vertically integrated archetype through its manufacturing footprint serving automotive and industrial clients. Japanese specialists Konoshima Chemical Co., Ltd. and KYOCERA Corporation occupy positions within the established sapphire substrate tier, leveraging decades of semiconductor supply relationships. Surmet Corporation represents the defense-qualified specialist model, anchoring transparent armor and infrared window segments through specialized processing capabilities.
| Leading Market Players |
|---|
| CeramTec GmbH |
| CeraNova |
| CoorsTek Inc. |
| Brightcrystals Technology Inc. |
| AGC Inc. |
| Schott AG |
| Konoshima Chemical Co., Ltd. |
| KYOCERA Corporation |
| Surmet Corporation |
| Others |
Cost & Logistics Intelligence
ITAR compliance requirements gate both supplier qualification and price differentiation simultaneously, restricting premium transparent armor contracts to domestic hot isostatic pressing facilities while relegating non-compliant processors to commoditized alumina segments. Pentagon procurement mandates compress vendor pools to ITAR-qualified domestic processors, amplifying pricing power for certified spinel suppliers while tape-casting operations compete on volume scale.
Pricing Analysis
Certification level (ITAR/ISO 9001-grade) creates the primary spread between defense-qualified spinel and commercial alumina tiers. Three-tier pricing structure separates ITAR-compliant armor-grade spinel from industrial sapphire substrates and cost-optimized lighting alumina. Cost compression in tape-cast alumina is intensifying because Yangtze River Delta capacity expansion outpaces LED substrate demand growth. Commercial electronics buyers exhibit highest price sensitivity, while Pentagon program offices absorb premiums for qualified domestic processing.
Supply Chain Analysis
Port congestion on transpacific lanes elevates inbound logistics costs for magnesia and alumina precursors sourced from Australian and Chinese mining operations. Hot isostatic pressing equipment draws from Japanese and German furnace manufacturers, creating single-source vulnerability for defense-qualified capacity expansion. Chemical vapor deposition precursors hinge on European specialty chemical suppliers subject to REACH reformulation mandates. Distribution runs through ITAR-compliant domestic facilities for military-grade spinel, while commercial sapphire feeds through Osaka and Kyoto fabrication clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transparent ceramics penetration sits at early-cycle expansion, with automotive LiDAR sensor adoption representing the most visible consumer-market tailwind beyond established defense and semiconductor channels.
For Market Incumbents: Shield qualified spinel margins by accelerating hot isostatic pressing capacity additions in Colorado and Arkansas before ITAR-compliant demand outstrips domestic supply. Cement long-term offtake relationships with Pentagon program offices to lock out emerging competitors facing 18-24 month qualification timelines. Counter single-crystal sapphire substitution threats in small-diameter optics through backward integration into precursor refining. For New Entrants and Emerging Players: Differentiate on automotive LiDAR window certification, where thermally stable infrared-transparent substrates lack established supply relationships. Target Maharashtra and Gujarat sintering operations for cost-optimized alumina serving India's Make in India defense localization requirements. Pursue joint qualification pathways with German automotive Tier 1 suppliers seeking REACH-compliant ceramic sensor housings. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hot isostatic pressing sub-segments as furnace manufacturers extend delivery timelines and Pentagon contracts lengthen. Five-to-ten year viability favors processors with captive precursor supply or established ITAR qualifications rather than commodity tape-casting operations. Monitor BIS standards alignment progress in India as the signal indicating when foreign ceramic processors can access indigenous armor programs.| Strategic Initiative | Industry Significance |
|---|---|
| Hot Isostatic Pressing Capacity Expansion | ITAR-compliant furnace installations in Colorado and Arkansas capture Pentagon transparent armor contract flows. |
| Backward Integration into Precursor Refining | Captive magnesia and alumina supply hedges feedstock price volatility constraining spinel production economics. |
| Automotive LiDAR Certification Investment | Thermally stable infrared window qualification opens autonomous vehicle sensor housing demand beyond military applications. |
| India Defense Localization Partnership | Maharashtra and Gujarat sintering joint ventures align with BIS standards and Make in India procurement mandates. |
| REACH-Compliant CVD Precursor Reformulation | Boron-free densification additive development preserves European medical imaging and industrial laser market access. |
Research Approach
The analysis maps defense-qualified spinel processing, commercial sapphire substrate fabrication, and cost-optimized alumina tape casting, each validated through procurement officers at Pentagon program offices, plant managers at Japanese ceramic manufacturers, and technical directors at German automotive Tier 1 suppliers. Primary interview findings triangulate against SEC 10-K filings from listed ceramic processors, customs data on magnesia and alumina trade flows, and ITAR compliance registry entries. Bottom-up capacity assessments and top-down demand modeling converge on segment-level outputs.
Consistency checks validated volume and value outputs against external benchmarks including semiconductor wafer shipment data and defense procurement contract announcements. The analytical framework segments by product type, technology tier, application stringency, and end-user industry across the projection horizon. CAGRs derive from installed base growth rates and replacement demand patterns, with specific inputs including LED substrate consumption trends and infrared sensor platform deployment schedules.
The analysis sits within stated boundaries; outcomes outside sustained Pentagon procurement acceleration or automotive LiDAR adoption timelines would require recalibration. Forecasts reflect assumptions regarding ITAR compliance continuity, REACH substance restriction implementation, and hot isostatic pressing equipment delivery schedules. Practitioners should keep alternative scenarios live as defense export control frameworks and clean-energy manufacturing incentives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Vaterite Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Heat-Resistant Ceramic Tableware Market
Ceramics
Ceramic Solid End Mills Market
Ceramics
China Ceramic Tiles Market
Ceramics
Calcium Oxide Market
Ceramics
Zirconia Ceramics Market
Ceramics
Fire Clay Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
Active Calcium Silicate Market
Ceramics
Philippines Ceramic Tiles Market
Ceramics
India Kaolin Market
Ceramics
Thermal Spray Powder Market
Ceramics
Ceramic Lining Market
Ceramics
Aluminium Nitride Market
Ceramics
Optical Ceramics Market