
 Photographic Paper Market | 2026-2036
Photographic Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Photographic Paper Market Outlook
Professional studio printing is decoupling from mass consumer snapshot output as a revenue anchor. Fujifilm leverages its chemical coating heritage to dominate archival fiber-based lines. Mitsubishi Paper Mills sustains integrated pulp-to-paper production across Japanese facilities. Ilford specializes in silver-halide monochrome stocks for a shrinking but loyal darkroom segment.
Photographic paper consists of a base substrate—wood pulp, alpha cellulose, or synthetic resin—coated with light-sensitive emulsions or ink-receptive microporous layers, engineered for optical density, D-max, and color gamut reproduction in analog or digital output systems. Glossy stocks command the widest volume base in commercial labs, while fiber-based papers capture premium margin pools among museum and gallery clients. Resin-coated material anchors high-speed minilab throughput, and satin finishes are gaining preference in portrait studio workflows where glare control matters.
EPA wastewater discharge rules and REACH substance restrictions shape coating chemistry choices and plant siting decisions for manufacturers serving North American and European buyers. Japan's METI energy efficiency standards influence drying and calendering equipment investments at domestic mills. Stakeholders must monitor how evolving chemical disclosure requirements alter raw material qualification timelines and regional sourcing flexibility.
Market Dynamics
Fine art photographers and museum conservators now drive margin capture, while mass-market snapshot printing collapses. This demand bifurcation concentrates premium coating expertise in Japanese and German supply clusters.
Growth Catalysts
- REACH substance disclosure:European ECHA registration requirements for silver-based emulsion precursors are accelerating qualification of archival-grade chemistries among coating specialists.
- Japan's precision paper mills:Domestic alpha-cellulose refining and proprietary baryta layering sustain captive supply chains for museum-certified fiber stocks.
- Inkjet receptor microporous coatings:Pigment-accepting surface engineering is expanding addressable volume among digital fine art printmakers.
Market Restraints
- Silver price volatility:Photographic-grade silver nitrate input costs swing with commodity futures, compressing margin predictability for emulsion coaters.
- Single-region pulp dependence:Alpha-cellulose supply concentrates in Nordic and Canadian softwood regions, exposing base stock producers to freight and tariff friction.
- Darkroom skill attrition:Silver-halide chemical processing expertise is vanishing from vocational training, constraining monochrome paper utilization.
Strategic Opportunities
- India's heritage digitization mandate:National museum conservation programs are seeding demand for archival inkjet and traditional silver-halide documentation stocks.
- EU Green Deal chemical substitution incentives:Funding pools for solvent-reduced coating processes are opening qualification pathways for water-based microporous layers.
- Direct-to-studio distribution:Bypassing wholesale photo-imaging distributors, manufacturers are building e-commerce portals for professional printmakers.
Industry Challenges
- ISO 18916 lightfastness certification:Accelerated aging test protocols now require 12-18 month validation cycles, delaying new product launches.
- Legacy coating line retrofitting:Solvent-based emulsion equipment demands capital-intensive aqueous conversion to meet German TA Luft emission rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photographic Paper Market |
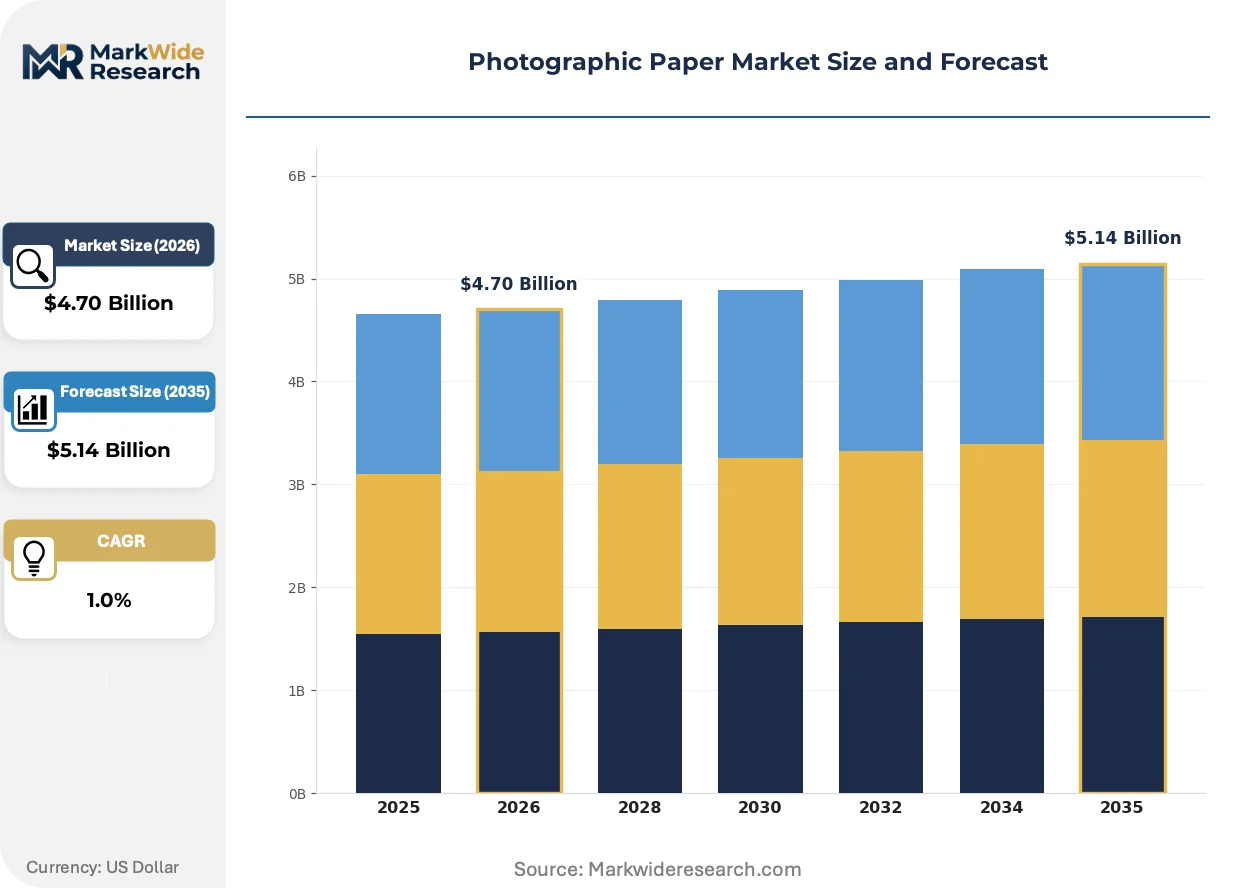
| Market Size in 2026 | $4.70 Billion |
| Market Size in 2035 | $5.14 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glossy, Matte, Satin, Luster Material: Paper, Resin Coated, Fiber Based, Specialty End User: Photographers, Artists, Studios, Educational Institutions Application: Print, Display, Framing, Digital Transfers |
| Companies Covered | Fujifilm, Mitsubishi Paper Mills, Eastman Kodak, Canon, Epson, HP, Ilford, Hahnemühle, PermaJet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photographic Paper Market Strategic Shifts
Coating chemistry and output format preferences are diverging sharply between volume commercial labs and premium archival producers. Three forces are reshaping technical roadmaps and supply relationships.
Nanoporous silica receptor layers are integrating into baryta-coated fiber bases, enabling pigment ink adhesion previously limited to resin-coated stocks. Fine art printmakers in Germany and Japan are adopting these hybrid constructions for gallery output. The technology is integrating archival longevity claims with production efficiency previously reserved for commercial minilabs.
ECHA REACH candidate list expansion is forcing reformulation of optical brightening agents and wetting surfactants in European coating facilities. Manufacturers serving EU museum clients are qualifying benzotriazole-free alternatives under shortened authorization timelines. Fiber-based paper lines for conservation photography face the steepest compliance recertification burden.
Consolidation among portrait studio chains is compressing supplier negotiation cycles and unbundling traditional paper-chemistry-service bundles. Independent studios in the US Northeast are migrating to direct manufacturer relationships, bypassing regional distributors. This channel shift is most visible in high-volume school and sports photography segments where contract terms now dominate material selection.
Photographic Paper Market Segmentation
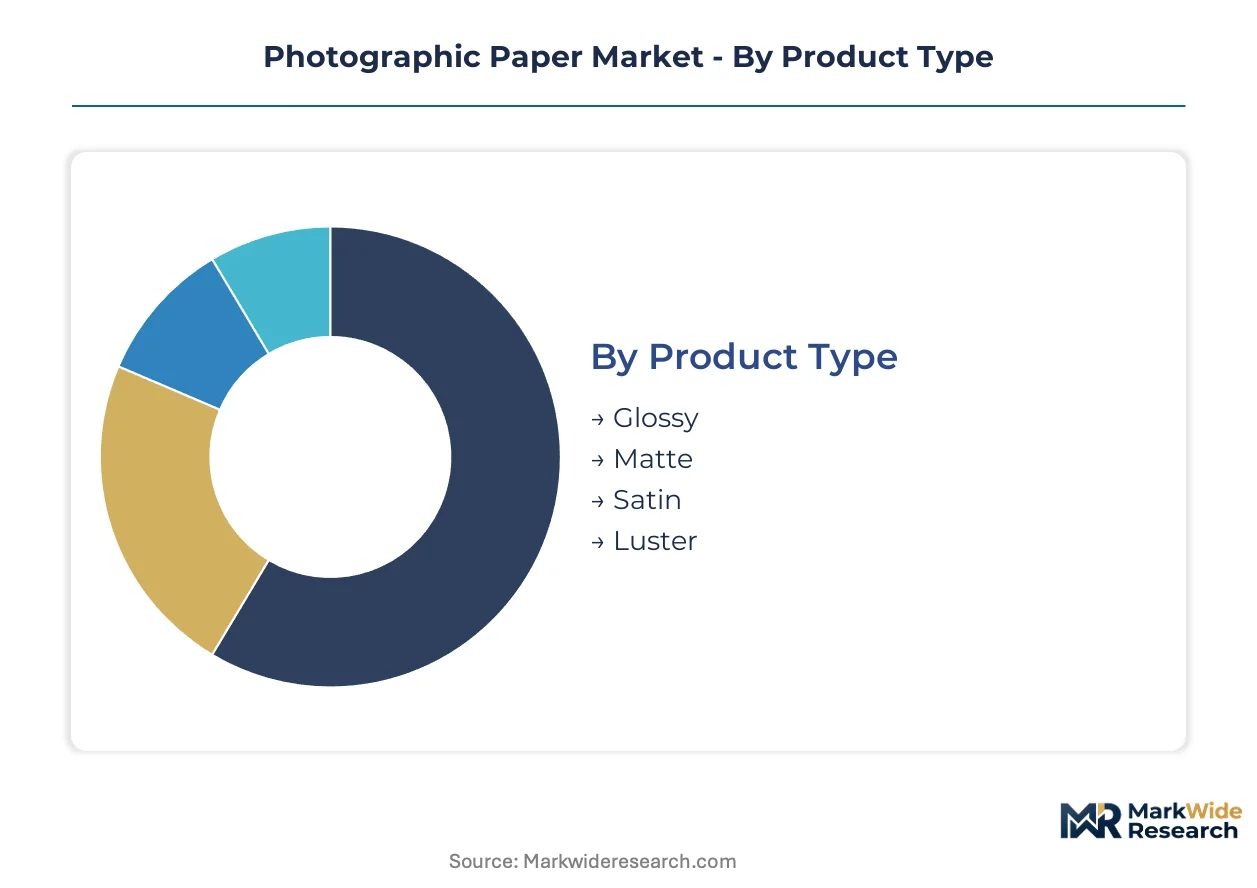
Photographic paper segmentation reveals how coating chemistry and surface engineering align with distinct output workflows. Professional printmakers select substrates based on archival longevity claims, ink compatibility, and display environment constraints.
Product Type:
Surface finish customization spans from high-gloss commercial output to glare-controlled portrait presentation, with each tier commanding different margin profiles.
- Glossy:Microporous coatings on resin bases maximize color saturation and D-max density for commercial minilabs. Wedding and event photographers in Japan specify these stocks for proofing volumes where visual punch drives client selection.
- Matte:Textured surfaces with reduced specular reflection suit fine art reproduction and museum display lighting. German gallery framers prefer matte fiber stocks for pigment ink portfolios where surface sheen distracts from tonal subtlety.
- Satin:Intermediate gloss levels balance durability with controlled reflection for portrait studio environments.
- Luster:Pearlized surfaces enhance perceived depth in commercial portrait and school photography segments.
Leading the category by volume: Glossy. Expanding most quickly: Matte.
Material:
Base substrate selection separates commodity throughput from conservation-grade supply chains, with raw material sourcing determining regional production clusters.
- Paper:Wood-pulp bases with aqueous coatings serve high-volume consumer snapshot printing through retail minilabs. Cost sensitivity here limits coating sophistication and compresses supplier margins.
- Resin Coated:Polyethylene-laminated bases enable rapid chemical processing and dimensional stability under humidity swings. Portrait studios across the US Northeast rely on resin-coated stocks for school photography contracts requiring same-day turnaround.
- Fiber Based:Alpha-cellulose or cotton rag substrates with baryta layers deliver archival longevity certified by ISO standards.
- Specialty:Synthetic bases and metallic receptor coatings serve niche display and industrial proofing applications.
Fiber-based substrates capture premium pricing tiers. Resin-coated material dominates unit volumes.
End User:
Customer sophistication ranges from institutional procurement offices to individual practitioners, with technical support requirements scaling accordingly.
- Photographers:Professional image-makers specify paper by color gamut matching and printer compatibility, with wedding specialists in India driving demand for archival documentation stocks.
- Artists:Fine art printmakers prioritize lightfastness certification and substrate texture for limited-edition sales.
- Studios:Volume operations negotiate contract pricing based on annual square-meter consumption.
- Educational Institutions:University photography programs balance curriculum requirements against budget constraints, often standardizing on single paper lines across darkroom and digital output courses.
Studios generate the largest aggregate tonnage. Artists deliver the steepest per-unit margins.
Application:
Output destination—immediate handling versus long-term preservation—determines coating durability requirements and certification needs.
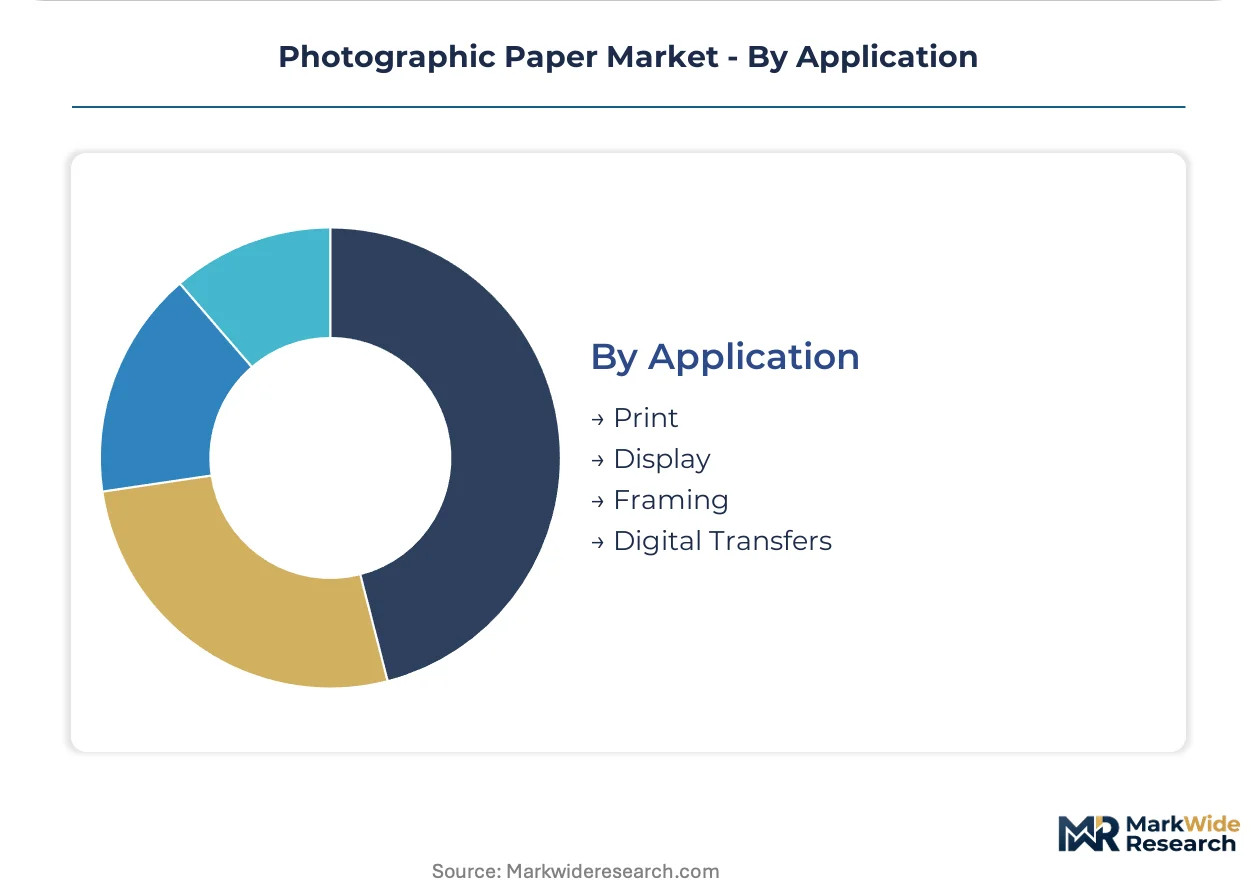
- Print:Direct photographic or inkjet output for portfolio, proofing, and sale purposes constitutes the core volume application.
- Display:Exhibition-mounted prints face UV exposure and handling stress, driving demand for protective laminate-compatible surfaces.
- Framing:Glazing interaction and mat board contact influence pH buffering and edge-sealing specifications.
- Digital Transfers:Dye-sublimation and heat-transfer workflows require specialized receptor coatings on transfer-release bases.
Standard print output anchors baseline demand. Display applications are gaining share fastest among premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese mills produce the majority of archival-grade fiber stocks, while consumption concentrates in European museum labs and North American portrait studios. This geographic split shapes trade flows and regulatory compliance requirements across coating chemistry supply chains.
Japan
Fine art photographers in Tokyo and Osaka drive demand for museum-certified baryta papers. METI energy efficiency standards govern drying equipment investments at domestic mills. Precision coating clusters in Shizuoka Prefecture sustain captive alpha-cellulose refining for premium export lines.
Germany
Gallery framers in Berlin and Munich specify matte fiber stocks for pigment ink portfolios. ECHA REACH substance restrictions force reformulation of optical brightening agents at coating facilities. Industrial concentration in North Rhine-Westphalia supports solvent-reduced aqueous layer development under TA Luft emission rules.
United States
Portrait studio chains in the Northeast negotiate contract pricing for high-volume school photography. EPA wastewater discharge rules shape coating chemistry choices for manufacturers serving domestic buyers. Independent studios increasingly bypass distributors through direct manufacturer e-commerce portals.
India
National museum conservation programs seed demand for archival documentation stocks. Heritage digitization mandates from the Archaeological Survey of India drive procurement of both inkjet and silver-halide substrates. Conservation labs in Delhi and Mumbai anchor regional distribution for South Asian cultural institutions.
United Kingdom
Educational institutions balance curriculum requirements against constrained procurement budgets. University photography programs in London and Glasgow standardize on single paper lines across darkroom and digital output courses. Specialist distributors in the Southeast maintain stockholding for independent fine art printmakers.
Photographic Paper Market Competitive Environment
Top-tier vendors anchor archival fiber-based production, while mid-scale specialists occupy resin-coated and inkjet receptor niches. Japanese and German manufacturers concentrate premium coating expertise, while diversified imaging conglomerates span multiple output technologies. Three archetypes dominate: integrated pulp-to-paper mills, precision coating specialists, and diversified imaging technology providers. Competitive moves center on direct-to-studio distribution channel development and aqueous coating line retrofitting for regulatory compliance.
Within the integrated mill archetype, Mitsubishi Paper Mills exemplifies captive alpha-cellulose refining and proprietary baryta layering capabilities. Fujifilm occupies a position representing chemical coating heritage applied to archival fiber-based lines. Among European specialists, Hahnemühle and Ilford sit within distinct positioning—one exemplifying fine art paper mill tradition, the other representing silver-halide monochrome expertise for darkroom practitioners.
| Leading Market Players |
|---|
| Fujifilm |
| Mitsubishi Paper Mills |
| Eastman Kodak |
| Canon |
| Epson |
| HP |
| Ilford |
| Hahnemühle |
| PermaJet |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal chemical substitution incentives gate qualified supply and premium-tier pricing access for photographic paper manufacturers. REACH substance restrictions on optical brightening agents and wetting surfactants force coating reformulation investments that only integrated mills can absorb. Buyers seeking ISO 18916 archival certification face limited supplier pools, concentrating pricing power among Japanese and German producers with captive alpha-cellulose refining.
Pricing Analysis
Margin tightening in resin-coated tiers reflects silver nitrate commodity volatility and compressed school photography contract terms. Pricing stratifies across museum-certified fiber, professional portrait resin, and consumer snapshot economy tiers. Cost-down pressure on glossy minilab stocks accelerates as portrait studio chains consolidate procurement volumes. Educational institutions exhibit highest price sensitivity; museum conservators accept steep premiums for baryta-layered longevity claims.
Supply Chain Analysis
Japan's METI domestic-content standards for energy-efficient drying equipment reshape sourcing toward domestic mill investments. Alpha-cellulose supply draws from Nordic softwood and Canadian pulp regions, tethering base stock producers to freight cost exposure. Silver-halide precursor chemicals hinge on single-source specialty chemical houses in Germany and Japan. Distribution runs through wholesale photo-imaging channels, though direct manufacturer portals are displacing regional distributors in North American independent studio segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photographic paper supply is tightening around precision coating capacity. Japanese and German mills with proprietary baryta layering control premium-tier pricing.
For Market Incumbents: Cement archival fiber dominance by retrofitting solvent-based lines to aqueous coating systems compliant with German TA Luft rules. Deepen captive alpha-cellulose refining to offset Nordic pulp freight exposure. Defend against inkjet receptor specialists by integrating nanoporous silica layers into hybrid baryta constructions. For New Entrants and Emerging Players: Begin with India's heritage digitization procurement corridors, where Archaeological Survey of India mandates seed demand for archival documentation stocks. Target conservation labs in Delhi and Mumbai with water-based microporous coating qualifications under shortened EU authorization timelines. Establish direct e-commerce relationships with independent fine art printmakers bypassing legacy distributor markups. For Investors and Strategic Acquirers: ECHA REACH candidate list expansion is the leading indicator that coating chemistry reformulation burdens will consolidate supplier tiers. Long-term viability favors integrated pulp-to-paper mills with in-house emulsion expertise over resin-coated commodity converters. Watch for Japanese mill energy efficiency upgrade announcements as signals of capacity discipline sustaining premium pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Coating Line Retrofit | Enables TA Luft compliance for German facilities serving EU museum clients. |
| Direct-to-Studio E-Commerce Portal | Bypasses wholesale distributors in North American portrait photography segments. |
| Alpha-Cellulose Refining Capacity Expansion | Reduces Nordic pulp dependence for Japanese archival fiber producers. |
| Nanoporous Silica Layer Integration | Bridges pigment ink compatibility with traditional baryta archival claims. |
| REACH-Compliant Chemistry Qualification | Secures benzotriazole-free optical brightener supply for European coating lines. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this photographic paper analysis. Primary interviews with coating plant managers, museum procurement officers, portrait studio chain buyers, fine art printmakers, and specialty chemical distributors informed demand segmentation. Secondary sources included EPA wastewater discharge databases, ECHA REACH registration filings, Japanese customs export statistics, and SEC 10-K disclosures from diversified imaging conglomerates. Bottom-up volume modeling and top-down value reconciliation triangulated market estimates.
Data-stream reconciliation across shipment volumes, coating capacity utilization, and end-user procurement surveys shaped the analytical framework. Segmentation dimensions spanned surface finish, substrate material, end-user archetype, and output application across the projection horizon. CAGRs derived from historical trade flow trajectories and capacity expansion announcements. Silver price futures curves and pulp freight indices fed raw material cost assumptions.
Underlying measurement precision varies by segment; resin-coated volume flows carry tighter precision than specialty synthetic substrate estimates. Forecasts embed assumptions around REACH authorization timelines and METI energy efficiency compliance costs. Silver commodity volatility and darkroom skill attrition present revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Acrylic Paper Market
Paper Products
Africa Tissue Paper Market
Paper Products
Printing Paper Market
Paper Products
Paper and Board Technologies Market
Paper Products
White Line Chipboard Market
Paper Products
Europe Paper Market
Paper Products
Global Wood Pulp Market
Paper Products
North America Decor Paper Market
Paper Products
Functional and Barrier Coatings for Paper Market
Paper Products
Unbleached Hardwood Kraft Pulp Market
Paper Products
Clay Coated Paper Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Paper Coating Materials Market
Paper Products
Digital Printing Paper Market
Paper Products
Pulp Market
Paper Products
North America Coated Paper Market