
 Global Printing Blanket Market | 2026-2036
Global Printing Blanket Market Size, Share, and Industry Trends Forecast 2026-2036
Global Printing Blanket Market Foresight
Asset-light leasing models for high-performance printing blankets is fragmenting competitive dynamics across the value chain. Trelleborg AB leverages captive rubber compounding to sustain margin control in premium offset segments. Continental AG anchors European gravure demand through vertically integrated polymer development. Flint Group competes on digital blanket compatibility as narrow-web converters shift run lengths.
A printing blanket is a compressible elastomeric sleeve or sheet, typically 1.7–2.0 mm thick with multi-ply fabric reinforcement, that transfers ink from the plate cylinder to the substrate in rotary printing systems. Its surface hardness, measured in Shore A, and solvent swell resistance determine print fidelity and blanket life in high-speed commercial environments. Rubber blankets still dominate newspaper and book applications where cost-per-impression governs procurement, while hybrid constructions capture packaging lines requiring both UV and conventional ink compatibility. Silicon blankets lead narrow-web label segments where heat resistance and dimensional stability command price premiums over standard polymer alternatives.
EPA emission standards for volatile organic compounds in commercial print facilities restrict solvent-based blanket cleaners and push demand toward low-VOC surface treatments. REACH chemical registration requirements in Europe limit certain plasticizer chemistries, compelling reformulation of polymer blanket layers. China's GB standards for printing materials enforce migration limits on food-contact applications, shaping export-oriented blanket specifications. Stakeholders must weigh regional compliance divergence against platform standardization when allocating R&D budgets and qualifying supplier footprints.
Market Dynamics
REACH chemical restrictions and water-based ink compatibility requirements are fragmenting product portfolios across European converters, while Asia-Pacific packaging manufacturers compress replacement cycles under tightening food-contact compliance regimes.
Growth Catalysts
- UV-curable ink adoption:Packaging converters in Germany and China demand hybrid-composition blankets capable of running both UV and conventional chemistries without press downtime.
- India's export packaging expansion:Commercial print clusters in Mumbai and Chennai serve global food brands, driving specification upgrades to GB standards-compliant blanket constructions.
- Asset-light leasing models:Narrow-web label converters shift from ownership to performance-based contracts, lowering entry barriers for high-performance silicone blanket technologies.
Market Restraints
- Petrochemical input volatility:Nitrile rubber and synthetic fabric reinforcement costs fluctuate with crude oil indices, compressing margin predictability for compounders.
- Supply concentration in German polymer development:Three specialized compounders control premium gravure blanket formulations, creating qualification bottlenecks for new entrants.
- Silicone blanket heat-resistance ceilings:Narrow-web flexo presses exceeding 200 meters per minute face dimensional stability failures, limiting addressable speed segments.
Strategic Opportunities
- India's underpenetrated corrugated post-print segment:Domestic box converters still run 40% natural rubber blankets versus 15% in China, creating upgrade headroom.
- EPA VOC emission mandates:US commercial print facilities face phased solvent-based cleaner restrictions, accelerating demand for low-swell surface treatment chemistries.
- Digital-narrow-web convergence:Inkjet blanket compatibility requirements open specification windows for elastomeric layers with controlled porosity and static dissipation.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for multi-ply fabric-to-elastomer adhesion resides with retiring specialists in Akron and Leverkusen.
- Dual certification timelines:Blankets qualifying for both FDA food-contact and EFSA migration limits require 18-24 month validation cycles, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Printing Blanket Market |
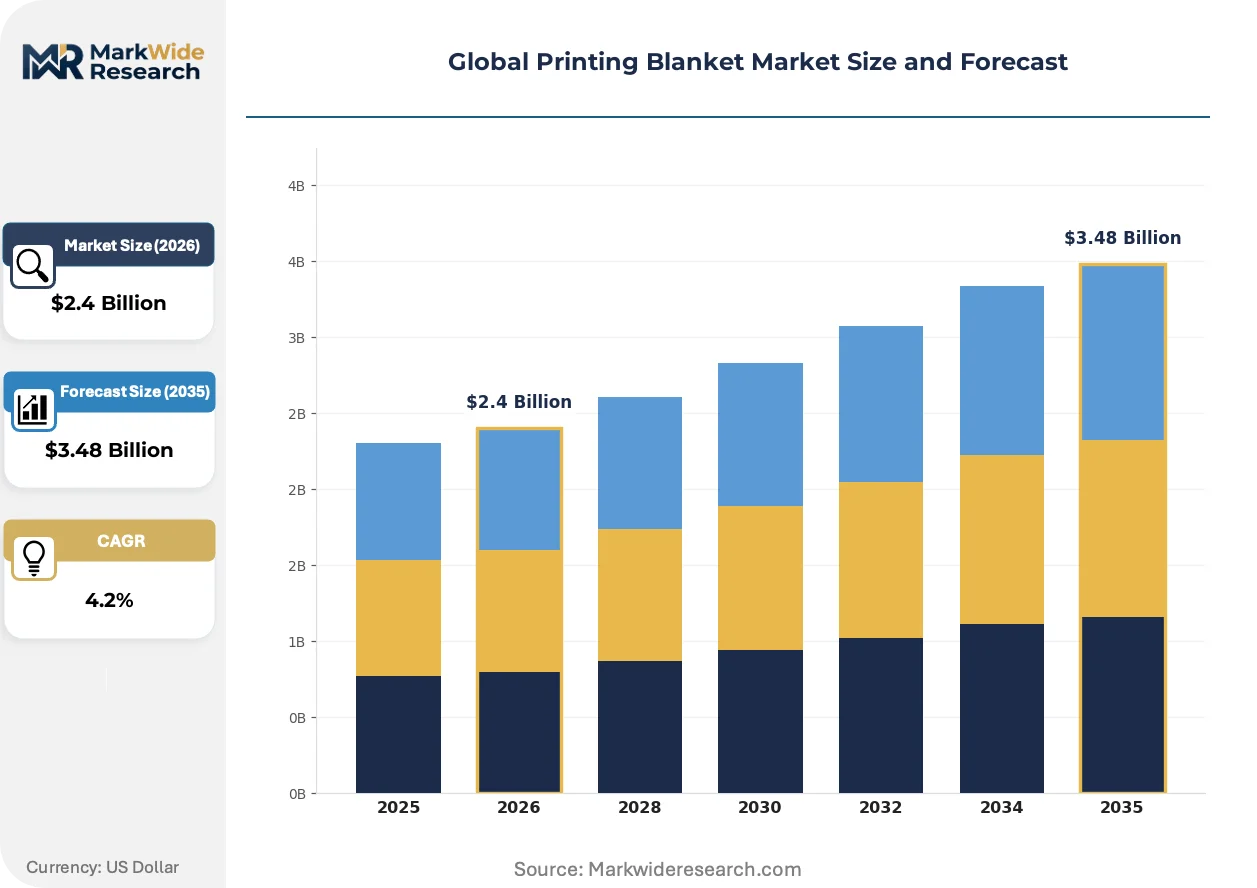
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, Polymer, Hybrid, Silicon, Polyester Technology: Offset, Gravure, Flexographic, Digital, Letterpress Application: Newspapers, Commercial Publishing, Packaging, Labeling, Security Printing End User: Print Shops, Advertising Agencies, Packaging Manufacturers, Publishing Houses, Design Studios |
| Companies Covered | Trelleborg AB, Continental AG (ContiTech), Flint Group, Fujikura Composites Inc., Kinyosha Co., Ltd., Habasit AG, Meiji Rubber and Chemical Co., Ltd., Birkan GmbH, Felix Böttcher GmbH and Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Printing Blanket Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are compressing traditional product lifecycles while opening specification windows for novel constructions.
Hybrid polymer-ceramic surface treatments are collapsing the performance gap between standard rubber and premium silicone blankets. Mid-tier packaging converters in Poland and Mexico adopt these constructions to run mixed UV-conventional jobs without dedicated press configurations. The technology is collapsing inventory complexity for converters serving multiple brand customers with incompatible ink specifications.
REACH Annex XVII restrictions on phthalate plasticizers force reformulation of compressible layer chemistries. European blanket manufacturers substitute bio-based polyester polyols and modified starch derivatives, sacrificing some solvent swell resistance for compliance security. German gravure houses now specify migration-tested constructions as standard, not premium, procurement criteria.
Converter procurement departments unbundle blanket supply from OEM press maintenance contracts. Independent service providers in Shanghai and São Paulo now source directly from compounders, bypassing traditional distributor markups. This pattern concentrates most visibly in narrow-web label segments where press downtime costs exceed blanket price differentials by an order of magnitude.
Global Printing Blanket Market Segmentation
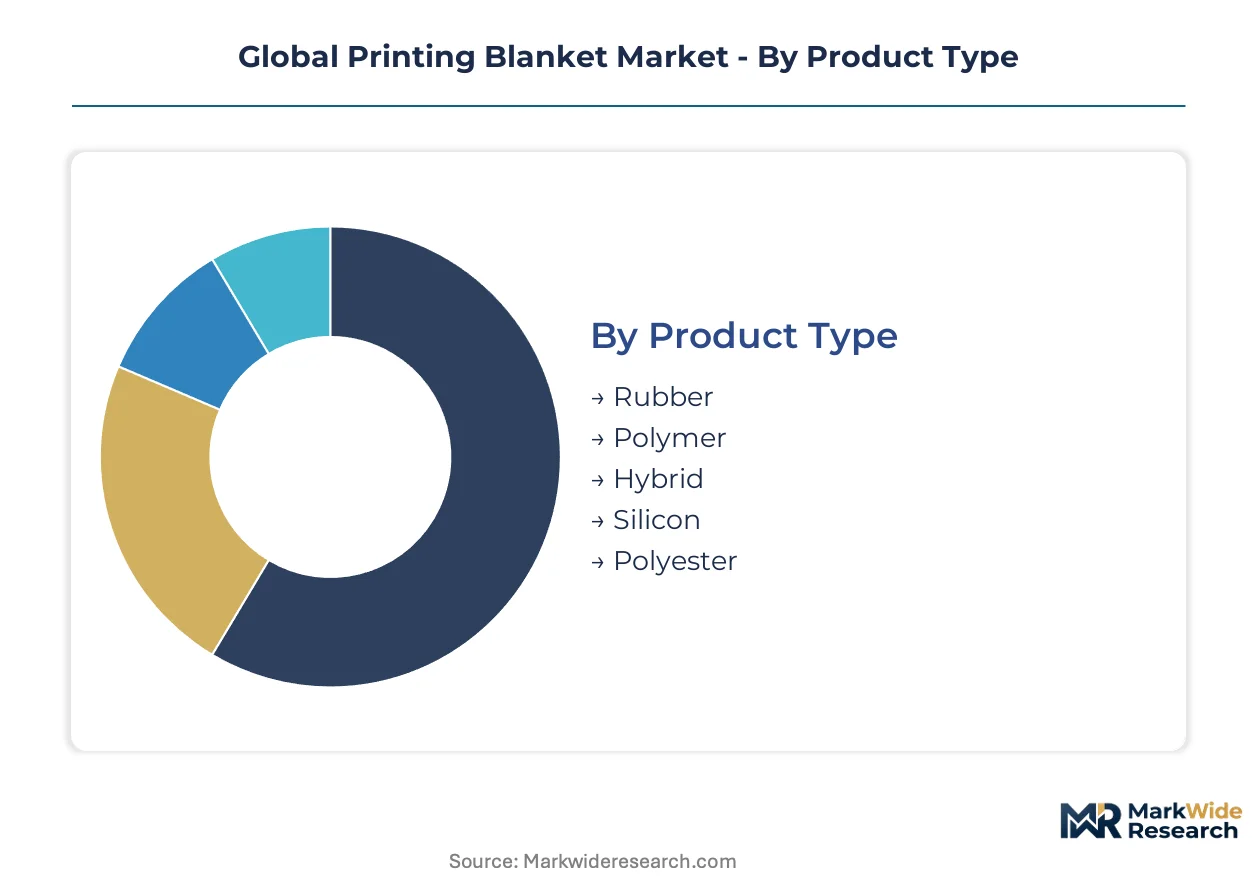
Printing blanket segmentation determines service contract structures, inventory holding costs, and technical qualification pathways. Product chemistry and press technology combinations create distinct aftermarket ecosystems with varying replacement cadences and margin profiles.
Product Type:
After-sales-service intensity varies dramatically across material platforms, with silicone and hybrid constructions demanding specialized technician deployment while rubber blankets rely on distributor-level support.
- Rubber:Natural and nitrile rubber formulations dominate newspaper and book printing where cost-per-impression drives procurement. Mumbai print clusters specify these for high-volume, short-run commercial jobs where blanket replacement occurs weekly.
- Hybrid:Multi-layer constructions blending elastomeric polymers with ceramic surface treatments capture packaging converters running mixed UV-conventional ink schedules. German gravure houses specify migration-tested hybrid constructions as standard procurement criteria under REACH Annex XVII constraints.
- Polymer:Synthetic elastomer sheets serve mid-tier commercial publishers seeking solvent swell resistance without silicone premiums.
- Silicon:Silicone blankets command narrow-web label segments where heat resistance above 180°C and dimensional stability justify price premiums over standard polymers.
- Polyester:Fabric-reinforced polyester constructions anchor textile printing and specialty coating applications requiring chemical resistance.
Rubber holds the largest share; momentum sits with hybrid constructions gaining share fastest in packaging conversion.
Technology:
Press technology segmentation maps directly to blanket specification complexity, with offset and gravure demanding multi-ply reinforced constructions while digital presses impose novel static dissipation and porosity requirements.
- Offset:Multi-ply fabric-reinforced blankets, typically 1.7–2.0 mm thick with Shore A hardness specification, transfer ink from plate cylinder to substrate in rotary systems. China's export-oriented packaging hubs in Guangdong province drive specification upgrades to GB standards-compliant constructions for food-contact applications.
- Gravure:Premium polymer formulations with vertically integrated development in Germany serve high-speed publication and decorative printing. Three specialized compounders control premium gravure blanket formulations, creating qualification bottlenecks for new entrants.
- Flexographic:Compressible sleeves and continuous printing blankets serve corrugated post-print and flexible packaging segments. India's domestic box converters still run 40% natural rubber blankets versus 15% in China, creating upgrade headroom.
- Digital:Inkjet blanket compatibility requirements open specification windows for elastomeric layers with controlled porosity and static dissipation properties. Narrow-web converters shift from ownership to performance-based contracts, lowering entry barriers for specialized constructions.
- Letterpress:Harder Shore A specifications serve security printing and specialty applications requiring precise impression control.
Offset maintains volume leadership; digital represents the fastest-growing trajectory as narrow-web converters adopt inkjet platforms.
Application:
Application segmentation reveals diverging compliance burdens, with food-contact packaging facing 18-24 month dual certification timelines while commercial publishing operates under lighter regulatory scrutiny.
- Packaging:Food-contact compliance rules in China, Germany, and India compress replacement cycles and mandate migration-tested constructions. Asia-Pacific packaging manufacturers accelerate blanket replacement as GB standards and EFSA limits tighten.
- Labeling:Narrow-web flexo and digital presses exceeding 200 meters per minute face dimensional stability failures with standard silicone constructions, limiting addressable speed segments. Asset-light leasing models concentrate visibly here.
- Newspapers:Cost-per-impression procurement governs rubber blanket selection in high-volume daily print operations.
- Commercial Publishing:Book and magazine printers balance solvent swell resistance against capital equipment amortization schedules.
- Security Printing:Letterpress and intaglio specifications demand precise hardness control for currency and document authentication applications.
Packaging commands the largest revenue pool; labeling climbs the fastest on digital-narrow-web convergence.
End User:
End-user segmentation determines procurement centralization, with packaging manufacturers consolidating blanket supply decisions while print shops fragment across independent service providers.
- Packaging Manufacturers:Export-oriented converters in Mumbai, Chennai, and São Paulo source directly from compounders, bypassing traditional distributor markups. EPA VOC emission mandates accelerate demand for low-swell surface treatment chemistries in US facilities.
- Print Shops:Commercial print clusters in Germany and China serve multiple brand customers with incompatible ink specifications, collapsing inventory complexity through hybrid constructions.
- Advertising Agencies:Spec-driven procurement for short-run promotional materials favors quick-change blanket systems.
- Publishing Houses:Newspaper and book publishers prioritize cost-per-impression metrics in long-term supply agreements.
- Design Studios:Proofing and prototype work drives demand for precision-calibrated blanket specifications.
Packaging manufacturers hold the largest share; print shops show steepest expansion trajectory on unbundled procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented packaging converters in China, Germany, and India drive blanket specification upgrades as food-contact compliance rules tighten across multiple jurisdictions.
China
Guangdong province packaging hubs serve global food brands demanding GB standards-compliant constructions. MEE enforcement of migration limits on food-contact materials compresses replacement cycles for export-oriented converters. Shenzhen and Dongguan clusters now specify hybrid blankets as standard procurement for mixed UV-conventional production lines.
Germany
Gravure houses in Baden-Württemberg and North Rhine-Westphalia anchor European demand for premium polymer formulations. REACH Annex XVII phthalate restrictions force reformulation of compressible layer chemistries across domestic compounders. Leverkusen and Stuttgart industrial corridors specify migration-tested constructions as baseline requirements, not premium tiers.
India
Mumbai and Chennai commercial print clusters supply global food packaging brands, driving specification upgrades to GB standards-compatible blanket constructions. FSSAI enforcement of food-contact material rules accelerates replacement cycles among export-oriented converters. Maharashtra and Tamil Nadu corrugated post-print segments still run 40% natural rubber blankets versus 15% in China, creating substantial upgrade headroom.
United States
Commercial print facilities in Illinois and Wisconsin face EPA phased restrictions on solvent-based blanket cleaners. FDA food-contact certification requirements extend qualification timelines for packaging converters serving multinational CPG brands. Chicago and Milwaukee metro areas show accelerating demand for low-swell surface treatment chemistries compliant with evolving VOC emission mandates.
Japan
Precision label converters in Kanto and Kansai regions demand silicone blankets with dimensional stability above 180°C for narrow-web flexo applications. METI industrial standards for printing materials shape domestic procurement specifications. Osaka and Nagoya industrial clusters concentrate high-speed narrow-web operations where press downtime costs exceed blanket price differentials significantly.
Global Printing Blanket Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels. Three specialized compounders dominate premium gravure formulations, while independent service providers in Shanghai and São Paulo bypass traditional distributor markups. Market structure separates captive rubber compounders serving OEM press manufacturers from independent specialists competing on digital compatibility and leasing models. Competitive moves concentrate on backward integration into polymer development and unbundled service contracts that separate blanket supply from maintenance agreements.
Among European-based compounders, Trelleborg AB and Continental AG occupy positions anchoring premium offset and gravure segments respectively. Flint Group exemplifies the digital-narrow-web specialist archetype competing on inkjet blanket compatibility. Japanese fabricators including Fujikura Composites and Kinyosha represent the precision silicone segment serving heat-critical narrow-web applications. These named entities illustrate how geographic concentration of polymer expertise in Germany and Japan shapes competitive positioning across material platforms.
| Leading Market Players |
|---|
| Trelleborg AB |
| Continental AG (ContiTech) |
| Flint Group |
| Fujikura Composites Inc. |
| Kinyosha Co., Ltd. |
| Habasit AG |
| Meiji Rubber and Chemical Co., Ltd. |
| Birkan GmbH |
| Felix Böttcher GmbH and Co. KG |
| Others |
Supply & Pricing Matrix
Petrochemical input volatility determines both pricing tier spreads and supply chain shape across the printing blanket market. Nitrile rubber and synthetic fabric reinforcement costs fluctuate with crude oil indices, compressing margin predictability for compounders while forcing buyers into longer-term contracting or spot-market exposure.
Pricing Analysis
Cost-plus contracts indexed to nitrile rubber and synthetic polymer feedstock prices dominate procurement between compounders and packaging manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates migration-tested hybrid constructions from conventional rubber blankets and natural rubber economy grades. Pricing pressure stems from REACH Annex XVII compliance investments that European compounders must recover through specification premiums. Newspaper publishers exhibit highest price sensitivity due to cost-per-impression procurement metrics, while narrow-web label converters prioritize dimensional stability over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with three specialized German compounders controlling premium gravure blanket formulations. Geographic supply concentration centers on Germany, China, and Japan where polymer development expertise and fabric reinforcement capabilities cluster. Raw material dependencies draw from Malaysian natural rubber plantations, South Korean synthetic polymer production, and German specialty chemical additives. Single-source vulnerability exists in migration-tested compressible layer chemistries where dual certification timelines create 18-24 month qualification bottlenecks. Distribution runs through independent service providers in Shanghai and São Paulo who bypass traditional distributor markups by sourcing directly from compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The printing blanket market sits at a platform-economics inflection where inkjet compatibility requirements are collapsing traditional specification boundaries. Interoperability between digital and conventional press architectures is reshaping competitive positioning across material platforms.
For Market Incumbents: Build certification moats around dual FDA-EFSA migration-tested constructions to defend against Asian compounders with faster qualification timelines. Deepen backward integration into captive rubber compounding to sustain margin control as nitrile feedstock volatility intensifies. Anchor European gravure demand through vertically integrated polymer development that new entrants cannot replicate within 24-month windows.
For New Entrants and Emerging Players: India's underpenetrated corrugated post-print segment represents the most penetrable entry point given 40% natural rubber blanket penetration versus 15% in China. Digital-narrow-web convergence in label applications opens specification windows for elastomeric layers with controlled porosity where incumbent R&D cycles lag converter adoption curves. Pursue asset-light leasing models that separate blanket supply from maintenance agreements to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that targets specialized compounders with REACH-compliant formulation libraries. Long-term viability hinges on acquiring polymer chemist expertise residing with retiring specialists in Akron and Leverkusen. Watch for EPA VOC emission mandate acceleration as the signal indicating low-swell surface treatment chemistry demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Development | Captive rubber compounding sustains margin control against nitrile feedstock volatility. |
| Dual Certification Investment | FDA-EFSA migration-tested constructions command specification premiums in food-contact packaging. |
| Asset-Light Leasing Model Deployment | Performance-based contracts lower entry barriers for silicone blanket technologies in narrow-web segments. |
| Hybrid Construction Scale-Up | UV-conventional compatibility collapses inventory complexity for multi-brand converters. |
| Independent Service Provider Partnership | Direct sourcing from Shanghai and São Paulo bypasses traditional distributor markups. |
Research Methodology
Cross-validation between primary interviews with polymer chemists, procurement directors at packaging manufacturers, gravure house operations managers, and aftermarket service heads anchors the qualitative findings. Secondary validation draws from customs and trade data tracking nitrile rubber imports, SEC 10-K filings of listed compounders, REACH Annex XVII regulatory submissions, and GB standards enforcement records from China's MEE. Bottom-up triangulation across press technology installations and top-down reconciliation against packaging output volumes ensures dimensional consistency.
Calibration against historical replacement cycle data and forward-looking compliance timeline assumptions shapes the analytical framework across the analysis window. Segmentation dimensions modeled include material platform chemistry, press technology architecture, application compliance burden, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating UV ink adoption rates and food-contact rule enforcement intensity. Industry-specific forecast inputs capture narrow-web press speed thresholds exceeding silicone dimensional stability limits and corrugated post-print upgrade penetration differentials between India and China.
Practitioners should monitor REACH Annex XVII expansion scope, EPA VOC emission mandate phase acceleration, and GB standards enforcement intensity for early signals of specification shift. Forecasts reflect documented assumptions regarding polymer chemist retirement timelines and dual certification backlog clearance rates. Quarterly review of nitrile rubber price indices, migration-tested construction qualification queues, and independent service provider market share in Shanghai and São Paulo is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Brazil Commercial Printing Market
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Global Printing Toners Market
Printing Inks
Screen Printing Inks Market
Printing Inks
Global Conductive Inks Market
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Food Grade Inks Market
Printing Inks
Global Dye Sublimation Inks Market
Printing Inks
Printing Inks Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Thermal Inkjet Inks Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
United States Flexographic Printing Market
Printing Inks
United States Printing Inks Market