
 Global High Performance Ceramic Coatings Market | 2026-2036
Global High Performance Ceramic Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Performance Ceramic Coatings Market Foresight
Specification-grade thermal barrier coatings is collapsing into commodity territory at the low end while premium aerospace-qualified formulations command widening margins. Praxair Surface Technologies leverages its captive powder production to control input costs across the value chain. Saint-Gobain anchors European supply through vertically integrated fused mineral operations. Oerlikon Metco differentiates via proprietary plasma spray parameter sets that OEMs lock into repair manuals.
High performance ceramic coatings are engineered thin-film deposits, typically alumina- or zirconia-based, applied through plasma spray or chemical vapor deposition to impart thermal insulation, wear resistance, or corrosion protection at operating temperatures exceeding 1,000°C. Plasma spraying dominates volume throughput for industrial machinery refurbishment, though physical vapor deposition captures the highest margin pool in electronics and medical implants where sub-micron thickness control is mandatory. Alumina formulations lead across cutting tools and pump components, while yttria-stabilized zirconia concentrates in aerospace hot-section applications where thermal cycling resistance dictates component life.
The US EPA and REACH in Europe both restrict hexavalent chromium processes, directly expanding addressable demand for ceramic replacement coatings in automotive and industrial end uses. Japan's METI enforces JIS standards on coating adhesion and porosity that filter market access for imported formulations. Stakeholders must monitor evolving F-Gas Regulation thresholds in Europe, as fluorinated precursor chemistries face phase-down schedules that could disrupt chemical vapor deposition supply chains.
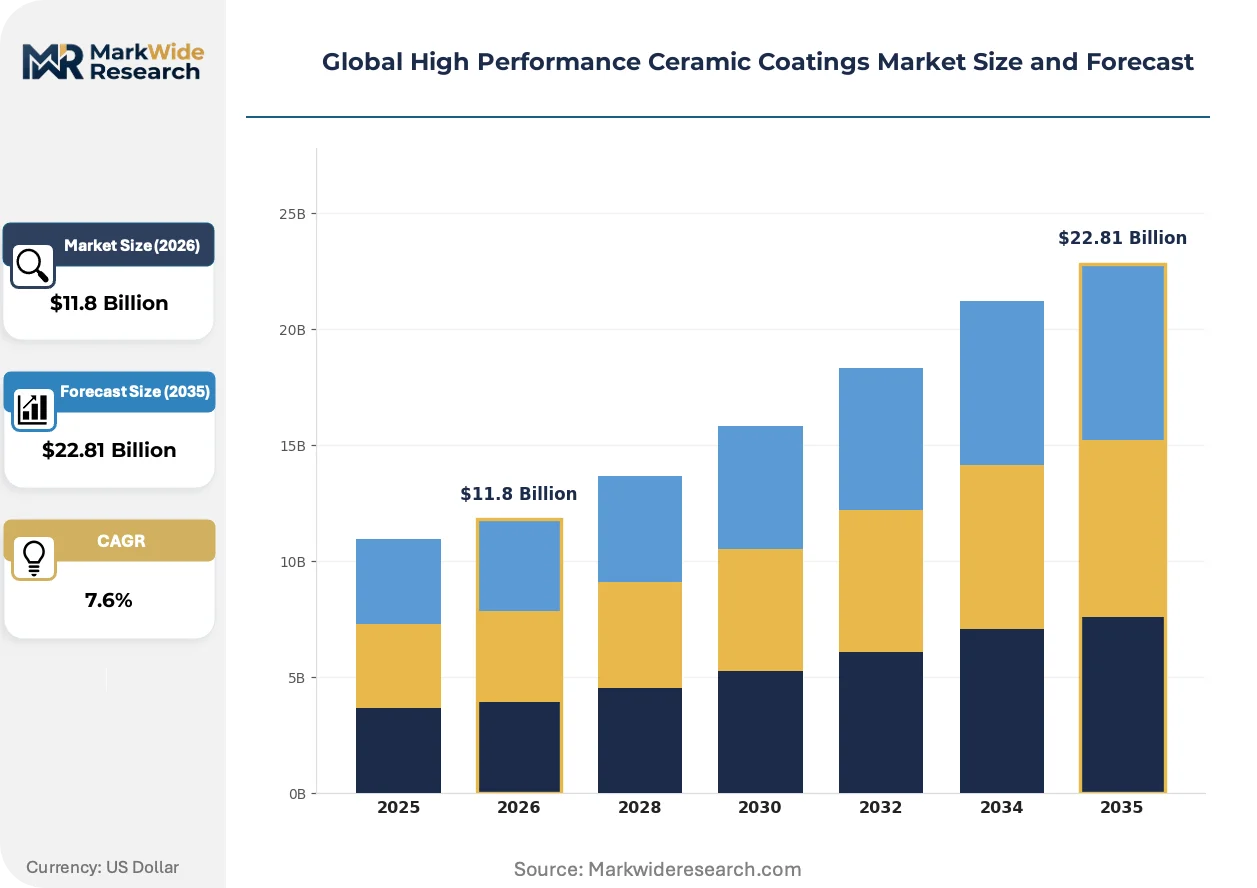
Market Dynamics
Plasma spray and chemical vapor deposition technologies are diverging into distinct value tiers, with aerospace OEMs locking qualified process parameters into repair manuals while industrial buyers commoditize standard thermal barrier formulations.
Growth Catalysts
- EPA hexavalent chromium restrictions:US automotive and industrial machinery manufacturers are substituting chrome plating with alumina-based ceramic coatings to meet emissions compliance deadlines.
- Turbine blade refurbishment cycles:Aerospace engine overhaul shops are expanding thermal barrier coating capacity to service next-generation geared turbofan fleets entering their first major maintenance windows.
- Germany's precision engineering clusters:Stuttgart and Munich industrial corridors are driving specification upgrades for cutting tool coatings that extend machining intervals.
Market Restraints
- Yttria powder supply concentration:Fused zirconia precursor production clusters in Chinese industrial zones, creating single-source vulnerability for yttria-stabilized formulations.
- F-Gas Regulation phase-down schedules:EU restrictions on fluorinated precursors are disrupting chemical vapor deposition supply chains for electronics-grade coatings.
- Plasma spray equipment capex thresholds:Automated spray cells require substantial capital outlay, freezing smaller job shops out of aerospace-qualified work.
Strategic Opportunities
- India's defense aerospace buildup:Hindustan Aeronautics and DRDO laboratories are qualifying domestic thermal barrier coating sources for indigenous combat engine programs.
- Medical implant surface engineering:Sub-micron alumina coatings via physical vapor deposition are penetrating orthopedic and dental implant markets requiring biocompatibility certification.
- Japan METI JIS standard harmonization:Alignment of coating adhesion and porosity test protocols with ISO standards is easing market access for imported formulations.
Industry Challenges
- Plasma spray parameter certification:OEM repair manuals specify proprietary spray trajectories and temperature profiles that lock maintenance providers into single-source relationships.
- Coating-to-substrate interface engineering:Thermal expansion mismatch between zirconia topcoats and nickel superalloy substrates drives delamination failures in high-cycle applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Performance Ceramic Coatings Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $22.81 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Zirconia, Silicon Carbide, Titanium Nitride, Chromium Nitride, Boron Nitride Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Plasma Spraying, Sol-Gel Coating, Thermal Spraying, Electrochemical Deposition Application: Aerospace Components, Cutting Tools, Electronics, Medical Implants, Automotive Components, Industrial Machinery End User: OEMs, Tool Manufacturers, Medical Device Firms, Electronics Producers, Aircraft Manufacturers, Heavy Equipment Makers |
| Companies Covered | Praxair Surface Technologies, Aremco Products, Saint-Gobain, Cetek Ceramic Technologies, APS Materials, DuPont de Nemours, Oerlikon Metco, Ceramic Polymer, Bodycote, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Performance Ceramic Coatings Market Shifts & Advancements
Process automation and digital twin modeling are compressing development cycles for qualified coating formulations, while regulatory phase-outs of hazardous processes accelerate materials substitution across automotive and industrial end uses.
Environmental barrier coatings for ceramic matrix composites are bifurcating the thermal protection market. GE Aviation and Rolls-Royce are qualifying silicon-based chemistries for next-generation turbine hot sections. This technology is compressing addressable demand for traditional yttria-stabilized zirconia in the highest-temperature applications.
REACH authorization requirements for chromium trioxide are forcing automotive tier suppliers to convert decorative and functional plating lines to ceramic alternatives. German and French stamping and forming tool manufacturers report 18-month qualification timelines for new coating vendors. The conversion is most advanced in powertrain component production where hexavalent chrome exposure risks are highest.
Aerospace engine lessors are unbundling coating refurbishment from core engine overhauls, creating standalone coating procurement events. MTU Maintenance and Lufthansa Technik now specify coating thickness and porosity bands separately from OEM repair schemes. This pattern is most visible in narrowbody engine aftermarket channels serving low-cost carriers in Southeast Asia and Eastern Europe.
Global High Performance Ceramic Coatings Market Segmentation
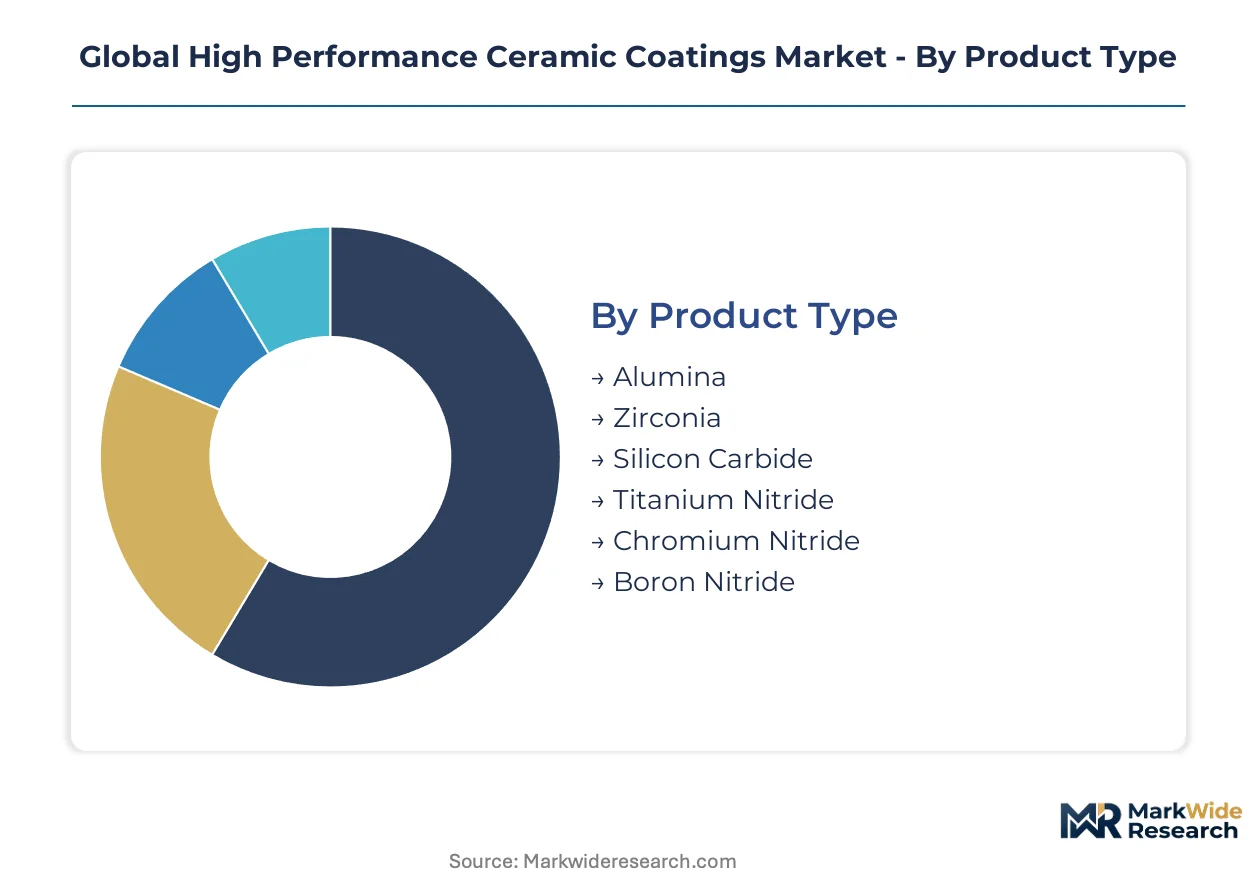
Segmentation in ceramic coatings reveals how technology qualification tiers, substrate compatibility requirements, and end-use certification standards fragment procurement patterns across industrial, aerospace, and medical channels. Understanding these divisions exposes where formulation premiums concentrate versus where coating specifications commoditize.
Product Type:
Alumina and zirconia formulations dominate export flows from German and Japanese production clusters, while silicon carbide and nitride chemistries serve more geographically concentrated domestic defense and semiconductor supply chains.
- Alumina:Alpha-phase aluminum oxide coatings deliver hardness values exceeding 9 Mohs with thermal stability to 1,800°C. German cutting tool manufacturers in Stuttgart industrial corridors specify alumina for high-speed machining of hardened steels, with REACH-driven chrome substitution accelerating specification upgrades in automotive powertrain production.
- Zirconia:Yttria-stabilized tetragonal zirconia polycrystal formulations provide thermal barrier protection with thermal expansion coefficients matched to nickel superalloy substrates. Aerospace engine overhaul shops in the US and UK concentrate procurement for turbine blade refurbishment, though Chinese yttria powder concentration creates supply vulnerability.
- Silicon Carbide:Covalent ceramic with exceptional thermal conductivity serves semiconductor wafer processing equipment and military armor applications, with demand clustering in domestic US and Israeli defense supply chains.
- Titanium Nitride:Gold-colored PVD coating dominates cutting tool decorative and functional finishing, with Swiss and Italian tool manufacturers driving specification standards.
- Chromium Nitride:Harder than titanium nitride with superior corrosion resistance, finding traction in marine and oilfield component protection where hexavalent chrome restrictions apply.
- Boron Nitride:Hexagonal phase provides solid lubrication and electrical insulation for high-temperature furnace fixtures and semiconductor crucibles, with Japanese electronics producers anchoring demand.
Zirconia holds the largest share; momentum sits with alumina as chrome substitution accelerates across European and North American industrial channels.
Technology:
Deposition technology selection maps directly to thickness precision requirements and capital intensity, with aerospace-qualified plasma spray systems commanding three-year payback periods while sol-gel methods enable lower-threshold market entry.
- Physical Vapor Deposition:Arc evaporation and sputtering techniques deposit sub-micron coatings with atomic-level thickness control. Electronics producers in South Korea and Taiwan specify PVD for semiconductor interconnect barrier layers, where JIS and ISO adhesion standards filter vendor qualification.
- Chemical Vapor Deposition:Precursor gas-phase reactions enable conformal coating of complex geometries with exceptional purity. EU F-Gas Regulation phase-down schedules on fluorinated precursors are disrupting electronics-grade CVD supply chains, forcing reformulation investments.
- Plasma Spraying:High-velocity oxy-fuel and atmospheric plasma spray dominate industrial machinery refurbishment volume, with automated spray cells requiring substantial capital outlay that freezes smaller job shops from aerospace-qualified work.
- Sol-Gel Coating:Liquid-phase deposition enables thin ceramic films at ambient pressure with minimal equipment investment, penetrating architectural glass and consumer electronics display protection.
- Thermal Spraying:Combustion and electric arc variants serve heavy equipment restoration where coating thickness tolerance is less critical, with Russian and Indian mining equipment operators driving demand.
- Electrochemical Deposition:Aqueous electrolyte methods produce ceramic oxide layers on valve metals, with medical implant producers leveraging the technique for biocompatible surface modification.
Plasma spraying holds the largest share; physical vapor deposition is expanding most quickly in electronics and medical precision applications.
Application:
Application segmentation tracks directly to thermal cycling severity and regulatory exposure, with aerospace and medical channels requiring multi-year qualification timelines while industrial machinery permits faster vendor switching.
- Aerospace Components:Thermal barrier coatings on turbine blades, combustor liners, and exhaust nozzles must survive 1,000+ thermal cycles between ambient and 1,200°C. US FAA and EASA airworthiness directives lock qualified process parameters into OEM repair manuals, creating single-source maintenance relationships.
- Cutting Tools:Hard coatings extend tool life in metal removal operations, with German and Japanese machine tool builders specifying coating adhesion and thickness bands in procurement contracts.
- Electronics:Dielectric and barrier layers in semiconductors, capacitors, and display substrates require sub-micron thickness uniformity, with South Korean memory chip producers driving specification intensity.
- Medical Implants:Alumina and hydroxyapatite coatings on orthopedic and dental implants require biocompatibility certification to FDA and EMA standards, with Swiss and US device firms controlling vendor qualification.
- Automotive Components:Piston rings, valves, and fuel injection components substitute ceramic coatings for chrome plating under EPA and REACH restrictions, with German powertrain manufacturers leading conversion timelines.
- Industrial Machinery:Pump seals, valve seats, and bearing surfaces in chemical processing and oilfield equipment represent the highest volume, lowest margin coating applications with shortest procurement cycles.
Aerospace components hold the largest share; medical implants are gaining share fastest as aging demographics expand joint replacement volumes.
End User:
End user segmentation reveals divergent procurement authority patterns, with aircraft manufacturers and medical device firms controlling specification writing while tool manufacturers and heavy equipment makers accept coating vendor recommendations.
- OEMs:Original equipment manufacturers in aerospace, automotive, and industrial equipment specify coating chemistries and application methods in design documentation, with German automotive OEMs mandating chrome-free alternatives.
- Tool Manufacturers:Cutting tool producers in Switzerland, Germany, and Japan source coated inserts and apply proprietary finishing layers, with coating performance directly determining product tier positioning.
- Medical Device Firms:Orthopedic and dental implant manufacturers qualify coating vendors through multi-year biocompatibility studies, with FDA 510(k) and EMA CE marking requirements creating substantial switching costs.
- Electronics Producers:Semiconductor and display manufacturers specify barrier and dielectric coatings in nanometer tolerances, with South Korean and Taiwanese foundries driving technology roadmaps.
- Aircraft Manufacturers:Boeing, Airbus, and COMAC specify thermal protection systems for engine and airframe applications, with repair manual control passing to engine OEMs and MRO providers post-delivery.
- Heavy Equipment Makers:Construction, mining, and agricultural equipment manufacturers specify wear coatings for hydraulic components and undercarriage parts, with Russian and Brazilian producers most price-sensitive.
OEMs hold the largest share; medical device firms are climbing the fastest as implant surface engineering requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Russia and Brazil prioritize coating thickness tolerance over certification pedigree, while German and Japanese purchasers absorb 40-60% premiums for aerospace-qualified process documentation. This elasticity gap shapes regional vendor strategies and qualification timelines.
United States
EPA hexavalent chromium restrictions are forcing automotive powertrain manufacturers in Michigan and Ohio to convert plating lines to alumina-based ceramic alternatives. FAA airworthiness directives lock qualified thermal barrier coating parameters into OEM repair manuals, creating single-source maintenance relationships for turbine blade refurbishment. Dallas-Fort Worth and Atlanta aerospace clusters concentrate engine overhaul capacity serving narrowbody fleets.
Germany
REACH authorization requirements for chromium trioxide are accelerating specification upgrades across Stuttgart and Munich industrial corridors. KBA enforcement of chrome-free alternatives in powertrain production has compressed qualification timelines to 18 months for new coating vendors. Precision engineering clusters in Baden-Württemberg drive cutting tool coating adhesion standards that filter supplier access.
China
Domestic yttria powder production clusters in Hunan and Jiangsu provinces create single-source vulnerability for stabilized zirconia formulations. MIIT standards on coating porosity and adhesion are tightening market access for imported plasma spray systems. Shenyang and Xi'an aerospace hubs are qualifying local thermal barrier coating sources for indigenous combat engine programs.
Japan
METI-enforced JIS standards on coating adhesion and porosity filter vendor qualification for electronics-grade barrier layers. Nagoya and Osaka industrial zones concentrate semiconductor equipment coating demand where sub-micron thickness control commands premium positioning. Harmonization of JIS protocols with ISO standards is easing import access for qualified formulations.
India
Hindustan Aeronautics and DRDO laboratories are qualifying domestic thermal barrier coating capacity for indigenous fighter engine development. BIS standards on ceramic coating adhesion are converging with aerospace OEM requirements. Bengaluru and Hyderabad defense aerospace clusters are absorbing technology transfer partnerships for plasma spray parameter certification.
Global High Performance Ceramic Coatings Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with aerospace-qualified plasma spray specialists commanding three-year payback periods while industrial refurbishment operators compete on throughput volume. The market structures around three tiers: vertically integrated powder producers, captive coating divisions of aerospace OEMs, and independent job shops serving industrial machinery channels. Dominant competitive moves include backward integration into precursor production and parameter certification lock-ins via OEM repair manual specifications.
Among European-based material science conglomerates, Saint-Gobain and Oerlikon Metco exemplify the vertically integrated archetype, while Praxair Surface Technologies represents the industrial gas-to-coating pipeline model. Aremco Products and APS Materials occupy positions within the specialty formulation tier serving qualified aerospace and defense applications.
| Leading Market Players |
|---|
| Praxair Surface Technologies |
| Aremco Products |
| Saint-Gobain |
| Cetek Ceramic Technologies |
| APS Materials |
| DuPont de Nemours |
| Oerlikon Metco |
| Ceramic Polymer |
| Bodycote |
| Others |
Supply & Pricing Matrix
Chrome-to-ceramic substitution in automotive powertrain production simultaneously redistributes supply geography toward German and Japanese powder producers and compresses pricing premiums for commodity-grade alumina formulations. Buyers in Stuttgart and Munich industrial corridors absorb substantial certification premiums while Russian and Brazilian heavy equipment makers prioritize coating thickness tolerance over documentation pedigree.
Pricing Analysis
Coating refurbishment contracts now drive lifetime value as aerospace engine lessors unbundle thermal barrier work from core overhauls. Three-tier pricing structure across aerospace-qualified, industrial-standard, and job-shop economy levels separates procurement channels. Cost compression in industrial refurbishment tiers is intensifying because automated plasma spray cells freeze smaller operators from qualified work. German automotive OEMs show least price sensitivity for REACH-compliant chrome alternatives, while Russian mining equipment operators demand lowest unit costs.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for yttria-stabilized zirconia precursors. Supply concentrates in Chinese Hunan and Jiangsu provinces for fused zirconia production, with German and Japanese clusters anchoring alumina powder output. The coating value chain draws from yttria powder, plasma spray equipment, and fluorinated CVD precursors. Single-source vulnerability in Chinese yttria production creates structural supply risk. Distribution runs through aerospace OEM repair manuals, industrial machinery job shops, and medical device contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a cyclical recovery phase driven by turbine blade refurbishment cycles entering their first major maintenance windows for next-generation geared turbofan fleets.
For Market Incumbents: Compound certification lock-ins by embedding proprietary plasma spray parameters into OEM repair manuals before environmental barrier coatings displace traditional yttria-stabilized zirconia in highest-temperature applications. Deepen upstream control over yttria powder supply through partnerships with Chinese fused zirconia producers to mitigate single-source concentration risk. For New Entrants and Emerging Players: Anchor in India's defense aerospace buildup where Hindustan Aeronautics and DRDO laboratories are qualifying domestic thermal barrier coating sources with compressed vendor timelines compared to Western aerospace channels. Target medical implant surface engineering for orthopedic and dental applications requiring biocompatibility certification, leveraging sub-micron PVD capabilities as the go-to-market wedge. For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors vertically integrated powder-to-coating specialists with captive precursor production. Long-term viability over the next decade hinges on positioning ahead of F-Gas Regulation phase-down schedules disrupting CVD supply chains. Watch silicon-based environmental barrier coating qualification timelines at GE Aviation and Rolls-Royce as the signal for technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yttria Powder Production | Mitigates Chinese supply concentration risk for stabilized zirconia formulations. |
| Aerospace Repair Manual Parameter Certification | Locks maintenance providers into single-source coating relationships with OEMs. |
| Environmental Barrier Coating Qualification | Positions suppliers for next-generation turbine hot-section silicon-based chemistries. |
| Medical Implant Biocompatibility Certification | Opens orthopedic and dental markets requiring FDA and EMA compliance. |
| REACH-Compliant Chrome Substitution Line Conversion | Captures automotive powertrain demand as German OEMs mandate alternatives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from coating equipment manufacturers, EPA regulatory dockets, and aerospace OEM procurement disclosures. Interviews with thermal spray job shop operators, procurement leads at German automotive Tier 1 suppliers, plasma spray equipment engineers, and medical device coating qualification specialists informed demand-side assumptions. Bottom-up coating volume estimates triangulated against top-down market value assessments.
Segmentation dimensions modeled include coating chemistry type, deposition technology, end-use application, and geographic production hub across the projection horizon. CAGRs derived from fitted growth curves incorporating yttria powder supply constraints, REACH enforcement timelines, and turbine engine fleet age profiles. Forecast inputs include aerospace MRO capacity expansion plans and F-Gas Regulation phase-down schedules affecting CVD precursor availability.
Decision-makers should treat outputs as directional under assumptions of continued EPA and REACH chrome restriction enforcement and stable yttria powder trade flows; material deviation would warrant model refresh. Specific risks include faster-than-anticipated environmental barrier coating adoption compressing zirconia demand, or Chinese export restrictions on fused zirconia precursors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramic Proppant Market
Ceramics
Potassium Feldspar Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Glazed Bricks Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
China Ceramic Market
Ceramics
Ceramic Solid End Mills Market
Ceramics
Calcium Oxide Market
Ceramics
Activated Alumina Market
Ceramics
Polymer-Derived Ceramics Market
Ceramics
South Korea Ceramic Sanitaryware Market
Ceramics
Alumina Slurry Market
Ceramics
High Temperature Ceramics Market
Ceramics
Global Ceramic Tube Market
Ceramics
Ceramic Binders Market
Ceramics
Ceramic Frit Glass Market