
 Ceramic Proppant Market | 2026-2036
Ceramic Proppant Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Proppant Market Analysis
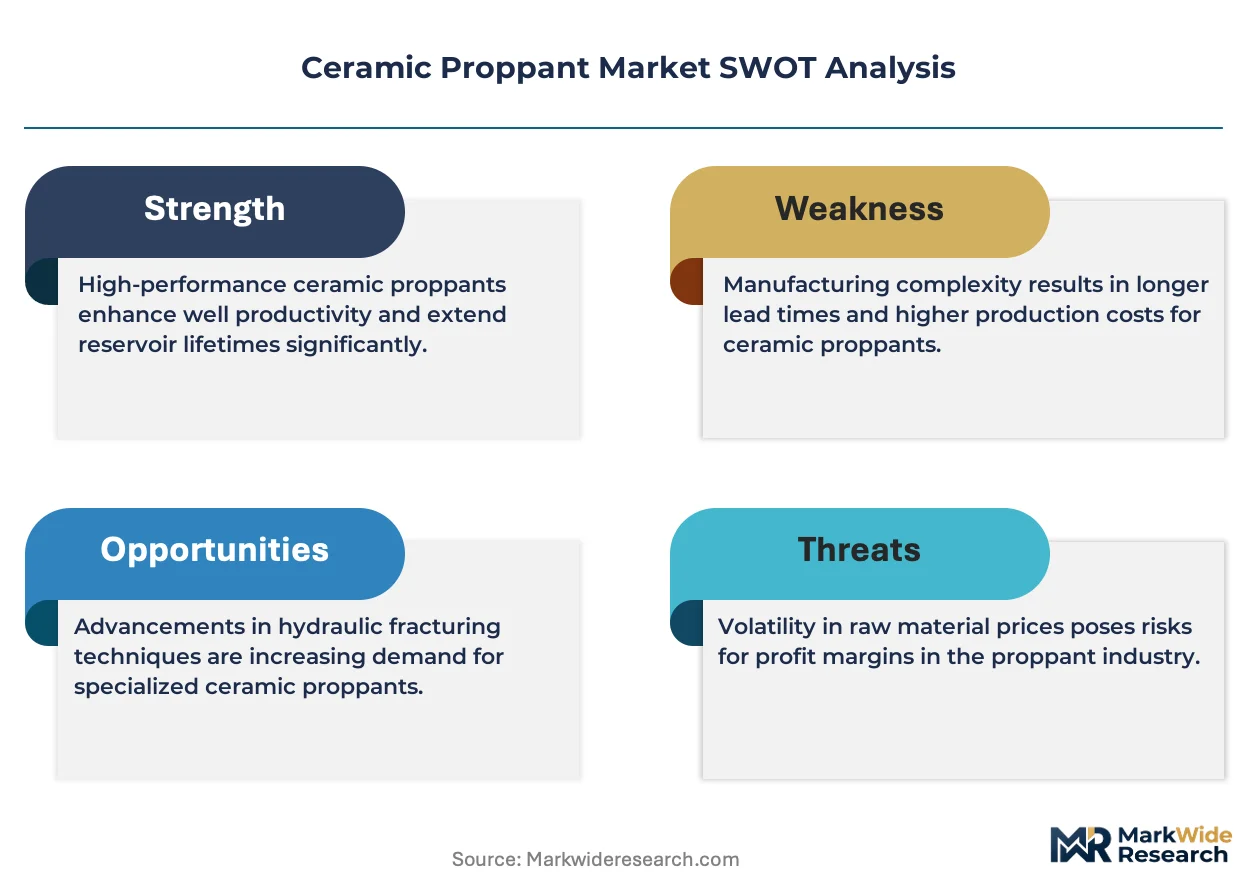
Resin-coated sand is recalibrating baseline economics for ceramic proppant suppliers as operators weigh crush resistance against cost per pound in moderate-depth wells. CARBO Ceramics dominates high-strength product manufacturing through captive bauxite processing and kiln control. Covia Holdings leverages integrated logistics networks to anchor supply contracts across Appalachian and Permian basins. Saint-Gobain competes on material science R&D, extending its alumina-zirconia formulations into specialty proppant grades for geothermal and deep-gas applications.
Ceramic proppants are sintered spherical grains manufactured from bauxite, kaolin, or alumina blends, engineered to withstand closure stresses exceeding 10,000 psi while maintaining fracture conductivity in hydraulically stimulated reservoirs. Their primary purpose is to prop open induced fractures after pressure release, enabling hydrocarbon flow paths from formation to wellbore. High-strength proppants command premium positioning in deep vertical and horizontal wells where closure stress degrades intermediate alternatives. Fracking services represent the fastest-growing application channel as integrated service providers bundle proppant delivery with pumping equipment. Oil and gas operators remain the dominant end-user category, though mining companies are testing ceramic proppants for in-situ leaching of hard-rock minerals.
EPA methane regulations and state-level NDEP requirements in New Mexico are tightening completion standards, forcing proppant selection toward higher-conductivity grades that reduce re-fracturing frequency and associated venting. OSHA silica exposure limits shape workplace handling protocols, adding cost to resin-coated alternatives but reinforcing demand for dust-suppressed ceramic formulations. Stakeholders must monitor how EPA's evolving New Source Performance Standards for oil and gas affect proppant specification in federal lease auctions, as compliance timelines could shift procurement volumes toward premium product tiers without warning.
Market Dynamics
Closure-stress tolerance requirements in deep shale formations are forcing operators to recalibrate proppant selection criteria, compressing demand for intermediate-strength alternatives while concentrating procurement around high-grade bauxite formulations.
Growth Catalysts
- EPA methane emissions rules:Federal venting restrictions are compelling operators to specify higher-conductivity proppants that extend well EUR and eliminate re-fracturing cycles.
- Permian basin drilling intensity:Texas and Louisiana operators are expanding horizontal laterals beyond 15,000 feet, requiring crush-resistant ceramic grains for sustained fracture conductivity.
- Resin-coating technology maturation:Dust-suppressed ceramic formulations are penetrating moderate-depth applications previously served by raw sand, expanding addressable well inventory.
Market Restraints
- Bauxite supply concentration:High-grade feedstock sourcing concentrates in Guinea, Australia, and Brazil, exposing kilns to maritime freight volatility and export licensing delays.
- Resin-coated sand substitution:Intermediate-depth wells in the Appalachian basin are defaulting to polymer-coated silica where closure stress stays below 8,000 psi, capping ceramic volume potential.
- OSHA silica exposure limits:Workplace respirable crystalline silica standards add handling infrastructure costs that compress margins on standard-grade ceramic shipments.
Strategic Opportunities
- Geothermal energy expansion:Enhanced geothermal systems in Nevada and Utah require thermally stable proppants for artificial fracture networks in hot dry rock formations.
- In-situ mining applications:Copper and uranium extraction operators are testing ceramic proppants to maintain permeability during acid leaching of deep ore bodies.
- EU Green Deal methane targets:European unconventional gas developers face imported LNG displacement pressure, creating demand for high-performance proppants that maximize recovery per well.
Industry Challenges
- Kiln operator skill scarcity:Sintering temperature control for ultra-high-strength grades requires ceramic engineering expertise concentrated among legacy refractory manufacturers.
- Proppant flowback certification:API RP 19C testing protocols for long-term conductivity under cyclic stress are extending qualification timelines for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Proppant Market |
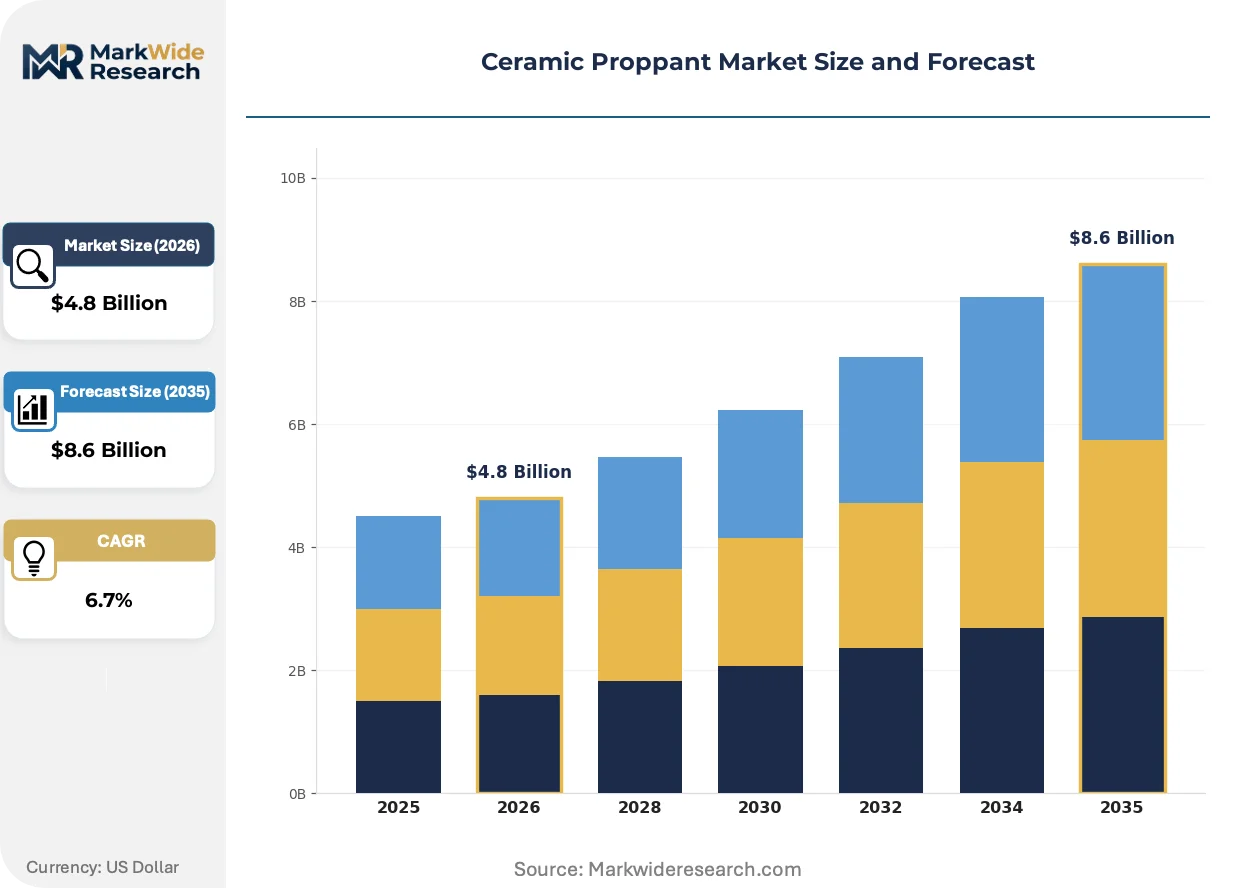
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Strength Proppants, Intermediate Proppants, Low-Strength Proppants, Specialty Proppants Application: Oil Extraction, Natural Gas Extraction, Shale Gas Operations, Fracking Services End User: Oil & Gas Operators, Mining Companies, Service Providers, Industrial Applications Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Outlets |
| Companies Covered | Covia Holdings LLC, Hexion Inc., CARBO Ceramics Inc., ChangQing Proppant Corporation, Borovichi Refractories Plant, Saint-Gobain, Badger Mining Corporation, Xinmi Wanli Industry Development Co. Ltd., U.S. Silica Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Proppant Market Emerging Trajectories
Material science advances and regulatory stringency are converging to redefine performance benchmarks across the proppant value chain, with durability and emissions compliance now co-equal selection criteria.
Ultra-lightweight ceramic microspheres engineered from kaolin-alumina blends are rewriting fracture design economics in moderate-depth horizontal wells. Bakken and Eagle Ford operators are specifying these grains at expanding rates, enabling wider propped fracture apertures without compromising crush resistance. The technology is compressing the historical trade-off between conductivity and specific gravity that constrained slurry transport efficiency.
REACH restrictions on crystalline silica classification are compelling European proppant handlers to implement dust-suppression systems or transition to pre-coated ceramic alternatives. The industrial consequence is a bifurcation in supply contracts, with North Sea gas developers now mandating certified low-dust formulations for offshore platform logistics. German and Norwegian drilling contractors are responding by consolidating procurement around suppliers with integrated coating capabilities.
Integrated service providers are unbundling proppant logistics from pumping services, creating direct procurement relationships between operators and manufacturers. This channel restructuring displaces traditional bulk-distributor intermediaries in the Permian and Haynesville basins. The shift is most visible among supermajor operators in Texas, where volume commitments now anchor multi-year supply agreements with kiln operators rather than pressure-pumping companies.
Ceramic Proppant Market Segmentation
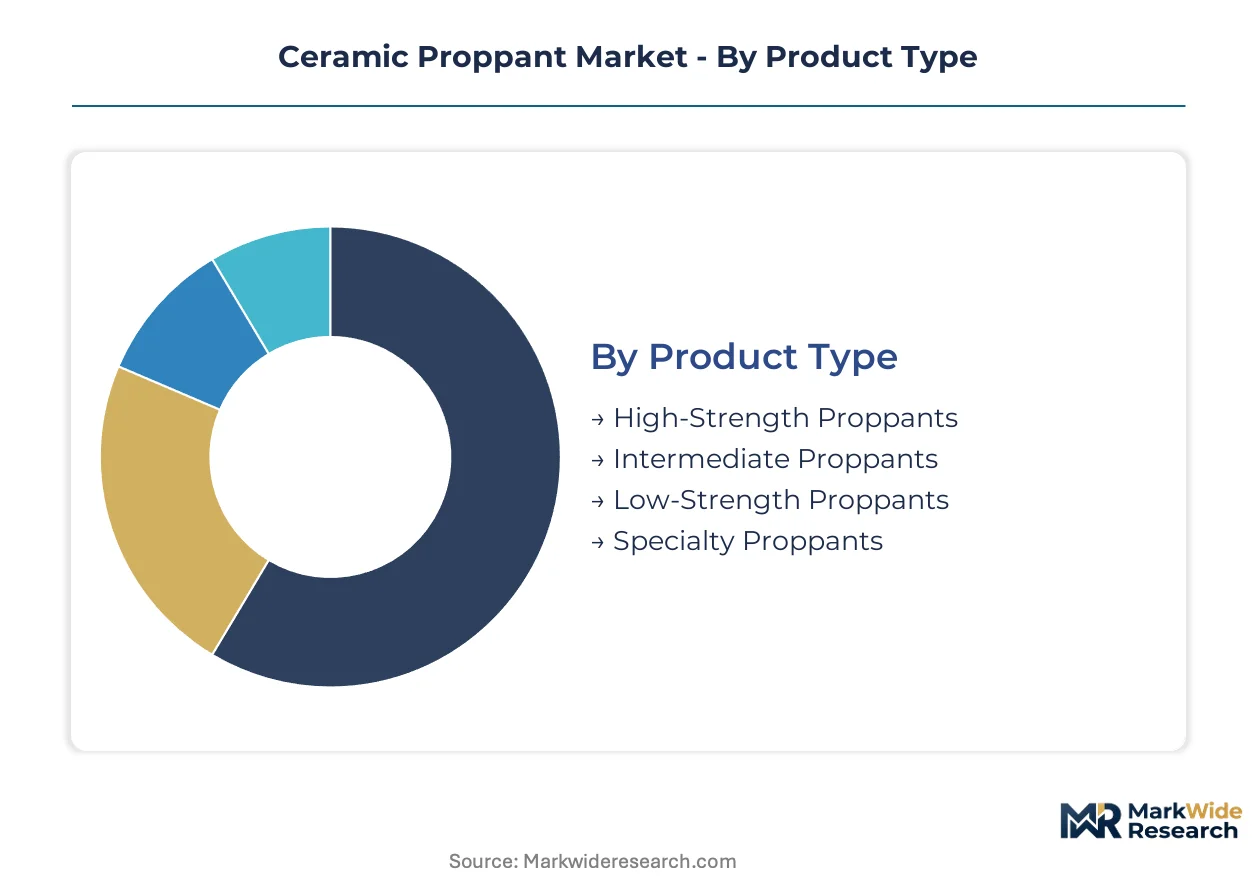
Ceramic proppant procurement patterns diverge sharply between integrated operators specifying directly and service-dependent buyers accepting bundled supply. Segment boundaries are blurring as resin-coating technology and logistics unbundling reshape traditional category definitions.
Product Type:
Integration depth varies: high-strength grades demand standalone specification expertise, while intermediate and low-strength categories increasingly embed within service-provider bundles.
- High-Strength Proppants:Sintered bauxite-alumina spheres engineered for closure stresses exceeding 10,000 psi. Permian basin operators in Texas and Louisiana specify these for horizontal laterals beyond 15,000 feet where fracture conductivity degradation risks well economics.
- Intermediate Proppants:Kaolin-based formulations balancing crush resistance against slurry transport efficiency. Appalachian shale developers in West Virginia and Pennsylvania default to these for moderate-depth wells where closure stress stays below 8,000 psi and resin-coated sand competition intensifies.
- Low-Strength Proppants:Lightweight ceramic microspheres from calcined kaolin blends for shallow conventional reservoirs.
- Specialty Proppants:Alumina-zirconia and thermally stable formulations targeting geothermal and deep-gas applications in Nevada and Utah.
High-Strength Proppants lead volumes today; Specialty Proppants is gaining share fastest.
Application:
Cost tier stratification separates capital-intensive extraction operations from margin-compressed pumping services, with channel economics dictating grade selection.
- Oil Extraction:Tight-oil operators in the Bakken and Eagle Ford specify ultra-lightweight ceramics to maximize propped fracture aperture without compromising pump rates.
- Natural Gas Extraction:Deep Haynesville verticals in Louisiana require premium bauxite-based grains to withstand cyclic stress from extended drawdown periods.
- Shale Gas Operations:Marcellus and Utica developers in Ohio balance conductivity against logistics cost through intermediate-grade procurement.
- Fracking Services:Integrated pressure pumpers bundle ceramic delivery with equipment spreads, compressing operator visibility into grade specification.
Fracking Services channels the most volume; Shale Gas Operations shows the steepest expansion trajectory as lateral lengths extend.
End User:
Customer type determines specification control—supermajors dictate directly while mining and industrial buyers remain price-takers with limited technical input.
- Oil & Gas Operators:Supermajors and independents in Texas anchor multi-year supply agreements with kiln operators, bypassing traditional distributor intermediaries.
- Mining Companies:Copper and uranium extraction operators in Arizona and New Mexico test ceramic proppants for in-situ leaching permeability maintenance.
- Service Providers:Pressure-pumping companies bundle proppant with pumping spreads, though unbundling trends in the Permian erode this channel.
- Industrial Applications:Geothermal developers and filtration media buyers represent fragmented, specification-light demand.
Oil & Gas Operators dominate procurement today; Mining Companies are climbing the fastest as hard-rock leaching trials expand.
Distribution Channel:
Supply concentration shapes channel power—kiln proximity to basin activity determines whether direct or intermediated logistics prevails.
- Direct Sales:Kiln operators in Texas and Louisiana contract directly with Permian and Haynesville supermajors, displacing bulk-distributor relationships.
- Distributors:Regional proppant handlers in Oklahoma and Colorado maintain relevance for smaller independents lacking volume scale.
- Online Sales:Digital procurement platforms penetrate spot-market transactions for non-critical well completions.
- Retail Outlets:Limited to small-scale mining and industrial buyers with intermittent, low-volume requirements.
Direct Sales leads transaction value today; Online Sales is expanding most quickly as operator procurement systems digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin in Texas anchors ceramic proppant procurement volumes as operators extend horizontal laterals beyond 15,000 feet. Deep-well completion intensity across shale basins is recalibrating regional demand patterns. Regulatory pressure on methane emissions is concentrating procurement in jurisdictions with stringent venting rules.
United States
Permian and Haynesville operators specify high-strength bauxite-based proppants for closure stresses exceeding 10,000 psi. EPA methane emissions rules and state-level NDEP requirements in New Mexico tighten completion standards, pushing specification toward higher-conductivity grades. Houston and Midland-Odessa anchor bulk procurement relationships as supermajors bypass traditional distributor intermediaries.
China
Domestic shale gas development in Sichuan and Chongqing drives intermediate-grade ceramic consumption for moderate-depth horizontal wells. MIIT industrial standards and GB quality certifications shape product qualification timelines for domestic kiln operators. Zhengzhou and Xinmi in Henan Province concentrate refractory-grade bauxite processing capacity for both domestic supply and export markets.
Russia
Bazhenov shale and Volga-Ural basin operators test ceramic proppants for deep vertical completions in high-closure-stress environments. Federal subsoil use regulations and Ministry of Energy licensing frameworks govern unconventional extraction permitting. Borovichi in Novgorod Oblast hosts legacy refractory manufacturing clusters with kiln infrastructure adaptable to proppant production.
Saudi Arabia
Gas drilling in the Empty Quarter and offshore sour gas fields creates demand for crush-resistant proppants in high-temperature reservoirs. Saudi Aramco's In-Kingdom Total Value Add program and national industrial localization mandates shape procurement localization requirements. Jubail Industrial City concentrates ceramics manufacturing investments as part of downstream diversification strategy.
Germany
North Sea gas redevelopment and geothermal exploration in the Upper Rhine Graben require thermally stable proppant formulations. REACH restrictions on crystalline silica classification and EU Green Deal methane targets drive specification toward dust-suppressed ceramic alternatives. Cologne and the Ruhr industrial corridor anchor logistics networks for continental European supply distribution.
Ceramic Proppant Market Vendor Landscape
Global majors compete with regional champions across kiln capacity and bauxite sourcing control. The vendor base stratifies between integrated refractory manufacturers with captive mineral processing and specialized proppant fabricators dependent on merchant feedstock. Three archetypes dominate: bauxite-integrated kiln operators, logistics-anchored distributors, and material science specialists extending alumina formulations into premium grades. Competitive moves center on backward integration into bauxite mining concessions and multi-year supply agreements that displace spot-market procurement.
Among North American-integrated players, Covia Holdings LLC and CARBO Ceramics Inc. exemplify contrasting scale positions, with the former leveraging distribution networks and the latter representing kiln-control specialization. Saint-Gobain occupies a position bridging European material science R&D with industrial ceramics manufacturing. These three anchors demonstrate how geographic origin and corporate structure shape competitive archetype alignment without dictating specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Covia Holdings LLC |
| Hexion Inc. |
| CARBO Ceramics Inc. |
| ChangQing Proppant Corporation |
| Borovichi Refractories Plant |
| Saint-Gobain |
| Badger Mining Corporation |
| Xinmi Wanli Industry Development Co. Ltd. |
| U.S. Silica Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Captive bauxite sourcing anchors both supply security and pricing power for integrated kiln operators, creating tiered margin structures that separate bauxite-integrated manufacturers from merchant-feedstock competitors dependent on spot-market alumina purchases.
Pricing Analysis
Input-cost pass-through from bauxite freight and energy tariffs shapes contract pricing across all grades. Three-tier pricing structure across premium, standard, and economy levels separates high-strength bauxite-alumina formulations from intermediate kaolin blends and lightweight microspheres. Cost compression in intermediate grades is intensifying because resin-coated sand substitutes erode volume leverage. Small independents in Oklahoma and Colorado exhibit highest price sensitivity, while Permian supermajors anchoring multi-year offtake agreements accept premium positioning for supply security.
Supply Chain Analysis
Single-source vulnerability sits with Guinean and Australian bauxite export licensing, where maritime freight volatility and bulk cargo congestion at Port Kamsar expose kiln operators to feedstock interruption. High-grade refractory bauxite concentrates in Guinea, Australia, and Brazil; calcined kaolin feeds from domestic Georgia deposits. Supply chain risk centers on export licensing delays from concentrated mining concessions. Distribution runs through direct rail-to-basin logistics from Texas and Louisiana kiln clusters, displacing traditional bulk-distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through premium-grade specification shifts as deep-well closure-stress requirements compress intermediate-grade viability.
For Market Incumbents: Anticipate resin-coated sand substitution in Appalachian moderate-depth wells by accelerating dust-suppressed ceramic formulation R&D and securing captive bauxite mining concessions in Guinea or Australia. Backward integration into refractory-grade bauxite processing defends margin position against merchant-feedstock competitors exposed to alumina spot volatility. For New Entrants and Emerging Players: Digital procurement platforms for spot-market transactions in non-critical well completions offer the most penetrable entry route, targeting small Oklahoma and Colorado independents lacking volume scale for direct kiln contracts. White-space opportunities concentrate in geothermal proppant grades for Nevada and Utah enhanced geothermal systems, plus in-situ leaching applications for Arizona copper extraction. For Investors and Strategic Acquirers: Roll-up economics work for bauxite-integrated mid-cap kiln operators because supply concentration and API RP 19C certification barriers limit new entrant capacity additions. Long-term viability hinges on exposure to Permian and Haynesville drilling intensity rather than Appalachian gas-directed rigs. Watch EPA methane rule enforcement timelines as the inflection signal for premium-grade procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Mining | Captive Guinean or Australian concessions insulate kiln operators from maritime freight volatility and export licensing delays. |
| Resin-Coating Technology Investment | Dust-suppressed ceramic formulations penetrate moderate-depth applications previously served by raw sand in the Appalachian basin. |
| Direct Sales Channel Expansion | Permian supermajors now contract directly with Texas and Louisiana kiln operators, displacing bulk-distributor intermediaries. |
| Geothermal Grade Development | Thermally stable alumina-zirconia formulations address Nevada and Utah enhanced geothermal system requirements. |
| API RP 19C Certification Acceleration | Long-term conductivity testing protocols extend qualification timelines, creating defensive moats for certified incumbents. |
Methodological Framework
Multiple input streams — completion engineer interviews, kiln operator production data, and customs bauxite trade records — were reconciled through bottom-up and top-down triangulation. Primary discussions with hydraulic fracturing operators, pressure-pumping procurement leads, ceramic engineering directors, and railroad logistics coordinators informed volume assumptions. Secondary validation drew from EPA enforcement disclosures, EIA drilling activity data, FERC infrastructure filings, and API specification documentation.
Data-stream reconciliation across product type, application channel, end-user category, and regional basin activity shaped the analytical framework over the projection horizon. CAGRs were derived from production capacity buildout schedules married to well-completion intensity forecasts. Closure-stress tolerance requirements and EPA methane rule compliance timelines served as industry-specific demand drivers in the quantitative model.
The model assumes a particular technology adoption path; alternative pathways for ultra-lightweight kaolin-alumina microspheres would alter the outlook if Bakken and Eagle Ford operators accelerate specification shifts faster than projected. Forecasts reflect assumptions regarding Permian lateral extension rates and bauxite export licensing continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Automotive Ceramics Market
Ceramics
Global Ceramic and Porcelain Tiles Market
Ceramics
Ceramics Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
Ceramics Packaging Market
Ceramics
North America Activated Alumina Market
Ceramics
Diatomite Market
Ceramics
Earthenware Market
Ceramics
Pottery Ceramics Market
Ceramics
Global Metal and Ceramic Injection Molding Market
Ceramics
Cerium Carbonate Market
Ceramics
Global Industrial Clay Market
Ceramics
Ceramic Substrate Market
Ceramics
China Ceramic Market
Ceramics
Controlled Pore Metal Oxide Market