
 Ceramic Tiles Market | 2026-2036
Ceramic Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Tiles Market Analysis
ISO 13006 classification for ceramic tile quality and water absorption thresholds is redrawing competitive boundaries among manufacturers. Mohawk Industries leverages captive supply of raw materials across North American quarry networks to sustain margin stability. RAK Ceramics anchors its position through integrated production from frit manufacturing to finished goods in the United Arab Emirates. Porcelanosa Grupo differentiates via design-forward porcelain slabs that command specification in premium architectural projects.
Ceramic tiles are inorganic, non-metallic solids formed from clay, silica, and fluxing agents, then fired at temperatures between 1,000°C and 1,400°C to achieve dimensional stability and surface hardness; their primary commercial purpose spans protective and decorative surfacing for built environments. Porcelain tiles, with water absorption below 0.5%, now dominate specification in high-traffic commercial flooring where freeze-thaw resistance and load-bearing capacity matter. The residential end-user segment leads volume absorption across Asia-Pacific markets, while wall cladding applications in hospitality and healthcare settings generate outsized margin pools relative to commodity flooring.
REACH compliance in Europe restricts heavy metal content in ceramic glazes, compelling reformulation investments that smaller producers cannot absorb. The EPA's National Emission Standards for Hazardous Air Pollutants govern kiln emissions from U.S. tile manufacturing, shaping plant location and abatement technology choices. India's BIS certification mandates IS 15622 conformance for dimensional and mechanical properties, creating non-tariff barriers for unqualified imports. Stakeholders must monitor how tightening embodied carbon regulations across multiple jurisdictions will reshape raw material sourcing and kiln energy profiles.
Market Dynamics
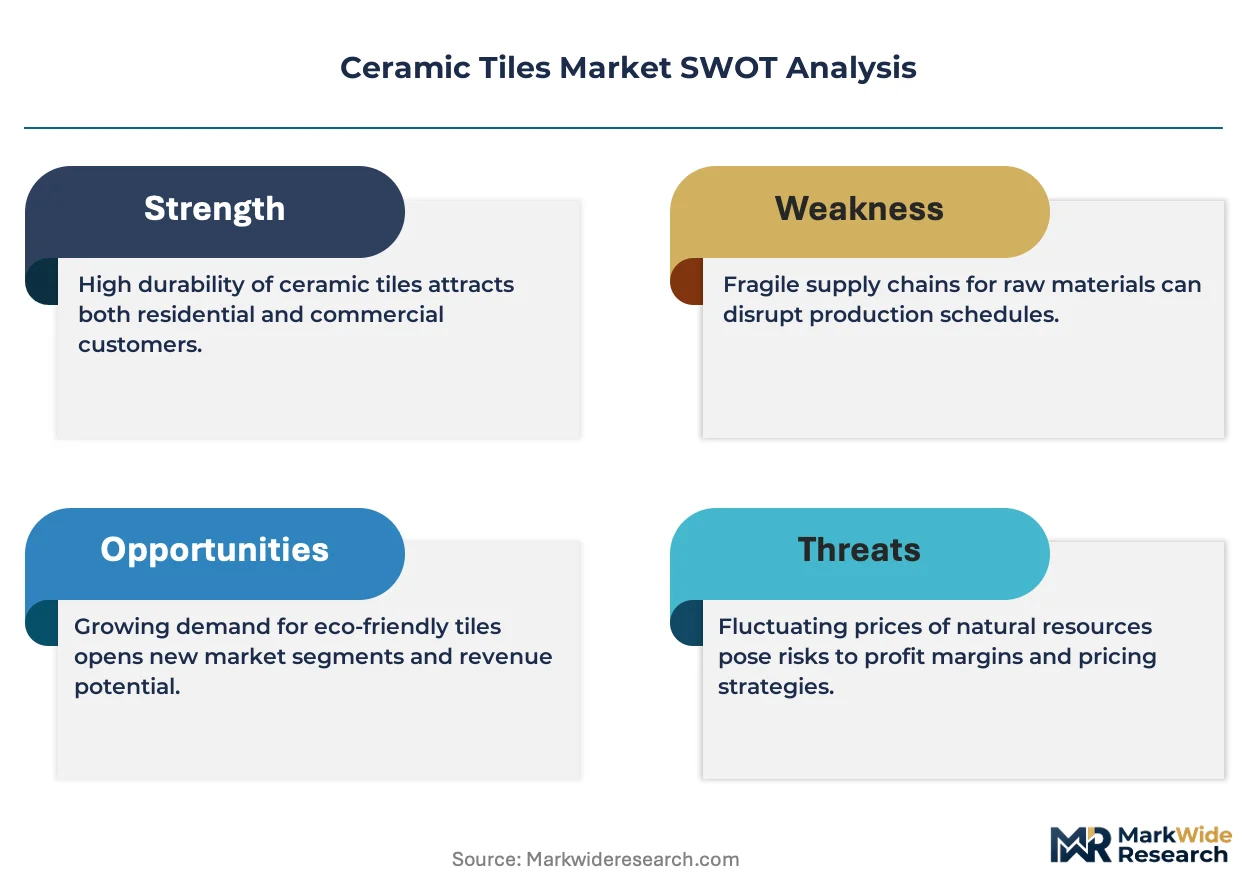
Embodied carbon regulations across multiple jurisdictions are forcing simultaneous reformulation of raw material inputs, kiln energy sources, and glaze chemistries, compressing margins for manufacturers lacking integrated supply chain control or captive renewable energy access.
Growth Catalysts
- EU Green Deal carbon border adjustments:The mechanism penalizes high-carbon imports, incentivizing local production investment and greenfield kiln construction with carbon capture integration.
- Large-format porcelain slabs:These products command specification in premium residential and commercial projects across Vietnam's urban corridor from Ho Chi Minh City to Binh Duong province.
- Healthcare infrastructure expansion:Antimicrobial glazed tiles meet stringent hygiene protocols in hospital construction across Southeast Asian markets.
Market Restraints
- Natural gas price volatility:Kiln operations depend on consistent thermal input, and European manufacturers face structurally elevated energy costs relative to Middle Eastern competitors with captive gas supply.
- China clinker concentration:Over sixty percent of global ceramic-grade kaolin and feldspar processing capacity sits within Chinese provincial borders, creating single-source vulnerability.
- Thin-set mortar substitution:Luxury vinyl tile and engineered wood flooring capture specification in residential renovation where speed of installation outweighs durability premiums.
Strategic Opportunities
- India's Smart Cities Mission:Urban infrastructure mandates create sustained demand for wear-resistant public space surfacing across 100 designated metropolitan zones.
- Photocatalytic self-cleaning glazes:Titanium dioxide surface treatments enable specification in high-maintenance commercial facades where labor cost reduction justifies material premium.
- Direct-to-contractor digital platforms:Bypassing traditional distributor markup, manufacturers capture margin and demand data through proprietary specification tools.
Industry Challenges
- ISO 13006 certification timelines:Water absorption and mechanical strength testing protocols extend product launch cycles by four to six months for new formulations.
- Legacy kiln retrofit complexity:Converting natural gas-fired tunnel kilns to hydrogen or electric heating requires complete refractory relining and control system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Tiles Market |
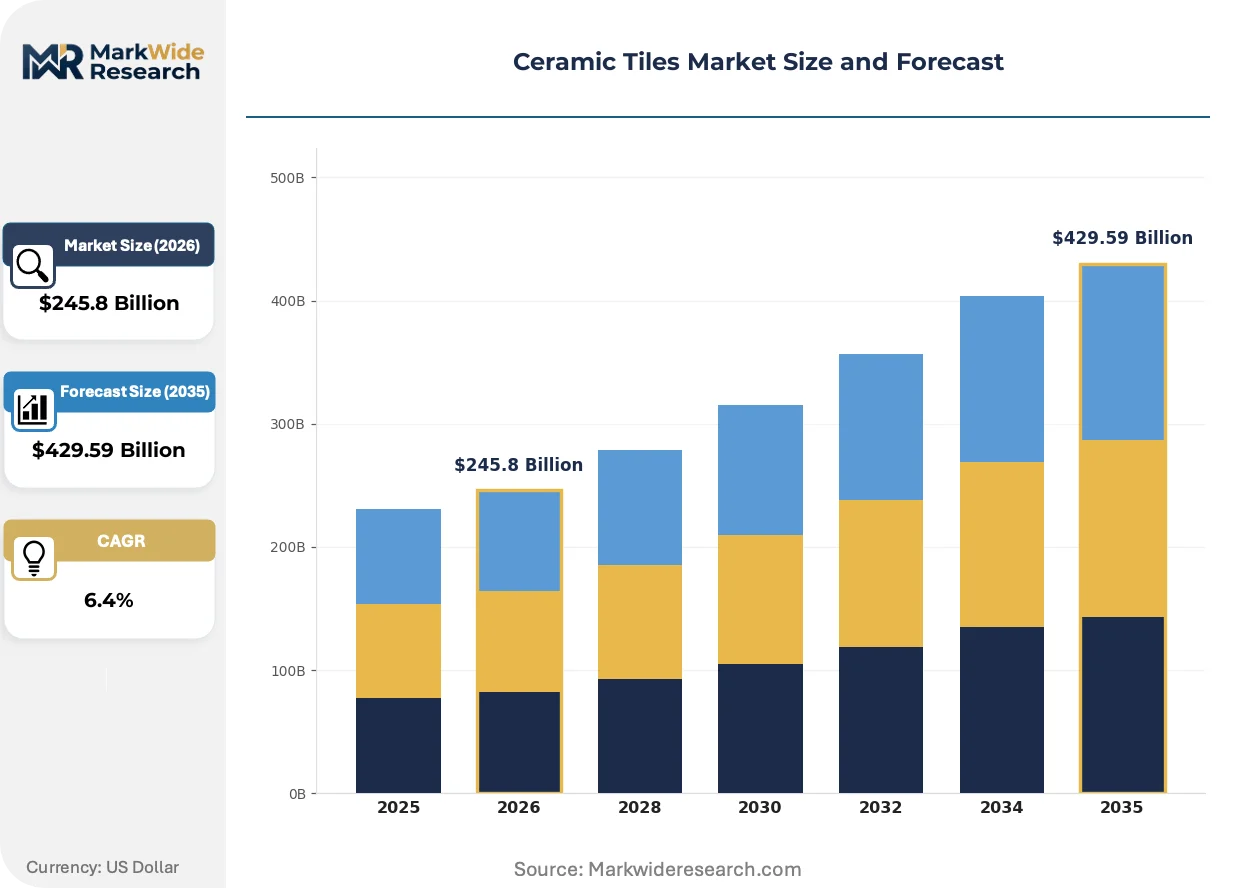
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $429.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed, Unglazed, Porcelain, Stoneware Application: Flooring, Wall Cladding, Backsplash, Countertops End User: Residential, Commercial, Institutional, Industrial Design Style: Traditional, Modern, Rustic, Contemporary |
| Companies Covered | RAK Ceramics, Lasselsberger Group, Mohawk Industries Inc., Florim Ceramiche, SCG Ceramics, Grupo Lamosa, Kajaria Ceramics Limited, Marco Polo, Porcelanosa Grupo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Tiles Market Emerging Trajectories
Digital inkjet decoration technology paired with advanced body preparation is collapsing the cost gap between premium aesthetic effects and commodity production, enabling mass customization without batch-size penalties.
Single-pass digital printing with reactive inks is supplanting traditional rotary screen and flexographic decoration methods in high-volume porcelain manufacturing. Architectural specifiers in hospitality and corporate interiors now demand marble and stone replication indistinguishable from natural material at one-third the installed weight. This capability compression is eroding the traditional premium tier occupied by imported Italian porcelain.
REACH compliance enforcement through ECHA is mandating third-party heavy metal testing for all ceramic glazes entering European distribution, regardless of origin. Manufacturers must maintain batch-level documentation for chromium, lead, and cadmium content. Small-format wall tile imports from unverified Asian producers face elevated customs inspection rates and bonded warehouse delays.
Specification decisions increasingly migrate from distributor showrooms to architect and contractor digital libraries where BIM object compatibility and embodied carbon data determine shortlist inclusion. Large commercial developers in the United Arab Emirates and Saudi Arabia now require Environmental Product Declaration documentation as a mandatory bid qualification. This certification-driven preference shift disadvantages producers lacking verified lifecycle assessment data.
Ceramic Tiles Market Segmentation
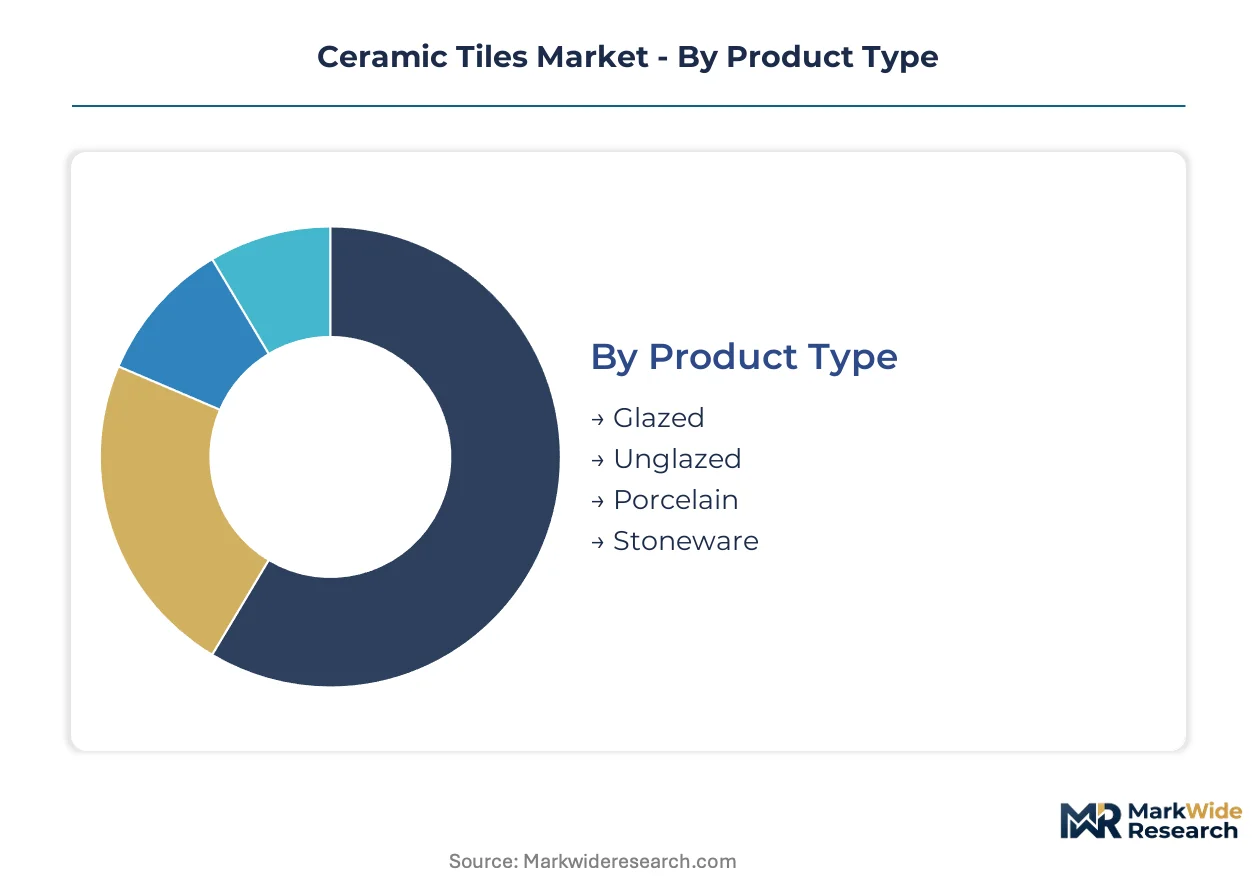
Ceramic tile manufacturers deploy distinct technical and commercial strategies across product architectures, surface applications, and aesthetic positioning. Segmentation discipline separates margin capture in specification-driven architectural projects from commodity flooring volume plays.
Product Type:
Porcelain commands the widest margin spreads through technical performance premiums, while glazed tiles anchor volume throughput in residential renovation channels.
- Glazed:Glass-based surface coatings fused at high temperature create decorative color variation and stain resistance. Demand concentrates in residential kitchen and bathroom renovation across Vietnam's urban corridor from Ho Chi Minh City to Binh Duong province, where moisture resistance justifies material specification over paint or wallpaper alternatives.
- Porcelain:Fired at temperatures exceeding 1,200°C with water absorption below 0.5%, achieving density suitable for high-traffic commercial flooring and exterior cladding. Demand concentrates in hospitality and healthcare construction across Southeast Asian markets, where freeze-thaw resistance and load-bearing capacity command specification premiums.
- Unglazed:Natural clay body exposed without surface coating, offering slip resistance for exterior and wet-area applications.
- Stoneware:Intermediate density between earthenware and porcelain, serving cost-conscious commercial projects requiring moderate durability.
Porcelain holds installed capacity in premium architectural specification. Glazed is rotating up the share rankings through residential renovation volume absorption.
Application:
Wall cladding generates outsized margin pools relative to commodity flooring through specification complexity and installation labor bundling.
- Wall Cladding:Vertical surfacing solutions requiring specialized adhesive systems and substrate preparation. Demand concentrates in hospitality and healthcare settings across Southeast Asian markets, where antimicrobial glazed tiles meet stringent hygiene protocols and large-format porcelain slabs reduce grout lines.
- Flooring:Horizontal load-bearing surfaces dominating volume absorption across residential construction. Demand concentrates in India's Smart Cities Mission metropolitan zones, where wear-resistant public space surfacing mandates create sustained procurement pipelines.
- Backsplash:Decorative protective surfacing for kitchen and bathroom wet zones, typically small-format with high design variation.
- Countertops:Structural work surfaces requiring enhanced thickness and edge treatment, competing with engineered stone and solid surface materials.
Flooring maintains volume dominance. Wall cladding is climbing the fastest through premium specification migration.
End User:
Commercial developers now require Environmental Product Declaration documentation as mandatory bid qualification, reshaping competitive access.
- Commercial:Office, retail, and hospitality construction with specification driven by architectural firms and facilities managers. Demand concentrates in the United Arab Emirates and Saudi Arabia, where large commercial developers mandate embodied carbon data and BIM object compatibility for shortlist inclusion.
- Residential:Single-family and multi-family housing construction absorbing volume through distributor and direct-to-contractor channels. Demand concentrates in Southeast Asia's urban corridor, where large-format porcelain slabs command specification in premium residential projects.
- Institutional:Government, education, and healthcare facilities with extended procurement cycles and public tender requirements.
- Industrial:Manufacturing and warehouse facilities prioritizing chemical resistance and load capacity over aesthetic consideration.
Residential leads volume absorption. Commercial is gaining share fastest through certification-driven preference shifts.
Design Style:
Digital inkjet decoration technology collapses the cost gap between premium aesthetic effects and commodity production.
- Modern:Clean lines, minimal ornamentation, and neutral palettes aligned with contemporary architectural movements. Specification concentrates in corporate interiors and premium residential projects where marble and stone replication indistinguishable from natural material commands premium positioning.
- Contemporary:Evolving aesthetic trends incorporating current color forecasts and texture innovations. Specification concentrates in hospitality renovation cycles across Southeast Asian markets, where design-forward porcelain slabs differentiate property positioning.
- Traditional:Classical patterns and ornamental motifs serving heritage restoration and conservative residential preferences.
- Rustic:Textured surfaces and earthy tones replicating natural material variation for residential and hospitality warmth positioning.
Modern holds specification density in premium architectural channels. Contemporary is expanding most quickly through hospitality renovation velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial developers and residential contractors across distinct geographies drive ceramic tile procurement patterns. Buyer archetypes cluster around hospitality specifiers in Southeast Asia, healthcare builders in the Gulf states, and urban infrastructure planners in South Asia.
United States
Residential renovation and commercial hospitality construction absorb porcelain slabs and glazed wall tiles. EPA National Emission Standards for Hazardous Air Pollutants govern kiln emissions, shaping plant siting decisions in the Southeast. The Dallas-Fort Worth metroplex anchors distribution hubs serving Sun Belt construction velocity.
China
Urban residential high-rises and commercial mixed-use developments drive large-format porcelain consumption. GB standards and MIIT regulations enforce product quality and energy efficiency benchmarks for ceramic manufacturing. The Pearl River Delta industrial corridor concentrates glazing technology suppliers and digital decoration equipment providers.
India
Smart Cities Mission infrastructure and affordable housing schemes sustain demand for wear-resistant public surfacing. BIS certification mandates IS 15622 conformance, creating compliance barriers for unqualified imports. Gujarat's Morbi ceramic cluster hosts concentrated kiln capacity serving domestic and export markets.
Germany
Commercial refurbishment and heritage restoration projects specify technical porcelain and traditional stoneware. REACH compliance through ECHA mandates heavy metal testing for all ceramic glazes entering distribution. The Rhine-Ruhr industrial region maintains specialized refractory supply chains for high-temperature kiln operations.
Vietnam
Urban residential towers and hospitality developments from Ho Chi Minh City to Binh Duong province absorb large-format porcelain slabs at scale. National technical regulations on construction materials enforce dimensional and mechanical property standards. The Southern Key Economic Zone concentrates specification-driven architectural project pipelines.
Ceramic Tiles Market Vendor Landscape
Player mix skews toward integrated manufacturers with captive raw material supply and design-forward specialists commanding premium specification. The vendor base separates into three tiers: global scale producers with quarry network control, regional champions with kiln-to-distribution integration, and niche specialists in large-format porcelain slabs. Competitive moves center on backward integration into frit manufacturing and portfolio expansion into antimicrobial surface treatments.
Within the integrated production tier, RAK Ceramics and Mohawk Industries occupy positions as archetypes of upstream control. Porcelanosa Grupo exemplifies design-forward positioning in premium architectural channels. Kajaria Ceramics Limited represents regional scale concentration serving infrastructure-intensive markets.
| Leading Market Players |
|---|
| RAK Ceramics |
| Lasselsberger Group |
| Mohawk Industries Inc. |
| Florim Ceramiche |
| SCG Ceramics |
| Grupo Lamosa |
| Kajaria Ceramics Limited |
| Marco Polo |
| Porcelanosa Grupo |
| Others |
Supply Flow & Price Mechanics
Capacity utilization rates above 85 percent in Morbi and Foshan clusters compress marginal cost curves and establish price floors that smaller regional kilns cannot match, concentrating supply-side pricing power among integrated producers with captive raw material reserves.
Pricing Analysis
Long-term offtake contracts with natural gas indexation dominate procurement between European manufacturers and Middle Eastern suppliers, insulating margin stability against spot price volatility. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade porcelain with ISO 13006 certification from commodity glazed tile. Price differentiation hinges on embodied carbon documentation and BIM object compatibility, with commercial developers in the Gulf states least sensitive and residential renovators in Southeast Asia most responsive to per-square-meter differentials. Cost compression in standard-grade glazed tile is intensifying because digital inkjet decoration collapses aesthetic premium capture.
Supply Chain Analysis
China and India anchor global ceramic-grade kaolin and feldspar processing, with Guangdong and Gujarat provinces hosting concentrated beneficiation capacity. Kiln operations draw from silica sand deposits in Vietnam, fluxing agents from Turkey, and digital decoration equipment from Italy. Single-source vulnerability concentrates in Chinese clinker supply, where over sixty percent of global processing sits within provincial borders. Distribution runs through regional distributor networks in Southeast Asia, direct-to-contractor platforms in North America, and project-specific specification channels in the Middle East.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Large-format porcelain slab adoption in Vietnam's urban corridor signals early-cycle expansion, with specification velocity in premium residential towers outpacing historical penetration curves for comparable surfacing materials.
For Market Incumbents: Compound specification lock-in through backward integration into frit manufacturing and captive renewable energy contracts that neutralize EU carbon border adjustment exposure. Secure ISO 13006 certification pipelines to defend against emerging Turkish producers with lower embodied carbon profiles. Prioritize antimicrobial glaze R&D to capture healthcare infrastructure procurement cycles across Southeast Asia.
For New Entrants and Emerging Players: Differentiate on photocatalytic self-cleaning surface treatments for high-maintenance commercial facades where labor cost reduction justifies material premium. Target India's Smart Cities Mission metropolitan zones with wear-resistant public space surfacing that meets BIS IS 15622 conformance. Deploy direct-to-contractor digital platforms to bypass traditional distributor markup and capture demand data.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated manufacturers with captive quarry networks and long-term offtake contracts with Gulf state developers. Five-to-ten year viability favors producers with verified Environmental Product Declaration documentation and hydrogen kiln retrofit roadmaps. Monitor EU Green Deal carbon border adjustment implementation timelines as inflection indicator for competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Frit Manufacturing | Captive glaze chemistry control neutralizes REACH compliance cost volatility for European market access. |
| Hydrogen Kiln Retrofit Program | Refractory relining and control system replacement enables EU Green Deal carbon border adjustment compliance. |
| Antimicrobial Surface Treatment Development | Titanium dioxide and silver-ion formulations capture hospital construction procurement across Southeast Asian markets. |
| Direct-to-Contractor Platform Launch | Proprietary specification tools bypass distributor markup and generate demand-side data for production planning. |
| Environmental Product Declaration Certification | Verified lifecycle assessment data meets mandatory bid qualification for commercial developers in UAE and Saudi Arabia. |
Methodological Framework
Initial hypotheses were tested against primary input from plant managers at integrated kiln facilities, procurement leads at commercial developers, ceramic glaze R&D directors, and distributor channel partners, and refined through secondary validation against customs trade data, BIS certification registries, SEC 10-K filings from listed manufacturers, and ECHA REACH compliance databases. Bottom-up capacity utilization estimates from Morbi, Foshan, and Castellon clusters were triangulated against top-down construction spend forecasts.
Variance decomposition across product type, application, end-user segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume absorption rates and value-per-unit trajectories, with kiln energy cost profiles and embodied carbon compliance timelines as ceramic-specific forecast inputs.
Material uncertainties — natural gas price volatility, EU carbon border adjustment implementation scope, and China clinker supply disruption — sit outside the modeled envelope. Forecasts reflect assumptions about specification migration toward large-format porcelain and tightening heavy metal content restrictions. Recalibration cycles align with material shifts in energy input costs and regulatory enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Dielectric Ceramics Market
Ceramics
Potassium Silicate Market
Ceramics
Ceramic Fabrication Services Market
Ceramics
Zirconia Ceramics Market
Ceramics
Barium Carbonate Powder Market
Ceramics
Calcined Alumina Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
North America Ceramic Coatings Market
Ceramics
Active Calcium Silicate Market
Ceramics
Asia-Pacific Ceramic Coatings Market
Ceramics
Carbon-Ceramic Discs Market
Ceramics
Global Alumina Trihydrate Market
Ceramics
Methyl Silicate Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Liquid Sodium Silicate Market