
 Europe Caustic Potash Market | 2026-2036
Europe Caustic Potash Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Caustic Potash Market Intelligence
Aftermarket technical service revenue is narrowing as European chlor-alkali producers consolidate captive maintenance capabilities. INOVYN leverages its integrated electrolysis network across the UK and France to control raw material flows. Kemira anchors its position through specialized water treatment applications that demand high-purity caustic potash grades. BASF differentiates via backward integration into potassium salt sourcing and proprietary refining technology.
Caustic potash, or potassium hydroxide, is an inorganic compound with the formula KOH, typically produced via membrane cell electrolysis of potassium chloride brine with purity grades ranging from industrial to food and pharmaceutical specifications; it serves as a core reagent in pH regulation, saponification, and potassium salt synthesis across multiple industries. Liquid formulations dominate volume flows into chemical manufacturing and agriculture due to handling efficiency and bulk logistics economics, while pearl and flake grades command premium positioning in food processing and pharmaceutical applications where dissolution control and low chloride content determine qualification. The fertilizer application segment is maturing amid substitution risks from alternative potassium sources, whereas pharmaceutical and food-grade channels concentrate margin pools through certification barriers and batch traceability requirements.
REACH registration mandates under ECHA govern substance classification and safe handling protocols across EU production sites, while the EU Green Deal and F-Gas Regulation are pressuring energy-intensive electrolysis operations to decarbonize or face carbon border adjustment exposure. Germany's KBA and France's ANSM enforce sector-specific purity standards for automotive and pharmaceutical end uses respectively, creating differentiated compliance obligations by application. Stakeholders must monitor the interplay between electricity cost structures and regulatory carbon intensity thresholds to determine capacity investment timing and product mix allocation.
Market Dynamics
Membrane cell electrolysis technology diffusion and EU carbon border adjustment mechanisms are restructuring production economics across European chlor-alkali operations, forcing asset reconfiguration and grade specialization decisions.
Growth Catalysts
- EU Green Deal carbon intensity thresholds:Electrolysis operators investing in renewable power sourcing secure preferential positioning under CBAM transition rules, advantaging low-carbon KOH output.
- Potassium-based fertilizer demand:German and Polish agricultural input manufacturers are expanding offtake agreements for industrial-grade material amid soil nutrient replenishment cycles.
- Pharmaceutical-grade certification pipelines:France's ANSM and Netherlands health authorities are tightening purity documentation requirements, creating captive demand for batch-traceable production.
Market Restraints
- Potassium chloride feedstock volatility:MOP (muriate of potash) contract pricing swings directly compress electrolysis margin structures without pass-through mechanisms.
- Energy cost asymmetry:Nordic hydroelectric-powered production sites undercut continental natural gas-dependent capacity on unit economics.
- Alternative potassium source substitution:Sulfate of potash and organic potassium compounds displace caustic potash in select fertilizer blending applications.
Strategic Opportunities
- Central European battery chemical supply:Poland and Czech Republic EV cathode material plants require high-purity KOH for precursor synthesis, opening geographic demand expansion.
- REACH-registered food-grade channel:EFSA-compliant pearl and flake grades command qualification premiums in confectionery and cocoa processing applications.
- Integrated carbon capture coupling:Electrolysis-CCUS technology convergence enables negative-emission KOH production eligible for EU Innovation Fund support.
Industry Challenges
- Electrolyzer membrane replacement cadence:Nafion and Flemion membrane procurement cycles strain maintenance planning amid supplier lead time extension.
- Multi-grade inventory complexity:Pharmaceutical, food, and industrial specification coexistence demands segregated logistics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Caustic Potash Market |
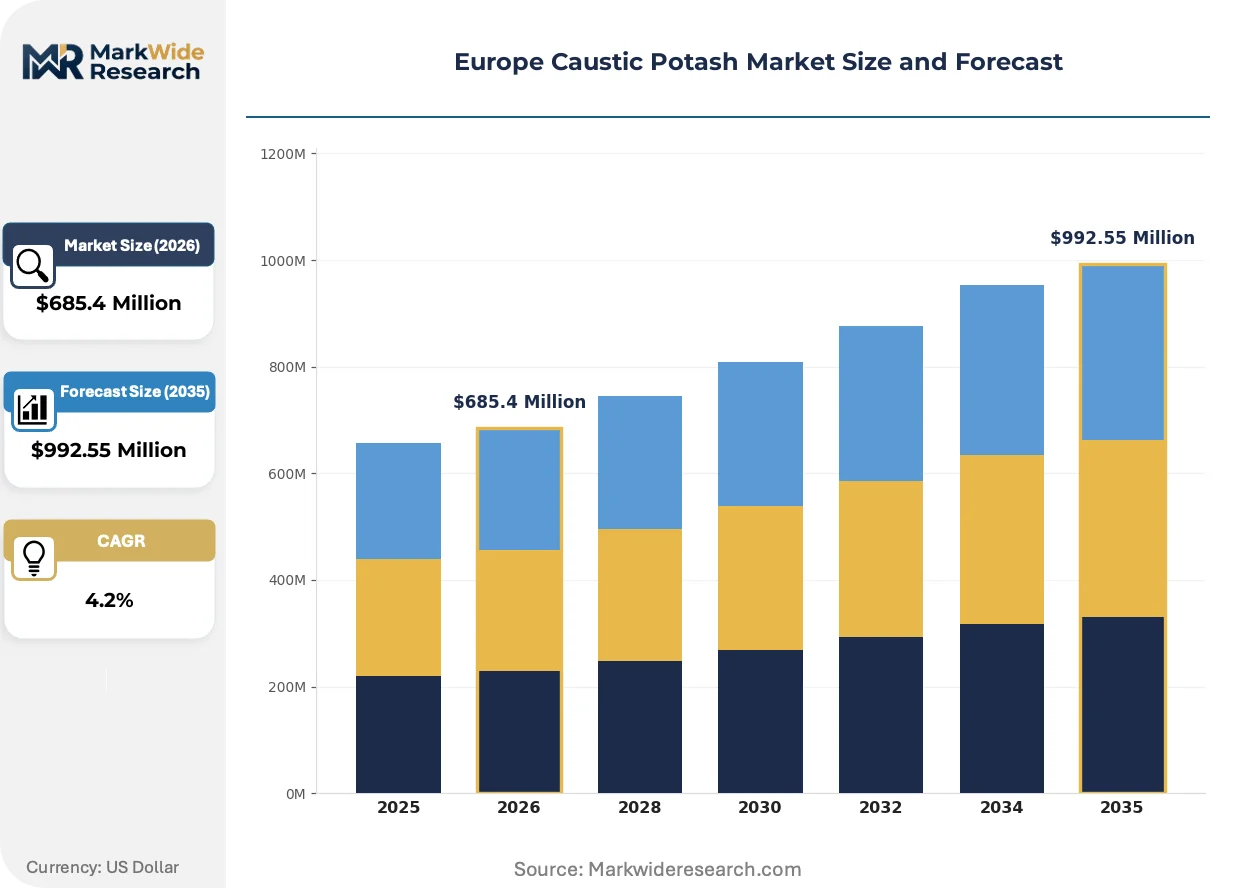
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Pearls, Liquid, Granules Application: Fertilizers, Industrial Chemicals, Food Processing, Pharmaceuticals End User: Agriculture, Chemical Manufacturing, Food Industry, Healthcare Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | INOVYN, Tessa Potash, Kemira, Arkema, Solvay, Evonik Industries, BASF, Westlake Chemical, Nouryon, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Caustic Potash Market Strategic Shifts & Innovations
Electrification of chemical process heat and tightening substance traceability mandates are compressing legacy production paradigms while opening premium positioning pathways for compliant operators.
Bipolar membrane electrolysis is collapsing energy intensity benchmarks in caustic potash production. Nordic operators adopting this cell architecture achieve 15-20% power consumption reduction versus monopolar configurations. The technology is collapsing competitive moats for gas-dependent continental producers unable to amortize retrofit capital.
REACH authorization sunset clauses are accelerating substitution planning across downstream formulators. ECHA's 2024-2027 substance evaluation roadmap flags specific KOH impurities for restriction assessment. Pharmaceutical and personal care compounders in Germany and Benelux are pre-qualifying alternative supply chains ahead of potential listing decisions.
Consolidated procurement desks at major fertilizer and detergent manufacturers are compressing supplier rosters to dual-source arrangements. Former fragmented purchasing across plant-level buyers is centralizing to category managers demanding ESG audit documentation. This concentration is most visible in German agricultural cooperative purchasing and French industrial chemical distribution.
Europe Caustic Potash Market Segmentation
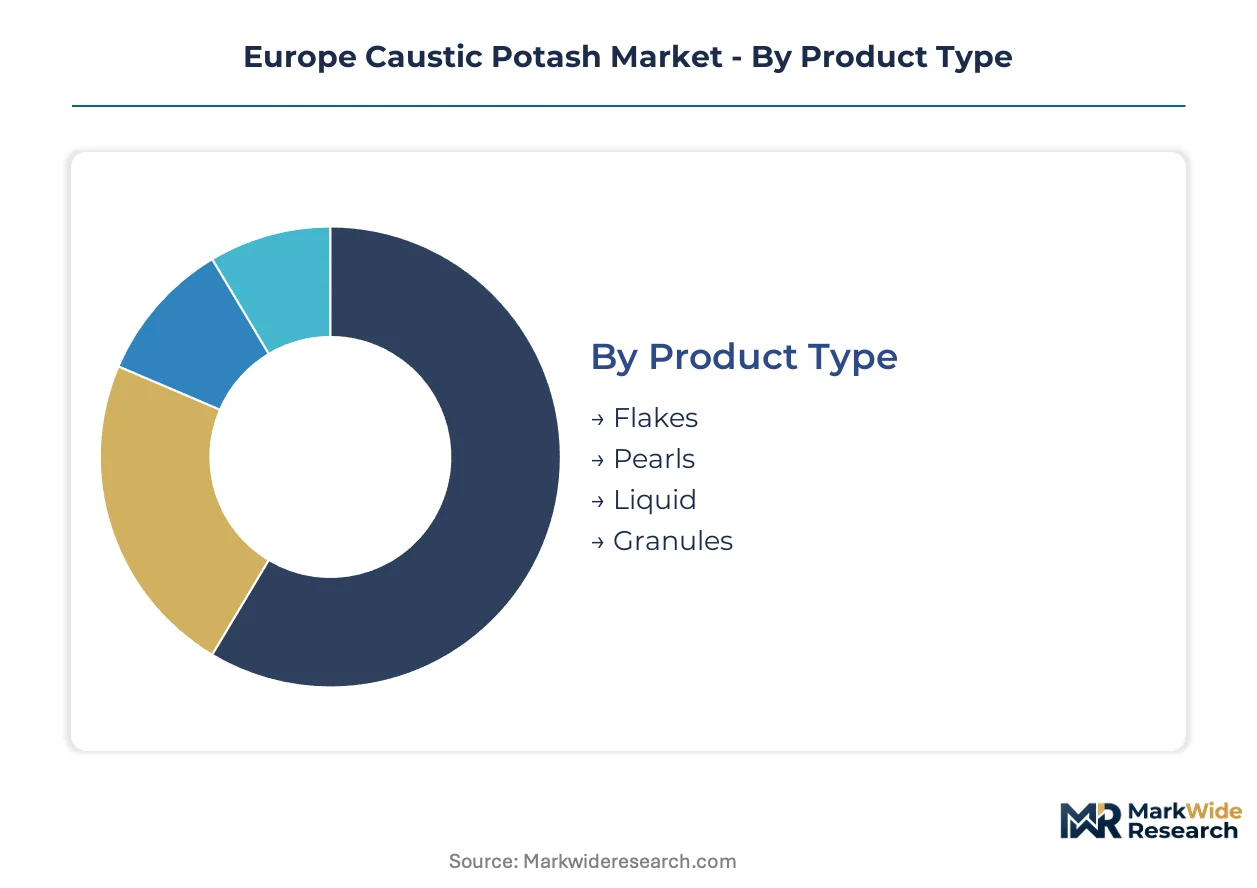
Segmentation in the European caustic potash market reveals how purity grades and delivery formats command divergent margin structures across regulatory environments. Understanding these divides allows producers to allocate membrane cell capacity toward the most defensible qualification tiers.
Product Type:
Mature industrial formats dominate volume flows, while emerging high-purity solid grades capture expanding premium pools in regulated end uses.
- Liquid:Concentrated aqueous solutions at 45-50% KOH by weight serve chemical manufacturing and agriculture through bulk tanker logistics. German fertilizer blenders and Dutch industrial compounders absorb the largest volumes under long-term offtake contracts tied to MOP feedstock indices.
- Flakes:Thin, dehydrated sheets with low dust generation profile meet food-grade and pharmaceutical specifications demanding rapid dissolution control. French confectionery processors and Belgian cocoa refiners are consolidating procurement around REACH-registered flake suppliers with batch traceability systems.
- Pearls:Spherical agglomerated particles offer handling advantages in automated dosing equipment for detergent and personal care formulation.
- Granules:Dense, low-surface-area particles serve specialized dehumidification and gas scrubbing applications in Nordic industrial operations.
Liquid handles the majority of throughput; flakes are climbing the fastest on share as food and pharmaceutical qualification requirements tighten.
Application:
Cost tier stratification separates commodity fertilizer consumption from certification-intensive premium channels.
- Fertilizers:Industrial-grade KOH neutralizes acidic soils and synthesizes potassium salts for NPK blending. Polish and German agricultural cooperatives are expanding spring application programs amid soil nutrient replenishment cycles, though sulfate of potash substitution pressures margin recovery.
- Pharmaceuticals:USP/EP-compliant grades with heavy metal limits below 10 ppm serve pH adjustment and API synthesis. France's ANSM and Netherlands health authorities are enforcing serialized batch documentation, creating captive demand for qualified producers with dedicated pharmaceutical production lines.
- Industrial Chemicals:Intermediate purity material feeds potassium carbonate, permanganate, and silicate manufacturing across Benelux chemical clusters.
- Food Processing:EFSA-compliant grades enable cocoa alkalization, olive curing, and pH regulation in confectionery with strict chloride content ceilings.
Fertilizers handles the majority of throughput; pharmaceuticals is gaining share fastest as regulatory barriers deepen.
End User:
Customer type concentration determines contract structure, with agriculture favoring volume commitments and healthcare demanding audit-intensive supply agreements.
- Agriculture:Cooperative purchasing desks across Germany and Poland centralize procurement for seasonal fertilizer application, compressing supplier rosters toward dual-source arrangements with ESG documentation capabilities.
- Healthcare:Pharmaceutical manufacturers and hospital compounders require validated supply chains with change control protocols and impurity profiling. French and Dutch authorities are tightening GMP alignment expectations for excipient-grade material.
- Chemical Manufacturing:Chlor-alkali derivatives producers and specialty chemical formulators absorb industrial-grade flows through pipeline-connected supply.
- Food Industry:Confectionery, beverage, and processing equipment manufacturers qualify pearl and flake grades through HACCP-integrated supplier audits.
Agriculture handles the majority of throughput; healthcare is expanding most quickly on share as pharmaceutical traceability mandates proliferate.
Distribution Channel:
Supply concentration favors direct relationships for volume accounts, while fragmented specialty demand routes through distributor networks with technical service capabilities.
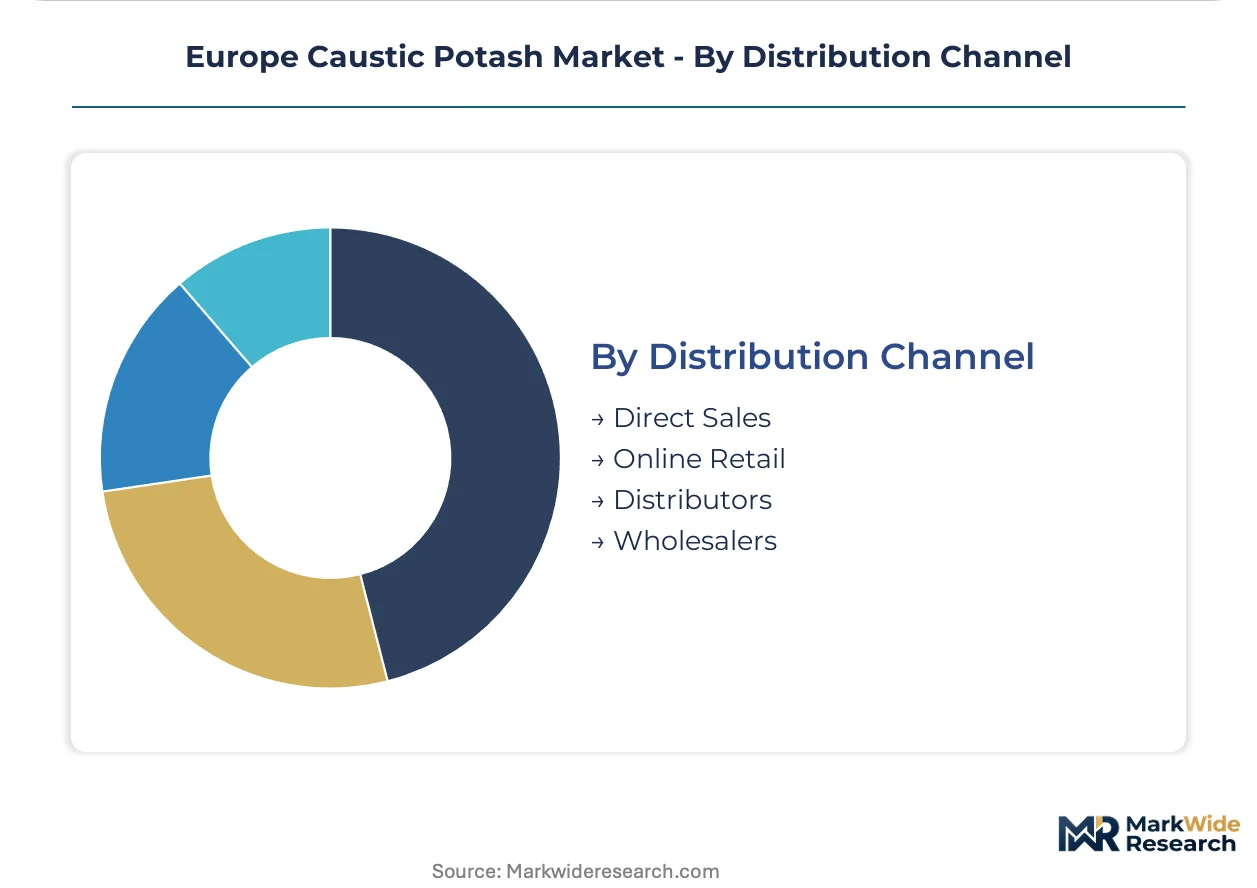
- Direct Sales:Producer-to-manufacturer contracts govern liquid bulk deliveries to fertilizer compounders and large chemical processors, with pricing indexed to electricity and potassium chloride input costs.
- Distributors:Regional chemical distributors with warehousing and blending capabilities serve mid-scale industrial accounts across France, Benelux, and Central Europe, consolidating fragmented demand into truckload quantities.
- Wholesalers:Agricultural supply cooperatives and commodity traders handle seasonal inventory positioning for farm-level distribution.
- Online Retail:Small-package specialty chemical vendors serve research laboratories, artisan food producers, and maintenance-repair-operations buyers with limited volume requirements.
Direct sales handles the majority of throughput; distributors are climbing the fastest on share as procurement centralization demands consolidated technical service relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs industrial-grade volumes for fertilizer blending while France and the Netherlands concentrate pharmaceutical-grade demand, creating a bifurcated consumption geography across the region.
Germany
Agricultural cooperatives in Lower Saxony and North Rhine-Westphalia expand potassium hydroxide offtake for spring soil treatment programs. KBA enforces purity standards for automotive battery applications, tightening qualification protocols. The Rhine-Ruhr chemical cluster hosts membrane cell operations supplying industrial compounders with pipeline-connected liquid deliveries.
France
Pharmaceutical manufacturers in the Île-de-France region drive USP-grade consumption for API synthesis and pH adjustment. ANSM mandates serialized batch documentation, creating captive demand for qualified producers. The Lyon chemical corridor concentrates pearl and flake processing for confectionery and cocoa alkalization applications.
Netherlands
Rotterdam-area chemical processors absorb bulk liquid flows for potassium salt derivative manufacturing. EFSA compliance requirements for food-grade material intensify supplier audit protocols. The port's integrated logistics infrastructure enables direct tanker discharge into Benelux industrial compounders.
Poland
Fertilizer blenders in the Silesian and Greater Poland voivodeships expand industrial-grade procurement amid soil nutrient replenishment cycles. EU Green Deal carbon intensity thresholds pressure electrolysis operators toward renewable power sourcing. Central European battery chemical plants in the Czech Republic border region draw high-purity KOH for cathode precursor synthesis.
United Kingdom
INOVYN's integrated electrolysis network spans Runcorn and Runcorn-area sites, controlling raw material flows across the British Isles. Post-Brexit REACH alignment obligations create parallel registration requirements for cross-channel trade. The Humber industrial cluster maintains chlor-alkali capacity serving domestic detergent and chemical manufacturing demand.
Europe Caustic Potash Market Key Industry Players
Capability concentration sits with specialized pharmaceutical-grade producers; scale advantage sits with integrated chlor-alkali operators commanding membrane cell networks. The vendor base stratifies across three tiers: multinational chemical conglomerates with backward integration into potassium salt sourcing, regional electrolysis specialists serving captive industrial demand, and niche refiners targeting food and pharmaceutical certification premiums. Dominant competitive moves include electrolyzer technology retrofit partnerships and multi-grade logistics infrastructure expansion.
Within the integrated chlor-alkali tier, INOVYN anchors membrane cell capacity across the UK and France, exemplifying geographic network advantages. Kemira occupies a position representing specialized water treatment application focus. BASF sits within the chemical conglomerate archetype, leveraging upstream potassium salt control. These three entities represent the competitive spectrum from electrolysis integration to application-specific refinement.
| Leading Market Players |
|---|
| INOVYN |
| Tessa Potash |
| Kemira |
| Arkema |
| Solvay |
| Evonik Industries |
| BASF |
| Westlake Chemical |
| Nouryon |
| Others |
Cost & Logistics Intelligence
Potassium chloride feedstock volatility determines both pricing tier spreads and supply chain shape across European caustic potash operations. MOP contract pricing swings compress electrolysis margins without pass-through mechanisms, forcing producers to segment capacity allocation between long-term fertilizer offtakes and premium pharmaceutical-grade spot markets.
Pricing Analysis
Long-term offtake contracts govern liquid bulk deliveries to German fertilizer compounders and Dutch industrial processors, with pricing indexed to electricity and potassium chloride input costs. Three-tier pricing structure across pharmaceutical, food, and industrial grades reflects certification burden and batch traceability requirements. Cost compression in industrial-grade channels is intensifying because sulfate of potash substitution pressures margin recovery. Agricultural cooperatives exhibit highest price sensitivity through centralized procurement desks, while pharmaceutical manufacturers accept premium positioning for ANSM-compliant material with serialized documentation.
Supply Chain Analysis
Muriate of potash feedstock draws from Belarusian, Russian, and Canadian mining operations before electrolysis conversion at membrane cell facilities. Nafion and Flemion membrane procurement rests on DuPont and Asahi Kasei supply cycles with extended lead times. Single-source vulnerability concentrates in electrolyzer membrane replacement cadence amid supplier capacity constraints. Distribution runs through pipeline-connected direct sales for volume accounts and regional chemical distributors serving fragmented specialty demand across France, Benelux, and Central Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European caustic potash markets approach a platform-economics inflection as REACH-registered supply chains consolidate around interoperable batch traceability systems. ECHA substance evaluation roadmaps and EU Green Deal carbon intensity thresholds are rewiring competitive moats toward compliance infrastructure rather than scale alone.
For Market Incumbents: Insulate pharmaceutical-grade positioning through dedicated production line investment and ANSM pre-qualification ahead of potential ECHA restriction listings. Secure backward integration into potassium salt sourcing to buffer MOP contract volatility. Expand membrane cell capacity in Nordic hydroelectric zones to undercut continental gas-dependent competitors on carbon-adjusted unit economics. For New Entrants and Emerging Players: Establish a beachhead in Central European battery chemical supply serving Poland and Czech Republic EV cathode material plants with high-purity KOH for precursor synthesis. Target food-grade flake qualification for French confectionery and Belgian cocoa alkalization applications where REACH registration creates defensible barriers. Pursue distributor partnerships with technical service capabilities rather than direct sales infrastructure. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors electrolysis-integrated operators with multi-grade logistics infrastructure and renewable power sourcing. Long-term viability centers on capacity positioned beneath EU carbon border adjustment thresholds. Watch Nordic bipolar membrane retrofit announcements as inflection indicators for competitive cost repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potassium Salt Sourcing | BASF's captive supply control buffers MOP contract volatility and secures feedstock qualification for pharmaceutical-grade output. |
| Bipolar Membrane Electrolysis Retrofit | Nordic operators adopting this cell architecture achieve power consumption reduction that collapses competitive moats for gas-dependent continental producers. |
| REACH-Registered Food-Grade Channel Expansion | EFSA-compliant pearl and flake grades command qualification premiums in French confectionery and Belgian cocoa processing applications. |
| Integrated Carbon Capture Coupling | Electrolysis-CCUS convergence enables negative-emission KOH production eligible for EU Innovation Fund support. |
| Central European Battery Chemical Supply Positioning | Poland and Czech Republic EV cathode plants require high-purity KOH for precursor synthesis, opening geographic demand expansion. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with membrane cell plant managers, procurement leads at fertilizer and pharmaceutical manufacturers, distribution channel partners, and technical R&D directors; and secondary validation through customs and trade data, Cefic chlor-alkali reports, SEC filings from listed chemical conglomerates, and ECHA substance registration databases. Bottom-up capacity and consumption modeling was cross-checked against top-down macroeconomic indicators.
Forecast inputs across the analysis window incorporated grade tier segmentation, end-use industry demand patterns, regional production hub economics, and electrolyzer technology diffusion curves. CAGRs were derived through logarithmic trajectory fitting against historical consumption baselines and projected capacity additions. Electricity cost structures and regulatory carbon intensity thresholds were modeled as scenario-dependent variables.
Stress conditions across potassium chloride feedstock pricing bands, renewable power cost trajectories, and ECHA authorization sunset timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against Cefic chlor-alkali production statistics and national customs discharge records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Phosphates Market
Bulk Chemicals
Meta Tartaric Acid Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
Sorbic Acid Market
Bulk Chemicals
Pyridine Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
Ferrous Oxalate Market
Bulk Chemicals
Global Persulfates Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Global Butyric Acid Market
Bulk Chemicals
Maleic Anhydride Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
Sulfamic Acid Market
Bulk Chemicals
1-Hexene Market
Bulk Chemicals
Isoprene Market