
 Polyamide Intermediate Chemicals Market | 2026-2036
Polyamide Intermediate Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Polyamide Intermediate Chemicals Market Analytics
Automotive component demand is hardening as the dominant pull factor for polyamide intermediate chemicals, displacing traditional textile offtake in volume terms. BASF SE leverages its integrated Ludwigshafen complex to anchor European supply security for adipic acid and caprolactam feedstocks. DuPont sustains technology leadership in high-heat polyamide formulations for under-the-hood applications. Ascend Performance Materials dominates the North American market through its Pensacola and Chocolate Bayou manufacturing assets.
Polyamide intermediate chemicals comprise monomeric building blocks such as adipic acid, hexamethylenediamine, and caprolactam, which undergo condensation or ring-opening polymerization to form nylon 6,6 and nylon 6 resins with melting points ranging from 220°C to 265°C. These intermediates serve primarily as precursors for engineering thermoplastics requiring mechanical strength, chemical resistance, and thermal stability in demanding industrial environments. Monomers command the largest value share as the non-substitutable foundation of all downstream polyamide synthesis, while additives represent the fastest-expanding margin pool as compounders seek flame-retardant and heat-stabilizer packages for electrified vehicle architectures. Automotive components and electronics applications concentrate the highest specification grades, where technical and industrial certifications determine supplier qualification timelines.
REACH registration requirements and the EU Green Deal's carbon border adjustment mechanism are tightening specifications for bio-based and recycled-content intermediates entering European value chains. EPA industrial emissions standards and OSHA process safety mandates in the United States elevate capital costs for adipic acid producers reliant on nitrous oxide-intensive oxidation chemistry. China's MEE environmental enforcement actions on caprolactam plants have triggered capacity rationalizations in Shandong and Zhejiang provinces. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments as circularity mandates propagate unevenly across major demand centers.
Market Dynamics
Automotive electrification programs are compressing qualification timelines for heat-stabilized polyamide formulations as OEMs consolidate multi-metal replacement strategies into single-platform sourcing decisions.
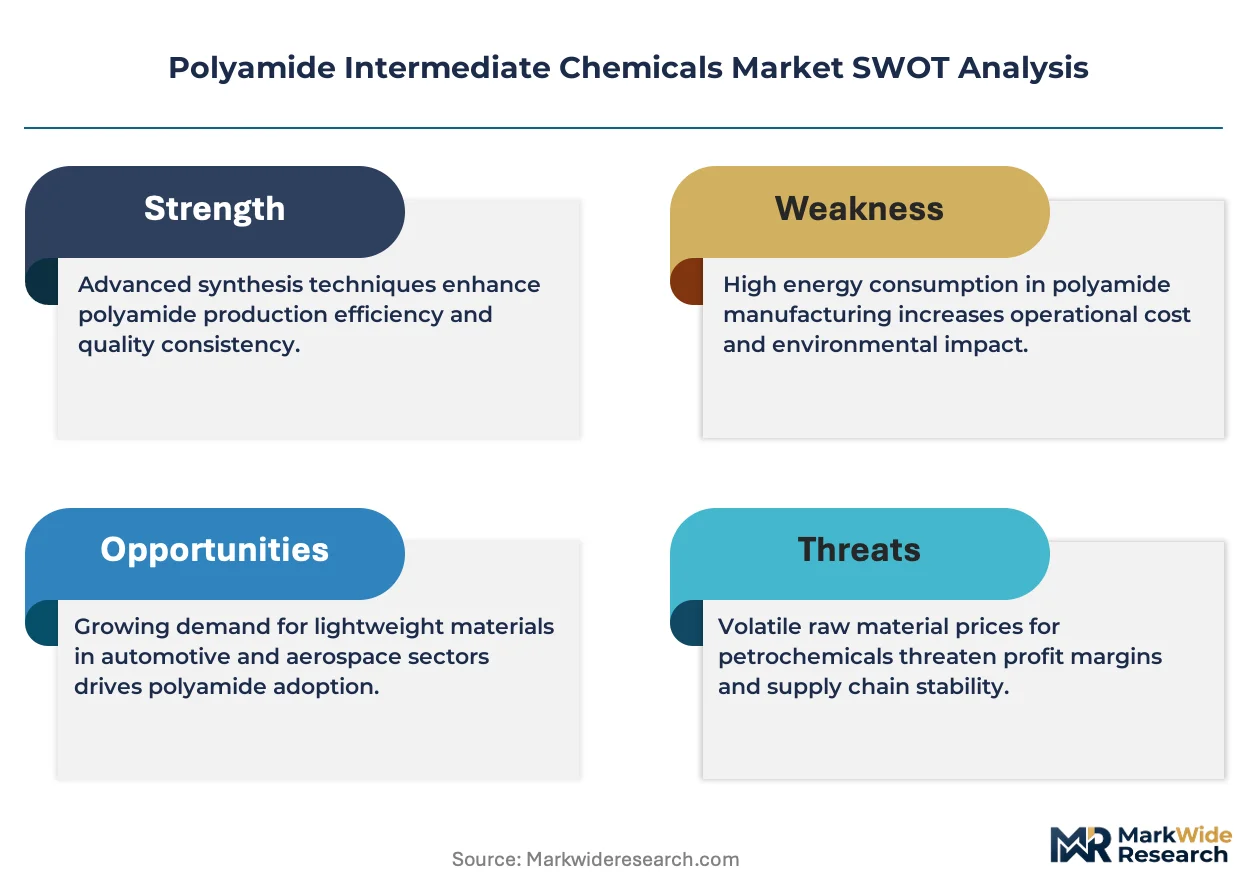
Growth Catalysts
- EU Green Deal carbon border adjustments:European compounders are accelerating bio-based adipic acid pilot programs to preempt CBAM exposure on fossil-derived feedstock imports.
- Under-the-hood thermal management:Electric vehicle battery pack housings and power electronics modules are specifying glass-filled nylon 6,6 grades above 40% loading for continuous-use temperatures exceeding 150°C.
- China's dual carbon targets:Provincial MEE enforcement in Shandong and Jiangsu is shuttering small-scale caprolactam units, concentrating viable capacity among state-backed producers with integrated benzene-to-polymer chains.
Market Restraints
- Benzene-cyclohexane price volatility:Crude-linked aromatics account for 60-70% of adipic acid variable cost, exposing margin structures to refinery turnaround schedules and naphtha arbitrage flows.
- Nitrous oxide abatement capex:EPA Clean Air Act Title V permitting for adipic acid expansions now mandates N2O catalytic decomposition units adding 15-20% to greenfield investment thresholds.
- Polypropylene substitution in interior trim:Cost-conscious Asian automakers are reverting to mineral-filled PP for non-structural cabin components where surface aesthetics trump mechanical load-bearing requirements.
Strategic Opportunities
- India PLI scheme for advanced chemistry:Reliance Industries and Indian Oil Corporation are evaluating caprolactam-adipic acid complexes to capture automotive polymer import substitution incentives.
- Chemical recycling feedstock certification:Pyrolysis-derived caprolactam from post-industrial carpet waste qualifies for ISCC PLUS mass-balance claims, opening premium pricing in European electronics supply chains.
- Direct e-commerce monomer distribution:Alibaba 1688 and specialty chemical marketplaces are disintermediating traditional distributor networks for standard-grade hexamethylenediamine in Southeast Asian compounding shops.
Industry Challenges
- Polymer characterization expertise scarcity:Compounders lack sufficient rheologists and thermal analysts to execute OEM-mandated multi-year aging protocols for electrified powertrain certification.
- Legacy ERP integration with mass-balance tracking:Batch-level carbon accounting systems for bio-attributed intermediates require middleware development that delays ISCC certification timelines by 8-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyamide Intermediate Chemicals Market |
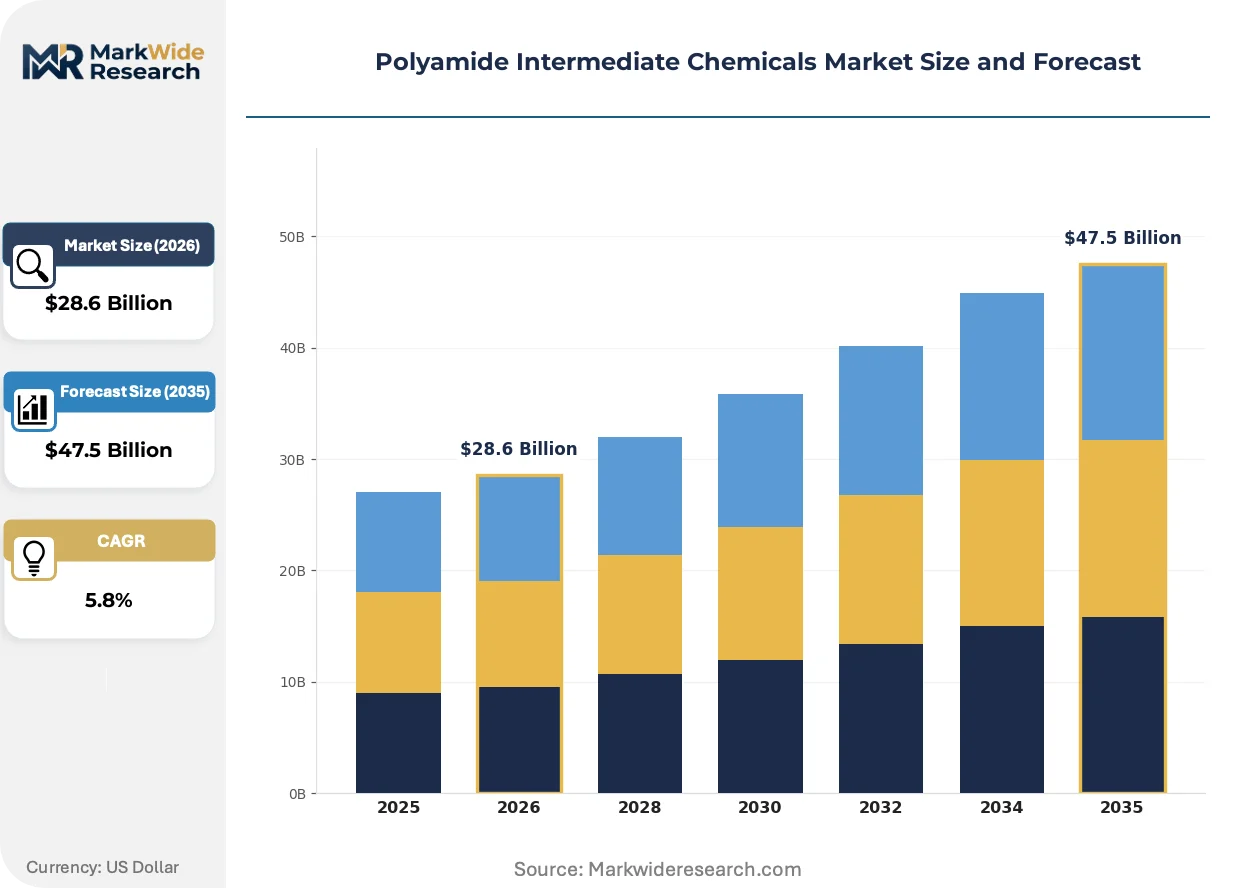
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monomers, Polymers, Additives, Compounds Application: Textiles, Automotive Components, Electronics, Packaging End Use Industry: Consumer Goods, Aerospace, Construction, Oil & Gas Grade: Industrial, Technical, Food Grade, Medical |
| Companies Covered | BASF SE, DuPont, DSM, Ascend Performance Materials, Envalior, Arkema, Evonik Industries, INVISTA, EMS-CHEMIE HOLDING AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyamide Intermediate Chemicals Market Evolving Landscape
Digital twin deployment across polymerization trains is compressing grade-changeover downtime while enabling real-time viscosity control that reduces off-specification batches in multi-product adipic acid and caprolactam facilities.
Continuous-flow reactor technology for cyclohexane oxidation is automating temperature profile management across thousands of micro-channels, eliminating hot-spot formation that degrades selectivity in conventional stirred-tank adipic acid plants. LyondellBasell and BASF are retrofitting European assets with modular flow-chemistry skids. The capital efficiency of these retrofits is automating capacity creep without full grassroots construction timelines.
REACH Article 33 disclosure requirements for Substances of Very High Concern are forcing reformulation of flame-retardant packages in electronics-grade polyamides, with phosphorus-based systems displacing legacy halogenated additives. Compounders must resubmit technical data files for UL 94 V-0 certifications. German automotive cable harness suppliers are qualifying alternative heat-stabilizer combinations to maintain OEM approval status.
Automotive Tier-1 buyers are consolidating resin specifications across model platforms, reducing approved supplier lists from 6-8 compounders per polymer grade to 2-3 strategic partners with guaranteed volume commitments. This concentration is compressing spot-market liquidity for standard nylon 6 and 6,6 grades. Procurement teams at Stellantis and Volkswagen are enforcing this consolidation most aggressively in powertrain and thermal management applications.
Polyamide Intermediate Chemicals Market Segmentation
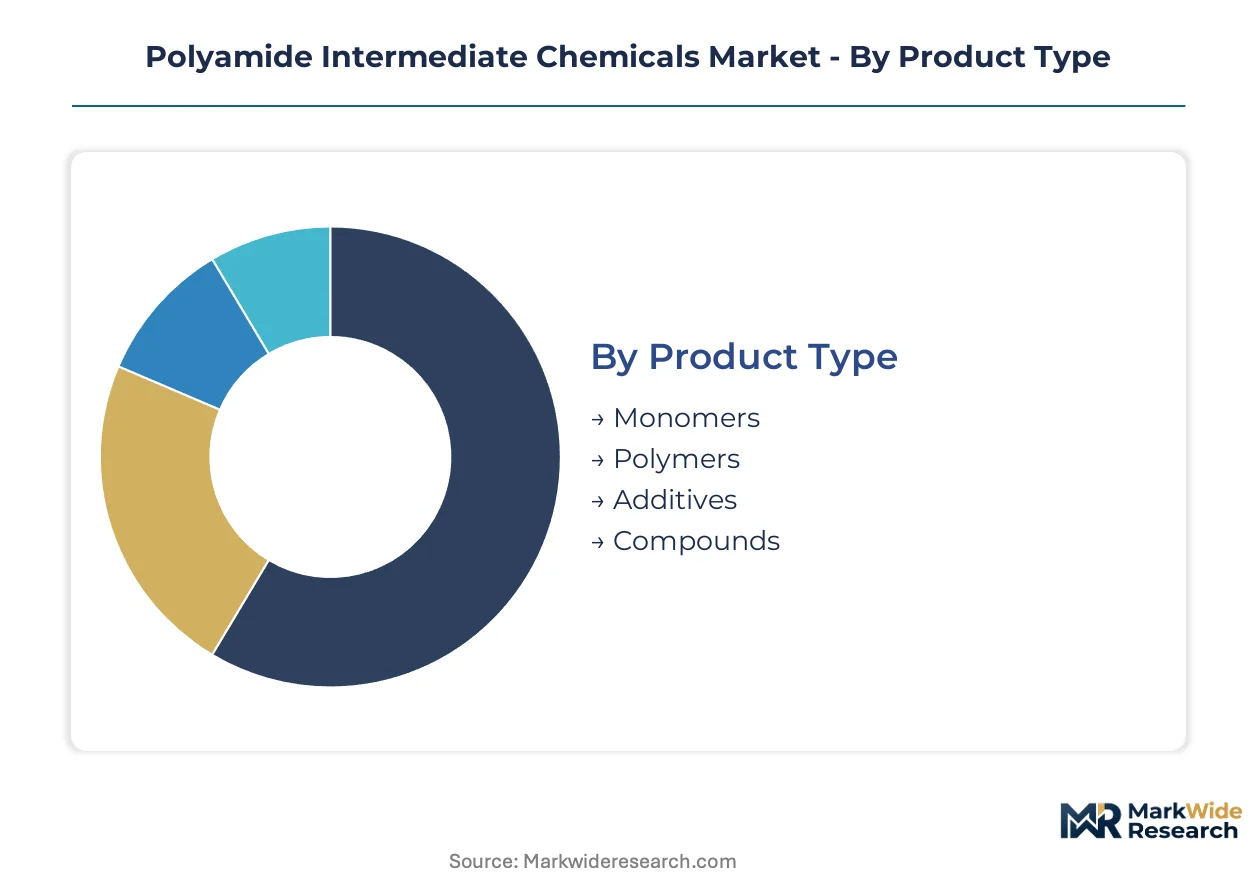
Segmentation in polyamide intermediate chemicals reflects divergent qualification barriers and margin architectures across the value chain. Product type distinctions separate commodity monomer producers from specialty compounders commanding formulation premiums. Application and end-use stratification determines whether suppliers compete on scale economies or technical service intensity.
Product Type:
Monomers operate as standalone feedstocks requiring massive integrated production, while additives and compounds embed into customer-specific formulations with higher switching costs.
- Monomers:Adipic acid, hexamethylenediamine, and caprolactam constitute the non-substitutable foundation of all nylon synthesis, produced via benzene-based oxidation or ammonia-based cyclization chemistry. Automotive electrification in Germany and the United States is hardening demand for ultra-high-purity grades as OEMs consolidate multi-metal replacement strategies into single-platform sourcing decisions.
- Additives:Flame retardants, heat stabilizers, and lubricant packages transform base resins into specification-grade compounds for electrified vehicle architectures. REACH Article 33 disclosure requirements for Substances of Very High Concern are forcing phosphorus-based systems to displace legacy halogenated additives across European electronics supply chains.
- Polymers:Nylon 6 and nylon 6,6 resins with melting points between 220°C and 265°C serve as the intermediate transformation stage between monomers and finished compounds.
- Compounds:Glass-filled and mineral-reinforced formulations tailored to OEM-mandated multi-year aging protocols for under-the-hood thermal management applications.
Monomers lead volumes today; additives are gaining share fastest.
Application:
Application segmentation tracks the migration of demand pull from traditional textile offtake toward engineered thermoplastics in mobility and electronics.
- Automotive Components:Battery pack housings, power electronics modules, and thermal management systems specify glass-filled nylon 6,6 grades above 40% loading for continuous-use temperatures exceeding 150°C. China's dual carbon targets and provincial MEE enforcement are shuttering small-scale caprolactam units, concentrating viable capacity among state-backed producers with integrated benzene-to-polymer chains serving this specification-intensive segment.
- Electronics:Connector housings, cable harness sheathing, and circuit breaker components require UL 94 V-0 flame-retardant certification combined with CTI tracking resistance. German automotive cable harness suppliers are qualifying alternative heat-stabilizer combinations to maintain OEM approval status amid REACH-driven reformulation mandates.
- Textiles:Carpet fiber and apparel filament applications, historically the dominant volume sink, now face displacement by engineering resin demand.
- Packaging:Barrier films and multilayer structures leveraging polyamide oxygen scavenging properties for food preservation.
Automotive components command the highest specification premiums; electronics is climbing the fastest.
End Use Industry:
End-use stratification separates cyclical industrial demand from consumer-driven replacement markets with divergent inventory velocity.
- Consumer Goods:Sporting equipment, power tool housings, and appliance components balance aesthetic surface finish against mechanical load-bearing requirements. Cost-conscious Asian appliance manufacturers are reverting to mineral-filled polypropylene for non-structural components where surface aesthetics trump mechanical specifications, constraining nylon penetration in this price-sensitive segment.
- Construction:Geotextiles, pipe fittings, and structural membranes requiring UV stabilization and hydrolysis resistance for infrastructure longevity.
- Aerospace:Interior cabin components and electrical insulation systems subject to FAR 25.853 fire-smoke-toxicity regulations.
- Oil & Gas:Subsea umbilical sheathing and pipeline corrosion barriers demanding hydrostatic pressure resistance and chemical inertness.
Consumer goods anchors current volume; construction shows the steepest expansion trajectory.
Grade:
Grade differentiation reflects the regulatory burden and certification overhead separating commodity industrial supply from medical and food-contact segments.
- Industrial:Standard viscosity resins for general-purpose extrusion and injection molding with basic thermal stability packages. EPA Clean Air Act Title V permitting for adipic acid expansions now mandates N2O catalytic decomposition units, elevating cost structures for producers serving this volume-driven tier.
- Technical:High-heat formulations with enhanced dimensional stability for precision engineering applications in powertrain and thermal management systems.
- Medical:Biocompatible grades meeting USP Class VI and ISO 10993 cytotoxicity standards for surgical instruments and drug delivery components.
- Food Grade:FDA and EFSA compliant materials for processing equipment and packaging films with extractables testing protocols.
Industrial grade dominates shipment volumes; technical grade is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting capital flows as producers seek jurisdictions with lower carbon-compliance costs and integrated feedstock access. The EU Green Deal's carbon border adjustment mechanism is accelerating capacity migration toward regions with abundant benzene derivatives and less stringent nitrous oxide abatement mandates.
China
Provincial MEE enforcement in Shandong and Zhejiang has shuttered small-scale caprolactam units, concentrating viable capacity among state-backed producers with integrated benzene-to-polymer chains. The dual carbon targets are tightening emissions standards for adipic acid oxidation chemistry. Yangtze River Delta chemical parks in Jiangsu province are absorbing rationalized capacity from shuttered inland facilities.
Germany
REACH registration requirements and the EU Green Deal's circularity mandates are redirecting formulation strategies toward bio-based and recycled-content intermediates. Ludwigshafen's integrated chemical complex anchors European supply security for adipic acid and caprolactam feedstocks. The Ruhr industrial corridor is retrofitting legacy assets with catalytic decomposition units to meet tightened N2O emissions standards.
United States
EPA Clean Air Act Title V permitting now mandates N2O catalytic decomposition units for adipic acid expansions, elevating greenfield investment thresholds. The Gulf Coast petrochemical corridor leverages cheap shale-derived benzene and cyclohexane feedstocks. Chocolate Bayou and Pensacola manufacturing assets dominate North American capacity for high-purity monomer grades serving automotive electrification programs.
India
The PLI scheme for advanced chemistry is attracting Reliance Industries and Indian Oil Corporation to evaluate caprolactam-adipic acid complexes for automotive polymer import substitution. BIS standards for engineering thermoplastics are tightening qualification barriers for electronics-grade compounds. Gujarat's Dahej and Mundra industrial zones are emerging as preferred locations for integrated aromatics-to-polymer investments.
Japan
METI's carbon neutrality roadmap is pressuring caprolactam producers to adopt bio-based feedstock pathways and chemical recycling technologies. The Chubu region around Nagoya maintains specialized capacity for ultra-high-purity grades serving semiconductor and automotive Tier-1 suppliers. Kyushu-based compounders are qualifying alternative heat-stabilizer packages to maintain OEM approval status amid REACH-driven reformulation mandates.
Polyamide Intermediate Chemicals Market Competitive Landscape
Capacity expansion dominates the current landscape as incumbents retrofit European assets with modular flow-chemistry skids and Gulf Coast producers leverage shale economics for greenfield adipic acid investments. The vendor base clusters around three strategic archetypes: integrated petrochemical majors with captive benzene supply, specialty compounders commanding formulation premiums, and regional distributors disintermediating traditional networks through digital marketplaces. M&A activity and strategic partnerships concentrate among compounders seeking guaranteed volume commitments from consolidating automotive Tier-1 buyers.
Within the integrated petrochemical tier, BASF SE and Ascend Performance Materials exemplify divergent geographic anchoring strategies for feedstock security. DuPont occupies a position in high-heat formulation specialization. DSM and Envalior represent the European specialty compounder archetype navigating REACH-driven reformulation cycles.
| Leading Market Players |
|---|
| BASF SE |
| DuPont |
| DSM |
| Ascend Performance Materials |
| Envalior |
| Arkema |
| Evonik Industries |
| INVISTA |
| EMS-CHEMIE HOLDING AG |
| Others |
Value Network & Pricing Analysis
Performance-grade certification divergence between automotive-specification compounds and standard industrial resins manifests in divergent margin architectures and procurement channel structures. ISCC PLUS mass-balance claims and REACH Article 33 compliance separate premium European compounders from commodity Asian suppliers, with certification overhead dictating direct OEM relationships versus distributor-mediated spot markets.
Pricing Analysis
Distributor margin compression in Southeast Asian hexamethylenediamine channels reflects Alibaba 1688 marketplace disintermediation. Three-tier pricing structure across premium, standard, and economy levels tracks UL 94 V-0 certification, glass-fiber loading percentage, and heat-stabilizer package sophistication. Cost compression in standard nylon 6 grades intensifies because mineral-filled polypropylene substitution erodes specification tolerance. Asian appliance manufacturers exhibit highest price sensitivity; German automotive Tier-1 buyers accept premium positioning for guaranteed volume commitments.
Supply Chain Analysis
Benzene-cyclohexane feedstock supply rests on Gulf Coast shale economics and Ludwigshafen integrated refinery-petrochemical complexes. China, Germany, and the United States concentrate adipic acid and caprolactam production capacity. Crude-linked aromatics, ammonia, and catalytic decomposition units constitute critical input dependencies. Single-source vulnerability concentrates in Shandong province caprolactam rationalizations. Distribution runs through regional distributor networks disintermediated by specialty chemical marketplaces for standard grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in bio-attributed intermediate premiums and automotive electrification qualification timelines. Continuous-flow reactor retrofits and chemical recycling feedstock certification represent the primary cost-down and premium-tier shift vectors.
For Market Incumbents: Anticipate nitrous oxide abatement capex escalation at EPA-permitted adipic acid expansions by accelerating catalytic decomposition unit deployment ahead of Title V enforcement waves. Consolidate formulation expertise through captive rheology and thermal analysis capabilities to compress OEM-mandated multi-year aging protocol execution. Backward integration into pyrolysis-derived caprolactam secures ISCC PLUS positioning against circularity-driven procurement shifts. For New Entrants and Emerging Players: India's PLI scheme for advanced chemistry opens a window for integrated caprolactam-adipic acid complexes serving automotive polymer import substitution. White-space targets include chemical recycling feedstock certification for European electronics supply chains and direct e-commerce monomer distribution for Southeast Asian compounding shops. The most penetrable segment is standard-grade hexamethylenediamine via marketplace platforms bypassing traditional distributor markups. For Investors and Strategic Acquirers: Consolidation pressure builds where automotive Tier-1 buyers reduce approved supplier lists from 6-8 compounders to 2-3 strategic partners per polymer grade. Long-term viability favors compounders with guaranteed volume commitments and mass-balance certification infrastructure. Acquisition target archetype: mid-cap European compounders navigating REACH-driven reformulation with established OEM approval status. The signal to watch is Stellantis and Volkswagen procurement consolidation velocity in powertrain applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive benzene-to-polymer chains in Yangtze River Delta chemical parks reduce feedstock cost volatility exposure. |
| Green Manufacturing Transition | Bio-based adipic acid pilot programs preempt EU Green Deal CBAM exposure on fossil-derived imports. |
| Long-term Supply Agreement | Guaranteed volume commitments from consolidating automotive Tier-1 buyers lock in specification-grade compound offtake. |
| Capacity Expansion | Modular flow-chemistry skids automate capacity creep without full grassroots construction timelines. |
| Joint Venture | Reliance Industries and Indian Oil Corporation partnerships capture PLI scheme incentives for domestic caprolactam production. |
Research Methodology
Direct dialogue with plant managers, procurement leads at downstream automotive OEMs, distribution channel partners, and technical R&D directors grounded qualitative findings. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA Clean Air Act permitting databases. Bottom-up and top-down triangulation cross-checked monomer capacity utilization against automotive electrification program pull-through estimates.
Bottom-up modeling segmented volume and value across grade tier, end-use industry, packaging format, and regional production hub dimensions. Top-down macroeconomic anchoring incorporated benzene-cyclohexane price volatility patterns and refinery turnaround schedules. CAGRs derived from regression analysis of historical automotive lightweighting penetration and projected electric vehicle battery pack housing specification adoption. Industry-specific inputs included OEM platform consolidation timelines and MEE enforcement intensity in Shandong and Jiangsu provinces.
Revisions become necessary when EPA Title V permitting delays, EU CBAM implementation scope changes, or provincial MEE enforcement intensity shifts materialize. Forecasts reflect documented assumptions on automotive electrification program cadence and circularity mandate propagation velocity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Tertiary Amines Market
Chemical Intermediates
Chemical Synthesizer Market
Chemical Intermediates
Refinery Process Chemicals Market
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
Fungal Staining Reagent Market
Chemical Intermediates
Global Etoricoxib Intermediate Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
Metal Alkyls Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Elemental Formula Market
Chemical Intermediates
Phosphate Chemical Reagents Market
Chemical Intermediates
Diethyl Phthalate Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Pigment Intermediates Market
Chemical Intermediates
Bromate Substitute Market