
 Valeryl Chloride Market | 2026-2036
Valeryl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Valeryl Chloride Market Analytics
Specialty chemical buyers is collapsing toward pharmaceutical intermediates as agrochemical offtake softens. BASF leverages its integrated C1-chemistry platform to secure backward integration into valeryl chloride feedstocks. Shandong Jiahong Chemical anchors regional supply through captive chlorination capacity in China's chemical corridor. CABB Chemicals differentiates via pharmaceutical-grade certification that commands premium positioning in regulated end-markets.
Valeryl chloride is an acyl chloride with the molecular formula C5H9ClO, produced through thionyl chloride-mediated chlorination of valeric acid or via phosgene routes, serving primarily as an acylation reagent and intermediate for pharmaceutical and agrochemical synthesis. Pharmaceutical Grade material captures the dominant margin pool due to stringent impurity thresholds and audit-intensive customer qualification processes. Intermediate applications within the Application dimension absorb the largest volume share as drug developers outsource late-stage custom synthesis steps. Bulk Containers in the Packaging Type category align with the concentration of demand among large-scale chemical manufacturers running continuous campaigns.
REACH registration requirements in Europe and FDA's ICH Q3D elemental impurity guidelines shape product specifications and testing burdens for exporters. China's MEE enforces wastewater discharge limits on chlorination facilities that elevate compliance capital for domestic producers. Buyers must monitor regulatory divergence between EMA's evolving nitrosamine guidance and EPA's TSCA Section 5 notification requirements for new chemical intermediates.
Market Dynamics
Pharmaceutical manufacturers are consolidating their supplier base around audit-capable producers, compressing the vendor landscape and elevating qualification barriers for mid-tier chlorination specialists.
Growth Catalysts
- ICH Q3D Elemental Impurity Guidelines:FDA's implementation of stricter metal contamination thresholds is forcing drug developers to source higher-purity acylation reagents, expanding the addressable market for certified-grade material.
- Custom Synthesis Outsourcing:European and North American pharmaceutical companies are divesting in-house chlorination capacity, redirecting volume toward specialized contract manufacturers with dedicated phosgene-handling infrastructure.
- Thionyl Chloride Process Optimization:Advances in catalytic chlorination efficiency are reducing yield loss during valeric acid conversion, lowering unit costs for research-grade batches.
Market Restraints
- Phosgene Feedstock Volatility:Concentrated production of phosgene precursors among three major chemical conglomerates creates input cost instability for non-integrated acyl chloride manufacturers.
- Jiangsu Province Supply Concentration:China's environmental enforcement under MEE oversight has shuttered numerous small chlorination facilities, tightening regional capacity and extending lead times for export orders.
- Isatoic Anhydride Substitution:Alternative acylation chemistries are displacing valeryl chloride in certain agrochemical intermediate applications, eroding volume in the historically largest end-use segment.
Strategic Opportunities
- India's CDSCO Accelerated Approval Pathway:Domestic pharmaceutical formulators are qualifying new intermediate suppliers under streamlined regulatory timelines, creating entry points for compliant exporters.
- Continuous Flow Chlorination:Adoption of microreactor technology is enabling on-demand production at customer sites, bypassing hazardous material shipping constraints for high-value synthesis campaigns.
- South Korea MFDS GMP Harmonization:Alignment with international pharmaceutical manufacturing standards is opening contract manufacturing opportunities for acyl chloride derivatives in the Korean market.
Industry Challenges
- Phosgene Safety Certification:Operators face extended timelines obtaining process safety management approvals for chlorination facilities, delaying capacity expansion projects by 18-24 months.
- REACH Data Gap Bridging:ECHA's evolving requirements for intermediate registration are forcing exporters to commission costly toxicological studies without guaranteed volume commitments from European buyers.
- Legacy Batch Reactor Integration:Pharmaceutical manufacturers struggle to incorporate continuous chlorination outputs into existing multi-step synthesis workflows optimized for discrete batch inputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valeryl Chloride Market |
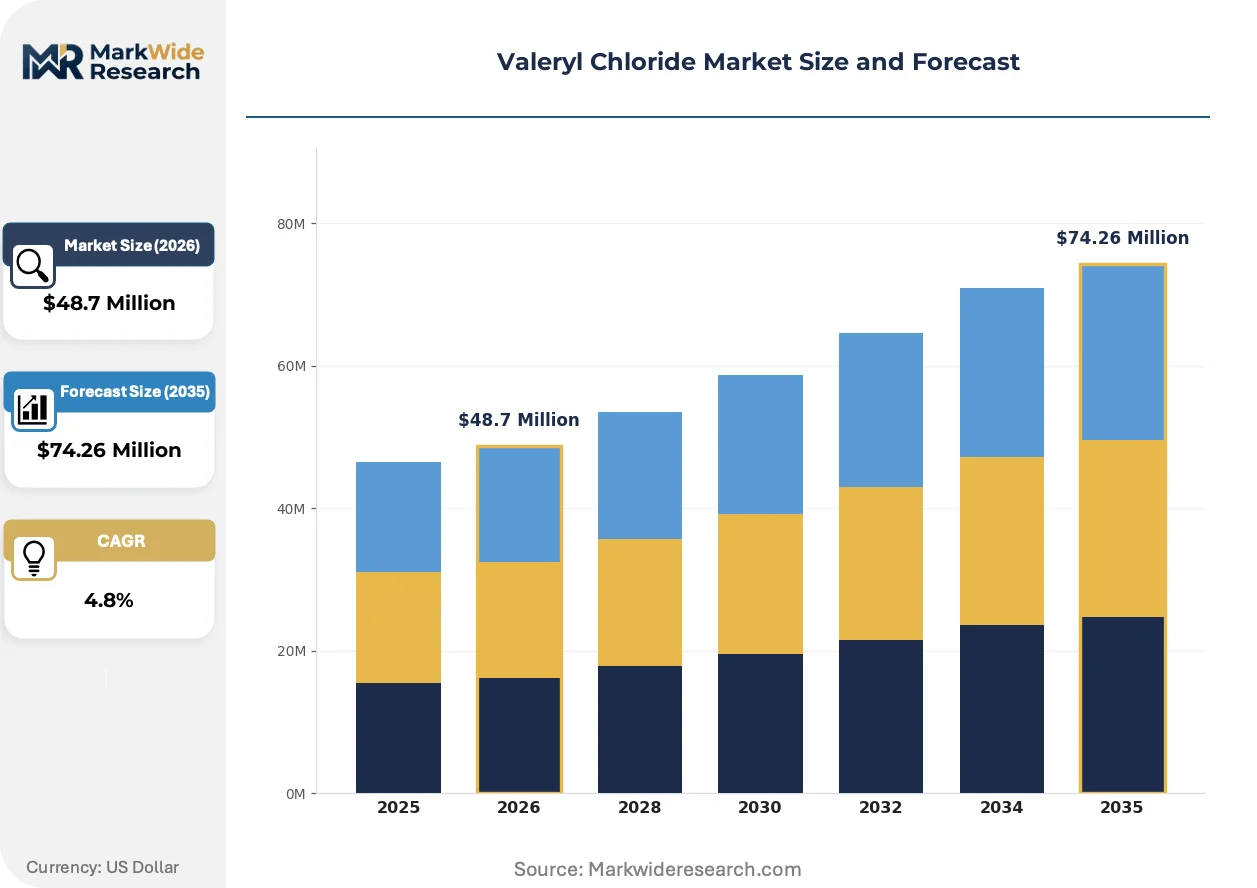
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $74.26 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Research Grade, Laboratory Grade Application: Syntheses, Reagent, Intermediate, Solvent End User: Pharmaceuticals, Chemicals, Academia, Research Institutions Packaging Type: Drums, Bottles, Tanks, Bulk Containers |
| Companies Covered | Leonid Chemicals, Shandong Jiahong Chemical, BASF, Lianfeng Chemicals, Hangzhou Fanda Chemical, CABB Chemicals, Jinnan Fufang Chemical, Shiva Pharmachem, Jiangsu Baichang Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valeryl Chloride Market Evolving Landscape
Process intensification and regulatory harmonization are compressing the traditional boundaries between bulk chemical production and pharmaceutical-grade finishing, reshaping competitive requirements across the acyl chloride value chain.
Microreactor-based continuous chlorination systems are miniaturizing production footprints while enabling precise temperature control during exothermic thionyl chloride reactions. Contract research organizations in Germany and Switzerland are adopting these skid-mounted units for kilogram-scale campaigns. The technology is miniaturizing the minimum efficient scale for profitable valeryl chloride production, allowing regional players to challenge centralized bulk manufacturers.
REACH's 2023 update to intermediate substance definitions is narrowing the exemption window for site-limited intermediates, compelling non-EU exporters to register or appoint only representatives. German and Dutch chemical distributors are absorbing registration costs to secure exclusive supply relationships. Small-batch pharmaceutical intermediate suppliers face disproportionate compliance burdens relative to their shipment volumes.
Long-term offtake agreements are replacing spot market purchasing among top-20 pharmaceutical developers, compressing supplier switching flexibility. Merck KGaA and Lonza have pioneered five-year framework contracts with embedded price adjustment mechanisms. This behavioral shift is most pronounced in Basel and Boston corridor markets where synthesis outsourcing has matured.
Valeryl Chloride Market Segmentation
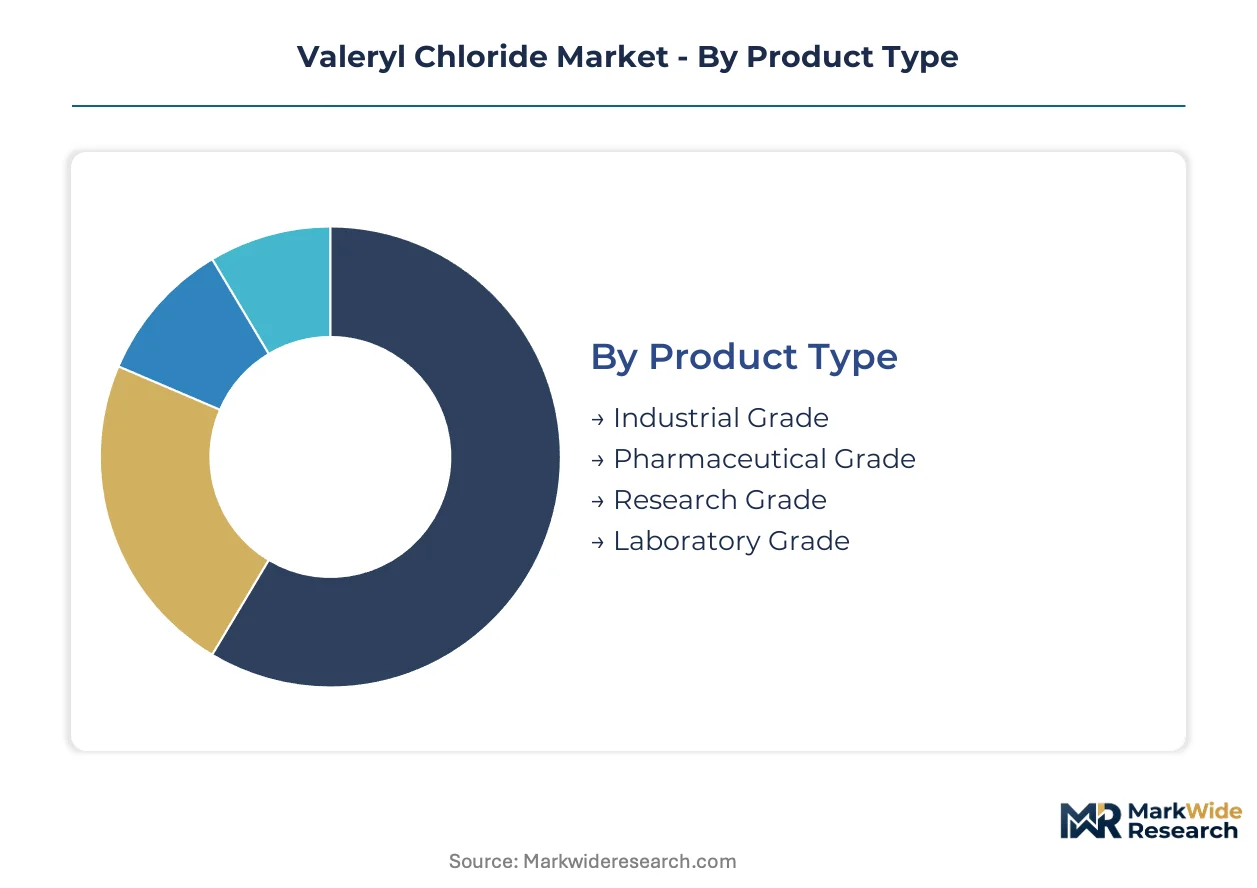
Segmentation in the valeryl chloride market reflects divergent purity requirements and regulatory burdens across end-use verticals. Pharmaceutical-grade specifications command fundamentally different supply chain configurations than industrial applications, with certification tiers determining geographic reach and customer qualification intensity.
Product Type:
Domestic consumption in China concentrates in industrial and laboratory grades serving regional chemical processors, while pharmaceutical and research grades flow predominantly toward export markets in Europe and North America under stringent audit protocols.
- Pharmaceutical Grade:Material meeting ICH Q3D elemental impurity thresholds and FDA audit requirements. Demand concentrates among European and North American drug developers outsourcing late-stage custom synthesis to contract manufacturers with dedicated phosgene-handling infrastructure.
- Research Grade:High-purity batches optimized for kilogram-scale pharmaceutical intermediate development. Procurement is expanding at biotechnology clusters in Basel, Boston, and Shanghai as developers accelerate candidate molecule screening.
- Industrial Grade:Standard purity material for bulk agrochemical and general chemical synthesis applications.
- Laboratory Grade:Small-volume specifications serving analytical and educational chemistry requirements.
Pharmaceutical Grade holds the largest share; momentum sits with Research Grade.
Application:
Cost tier differentiation separates commodity synthesis applications from premium reagent positioning, with intermediate applications absorbing the highest absolute volumes through contract manufacturing channels.
- Intermediate:The dominant volume category encompassing late-stage pharmaceutical and agrochemical synthesis steps. European and North American drug developers are divesting in-house chlorination capacity, redirecting volume toward specialized contract manufacturers.
- Reagent:Acylation chemistry applications requiring precise stoichiometric control. Demand clusters at research-intensive pharmaceutical sites in Switzerland and Massachusetts where high-throughput experimentation protocols consume consistent reagent volumes.
- Syntheses:Bulk chemical transformation applications serving commodity chemical manufacturers.
- Solvent:Niche dissolution applications in specialized extraction and purification workflows.
Intermediate applications command the dominant volume position; Reagent applications are gaining share fastest in high-value synthesis corridors.
End User:
Customer type fragmentation reflects fundamentally different procurement behaviors, with pharmaceutical buyers consolidating around audit-capable producers while academic institutions remain dispersed across numerous small suppliers.
- Pharmaceuticals:The primary revenue pool encompassing innovator drug companies and contract development organizations. Merck KGaA and Lonza have pioneered five-year framework contracts with embedded price adjustment mechanisms, compressing supplier switching flexibility.
- Research Institutions:Fragmented demand across government laboratories and independent research centers. Procurement concentrates at German and Swiss contract research organizations adopting microreactor-based continuous chlorination systems for kilogram-scale campaigns.
- Chemicals:Commodity chemical manufacturers running continuous production campaigns.
- Academia:Educational and fundamental research applications with irregular purchase patterns.
Pharmaceuticals holds the largest share; Research Institutions show the steepest expansion trajectory.
Packaging Type:
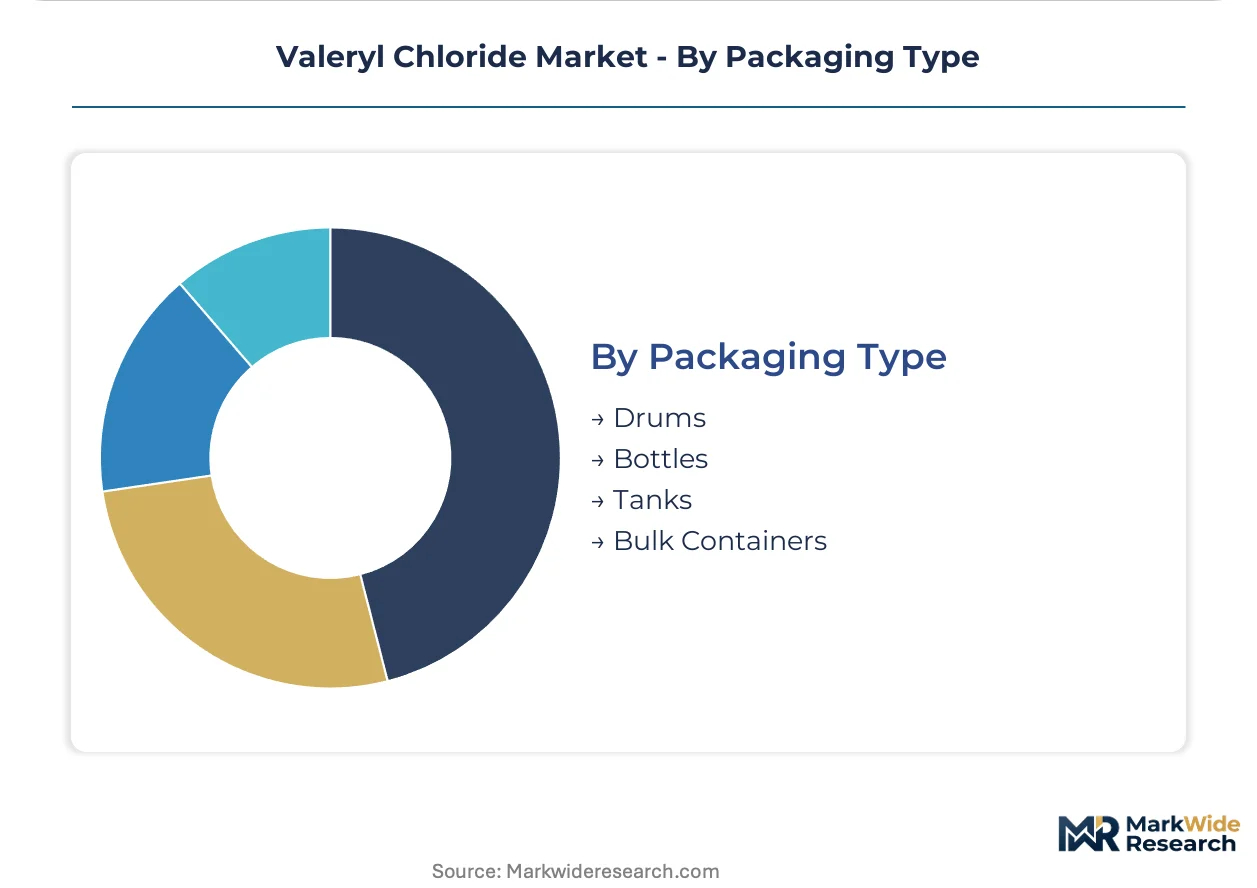
Volume scale determines packaging configuration, with large-scale chemical manufacturers driving bulk container demand while research applications sustain drum and bottle formats.
- Bulk Containers:The dominant format for large-scale chemical manufacturers running continuous campaigns. Shandong Jiahong Chemical anchors regional supply through captive chlorination capacity serving this segment.
- Drums:Mid-scale shipments for multi-step synthesis workflows. Pharmaceutical manufacturers struggle to incorporate continuous chlorination outputs into existing batch-optimized workflows, sustaining drum-format demand.
- Bottles:Small-volume research and laboratory applications.
- Tanks:Dedicated tanker shipments for integrated chemical complexes with direct pipeline connections.
Bulk Containers holds the largest share; momentum sits with Drums as batch-optimized workflows persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports valeryl chloride predominantly to European pharmaceutical developers and North American contract manufacturers, with BASF's Ludwigshafen complex and Lonza's Basel operations serving as major demand anchors for high-purity material.
China
Domestic chlorination capacity concentrates in Jiangsu and Shandong provinces under tightening MEE wastewater discharge enforcement. The dual carbon goals policy framework is accelerating facility consolidation toward compliant producers with captive environmental treatment infrastructure. Shandong Jiahong Chemical anchors regional supply through integrated chlorination assets serving both export and domestic intermediate demand.
Germany
Specialty chemical demand from Ludwigshafen and Leverkusen pharmaceutical clusters sustains import volumes for GMP-certified acylation reagents. ECHA's REACH intermediate substance definition updates are narrowing exemption windows and compelling registration investments from Asian exporters. Bavarian contract research organizations are adopting microreactor-based continuous chlorination systems for kilogram-scale pharmaceutical campaigns.
United States
FDA's ICH Q3D elemental impurity guidelines are forcing drug developers in Massachusetts and New Jersey to source higher-purity acylation reagents from audited suppliers. EPA TSCA Section 5 notification requirements for new chemical intermediates create regulatory friction for novel synthesis route adoption. Boston corridor pharmaceutical developers are consolidating supplier bases around audit-capable producers with dedicated phosgene-handling infrastructure.
India
Domestic pharmaceutical formulators in Maharashtra and Gujarat are qualifying new intermediate suppliers under CDSCO accelerated approval pathways. The PLI scheme for active pharmaceutical ingredients is incentivizing backward integration into acyl chloride production among large generic manufacturers. Hyderabad and Ahmedabad synthesis clusters are expanding procurement of research-grade material for late-stage custom synthesis outsourcing.
Switzerland
Swissmedic GMP harmonization with international standards sustains premium positioning for pharmaceutical-grade material in Basel and Zurich pharmaceutical corridors. Lonza's five-year framework contracts with embedded price adjustment mechanisms are compressing supplier switching flexibility among innovator drug companies. Contract research organizations in Basel are pioneering continuous flow chlorination adoption for high-value synthesis campaigns.
Valeryl Chloride Market Competitive Landscape
Player mix skews toward integrated chlorination specialists with captive phosgene infrastructure and regional chemical conglomerates with backward integration into valeric acid feedstocks. Market structure exhibits tiered concentration, with three to four audit-capable producers commanding pharmaceutical-grade margins while industrial-grade volume fragments across numerous regional operators. Strategic archetypes include integrated C1-chemistry platforms, captive chlorination specialists, and pharmaceutical-grade certification-focused contract manufacturers. Dominant competitive moves center on long-term offtake agreement negotiations with top-20 pharmaceutical developers and continuous flow technology licensing for microreactor-based production footprints.
Among China-based chlorination specialists, Shandong Jiahong Chemical and Lianfeng Chemicals occupy positions within the industrial-grade volume tier, leveraging proximity to Shandong province's chemical corridor infrastructure. BASF represents the integrated C1-chemistry platform archetype, with its Ludwigshafen complex exemplifying backward integration into acyl chloride feedstock control. CABB Chemicals anchors the pharmaceutical-grade certification tier, with its positioning reflecting premium market access through regulated end-market qualifications.
| Leading Market Players |
|---|
| Leonid Chemicals |
| Shandong Jiahong Chemical |
| BASF |
| Lianfeng Chemicals |
| Hangzhou Fanda Chemical |
| CABB Chemicals |
| Jinnan Fufang Chemical |
| Shiva Pharmachem |
| Jiangsu Baichang Pharmaceutical |
| Others |
Value Network & Pricing Analysis
Extended lead times of 8-12 weeks for pharmaceutical-grade material now concentrate pricing power among Jiangsu and Shandong producers with MEE-compliant chlorination infrastructure, compressing margin capture for non-integrated contract manufacturers dependent on spot thionyl chloride procurement.
Pricing Analysis
Batch-process versus continuous-flow versus on-site microreactor generation defines the current pricing architecture. Three-tier pricing structure across pharmaceutical, research, and industrial grades separates audit-intensive certified material from standard purity tiers. Cost compression in industrial-grade segments is intensifying because isatoic anhydride substitution erodes volume in agrochemical applications. Academic and small research institution buyers exhibit highest price sensitivity, while pharmaceutical contract manufacturers prioritize qualification stability over unit cost.
Supply Chain Analysis
Phosgene precursor availability from Ludwigshafen, Caojing, and Yeosu chemical complexes underwrites global acyl chloride output stability. Production draws from valeric acid feedstocks, thionyl chloride reagents, and catalytic chlorination systems. Single-source vulnerability concentrates in phosgene handling certification, where three conglomerates control precursor supply. Distribution runs through bulk container shipments to integrated chemical manufacturers and drum-format deliveries to batch-optimized pharmaceutical synthesis workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Valeryl chloride procurement is consolidating around platform-certified suppliers as REACH registration data and FDA audit trails become interoperable currency across European and North American pharmaceutical ecosystems.
For Market Incumbents: Shield pharmaceutical-grade margin pools by accelerating captive chlorination capacity additions in MEE-compliant Shandong corridors before environmental enforcement tightens further. Secure backward integration into valeric acid feedstocks to insulate against thionyl chloride volatility. Prioritize continuous flow technology licensing to capture microreactor adoption cycles among Basel and Boston contract research organizations. For New Entrants and Emerging Players: Kilogram-scale research-grade supply gaps in Hyderabad and Ahmedabad synthesis clusters offer entry points where incumbent certification burdens exceed shipment economics. Target CDSCO accelerated approval pathway qualifications for domestic Indian pharmaceutical formulators. Lead with phosgene-free thionyl chloride process offerings to bypass 18-24 month safety certification timelines blocking conventional entrants. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat specialty chemical play because intermediate registration requirements and audit-intensive customer qualification processes compound competitive barriers over time. Acquisition targets should display integrated chlorination assets with existing FDA or EMA site certifications. Monitor ECHA intermediate substance definition enforcement intensity as the signal for registration cost inflection and vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Valeric Acid | BASF's Ludwigshafen complex exemplifies feedstock control insulating against thionyl chloride volatility. |
| Continuous Flow Chlorination Adoption | Microreactor technology licensing enables kilogram-scale regional production bypassing hazardous material shipping constraints. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA site audits command premium positioning in regulated end-markets with embedded price adjustment mechanisms. |
| Long-term Supply Agreement Negotiation | Merck KGaA and Lonza framework contracts compress supplier switching flexibility among top-20 pharmaceutical developers. |
| Regional Capacity Expansion in MEE-Compliant Zones | Shandong Jiahong Chemical's captive environmental treatment infrastructure anchors export supply under tightening discharge limits. |
Research Methodology
A spread of perspectives from plant managers at chlorination facilities, procurement leads at pharmaceutical contract manufacturers, distribution channel partners in European chemical corridors, and technical R&D directors at acylation reagent specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from disclosed chemical producers, and MEE environmental enforcement records enabled bottom-up volume triangulation against top-down market sizing.
Segmentation dimensions modeled span grade tier, end-use industry, packaging format, and regional production hub across the projection horizon. CAGRs were derived from growth driver elasticity analysis against baseline pharmaceutical outsourcing trends and agrochemical substitution patterns. Forecast inputs incorporated ICH Q3D implementation timelines, REACH intermediate registration cost trajectories, and CDSCO approval pathway throughput assumptions.
Underlying assumptions cover sustained pharmaceutical custom synthesis outsourcing, stable phosgene precursor supply concentration, and MEE enforcement continuity, with deviation risk concentrated in alternative acylation chemistry displacement and regional environmental policy reversals. Practitioners should keep alternative scenarios live as nitrosamine guidance evolution and TSCA Section 5 notification requirements reshape intermediate qualification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Benzophenone (Oxybenzone) Market
Chemicals
1, 4 Butanediol Market
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
5 Dinitroaniline Market
Chemicals
Chemical Distribution Market
Chemicals
Global E Series Glycol Ether Market
Chemicals
Etidronic Acid Market
Chemicals
4-Methyl-2-Pentanone Market
Chemicals
1-Methylimidazole Market
Chemicals
Peracetic Acid Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
Methanol Market
Chemicals
Naturally Derived Fatty Alcohol Market