
 Ferrous Oxalate Market | 2026-2036
Ferrous Oxalate Market Size, Share, and Industry Trends Forecast 2026-2036
Ferrous Oxalate Market Analysis
Pharmaceutical intermediate demand is realigning the ferrous oxalate value chain as battery-grade applications expand. Jinan Haohua Industry Co., Ltd. leverages its Shandong manufacturing base to serve both chemical synthesis and pharmaceutical clients. Loba Chemie Pvt. Ltd. specializes in high-purity laboratory and reagent-grade formulations for institutional buyers. Spectrum Chemical Manufacturing Corp. controls North American distribution channels for USP and ACS-certified grades.
Ferrous oxalate (FeC₂O₄) is an iron(II) salt of oxalic acid, typically appearing as a pale yellow crystalline powder with applications requiring precise stoichiometry in redox reactions and metal coordination chemistry. The compound serves primarily as a precursor in iron oxide nanoparticle synthesis, cathode material preparation for energy storage, and controlled-release iron fortification systems. High Purity grades command premium positioning in pharmaceutical intermediates and electronic material applications where trace metal specifications determine batch acceptance. Technical Grade volumes dominate tonnage flows into pigment manufacturing and agricultural micronutrient formulations, though margin pools remain thinner in these commoditized segments.
REACH registration requirements in Europe and China's MEE emissions standards are elevating compliance costs for oxalate derivative producers while filtering out sub-scale operators. The US EPA and FDA jointly govern ferrous oxalate use in food additives and pharmaceutical applications through distinct purity and labeling mandates. Stakeholders must monitor evolving cathode chemistry roadmaps, as iron-based alternatives to cobalt and nickel formulations could either amplify or redirect ferrous oxalate demand depending on commercialization trajectories in solid-state and lithium-iron-phosphate battery platforms.
Market Dynamics
Lithium-ion battery cathode chemistry roadmaps are redirecting ferrous oxalate demand from pigment and pharmaceutical intermediates toward energy storage precursors, compressing legacy supply allocation models.
Growth Catalysts
- China's dual carbon goals:MEE emissions standards are forcing iron salt producers to upgrade purification capabilities, filtering out sub-scale competitors and consolidating supply among compliant manufacturers.
- LFP cathode expansion:Lithium-iron-phosphate battery platforms are absorbing technical-grade ferrous oxalate volumes previously directed toward pigment applications.
- Hubei province clustering:Multiple manufacturers concentrate near phosphate and iron ore supply chains, reducing logistics costs for battery material buyers.
Market Restraints
- Oxalic acid price volatility:Feedstock cost swings from petrochemical and biomass routes compress margin predictability for derivative producers.
- REACH registration burden:ECHA compliance costs for iron salt derivatives disproportionately burden European mid-scale operators versus Asian competitors.
- Iron oxide nanoparticle substitution:Direct thermal decomposition routes are bypassing ferrous oxalate intermediates in some magnetic material applications.
Strategic Opportunities
- Solid-state battery cathodes:Iron-based alternatives to cobalt and nickel formulations could amplify ferrous oxalate demand if sulfide electrolyte platforms commercialize.
- Controlled-release fortification:Micronutrient delivery systems for staple food processing represent underpenetrated demand in Sub-Saharan African markets.
- India's PLI scheme:Domestic cell manufacturing incentives are attracting precursor chemical investments near Gujarat and Tamil Nadu battery hubs.
Industry Challenges
- High-purity certification timelines:USP and ACS grade approvals require 18-24 month validation cycles that delay customer qualification.
- Redox chemistry expertise scarcity:Specialized process engineers capable of maintaining Fe(II) oxidation state control during synthesis command premium compensation.
- Legacy ERP integration:Batch tracking systems for REACH and FDA compliance must interface with decades-old manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferrous Oxalate Market |
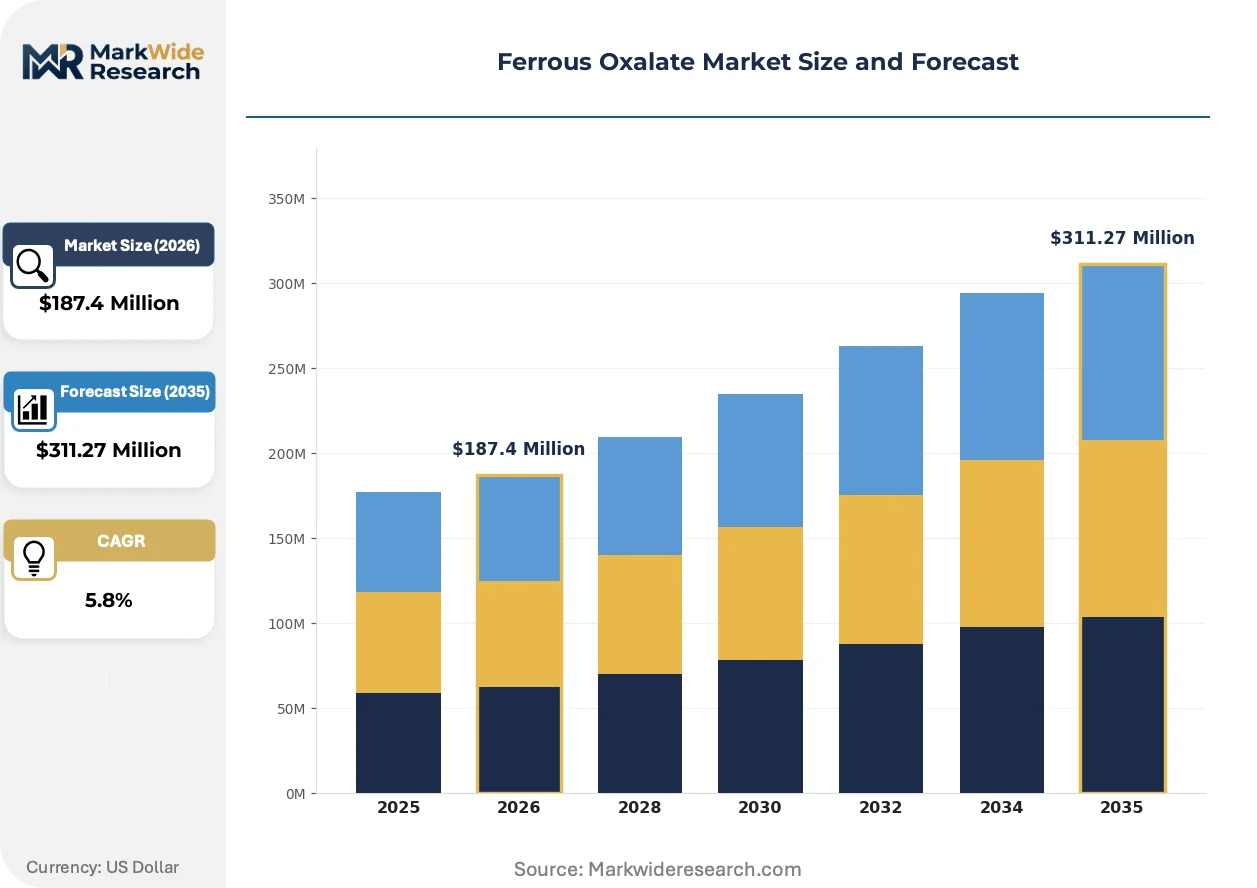
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Technical Grade, Food Grade, Pharmaceutical Grade Application: Chemical Synthesis, Pharmaceutical Intermediates, Food Additives, Pigments End User: Pharmaceuticals, Chemicals, Food Industry, Agriculture Packaging Type: Bags, Drums, Bulk Containers, Pails |
| Companies Covered | MP Biomedicals, LLC, Jinan Haohua Industry Co., Ltd., Santa Cruz Biotechnology, Inc., Hubei Wanrun New Energy Technology Development, Loba Chemie Pvt. Ltd., Chemada Fine Chemicals, Spectrum Chemical Manufacturing Corp., Luotian Yongfei Chemical, KCI Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferrous Oxalate Market Emerging Trajectories
Continuous flow reactor technology is displacing batch synthesis across iron salt production, enabling tighter stoichiometric control and reducing oxidation degradation during ferrous oxalate crystallization.
Solvent-free mechanochemical synthesis is integrating into pharmaceutical-grade ferrous oxalate manufacturing. European API producers are adopting ball-milling routes to eliminate aqueous waste streams. This technology is compressing environmental compliance costs while maintaining crystallinity specifications for iron oxide nanoparticle precursors.
REACH authorization requirements for oxalic acid derivatives are tightening trace metal specifications across the value chain. ECHA's 2023 update to Annex XIV candidate list entries is forcing reformulation of technical-grade products. Battery material suppliers in Germany and Belgium are accelerating substitution studies to preempt supply disruption.
Long-term offtake contracting is displacing spot purchasing among cathode material producers. Tier-1 battery manufacturers in South Korea and Japan are locking multi-year ferrous oxalate supply agreements directly with Hubei and Shandong producers. This channel consolidation is squeezing distributor margins while securing volume commitments for capacity expansion financing.
Ferrous Oxalate Market Segmentation
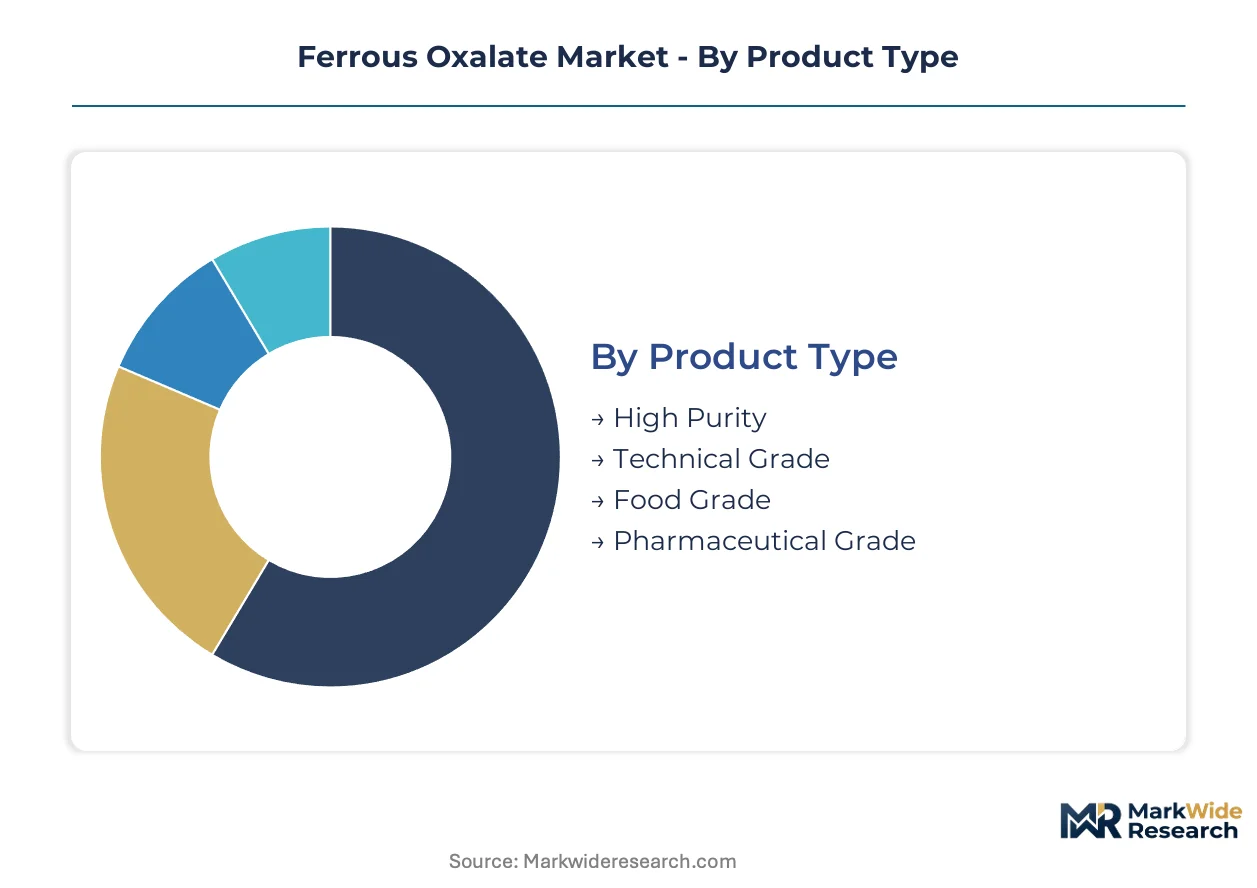
Ferrous oxalate segmentation reflects divergent purity requirements across battery cathodes, pharmaceutical APIs, and agricultural formulations. Grade specifications determine batch acceptance criteria, pricing tiers, and regulatory compliance pathways for manufacturers.
Product Type:
Integration depth varies sharply: High Purity and Pharmaceutical Grade segments serve embedded systems within complex manufacturing chains, while Technical and Food Grade products often function as standalone inputs with simpler downstream processing.
- High Purity:Iron(II) salt with trace metal specifications below 10 ppm total impurities, produced through multi-stage recrystallization and controlled-atmosphere drying. Battery cathode precursor demand in Hubei province absorbs volumes as LFP chemistry scales, though 18-24 month USP/ACS certification timelines delay customer qualification.
- Technical Grade:Standard purity formulations with broader impurity tolerances, typically 95-98% FeC₂O₄ content. Pigment manufacturers in Shandong province dominate procurement, but MEE emissions standards are forcing purification upgrades that blur grade boundaries.
- Food Grade:Meets FSSAI and FDA iron fortification specifications for staple food processing.
- Pharmaceutical Grade:USP-certified batches for API synthesis and controlled-release iron supplements.
Technical Grade leads volumes today; High Purity is gaining share fastest.
Application:
Cost tier stratification separates commodity pigment applications from premium pharmaceutical and energy storage precursors.
- Chemical Synthesis:Precursor for iron oxide nanoparticles, magnetic materials, and metal-organic frameworks. Direct thermal decomposition routes in Japan and South Korea are bypassing ferrous oxalate intermediates in some magnetic material segments.
- Pharmaceutical Intermediates:Controlled-release iron fortification systems and API synthesis. European producers adopt solvent-free mechanochemical synthesis to eliminate aqueous waste streams while maintaining crystallinity specifications.
- Food Additives:Micronutrient delivery for flour and cereal fortification.
- Pigments:Iron oxide colorant production for coatings and construction materials.
Chemical Synthesis anchors current demand; Pharmaceutical Intermediates is climbing the fastest.
End User:
Customer type determines procurement patterns: institutional buyers lock multi-year offtake agreements while spot purchasing persists among commodity processors.
- Pharmaceuticals:API manufacturers and nutraceutical formulators requiring USP/ACS certified grades. Tier-1 battery manufacturers in South Korea and Japan are locking multi-year supply agreements directly with producers, squeezing distributor margins.
- Chemicals:Specialty and commodity chemical producers serving pigment, catalyst, and materials science applications.
- Food Industry:Millers and processors fortifying staple foods for Sub-Saharan African and South Asian markets.
- Agriculture:Micronutrient formulations for soil amendment and foliar feeding.
Chemicals leads volumes today; Pharmaceuticals is expanding most quickly.
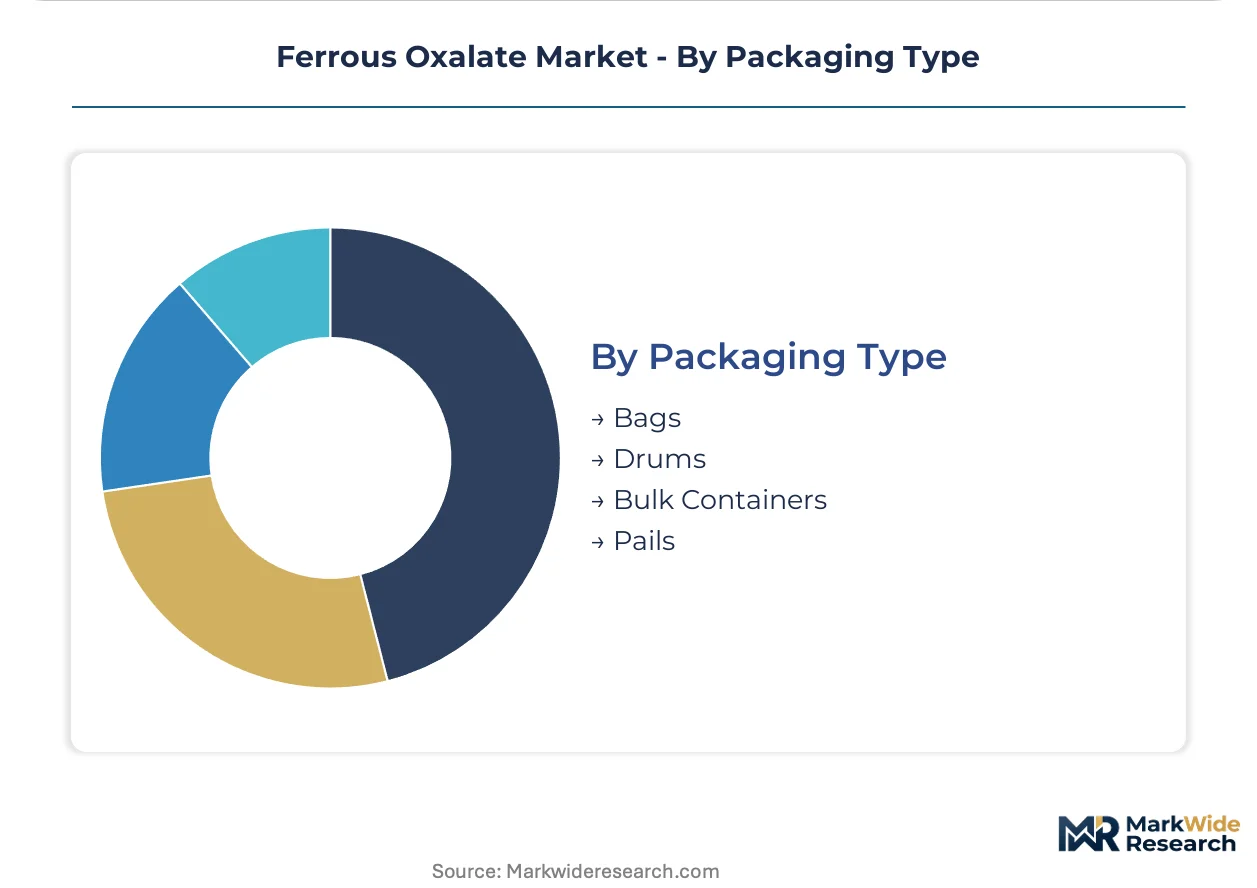
Packaging Type:
Supply concentration near Hubei phosphate corridors favors bulk formats, while pharmaceutical and food-grade specifications require sealed, contamination-resistant containers.
- Bags:Multi-layer paper or woven polypropylene for Technical Grade pigment shipments.
- Drums:Steel or fiber containers for mid-volume pharmaceutical and chemical synthesis orders.
- Bulk Containers:ISO tanks and flexible intermediate bulk containers for cathode material producers clustering near Hubei manufacturing bases.
- Pails:Sealed plastic or steel containers for high-purity laboratory and reagent-grade formulations.
Bulk Containers lead volumes today; Pails is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing ferrous oxalate production capacity toward jurisdictions with streamlined chemical registration frameworks, compressing European manufacturing share as Asian producers capture battery precursor demand.
China
Hubei province hosts the densest concentration of ferrous oxalate manufacturers, with producers clustering near phosphate mining corridors to serve lithium-iron-phosphate cathode supply chains. MEE emissions standards are forcing purification upgrades that filter sub-scale operators while consolidating output among compliant facilities. Shandong-based manufacturers in Jinan and surrounding chemical parks are diversifying across pharmaceutical intermediate and battery-grade specifications.
Germany
ECHA REACH registration requirements impose disproportionate compliance burdens on mid-scale iron salt derivative producers versus Asian competitors. Battery material suppliers in Belgium and the Netherlands are accelerating substitution studies to preempt supply disruption from Annex XIV candidate list updates. Industrial chemical production concentrates in the North Rhine-Westphalia and Bavaria regions, where specialty manufacturers serve pharmaceutical and electronic material applications.
United States
FDA and EPA joint governance of ferrous oxalate in food additives and pharmaceutical applications creates distinct purity and labeling mandates that delay market entry. Spectrum Chemical Manufacturing Corp. anchors North American distribution for USP and ACS-certified grades. The absence of domestic LFP cathode manufacturing limits battery-grade demand, redirecting procurement toward pigment and chemical synthesis applications.
India
PLI scheme incentives for domestic cell manufacturing are attracting precursor chemical investments near Gujarat and Tamil Nadu battery hubs. Loba Chemie Pvt. Ltd. specializes in high-purity laboratory and reagent-grade formulations for institutional buyers. FSSAI iron fortification specifications for staple food processing represent underpenetrated demand in Sub-Saharan African export markets served through Indian chemical ports.
South Korea
Tier-1 battery manufacturers are locking multi-year ferrous oxalate supply agreements directly with Chinese producers, bypassing distributor channels. MFDS pharmaceutical regulations create parallel compliance pathways for API-grade material imports. The concentration of cathode material producers in the Busan-Ulsan industrial corridor drives bulk procurement patterns for technical-grade precursors.
Ferrous Oxalate Market Vendor Landscape
Long-term offtake contracting dominates the current landscape as cathode material producers displace spot purchasing with multi-year supply agreements. The vendor base stratifies across three tiers: multinational chemical distributors controlling certification-heavy pharmaceutical channels, regional Chinese manufacturers capturing battery-grade volume, and specialty laboratory suppliers serving institutional research markets. Strategic archetypes include backward-integrated phosphate producers, purity-focused pharmaceutical intermediates specialists, and diversified industrial chemical conglomerates. Capacity expansion in Hubei and Shandong provinces and direct supplier-manufacturer partnerships constitute the dominant competitive moves.
Among China-based producers, Jinan Haohua Industry Co., Ltd. and Hubei Wanrun New Energy Technology Development exemplify the regional manufacturing archetype serving dual chemical synthesis and energy storage demand. Spectrum Chemical Manufacturing Corp. occupies a position within the North American distribution tier for certified-grade formulations. Loba Chemie Pvt. Ltd. represents the laboratory and reagent-grade specialization segment anchored in Indian pharmaceutical supply chains.
| Leading Market Players |
|---|
| MP Biomedicals, LLC |
| Jinan Haohua Industry Co., Ltd. |
| Santa Cruz Biotechnology, Inc. |
| Hubei Wanrun New Energy Technology Development |
| Loba Chemie Pvt. Ltd. |
| Chemada Fine Chemicals |
| Spectrum Chemical Manufacturing Corp. |
| Luotian Yongfei Chemical |
| KCI Limited |
| Others |
Supply Flow & Price Mechanics
Continuous flow reactor adoption across Hubei and Shandong manufacturing corridors is compressing unit production costs while concentrating output among capital-rich operators capable of financing purification upgrades. This technology transition simultaneously erodes batch-process margins and locks in supply advantages for early adopters serving battery cathode and pharmaceutical precursor demand.
Pricing Analysis
Distributor margins in ferrous oxalate distribution are compressing as Tier-1 battery manufacturers in South Korea and Japan negotiate direct long-term offtake agreements with Hubei producers. Three-tier pricing structure across high-purity, technical, and food-grade levels separates USP-certified pharmaceutical batches from commodity pigment inputs. Cost compression in technical-grade segments is intensifying because MEE emissions upgrades force sub-scale exits. Pigment manufacturers in Shandong province exhibit highest price sensitivity; API producers accept premium positioning for oxidation-state-controlled batches.
Supply Chain Analysis
Refurbishment and requalification of spent oxalic acid streams remains underdeveloped across iron salt production, though European API producers pilot solvent-free mechanochemical routes to eliminate aqueous waste. Supply concentrates in China, South Korea, and Germany, with Hubei province anchoring cathode precursor output. Feedstock dependencies center on oxalic acid from petrochemical and biomass routes, iron ore concentrates, and phosphate rock. Single-source vulnerability runs through Hubei's phosphate-iron ore corridor. Distribution runs through bulk ISO tank shipments for battery material buyers and sealed drum channels for pharmaceutical-grade formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ferrous oxalate functions as a stable compounder anchored by lithium-ion battery cathode chemistry roadmaps that lock in decade-long precursor demand. Battery-grade purity requirements and REACH compliance barriers protect incumbent positioning while filtering speculative entrants.
For Market Incumbents: Acquire controlled-atmosphere drying and multi-stage recrystallization assets to defend high-purity positioning against direct thermal decomposition substitutes. Lock multi-year offtake agreements with Busan-Ulsan cathode producers before India's PLI scheme matures domestic supply. Capacity expansion in Shandong chemical parks captures pharmaceutical intermediate demand migrating from European REACH-burdened competitors. For New Entrants and Emerging Players: Laboratory distributors represent the most accessible channel partnership for reagent-grade market entry without competing against Hubei's bulk cost structure. White-space targets include Sub-Saharan African food fortification markets served through Indian chemical ports and solid-state battery sulfide electrolyte precursor development. Position around FSSAI-certified iron fortification specifications for flour and cereal processors in underpenetrated African export corridors. For Investors and Strategic Acquirers: Valuations sit cheapest among technical-grade pigment specialists facing MEE-forced consolidation. Five-to-ten-year viability favors backward-integrated phosphate producers with captive iron ore access and existing purification infrastructure. Monitor ECHA Annex XIV candidate list updates for oxalic acid derivative authorization triggers that would accelerate European supply substitution toward Asian producers.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Hubei province additions serve lithium-iron-phosphate cathode demand from South Korean battery manufacturers. |
| Backward Integration | Captive oxalic acid production from biomass routes insulates margin from petrochemical feedstock volatility. |
| Long-term Supply Agreement | Direct Tier-1 battery manufacturer contracts displace distributor channels and secure expansion financing. |
| Green Manufacturing Transition | Solvent-free mechanochemical synthesis eliminates aqueous waste streams for European API producers. |
| Joint Venture | India PLI-aligned partnerships near Gujarat battery hubs localize precursor supply for domestic cell manufacturing. |
Methodological Framework
Direct dialogue with plant managers at Hubei and Shandong manufacturing facilities, procurement leads at South Korean cathode material producers, pharmaceutical API synthesis directors, and distribution channel partners in North America and Europe grounded qualitative assessment. Secondary validation drew from customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings for listed chemical conglomerates, and ECHA REACH registration databases. Bottom-up volume builds across grade tiers and application segments triangulated against top-down demand estimates from battery chemistry roadmaps and pharmaceutical intermediate consumption patterns.
Bottom-up modeling segmented the market across high-purity, technical, food-grade, and pharmaceutical-grade tiers; chemical synthesis, pharmaceutical intermediate, food additive, and pigment applications; and bulk container, drum, bag, and pail packaging formats. Value projections incorporated regional production cost differentials, certification premium structures, and contract-versus-spot pricing spreads. CAGRs derived from segment-level volume trajectories weighted by cathode material expansion timelines, REACH compliance cost pass-through assumptions, and iron oxide nanoparticle substitution elasticities in magnetic material applications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state battery cathode chemistry commercialization, ECHA authorization decisions for oxalate derivatives, and China's MEE emissions enforcement intensity. Practitioners should monitor LFP versus sodium-ion battery chemistry announcements, Annex XIV candidate list update schedules, and Indian PLI scheme precursor chemical investment filings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Concentrated Nitric Acid Market
Bulk Chemicals
Isovaleryl Chloride Market
Bulk Chemicals
Ethylbenzene Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Ethylene Oxide Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Furfural Market
Bulk Chemicals
China Starch and Starch Derivatives Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
N-Heptane Market
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
Magnesium Phosphate Market
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
Potassium Chloride Market