
 1-Hexene Market | 2026-2036
1-Hexene Market Size, Share, and Industry Trends Forecast 2026-2036
1-Hexene Market Analysis
Middle Eastern capacity additions are narrowing the historical supply gap between Asian demand and Atlantic basin production. Chevron Phillips Chemical Company leverages its proprietary full-range alpha olefin technology to sustain cost leadership across polymer-grade output. INEOS Group Limited anchors its European position through integrated crackers at Grangemouth and Lavéra, while SABIC competes via its Jubail complex with direct pipeline access to ethylene feedstock.
1-Hexene is a six-carbon linear alpha olefin with a terminal double bond, produced primarily through ethylene oligomerization using either SHOP (Shell Higher Olefins Process) or Ziegler-type chemistry, and functions chiefly as a comonomer in linear low-density polyethylene (LLDPE) production to control polymer density and toughness. Polymer Grade material dominates value capture given its purity requirements for metallocene catalyst systems, while Reagent Grade serves specialty chemical synthesis with tighter specification tolerances. The Application dimension shows Polyethylene Production carrying the majority volume, though Chemical Intermediary applications are gaining traction in surfactant and lubricant additive chains.
REACH registration requirements in Europe and EPA emissions guidelines in the United States shape product specifications and handling protocols for 1-hexene producers seeking market access. China's GB standards and MEE environmental enforcement are tightening allowable volatile organic compound thresholds at olefin production facilities. Saudi Arabia's national industrial regulator imposes local content requirements that favor domestic producers like SABIC in government-linked procurement. Stakeholders must track feedstock cost differentials between naphtha and ethane cracking economics while monitoring regulatory shifts in polymer end-markets that ultimately dictate comonomer call-offs.
Market Dynamics
Ethylene feedstock cost differentials between naphtha and ethane cracking economics are compressing margins for Atlantic basin producers while advantaging Gulf Coast and Middle Eastern operations with access to cheap shale gas.
Growth Catalysts
- China's petrochemical capacity expansion:New ethylene crackers in Zhejiang and Jiangsu provinces are adding dedicated comonomer trains, pulling incremental 1-hexene volumes from regional traders.
- REACH polymer registration:ECHA's updated substance evaluation protocols for polyethylene additives are forcing reformulation toward higher-purity comonomer grades, tightening specification premiums.
- Metallocene catalyst proliferation:Polymer producers are retrofitting solution-phase reactors to single-site systems that demand precise comonomer distribution control, locking in 1-hexene offtake.
Market Restraints
- Naphtha price volatility:European crackers dependent on Mediterranean and North Sea feedstock face margin squeeze when Brent crude differentials widen against Henry Hub gas benchmarks.
- Supply concentration in Jubail:SABIC's integrated complex controls pipeline-export volumes across the Red Sea, creating single-source dependency for Levantine polymer compounders.
- 1-Butene substitution in film grades:Lower-alpha olefin comonomers are capturing share in commodity stretch-film applications where toughness specifications permit density trade-offs.
Strategic Opportunities
- Bio-based feedstock pivot:EU Green Deal carbon-border adjustments are incentivizing fermentation-derived ethylene pilot plants in Rotterdam and Antwerp harbor zones.
- Surfactant chain expansion:Oxo-alcohol producers are qualifying 1-hexene for C6-based plasticizer precursors, opening volume outside polyethylene comonomer demand.
- MEE enforcement tightening:China's volatile organic compound emission audits are idling small-scale oligomerization units, consolidating volume toward import-dependent coastal consumers.
Industry Challenges
- Specialized catalyst procurement:Chromium-based ethylene trimerization systems require long-lead equipment from single-source engineering contractors, stretching project timelines.
- Polymer-grade certification latency:New production trains face 18-24 month qualification cycles with metallocene license-holders before securing offtake contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1-Hexene Market |
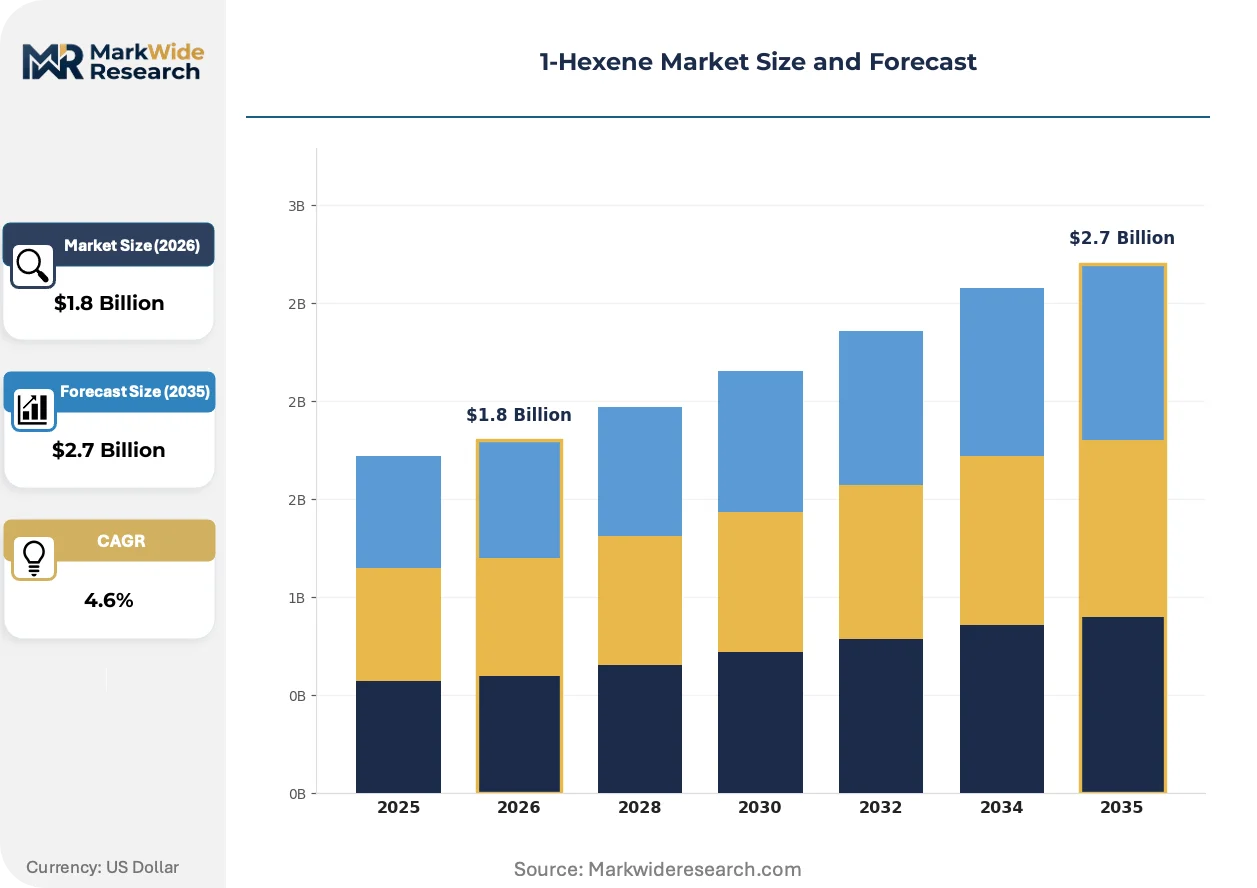
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Grade, Reagent Grade, Technical Grade, Industrial Grade End Use Industry: Plastics, Coatings, Adhesives, Textile Application: Polyethylene Production, Chemical Intermediary, Synthesis, Laboratory Use Distribution Channel: Direct Sales, Distributors, Online Retailers, Trading Companies |
| Companies Covered | Chevron Phillips Chemical Company, INEOS Group Limited, Royal Dutch Shell plc, SABIC, Sasol, The Dow Chemical Company, Idemitsu Kosan Co., Ltd, Qatar Chemical Company Ltd, ExxonMobil Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1-Hexene Market Emerging Trajectories
Process intensification and catalyst sophistication are converging to reshape how linear alpha olefins are produced, purified, and specified for downstream polymer systems.
Membrane separation technology for oligomer fractionation is rendering obsolete energy-intensive distillation trains at older SHOP-based facilities. Polymer producers in South Korea and Thailand are piloting these units to reduce steam consumption. The capital efficiency gain is compressing the minimum economic scale for new entrants.
EPA's updated National Emission Standards for Hazardous Air Pollutants are mandating closed-loop sampling systems at ethylene oligomerization units. US Gulf Coast operators are retrofitting existing plants with nitrogen-purged analytical cabinets. The compliance burden falls heaviest on standalone merchant producers lacking integrated flares and thermal oxidizers.
Long-term offtake contracting is displacing spot market exposure for polyethylene comonomer procurement. Compounders in Germany and Italy are locking in three-year supply agreements with fixed ethylene-alpha spreads. The risk transfer is most pronounced among mid-tier film extruders lacking backward integration into cracker economics.
1-Hexene Market Segmentation
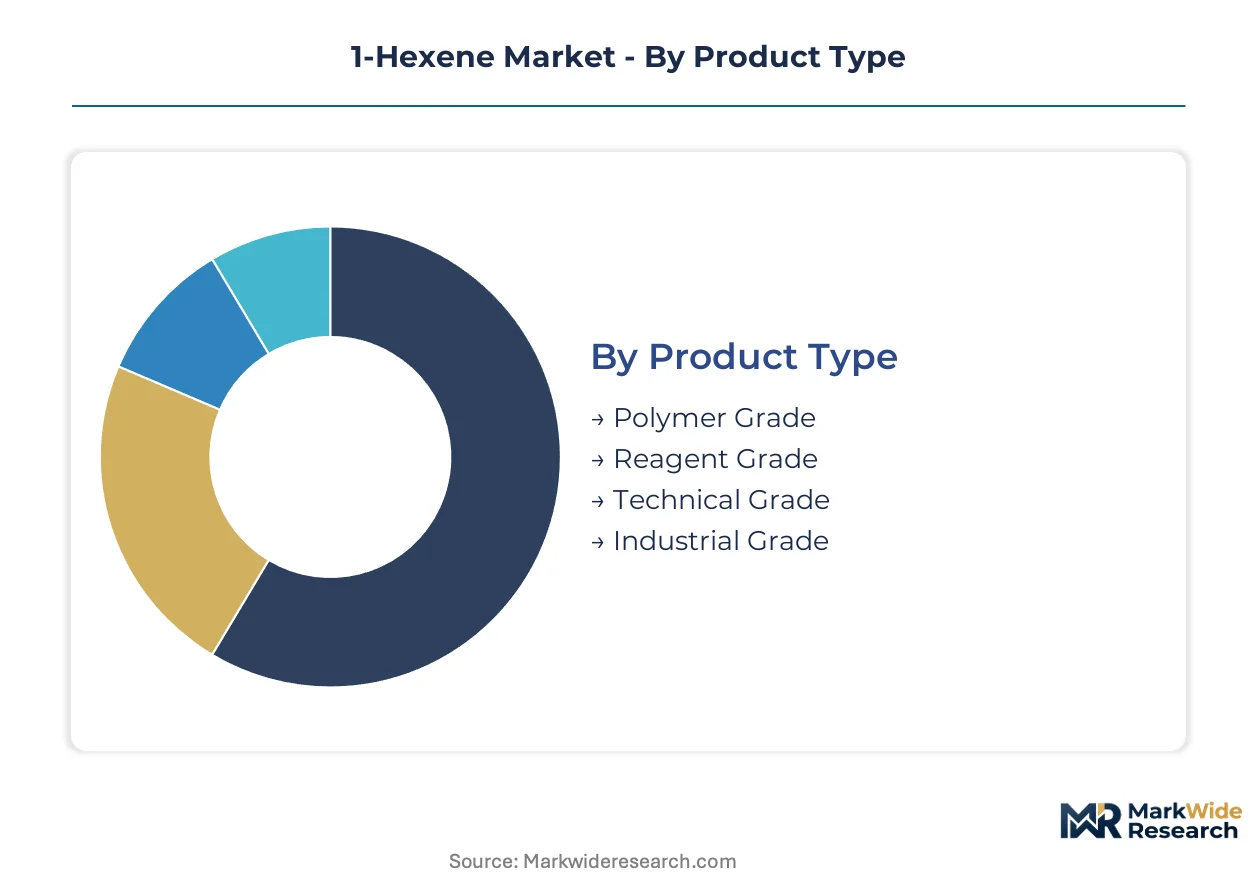
1-Hexene demand fragments across purity grades and application contexts that dictate pricing power and supply chain configuration. Comonomer specifications for metallocene polyethylene systems create rigid tier boundaries that resist substitution, while specialty chemical applications tolerate wider specification bands.
Product Type:
Purity thresholds separate segments by catalyst compatibility and end-use tolerance for impurities, with metallocene polymer systems demanding the tightest controls.
- Polymer Grade:Minimum 99.0% purity with controlled isomer content for single-site catalyst systems. Demand concentrates in China where Zhejiang and Jiangsu polyethylene expansions specify this grade exclusively, with ECHA's updated REACH protocols tightening allowable contaminant thresholds further.
- Reagent Grade:Ultra-high purity exceeding 99.5% for pharmaceutical and fine chemical synthesis. European surfactant producers in Rotterdam and Antwerp harbor zones are qualifying this material for C6-based plasticizer precursors, opening volume outside traditional polyethylene demand.
- Technical Grade:95-98% purity serving general industrial applications with relaxed specifications.
- Industrial Grade:Broad-spectrum material for non-critical applications where purity premiums cannot be recovered.
Polymer Grade holds installed capacity. Reagent Grade is rotating up the share rankings.
End Use Industry:
Application sectors differ fundamentally in volume scale, specification tolerance, and procurement contracting patterns.
- Plastics:Linear low-density polyethylene production consumes the majority volume, with metallocene catalyst proliferation locking in precise comonomer distribution requirements. China's film extrusion base in Shandong and Guangdong provinces drives call-off timing.
- Coatings:Solvent and resin formulation applications where 1-hexene contributes to drying properties and film formation. German automotive coating compounders are securing three-year supply agreements with fixed ethylene-alpha spreads to transfer price risk.
- Adhesives:Hot-melt and pressure-sensitive formulations requiring controlled volatility.
- Textile:Fiber treatment and finishing chemical production with modest volume contribution.
Plastics dominates volume throughput. Coatings is expanding most quickly as formulation complexity increases.
Application:
Functional use cases determine specification stringency and the length of producer qualification cycles.
- Polyethylene Production:Comonomer incorporation controls polymer density and toughness in solution-phase reactors. New production trains face 18-24 month qualification cycles with metallocene license-holders before securing offtake contracts, creating barriers to supply switching.
- Chemical Intermediary:Oxo-alcohol and surfactant precursor synthesis. South Korean and Thai membrane separation pilots are reducing steam consumption in oligomer fractionation, improving capital efficiency for intermediate producers.
- Synthesis:General organic chemistry applications with variable purity requirements.
- Laboratory Use:Analytical standards and research-scale consumption in small packaged quantities.
Polyethylene Production anchors producer economics. Chemical Intermediary is climbing the fastest as surfactant chains diversify feedstock.
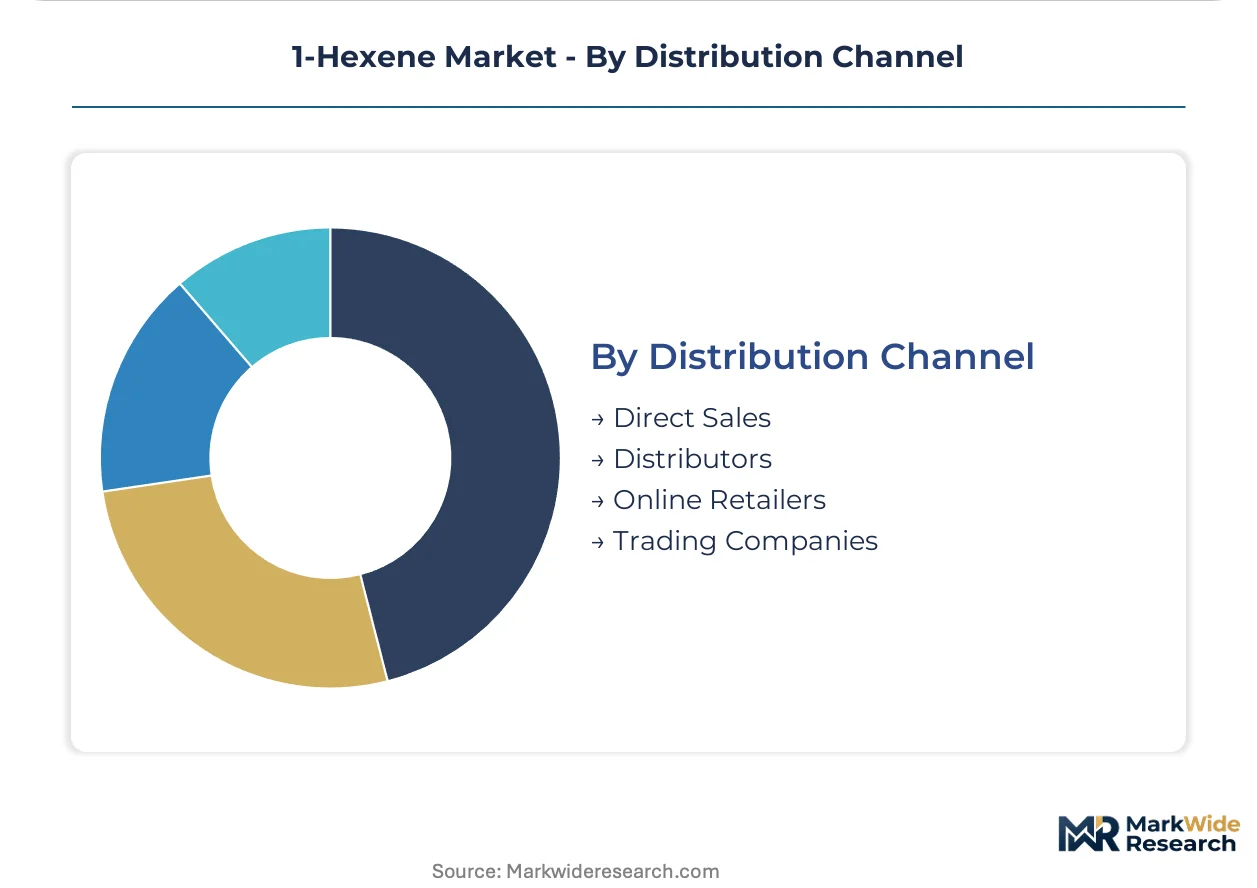
Distribution Channel:
Channel selection reflects buyer scale, geographic position relative to production clusters, and inventory risk tolerance.
- Direct Sales:Large-volume polyethylene producers with integrated cracker access or long-term offtake agreements. SABIC's Jubail complex leverages pipeline connectivity to serve Red Sea polymer compounders directly, bypassing intermediary margins.
- Distributors:Regional stockholding intermediaries serving mid-tier compounders lacking backward integration. European distributors are consolidating as REACH registration costs favor scaled operators with dedicated compliance staff.
- Online Retailers:Small-package fulfillment for laboratory and specialty chemical buyers.
- Trading Companies:Spot market exposure for buyers with flexible timing and specification tolerance.
Direct Sales commands the largest volume flow. Distributors is gaining share fastest as mid-tier buyers seek risk transfer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene oligomerization capacity clusters near feedstock-advantaged crackers, with investment gravitating toward shale gas corridors and integrated petrochemical complexes. The geographic distribution of 1-hexene production reflects ethane cracking economics and pipeline infrastructure density rather than end-use proximity.
United States
Gulf Coast crackers along the Texas-Louisiana corridor leverage Henry Hub-priced ethane to sustain cost leadership in alpha olefin output. EPA's National Emission Standards for Hazardous Air Pollutants mandate closed-loop sampling systems at oligomerization units, driving retrofit investments. Chevron Phillips Chemical Company operates from its Cedar Bayou complex near Houston, shipping polymer-grade material to domestic LLDPE compounders and export terminals.
China
Zhejiang and Jiangsu provinces host the majority of new ethylene capacity with dedicated comonomer trains pulling incremental 1-hexene volumes. MEE volatile organic compound emission audits are idling small-scale oligomerization units, consolidating demand toward import-dependent coastal consumers. The Yangtze River Delta petrochemical belt around Ningbo and Shanghai anchors polyethylene production call-offs.
Saudi Arabia
SABIC's Jubail complex controls pipeline-export volumes across the Red Sea with direct ethylene feedstock access from adjacent crackers. The national industrial regulator imposes local content requirements favoring domestic producers in government-linked procurement. The Eastern Province industrial zone concentrates alpha olefin output for Levantine and African polymer compounders.
Germany
Ruhr Valley chemical producers face margin compression from naphtha-dependent cracking economics when Brent crude differentials widen. ECHA's updated REACH substance evaluation protocols for polyethylene additives tighten specification premiums for higher-purity comonomer grades. BASF and INEOS operations at Ludwigshafen and Cologne serve European film extruders locking in three-year supply agreements.
South Korea
Ulsan and Yeosu industrial complexes host membrane separation pilots reducing steam consumption in oligomer fractionation. MFDS chemical facility safety audits align with broader OECD chemical management frameworks. Daesan-based producers are qualifying 1-hexene for C6-based surfactant precursors outside traditional polyethylene demand channels.
1-Hexene Market Vendor Landscape
Integrated petrochemical majors and standalone merchant producers split the market between captive supply chains and spot-exposed trading positions. The vendor base concentrates around ethylene cracker operators with oligomerization downstream, supplemented by regional trading houses filling geographic gaps. Two strategic archetypes dominate: Gulf Coast ethane-advantaged producers with full-range alpha olefin technology, and European naphtha-based operators defending position through metallocene certification lock-in. Capacity expansion and long-term offtake contracting represent the dominant competitive moves, with producers securing polymer-grade qualification cycles before rival trains commence operations.
Within the integrated-major tier, Chevron Phillips Chemical Company and SABIC exemplify feedstock-advantaged positioning through Gulf Coast and Jubail complex operations respectively. INEOS Group Limited occupies a position bridging Atlantic basin naphtha economics with Grangemouth and Lavéra integration. These three anchors represent divergent responses to ethylene feedstock cost differentials: ethane cracking scale, pipeline-connected integration, and European regulatory compliance specialization.
| Leading Market Players |
|---|
| Chevron Phillips Chemical Company |
| INEOS Group Limited |
| Royal Dutch Shell plc |
| SABIC |
| Sasol |
| The Dow Chemical Company |
| Idemitsu Kosan Co., Ltd |
| Qatar Chemical Company Ltd |
| ExxonMobil Chemical |
| Others |
Supply Flow & Price Mechanics
Red Sea pipeline corridors from Jubail to Levantine polymer compounders carry freight premiums that amplify supply concentration effects, compressing margins for buyers lacking direct ethylene cracker access while enabling tiered price discrimination between pipeline-connected and spot-dependent purchasers.
Pricing Analysis
REACH registration protocols dictate the pricing tier structure across European polyethylene comonomer procurement. Three-tier pricing separates polymer-grade certified material from standard comonomer grades from technical-grade industrial supply, with ECHA substance evaluation thresholds widening spreads between tiers. Cost compression in Atlantic basin naphtha-based output is intensifying because Henry Hub ethane differentials sustain Gulf Coast cost leadership. Mid-tier film extruders lacking backward integration into cracker economics exhibit highest price sensitivity; integrated majors with captive ethylene supply show lowest.
Supply Chain Analysis
Merchant oligomerization capacity concentrates with Chevron Phillips Chemical Company at Cedar Bayou, SABIC at Jubail, and INEOS at Grangemouth and Lavéra. Feedstock supply draws from ethane cracking corridors along the US Gulf Coast, naphtha-dependent Mediterranean crackers, and integrated Saudi ethylene pipelines. Single-source vulnerability runs through SABIC's Red Sea pipeline monopoly for Levantine compounders. Distribution runs through direct pipeline sales for integrated majors, regional distributors for mid-tier buyers, and trading houses for spot-exposed consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
1-Hexene demand sits in early-cycle expansion as metallocene catalyst proliferation across Asian polyethylene capacity creates structural comonomer pull. Metallocene license-holders are retrofitting solution-phase reactors faster than alternative comonomer qualification cycles can match.
For Market Incumbents: Build certification moats by securing 18-24 month qualification cycles with metallocene license-holders before rival trains commence operations. Anchor backward integration into ethane cracking economics at Gulf Coast or Jubail complexes to defend against naphtha margin squeeze. Counter 1-butene substitution threats in commodity film grades by locking three-year offtake agreements with fixed ethylene-alpha spreads. For New Entrants and Emerging Players: Build out surfactant chain qualification in Rotterdam and Antwerp harbor zones where oxo-alcohol producers are sourcing C6-based plasticizer precursors outside polyethylene demand. Target China's coastal import-dependent consumers where MEE emission audits have idled small-scale oligomerization units. Pursue membrane separation technology licensing to reduce minimum economic scale barriers versus legacy SHOP-based competitors. For Investors and Strategic Acquirers: Standalone merchant producers with stranded naphtha cracking exposure present acquisition targets as ethane cost differentials compress Atlantic basin margins. Long-term viability hinges on feedstock position and metallocene certification lock-in rather than spot market trading exposure. Watch SABIC pipeline export volumes across the Red Sea as inflection indicator for Levantine supply security and pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New ethylene crackers in Zhejiang and Jiangsu provinces pull dedicated comonomer train investment. |
| Backward Integration | Gulf Coast operators securing Henry Hub ethane supply sustain cost leadership against naphtha competitors. |
| Long-term Supply Agreement | German and Italian compounders lock three-year contracts with fixed ethylene-alpha spreads to transfer price risk. |
| Green Manufacturing Transition | EU Green Deal carbon-border adjustments incentivize fermentation-derived ethylene pilot plants in Rotterdam harbor zones. |
| Joint Venture | Membrane separation pilots in South Korea and Thailand reduce steam consumption and compress economic scale thresholds. |
Methodological Framework
A spread of perspectives from plant managers at oligomerization facilities, procurement leads at downstream polyethylene compounders, distribution channel partners in European harbor zones, and technical R&D directors at catalyst licensors converged on the working assumptions. Primary interview insights triangulated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated majors, and EPA National Emission Standards documentation. Bottom-up volume modeling from individual cracker and comonomer train capacities cross-checked against top-down polyethylene production forecasts.
Demand-supply balance modeling anchored the analytical framework across the projection horizon. Segmentation dimensions spanned purity grade tiers, end-use industry concentration in plastics versus coatings, application splits between polyethylene production and chemical intermediary channels, and regional production hub clustering. CAGRs derived from ethylene capacity expansion pipelines, metallocene catalyst retrofit timelines, and comonomer specification tightening trajectories. Feedstock cost differentials between naphtha and ethane cracking economics and REACH registration compliance burdens shaped regional growth differentials.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Gulf Coast ethane-advantaged producers or accelerated bio-based feedstock pivots by European operators would shift outcomes. Regulatory enforcement intensity at China's MEE, ECHA substance evaluation protocol updates, and metallocene license-holder qualification cycle durations present specific revision risks. Quarterly review of SABIC pipeline export volumes, Zhejiang cracker commissioning timelines, and membrane separation pilot scale-up rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Diketene Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Naphthalene Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Acetochlor Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Global Tetrahydrofuran Market
Bulk Chemicals
Propionic Anhydride Market
Bulk Chemicals
Barium Sulphate Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Sodium Sulfide Market
Bulk Chemicals
Oman Sodium Hydroxide Market
Bulk Chemicals
Phosphorus Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
Triammonium Citrate Market