
 Maleic Anhydride Market | 2026-2036
Maleic Anhydride Market Size, Share, and Industry Trends Forecast 2026-2036
Maleic Anhydride Market Intelligence
Aftermarket formulation services for unsaturated polyester resins is narrowing as integrated producers internalize compounding expertise. Huntsman Corporation leverages its North American manufacturing footprint to sustain captive supply of downstream derivatives. INEOS AG anchors European volume through its Rotterdam-adjacent production complex. Polynt S.p.A. specializes in vertically integrated resin systems that compete on specification breadth rather than commodity pricing alone.
Maleic anhydride is a cyclic dicarboxylic anhydride manufactured primarily through vapor-phase oxidation of n-butane or benzene, yielding a white crystalline solid with a molecular weight of 98.06 g/mol that serves as a critical chemical intermediate for unsaturated polyester resins, agricultural chemicals, and copolymer production. Petroleum-based production still dominates volume economics, though bio-based pathways are gaining structural attention as carbon accounting intensifies across chemical value chains. The application split shows unsaturated polyester resins occupying the largest margin pool due to construction and automotive component demand, while copolymers represent the fastest-growing structural segment driven by packaging and adhesive formulations. End-use concentration in construction and paints coatings sustains bulk consumption patterns even as automotive lightweighting creates specification pressure for higher-purity grades.
EPA emissions standards for volatile organic compounds and OSHA process safety management requirements shape US plant configurations and capital intensity for new maleic anhydride capacity. REACH registration obligations and the EU Green Deal carbon border adjustment mechanism are redirecting European procurement toward verified lower-carbon feedstock pathways. Stakeholders must monitor how divergent regulatory stringency between US EPA frameworks and European ECHA chemical safety protocols reshapes trade flows and investment location decisions for derivative manufacturing.
Market Dynamics
Vapor-phase oxidation economics and REACH-driven feedstock verification requirements are compressing margin structures for n-butane-based producers while accelerating capital flows toward bio-based pathway development.
Growth Catalysts
- Construction sector demand:Unsaturated polyester resin consumption for composite panels and corrosion-resistant piping sustains volume pull across industrialized economies. Building code modernization in seismic zones drives specification upgrades.
- REACH compliance verification:European manufacturers are procuring certified lower-carbon maleic anhydride to satisfy EU Green Deal carbon border adjustment mechanism documentation requirements for derivative exports.
- Automotive lightweighting:Glass-reinforced thermoset composites replacing metal components in electric vehicle battery housings and structural members expand high-purity grade requirements.
Market Restraints
- n-Butane feedstock volatility:Crude oil and natural gas liquid price swings transmit directly to production economics, compressing margins for non-integrated producers without captive butane supply.
- Chinese supply concentration:Wanhua and domestic petrochemical complexes control regional derivative chemical supply chains, creating import dependency risks for buyers outside Asia-Pacific.
- Biomass conversion technical limits:Furfural and bio-butane pathways face yield penalties and catalyst poisoning challenges that prevent cost parity with petroleum-based production at commercial scale.
Strategic Opportunities
- India industrialization:PLI scheme incentives for domestic chemical manufacturing and infrastructure build-out create greenfield demand for unsaturated polyester resins in construction and transportation applications.
- Packaging copolymer expansion:Maleic anhydride-grafted polyolefins for adhesive tie layers and barrier films are penetrating flexible packaging specifications as multilayer film complexity increases.
- Digital supply chain integration:Blockchain-enabled feedstock provenance tracking allows premium pricing for verified bio-based content certificates sold to brand owners with net-zero commitments.
Industry Challenges
- Process safety engineering talent:OSHA process safety management compliance for vapor-phase oxidation units requires specialized expertise that competes with broader petrochemical sector hiring.
- Legacy equipment retrofit complexity:Existing fixed-bed reactor installations face catalyst replacement and emissions control upgrade cycles that disrupt production scheduling and working capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maleic Anhydride Market |
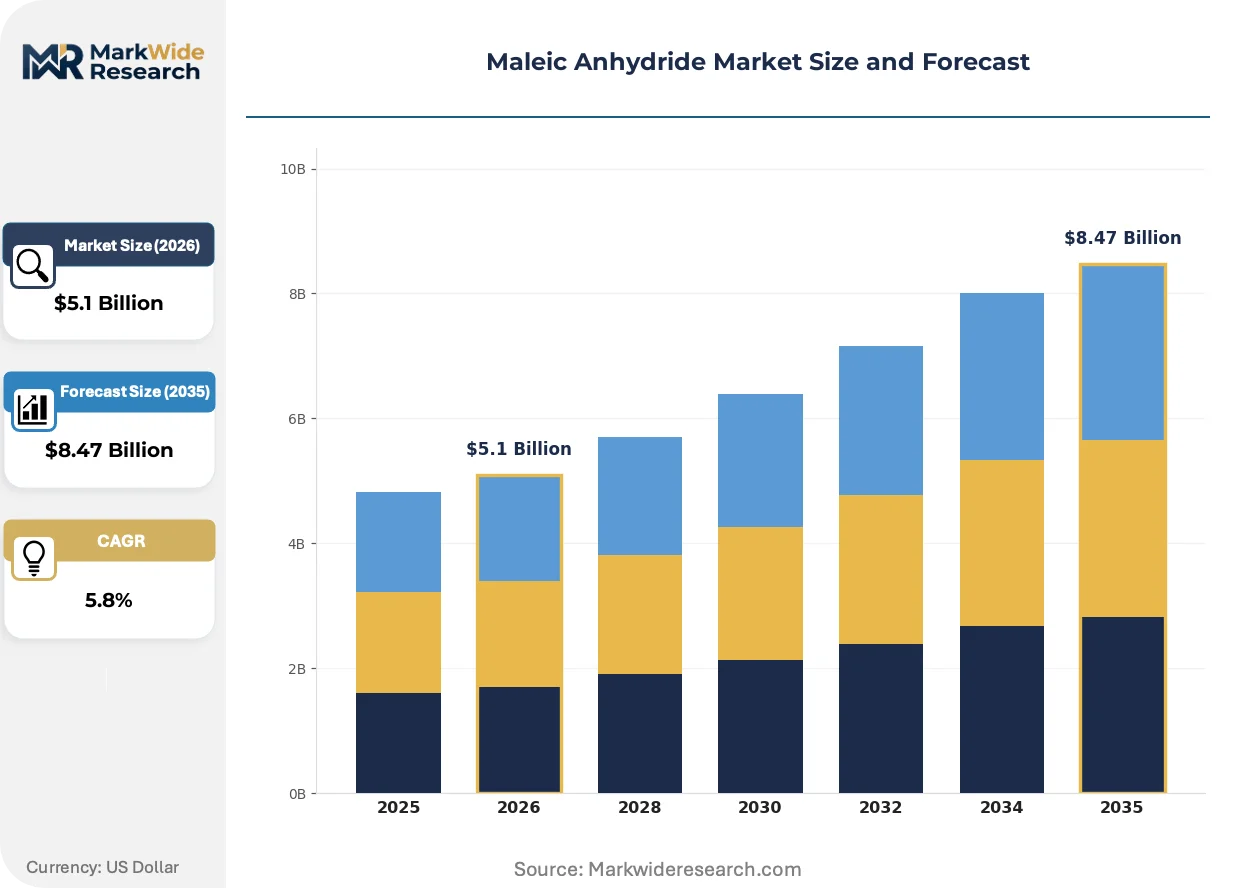
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $8.47 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Petroleum-Based, Bio-Based, Grafted, Others Application: Unsaturated Polyester Resins, Agricultural Chemicals, Lubricant Additives, Copolymers End Use Industry: Construction, Automotive Components, Paints & Coatings, Textile Finishing Form: Powder, Flake, Granules, Liquid |
| Companies Covered | Mitsubishi Chemical Corporation, Nippon Shokubai Co., Ltd., Huntsman Corporation, Wanhua, INEOS AG, BASF SE, LANXESS AG, Arkema S.A., Polynt S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maleic Anhydride Market Strategic Shifts & Innovations
Process intensification and carbon accounting automation are restructuring how maleic anhydride producers validate feedstock origins and optimize reactor yields across geographically dispersed manufacturing assets.
Advanced process control systems deploying machine learning for real-time catalyst performance prediction is digitizing yield optimization workflows. Integrated producers with captive n-butane supply are deploying these platforms fastest. The technology is digitizing margin capture by reducing unplanned shutdown frequency and extending catalyst campaign lengths.
EU Green Deal carbon border adjustment mechanism documentation requirements are forcing feedstock provenance verification systems into procurement contracts. European derivative manufacturers now require supplier-provided lifecycle assessment data for REACH registration dossier updates. Unsaturated polyester resin compounders serving automotive OEMs face the steepest compliance cost escalation.
Specification-driven procurement consolidation is compressing supplier lists as construction and automotive buyers centralize resin purchasing through qualified supplier programs. Large unsaturated polyester resin consumers are bypassing distributors for direct mill contracts with volume commitments. This pattern is most visible in China where Wanhua anchors regional supply chains and tier-one composite manufacturers internalize blending operations.
Maleic Anhydride Market Segmentation
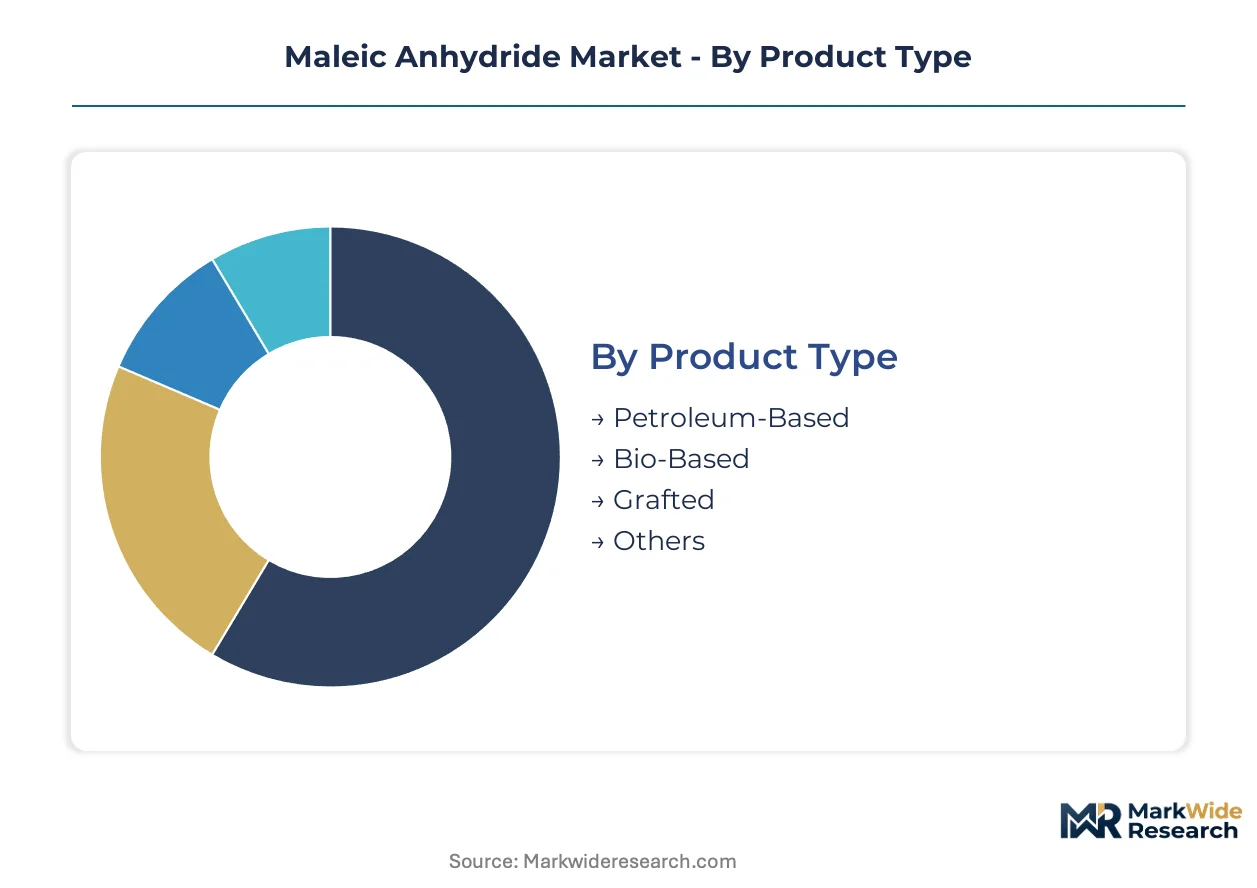
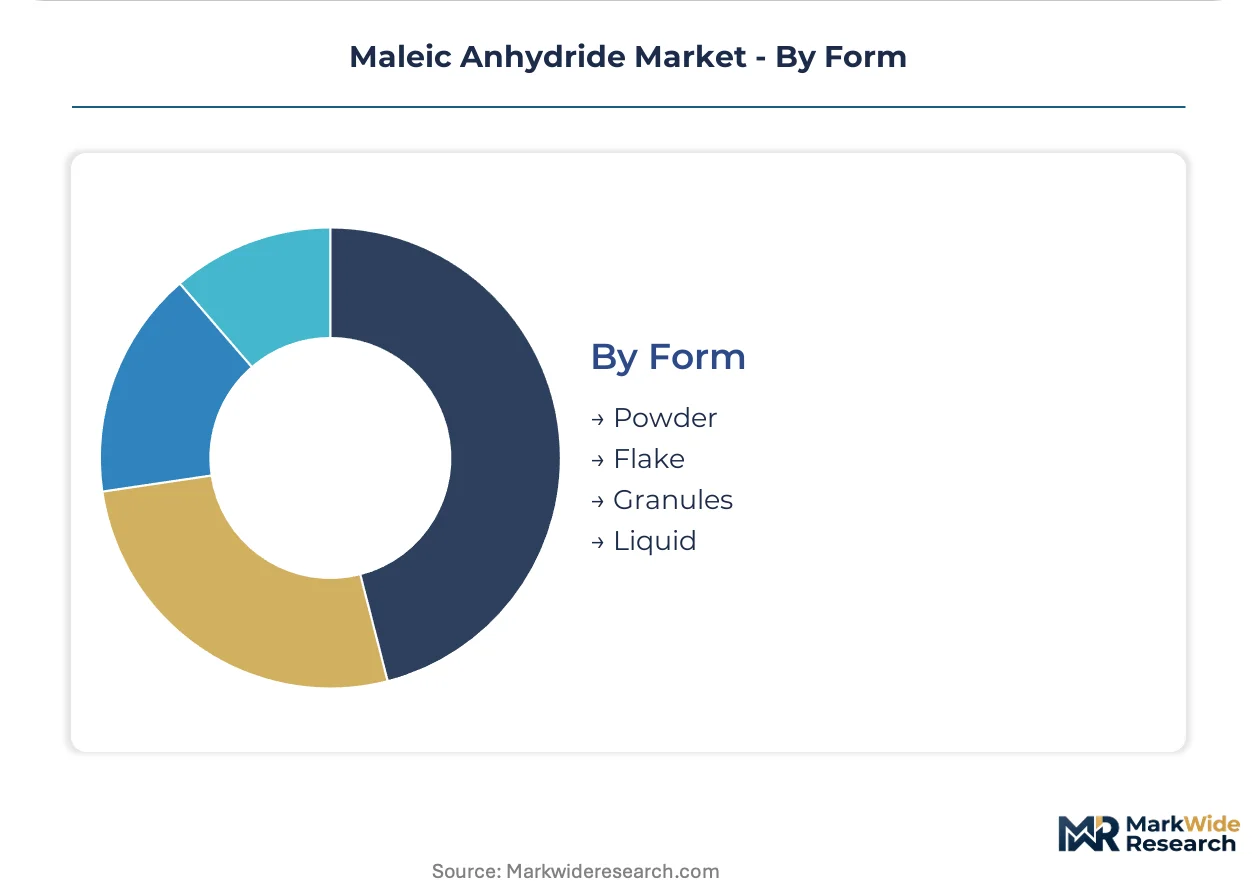
Maleic anhydride segmentation reveals how feedstock chemistry, application performance requirements, and physical handling constraints create distinct margin pools. Producers configure asset portfolios across these dimensions to match regional demand cycles and regulatory compliance burdens.
Product Type:
Inventory velocity varies sharply across feedstock pathways, with petroleum-based grades turning fastest through commodity channels while bio-based batches move slower due to certification documentation requirements.
- Petroleum-Based:Derived from n-butane or benzene vapor-phase oxidation, this grade dominates volume economics through established catalyst systems and integrated petrochemical supply chains. Construction sector procurement in China and the US sustains the highest throughput volumes, though n-butane price volatility compresses margins for non-integrated producers.
- Bio-Based:Manufactured via furfural dehydration or bio-butane pathways, this segment commands premium pricing through EU Green Deal carbon border adjustment mechanism compliance documentation. REACH registration dossiers for derivative exports increasingly require verified lifecycle assessment data, accelerating procurement shifts among European unsaturated polyester resin compounders.
- Grafted:Maleic anhydride functionalized onto polyolefin backbones for adhesive and compatibilizer applications, serving packaging multilayer film specifications.
- Others:Specialty derivatives including sulfonated and halogenated variants for niche chemical synthesis.
Petroleum-based production anchors the volume base while bio-based pathways gain share at the steepest rate.
Application:
Margin concentration follows application complexity, with resin systems capturing value through formulation expertise while copolymer growth reflects packaging specification evolution.
- Unsaturated Polyester Resins:The largest application by revenue, consuming maleic anhydride as a reactive diluent and crosslinking agent in thermoset composites. Demand concentrates in China where Wanhua and domestic petrochemical complexes anchor regional supply chains for construction panels and corrosion-resistant piping.
- Copolymers:Maleic anhydride-grafted polyolefins for adhesive tie layers and barrier films are penetrating flexible packaging specifications as multilayer film complexity increases. Automotive OEMs specify these materials for battery housings and structural lightweighting components.
- Agricultural Chemicals:Intermediate for pesticides and plant growth regulators, with demand tied to seasonal planting cycles and regulatory re-registration requirements.
- Lubricant Additives:Dispersant and viscosity modifier feedstock serving industrial and automotive fluid formulations.
Unsaturated polyester resins generate the deepest margin pool while copolymers are expanding most quickly.
End Use Industry:
Customer concentration patterns differ by sector, with construction buyers centralizing procurement through qualified supplier programs while automotive OEMs enforce direct mill contracts with volume commitments.
- Construction:Composite panel and reinforced piping applications sustain bulk consumption across industrialized economies. Building code modernization in seismic zones drives specification upgrades for higher-purity grades.
- Automotive Components:Glass-reinforced thermoset composites replacing metal in electric vehicle battery housings and structural members. EPA emissions standards for volatile organic compounds and OSHA process safety management requirements shape US plant configurations serving this sector.
- Paints & Coatings:Alkyd resin and curing agent applications with demand tied to architectural and industrial maintenance cycles.
- Textile Finishing:Wrinkle resistance and durable press treatments, facing substitution pressure from formaldehyde-free alternatives.
Construction absorbs the highest absolute volumes while automotive components drive the steepest grade premium expansion.
Form:
Physical state selection reflects handling infrastructure and dissolution requirements, with powder and flake dominating established resin operations while liquid forms penetrate continuous process manufacturing.
- Flake:Standard crystalline form for bulk resin production, optimized for melting and dissolution in unsaturated polyester manufacturing. INEOS AG and Huntsman Corporation maintain dedicated flaking capacity adjacent to derivative production.
- Liquid:Molten or solution forms for continuous process integration, reducing solid handling and dust exposure compliance costs. Polynt S.p.A. specializes in vertically integrated liquid supply systems.
- Powder:Micronized grades for rapid dissolution in small-batch compounding operations.
- Granules:Agglomerated forms for controlled release and reduced caking in storage.
Flake maintains the broadest installed base while liquid forms are climbing the fastest as process integration intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China absorb volume without price elasticity, while European purchasers demand certified carbon documentation that commands premium tolerance. Price sensitivity concentrates in North American construction procurement, where n-butane volatility transmits directly to derivative margins.
United States
Construction composite panel demand and automotive lightweighting programs drive consumption across the Gulf Coast and Midwest manufacturing belts. EPA emissions standards for volatile organic compounds and OSHA process safety management requirements shape plant configurations in Texas and Louisiana. The Houston Ship Channel petrochemical complex anchors n-butane supply integration for derivative resin production serving domestic automotive OEMs.
Germany
Automotive battery housing specifications and REACH-driven feedstock verification sustain premium-grade procurement from compounders serving BMW and Volkswagen supply chains. ECHA chemical safety protocols and EU Green Deal carbon border adjustment mechanism documentation requirements redirect procurement toward verified lower-carbon pathways. The North Rhine-Westphalia chemical cluster around Leverkusen and Dormagen concentrates formulation expertise for high-purity unsaturated polyester resin systems.
China
Wanhua and domestic petrochemical complexes anchor regional supply chains for construction panels and corrosion-resistant piping across coastal provinces. GB standards and MIIT industrial policy guide capacity expansion in Shandong and Jiangsu chemical parks. The Yangtze River Delta manufacturing corridor concentrates derivative chemical production for export-oriented composite manufacturers.
India
PLI scheme incentives for domestic chemical manufacturing and infrastructure build-out create greenfield demand for unsaturated polyester resins in construction and transportation applications. BIS certification requirements and DGFT import duty structures shape procurement patterns for resin compounders. The Gujarat chemical belt around Dahej and Mundra anchors new maleic anhydride derivative capacity serving western Indian automotive and construction markets.
Japan
Specialty copolymer demand for electronic packaging and automotive adhesive applications sustains high-purity grade consumption. METI carbon neutrality roadmaps and JIS standards drive feedstock provenance verification for export-oriented derivative manufacturers. The Chubu region around Nagoya concentrates precision compounding operations serving Toyota and Honda supply chain specifications.
Maleic Anhydride Market Key Industry Players
Capability concentration sits with integrated petrochemical conglomerates; scale advantage sits with regional specialists with captive feedstock access. The vendor base organizes around three tiers: multinational chemical majors with backward integration into n-butane supply, mid-cap regional producers with derivative-focused asset configurations, and specialty compounders competing on specification breadth. Dominant competitive moves include capacity expansion adjacent to downstream resin operations and strategic partnerships for bio-based feedstock pathway development.
Among Asia-Pacific-based chemical majors, Mitsubishi Chemical Corporation and Nippon Shokubai Co., Ltd. occupy positions exemplifying integrated petrochemical scale with downstream derivative control. Huntsman Corporation represents North American manufacturing footprint leverage for captive supply sustainability. These three names anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Nippon Shokubai Co., Ltd. |
| Huntsman Corporation |
| Wanhua |
| INEOS AG |
| BASF SE |
| LANXESS AG |
| Arkema S.A. |
| Polynt S.p.A. |
| Others |
Cost & Logistics Intelligence
The Houston Ship Channel freight corridor transmits n-butane feedstock cost swings directly to derivative margins while enabling premium capture for REACH-certified bio-based grades destined for European compounders. Supply concentration along this Gulf Coast petrochemical artery amplifies pricing power for integrated producers with captive butane access, forcing non-integrated buyers into long-term offtake commitments to hedge volatility.
Pricing Analysis
Long-term offtake contracts dominate procurement for unsaturated polyester resin compounders, insulating integrated producers from spot n-butane volatility while spot purchases concentrate among small-batch specialty buyers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified bio-based grades from commodity petroleum-based flake and unverified imports. Cost compression in standard-grade flake is intensifying because Chinese petrochemical complexes are flooding export markets with volume-driven pricing. Construction sector buyers in North America exhibit the highest price sensitivity, while automotive OEMs in Germany tolerate premium grades for battery housing specifications.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for European distributors serving REACH-compliant compounders, reflecting working capital pressure from carbon border documentation costs. Production gravity centers on China, the United States, and Germany, with n-butane feedstock, vanadium-phosphorus oxide catalysts, and specialized flaking equipment forming critical input dependencies. Single-source vulnerability concentrates in catalyst supply chains dominated by Japanese and Belgian specialty chemical producers. Distribution runs through qualified supplier programs where tier-one composite manufacturers bypass distributors for direct mill contracts with volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket formulation services represent the fastest-expanding recurring-revenue layer, outpacing commodity maleic anhydride sales as automotive OEMs outsource resin system specification development to qualified compounders.
For Market Incumbents: Harden supply security by securing captive n-butane access through pipeline interconnect agreements or storage terminal positions in the Gulf Coast and Rotterdam-adjacent corridors. Invest in REACH registration dossier pre-submission for bio-based grades before EU Green Deal carbon border adjustment mechanism documentation requirements tighten further. These moves counter margin erosion from Chinese volume exports and protect qualified supplier status with BMW and Volkswagen supply chains. For New Entrants and Emerging Players: Establish a beachhead in India PLI scheme-supported construction resin compounding, where domestic maleic anhydride derivative capacity lags infrastructure build-out demand. Target unsaturated polyester resin formulation for corrosion-resistant piping in Gujarat chemical parks, leveraging BIS certification requirements that disadvantage import-dependent competitors. A technical partnership with established catalyst suppliers accelerates plant commissioning and qualified supplier program admission. For Investors and Strategic Acquirers: Carve-out targets emerge from European petrochemical conglomerates divesting non-core specialty anhydride operations to fund energy transition capital allocation. Mid-cap producers with REACH-registered bio-based pathways and existing automotive OEM supply chain relationships present the strongest five-to-ten-year viability profiles. Monitor EU ETS carbon price trajectories as the signal to watch for inflection in bio-based pathway economics versus petroleum-based production.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into n-Butane Supply | Huntsman Corporation's Texas pipeline network demonstrates how captive feedstock access stabilizes margin capture against commodity volatility. |
| REACH Certification Investment | INEOS AG's Rotterdam complex illustrates how pre-registered bio-based grades command premium positioning under EU Green Deal documentation rules. |
| Joint Venture for Bio-Based Pathway Development | Polynt S.p.A.'s vertically integrated liquid supply systems show how furfural dehydration partnerships reduce catalyst poisoning yield penalties. |
| Long-term Supply Agreement with Automotive OEMs | Wanhua's direct mill contracts with tier-one composite manufacturers reveal how volume commitments secure capacity utilization through demand cycles. |
| Capacity Expansion Adjacent to Downstream Resin Operations | Mitsubishi Chemical Corporation's Chubu region clustering demonstrates how co-location with Toyota and Honda specifications reduces logistics and quality assurance costs. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, Cefic chemical industry reports, and customs trade data to validate supply chain concentration patterns and pricing dynamics. Plant managers at n-butane oxidation facilities, procurement leads at unsaturated polyester resin compounders, distribution channel partners serving construction and automotive sectors, and technical R&D directors for catalyst systems provided structured interview input. Bottom-up capacity and utilization estimates triangulate against top-down consumption models derived from derivative production volumes.
Forecast inputs include feedstock cost trajectories, regulatory implementation timelines for EU carbon border adjustments, and automotive lightweighting content-per-vehicle assumptions across the projection horizon. Segmentation dimensions span petroleum versus bio-based feedstock pathways, unsaturated polyester resin versus copolymer application splits, and construction versus automotive end-use concentration. CAGRs derive from regression analysis of historical price-volume relationships and scenario-weighted regulatory implementation probabilities.
Sensitivities concentrate around n-butane price volatility, REACH dossier acceptance timelines, and Chinese export tax policy shifts. Forecasts reflect assumptions about catalyst technology yield improvements and bio-based pathway cost convergence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
Ethylene Dichloride Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
Glacial Methacrylic Acid Market
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
Isovaleryl Chloride Market
Bulk Chemicals
Global Dicyandiamide Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market
Bulk Chemicals
Global Isobutanol Market
Bulk Chemicals
Global Glycerol Monostearate (GMS) Powder Market
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
North America Glycerol Market
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Green Petroleum Coke and Calcined Petroleum Coke Market