
 Ethyl Mercaptan Market | 2026-2036
Ethyl Mercaptan Market Size, Share, and Industry Trends Forecast 2026-2036
Ethyl Mercaptan Market Foresight
Asset-light leasing arrangements for specialty chemical storage and transport are fragmenting competitive entry barriers across the ethyl mercaptan value chain. ExxonMobil leverages captive feedstock integration across Gulf Coast refineries to sustain cost advantages in synthetic production. Huntsman International anchors its position through dedicated mercaptan technology leadership and controlled distribution networks for odorant blends.
Ethyl mercaptan, also known as ethanethiol, is an organosulfur compound with the molecular formula C₂H₅SH and a characteristic penetrating odor detectable at parts-per-billion concentrations, manufactured primarily through ethylene hydrogen sulfide reaction or ethanol thiolation processes. Its primary industrial purpose centers on odorizing odorless natural gas and LPG to enable leak detection, alongside serving as a chemical intermediate for pesticides and pharmaceuticals. Synthetic grade production dominates volume given consistent purity requirements for gas odorant applications, while specialty grades command margin premiums in pharmaceutical synthesis where impurity thresholds tighten. Drum packaging for chemical reagent applications sustains stable revenue pools despite slower volume growth relative to bulk tanker shipments serving utility-scale odorant injection systems.
EPA regulations under the Clean Air Act govern volatile organic compound emissions from mercaptan handling facilities, while OSHA sets permissible exposure limits for worker safety in production environments. DOT hazardous materials standards shape packaging and transport protocols across interstate commerce. Stakeholders must monitor evolving state-level methane reduction mandates that could expand odorant specification requirements beyond federal baselines.
Market Dynamics
EPA odorant concentration mandates are tightening specifications across natural gas distribution networks, forcing reformulation investments and supplier consolidation around Gulf Coast production clusters.
Growth Catalysts
- Pipeline network expansion:North American midstream operators are extending odorant injection infrastructure across shale basin gathering systems, creating sustained volume pull for bulk mercaptan supply.
- Clean Air Act enforcement:EPA leak detection protocols are mandating lower detection thresholds for odorless gas releases, driving specification upgrades in odorant blend formulations.
- Ethylene feedstock proximity:Gulf Coast petrochemical corridor concentration enables integrated hydrogen sulfide reaction economics that coastal importers cannot replicate.
Market Restraints
- Feedstock volatility:Ethylene and hydrogen sulfide input costs fluctuate with refinery operating rates, compressing margin stability for non-integrated producers.
- Supplier concentration:Synthetic grade production clusters along Texas and Louisiana coastlines create geographic exposure to hurricane disruption and force majeure risk.
- Substitution pressure:Tertiary butyl mercaptan and tetrahydrothiophene odorants compete for specification slots in select LPG distribution contracts.
Strategic Opportunities
- Pharmaceutical synthesis grades:Ultra-low impurity mercaptan for active pharmaceutical ingredient production commands margin premiums above industrial odorant specifications.
- Modular odorant skids:Pre-engineered injection systems reduce field installation complexity for rural gas utilities lacking specialized chemical handling expertise.
- State methane mandates:California and Colorado leak reduction frameworks extend odorant performance requirements beyond federal EPA baselines.
Industry Challenges
- Specialized chemical handling certification:DOT hazardous materials licensing and OSHA process safety management compliance extend lead times for new distribution partnerships.
- Legacy injection system incompatibility:Older mechanical odorizers in municipal gas utilities require retrofit or replacement to handle reformulated higher-concentration blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethyl Mercaptan Market |
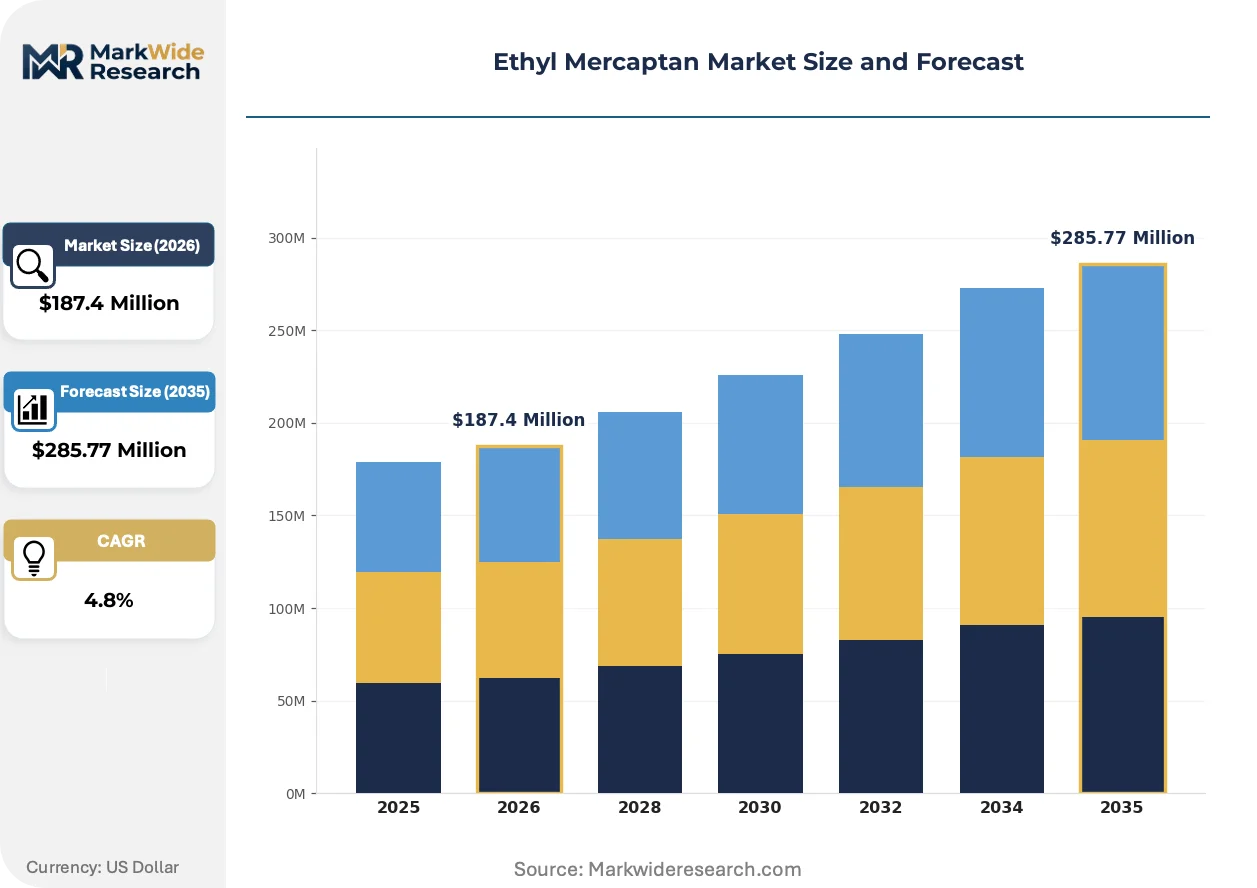
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Industrial, Specialty End Use Industry: Chemical Manufacturing, Oil & Gas, Agriculture, Pharmaceuticals Packaging Type: Drums, Bottles, Tankers, Cylinders Application: Odorant, Synthesis, Fuel Additive, Chemical Reagent |
| Companies Covered | ExxonMobil, Huntsman International, Arkema, Hangzhou Dayangchem, Evonik, Chevron Phillips Chemical, Air Liquide, Hebei Yanxi Chemical, DowDuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethyl Mercaptan Market Shifts & Advancements
Reformulation chemistry and delivery system engineering are converging to address odorant stability, injection precision, and environmental compliance simultaneously across gas utility operations.
Continuous odorant monitoring technology is migrating from manual sampling protocols to real-time spectroscopic detection at injection points. Major interstate pipeline operators deploy these systems to verify concentration compliance across thousand-mile networks. The shift is compressing demand for traditional drum-packaged reference standards while expanding service contracts for calibration and sensor maintenance.
EPA New Source Performance Standards for oil and gas facilities are tightening fugitive emission accounting for odorant storage and handling equipment. Tank farm operators must upgrade vapor recovery and secondary containment systems to maintain operating permits. Gulf Coast terminals face the steepest retrofit timelines given their concentration of bulk mercaptan throughput.
Gas procurement departments are consolidating supplier relationships around integrated odorant-plus-service offerings rather than commodity chemical transactions. Large municipal utilities negotiate multi-year blanket contracts covering chemical supply, injection equipment lease, and compliance monitoring. This bundling concentrates purchasing power with vertically capable vendors and marginalizes pure-play chemical distributors in the United States Midwest and Northeast utility markets.
Ethyl Mercaptan Market Segmentation
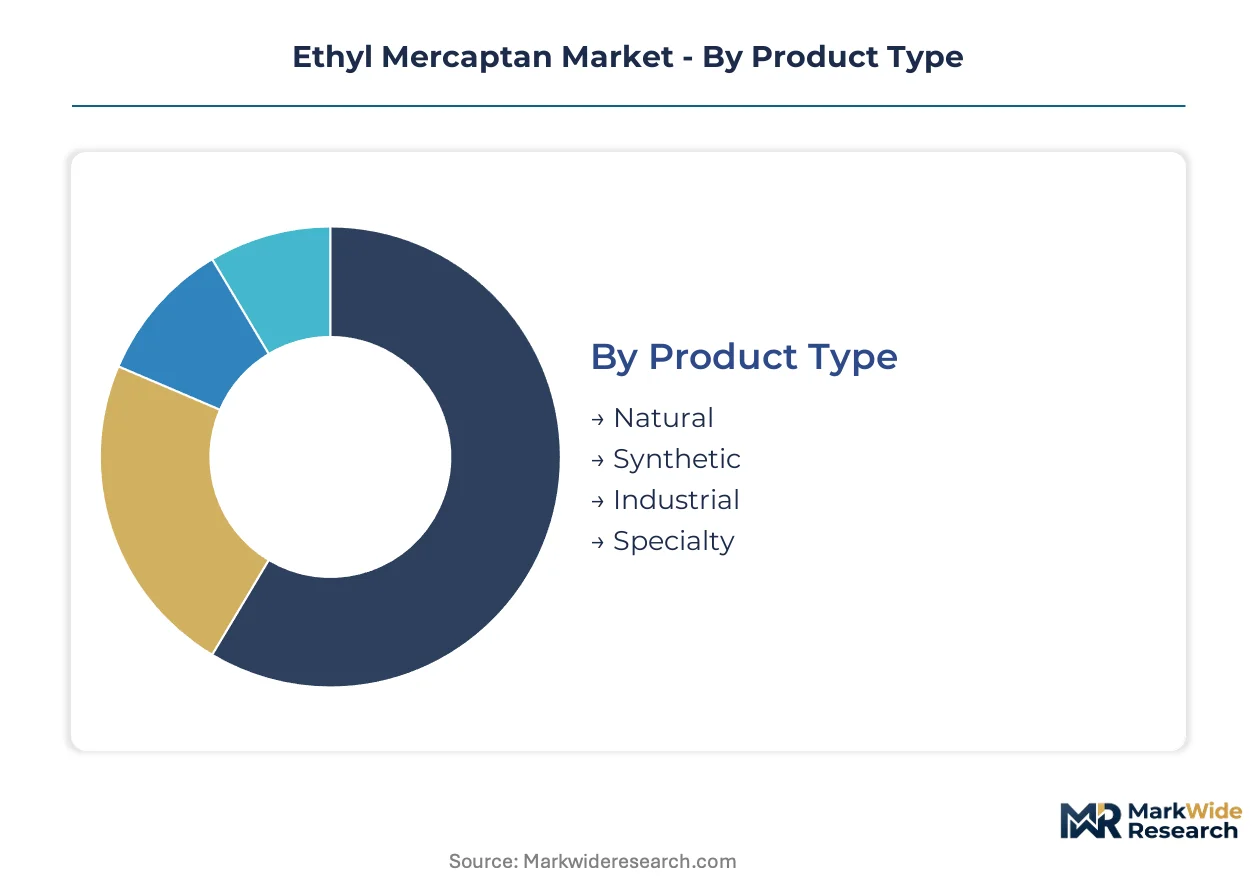
Segmentation in ethyl mercaptan markets reveals how purity grades, packaging formats, and application specifications create divergent margin profiles and service intensity requirements across the value chain. Understanding these divisions exposes where supplier capabilities must stretch beyond commodity chemical delivery.
Product Type:
After-sales service intensity varies sharply across purity tiers, with pharmaceutical-grade contracts demanding batch traceability and technical support that industrial odorant supply rarely requires.
- Synthetic:Manufactured through ethylene hydrogen sulfide reaction with consistent purity profiles above 99.5%, this grade dominates utility-scale natural gas odorant contracts across Texas and Louisiana pipeline networks where EPA concentration mandates enforce tight specification windows.
- Specialty:Ultra-low impurity formulations for active pharmaceutical ingredient synthesis command intensive quality documentation and regulatory filing support; demand concentrates with CDMOs in New Jersey and Massachusetts where FDA validation protocols extend sales cycles but multiply contract values.
- Natural:Derived from petroleum refining byproduct recovery, this grade serves regional chemical reagent distributors with lower purity tolerance.
- Industrial:Intermediate purity for agricultural intermediate production where cost sensitivity outweighs specification stringency.
By volume, Synthetic leads. By growth pace, Specialty is ahead.
End Use Industry:
Cost tier stratification separates capital-intensive pipeline operators from price-sensitive agricultural formulators.
- Oil & Gas:Interstate pipeline operators and municipal gas utilities drive bulk demand through odorant injection systems; Gulf Coast midstream expansion and EPA leak detection mandates sustain volume pull for high-concentration blend formulations across Permian and Marcellus basin gathering networks.
- Pharmaceuticals:API manufacturers and contract development organizations absorb premium-grade supply with impurity thresholds below 50 ppm; regulatory filing support and stability documentation requirements extend supplier relationships beyond transactional chemical procurement.
- Chemical Manufacturing:Intermediate demand for pesticide precursors and polymerization regulators, concentrated in Gulf Coast petrochemical corridors.
- Agriculture:Herbicide and fungicide intermediate production where sulfur chemistry cost efficiency determines supplier selection.
Oil & Gas anchors volume absorption. Pharmaceuticals exhibits the steepest margin expansion trajectory.
Packaging Type:
Customer type dictates format selection, with integrated pipeline operators rejecting drum logistics that laboratory reagent distributors require.
- Tankers:Bulk liquid transport in dedicated chemical tank trucks serves utility-scale odorant injection facilities; Gulf Coast terminal concentration enables just-in-time delivery contracts with pipeline operators who reject inventory carrying costs.
- Drums:Standard 55-gallon steel containers sustain chemical reagent distributors and regional blenders with lower throughput requirements; stable revenue pools persist despite slower volume growth relative to bulk shipment formats.
- Cylinders:Pressurized containment for high-purity pharmaceutical and specialty chemical applications requiring inert atmosphere preservation.
- Bottles:Small-volume packaging for analytical reference standards and laboratory research supply.
Tankers dominate tonnage movement. Cylinders deliver the highest revenue per kilogram.
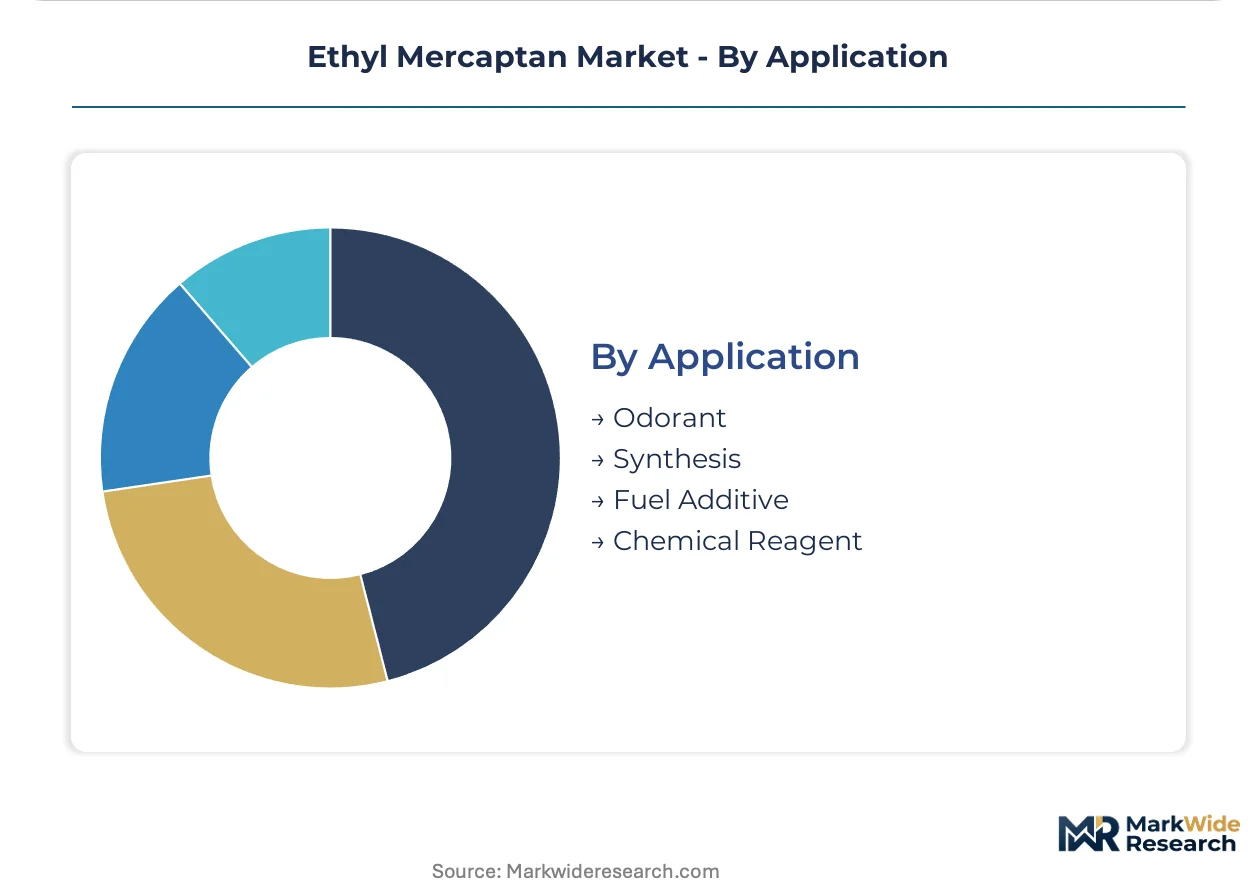
Application:
Supply concentration in odorant-grade production creates margin pressure on synthesis and reagent applications where specification differentiation narrows.
- Odorant:Natural gas and LPG odorization remains the primary industrial purpose; EPA Clean Air Act enforcement tightens detection threshold requirements, forcing reformulation investments and concentration standard upgrades across United States distribution networks.
- Synthesis:Pharmaceutical and agrochemical intermediate production demands ultra-low impurity grades; CDMO partnerships in New Jersey and Massachusetts require stability data packages and regulatory submission support that commodity suppliers cannot provide.
- Chemical Reagent:Analytical and research applications with stable but slow-growing demand profiles.
- Fuel Additive:Lubricant and refining process applications competing with alternative sulfur chemistry solutions.
Odorant commands volume leadership. Synthesis is climbing fastest on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA mandates on gas leak detection are tightening odorant concentration standards across United States distribution networks, while parallel regulatory developments in other major economies are reshaping regional demand patterns for ethyl mercaptan supply.
United States
Gulf Coast petrochemical corridor concentration drives synthetic production economics, with Texas and Louisiana refineries supplying bulk odorant to Permian and Marcellus basin pipeline networks. EPA Clean Air Act enforcement mandates lower detection thresholds for odorless gas releases. Houston-area terminal operators face accelerated retrofit timelines for vapor recovery systems under New Source Performance Standards.
Germany
Industrial gas utilities along the Rhine-Ruhr corridor absorb specialty-grade mercaptan for precision odorant injection systems serving municipal distribution networks. ECHA REACH compliance requirements govern volatile organic compound handling across chemical manufacturing facilities. BASF Ludwigshafen complex anchors regional synthesis capacity for pharmaceutical-grade applications requiring ultra-low impurity thresholds.
China
State-owned pipeline operators extend odorant infrastructure across Sichuan-Chongqing shale gas fields and Xinjiang coal-to-gas conversion projects. MIIT industrial standards for city gas distribution tighten safety specifications for odorant concentration monitoring. Yangtze River Delta chemical clusters near Shanghai concentrate domestic production capacity for both synthetic and natural-grade mercaptan derivatives.
India
City gas distribution expansion under the Petroleum and Natural Gas Regulatory Board mandate drives odorant procurement across Gujarat, Maharashtra, and Delhi-NCR networks. BIS certification requirements for LPG odorization create specification barriers for imported chemical supply. Reliance Industries Jamnagar complex leverages refinery integration to serve regional petrochemical intermediate demand.
Saudi Arabia
Saudi Aramco master gas system expansion and residential LPG distribution networks sustain bulk odorant absorption across Eastern Province industrial zones. SASO national standards for gas safety equipment shape import specification requirements for odorant injection systems. Jubail petrochemical city concentration enables captive hydrogen sulfide feedstock access for regional mercaptan synthesis.
Ethyl Mercaptan Market Competitive Landscape
On the supply side, the industry is consolidating around integrated petrochemical majors with captive feedstock positions and specialized mercaptan technology leaders with controlled distribution networks. Three strategic archetypes dominate: Gulf Coast refiners leveraging ethylene-hydrogen sulfide reaction economics, European chemical multinationals with pharmaceutical-grade certification capabilities, and Chinese regional producers serving cost-sensitive agricultural intermediate markets. Capacity expansion and strategic partnerships represent the dominant competitive moves, with odorant-plus-service bundling displacing commodity chemical transactions.
Among United States-based integrated producers, ExxonMobil and Chevron Phillips Chemical exemplify the refiner-archetype with Gulf Coast concentration, while Huntsman International occupies a position within the specialty technology tier through dedicated mercaptan process leadership. European presence is anchored by Evonik and Arkema, representing the quality-certification archetype for pharmaceutical and industrial gas applications. Chinese supply is fragmented across regional entities including Hangzhou Dayangchem and Hebei Yanxi Chemical, which sit within the cost-optimized intermediate segment serving agricultural and regional reagent markets.
| Leading Market Players |
|---|
| ExxonMobil |
| Huntsman International |
| Arkema |
| Hangzhou Dayangchem |
| Evonik |
| Chevron Phillips Chemical |
| Air Liquide |
| Hebei Yanxi Chemical |
| DowDuPont |
| Others |
Supply & Pricing Matrix
Houston-Galveston terminal concentration anchors bulk mercaptan throughput capacity, concentrating pricing power with integrated Gulf Coast producers who command premium contract terms from municipal utilities lacking alternative supply sources.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and industrial odorant tiers, with FDA-validated specialty batches commanding substantial premiums over EPA-mandated utility specifications. Three-tier pricing structure across premium synthesis grades, standard odorant formulations, and economy natural-grade derivatives reflects purity thresholds and documentation burdens. Cost compression in industrial odorant supply is intensifying because ethylene feedstock volatility compresses margin stability for non-integrated producers. Agricultural intermediate buyers exhibit highest price sensitivity, while interstate pipeline operators absorb premium pricing for guaranteed supply security.
Supply Chain Analysis
Contract manufacturing concentration rests with captive Gulf Coast refiners and dedicated mercaptan technology specialists rather than independent toll producers. Geographic supply concentrates in the United States, Germany, and China, with each hub serving distinct specification tiers. Raw material dependencies center on ethylene, hydrogen sulfide, and ethanol feedstocks sourced from adjacent refinery operations. Single-source vulnerability runs through hurricane-exposed Texas and Louisiana production clusters. Distribution runs through dedicated chemical tanker fleets serving utility injection facilities, with drum logistics sustaining regional reagent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethyl mercaptan demand sits in early-cycle expansion as EPA methane reduction mandates extend odorant performance requirements beyond federal baselines, accelerating specification upgrades across United States distribution networks.
For Market Incumbents: Build regulatory certification moats by securing state-level methane mandate pre-qualifications ahead of California and Colorado framework implementations. Deepen backward integration into hydrogen sulfide recovery from refinery streams to neutralize feedstock volatility exposure. Capture tertiary butyl mercaptan substitution threats through reformulation partnerships that lock in long-term odorant blend contracts.
For New Entrants and Emerging Players: Pursue modular odorant skid system deployment targeting rural gas utilities lacking specialized chemical handling infrastructure. Pharmaceutical-grade synthesis represents the most penetrable white-space segment, with CDMO partnerships in New Jersey and Massachusetts requiring stability documentation capabilities that commodity suppliers cannot fulfill. Lead with regulatory filing support bundled with ultra-low impurity supply to differentiate from transactional chemical distributors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated odorant-plus-service vendors with multi-year municipal utility blanket contracts covering chemical supply, injection equipment lease, and compliance monitoring. Long-term viability centers on Gulf Coast production assets with captive ethylene access and vapor recovery system retrofit completion. Acquisition target archetypes include specialty mercaptan technology leaders with controlled distribution networks. Watch for EPA New Source Performance Standards enforcement acceleration as the inflection indicator for supplier consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Sulfide Recovery | Captive feedstock access neutralizes margin volatility from refinery operating rate fluctuations. |
| Pharmaceutical-Grade Certification Investment | FDA validation protocols extend sales cycles but multiply contract values with CDMO partners. |
| Modular Odorant Skid System Deployment | Pre-engineered injection systems reduce field installation complexity for rural gas utilities. |
| Long-Term Utility Blanket Contract Negotiation | Multi-year chemical-plus-service bundles concentrate purchasing power with vertically capable vendors. |
| Vapor Recovery System Retrofit Acceleration | EPA New Source Performance Standards compliance maintains operating permits for Gulf Coast terminals. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with odorant procurement managers at interstate pipeline operators, technical directors at pharmaceutical CDMOs, plant managers at Gulf Coast mercaptan synthesis facilities, and distribution channel partners serving municipal gas utilities. Secondary validation drew from EPA enforcement databases, DOT hazardous materials incident reports, SEC 10-K filings of integrated petrochemical majors, and trade flow data through Houston-Galveston customs districts. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down production capacity assessments across Texas and Louisiana corridor assets.
Calibration against historical price realization data and documented contract award values anchored volume and value outputs across the modeling period. Segmentation dimensions modeled include purity grade tier, end-use industry concentration, packaging format, and regional regulatory cluster. CAGRs were derived from slope analysis of adoption curves and capacity expansion announcements. Industry-specific forecast inputs incorporated EPA leak detection threshold revision timelines and state methane mandate implementation schedules.
Sensitivities concentrate around hurricane disruption frequency in Gulf Coast production zones, ethylene feedstock price volatility, and tertiary butyl mercaptan substitution rates in LPG distribution contracts. Forecasts reflect assumptions regarding regulatory enforcement consistency and pipeline network expansion cadence. Cross-checking against EIA natural gas distribution infrastructure investment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Lithium Derivatives Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
North America Lactic Acid Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
Europe Ammonium Nitrate Market
Bulk Chemicals
United States Starch Derivatives Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
Sodium Bicarbonate Market
Bulk Chemicals
GCC Calcium Chloride Market
Bulk Chemicals
Europe Caustic Soda Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Borates Market
Bulk Chemicals
Ammonium Bicarbonate Market