
 Global Butyric Acid Market | 2026-2036
Global Butyric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Butyric Acid Market Analysis
Multi-source procurement among derivative manufacturers is broadening as buyers reduce reliance on single fermentation houses. Celanese Corporation leverages its acetyls platform to secure cost-advantaged butyric acid feedstock for downstream esters. OXEA GmbH anchors European supply through oxo-synthesis integration, while Kemin Industries, Inc. specializes in microencapsulated butyrate formats for animal nutrition.
Butyric acid is a short-chain carboxylic acid with the molecular formula C4H8O2, produced synthetically via oxo-synthesis of propylene or naturally through carbohydrate fermentation by Clostridium strains; it functions primarily as a platform chemical for esters, salts, and flavor precursors across food, pharmaceutical, and animal health applications. Synthetic butyric acid dominates volume owing to scale and cost structure, though natural butyric acid commands premium positioning in clean-label food preservatives where EU flavoring regulations restrict petrochemical-derived additives. Animal feed applications represent the fastest-expanding consumption pool, driven by antibiotic-replacement protocols that elevate butyrate salts in gut-health formulations for broiler and swine operations.
REACH registration requirements and EFSA feed additive evaluations shape product specifications and market access across Europe, while FDA Center for Veterinary Medicine oversight governs butyrate inclusion in US animal diets. China's GB standards and NMPA pharmaceutical excipient rules add compliance layers for exporters targeting fermentation-derived grades. Stakeholders must monitor regulatory divergence between synthetic and natural origin pathways, as classification under emerging green chemistry frameworks will determine tariff treatment and eligibility for public procurement programs.
Market Dynamics
Antibiotic-replacement mandates across livestock sectors are compressing substitution timelines and forcing feed compounders to lock in butyrate supply contracts ahead of formulation approvals.
Growth Catalysts
- EFSA feed additive re-evaluations:Renewed safety clearances for butyrate salts in poultry and swine diets are expanding permissible inclusion rates across European Union member states.
- Fermentation capacity clusters:Concentrated carbohydrate processing infrastructure in Shandong and Jiangsu provinces is lowering unit costs for natural-grade material.
- Clean-label preservative demand:EU flavoring regulations restricting petrochemical-derived additives in food applications are elevating fermentation-sourced butyric acid premiums.
Market Restraints
- Propylene feedstock volatility:Synthetic butyric acid producers face margin compression when oxo-synthesis input costs spike, given limited alternative feedstock pathways.
- Single-source fermentation risk:Derivative manufacturers dependent on individual Clostridium strain houses in China face supply interruption exposure during environmental compliance audits.
- Acetic acid substitution:Lower-cost short-chain acids in certain flavor precursor applications displace butyric acid where sensory profiles permit formulation flexibility.
Strategic Opportunities
- India pharmaceutical excipient demand:CDSCO tightening of excipient purity standards creates entry windows for fermentation-grade suppliers meeting USP-NF monograph specifications.
- Microencapsulation technology convergence:Coating advances combining lipid matrices with pH-triggered release are opening ruminant feed applications previously inaccessible to unprotected butyrate.
- Brazilian integrated poultry operations:ANVISA feed additive registration simplification is reducing time-to-market for gut-health formulations targeting contract grower networks.
Industry Challenges
- Clostridium strain engineering expertise:Fermentation houses struggle to recruit metabolic engineers capable of optimizing butyrate titers under anaerobic industrial conditions.
- REACH registration dossier complexity:Synthetic producers face extended data requirements for substance volume thresholds, delaying market access for new manufacturing entrants.
- Legacy esterification equipment retrofits:Batch reactor systems designed for conventional acid feedstocks require capital-intensive modifications to handle high-purity fermentation-derived inputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Butyric Acid Market |
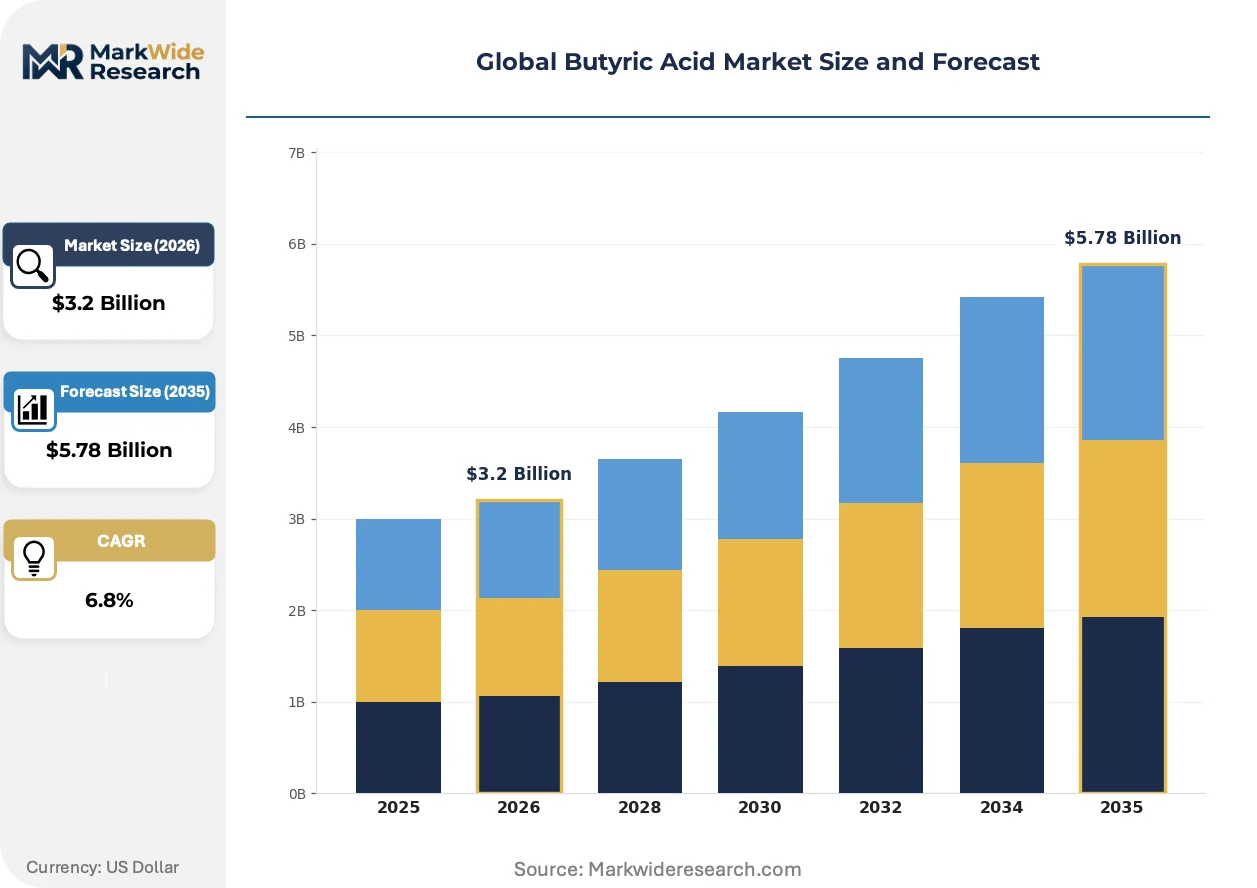
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
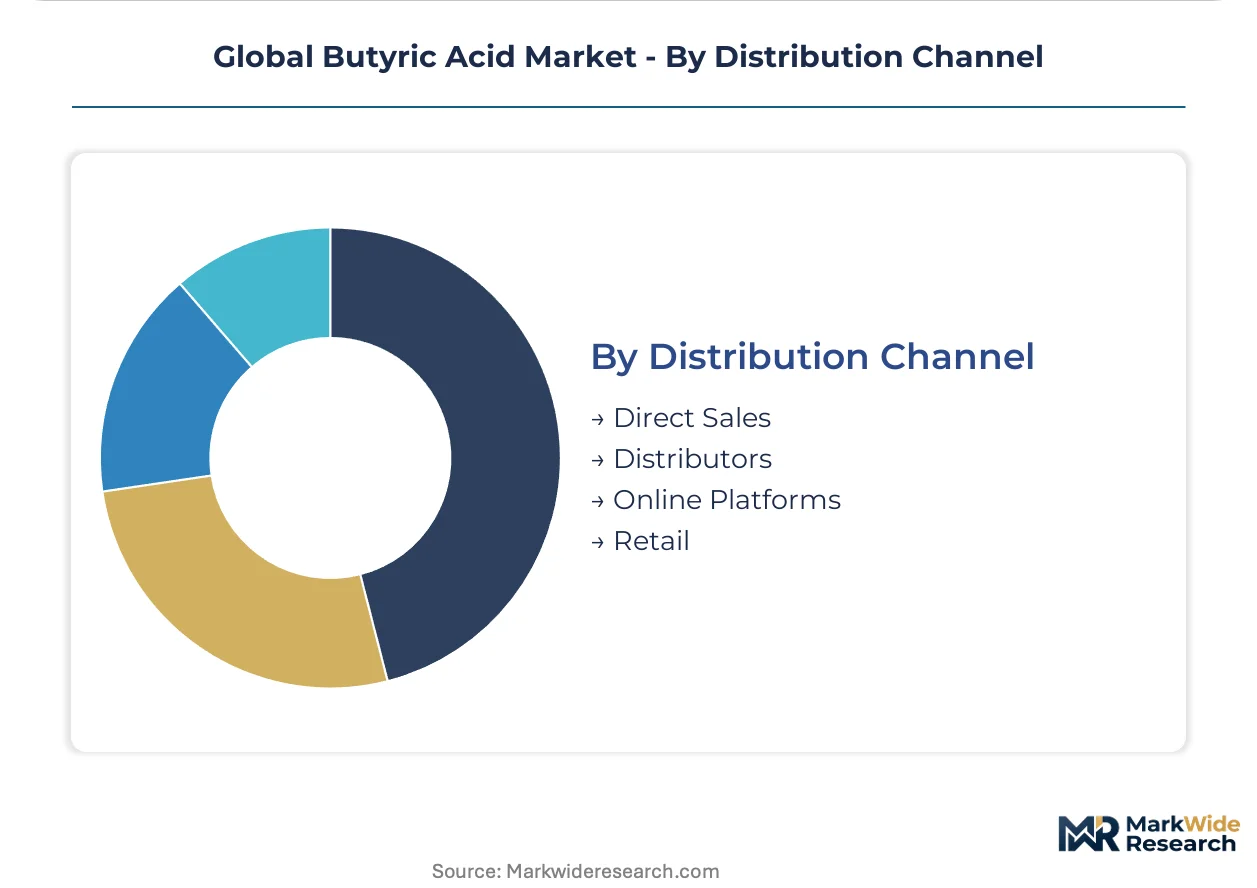
| Segmentation | Product Type: Natural Butyric Acid, Synthetic Butyric Acid, Butyric Acid Derivatives, Butyrate Salts Application: Food Preservatives, Pharmaceuticals, Animal Feed, Personal Care Products End User: Food Industry, Healthcare Sector, Agriculture, Cosmetic Industry Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail |
| Companies Covered | Tokyo Chemical Industry Co. Ltd., Celanese Corporation, Eastman Chemical Company, Merck KGaA, Kemin Industries, Inc., OXEA GmbH, BASF, Hangzhou Better ChemTech Ltd, Perstorp Holding AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Butyric Acid Market Emerging Trajectories
Process intensification and regulatory reclassification are compressing traditional production economics while opening application boundaries previously closed to butyric acid derivatives.
Continuous fermentation systems with integrated cell retention are automating the transition from batch-wise Clostridium cultivation to steady-state butyrate production. Animal nutrition compounders in Denmark and the Netherlands are adopting these volumes for microencapsulated broiler formulations. The shift is automating quality consistency improvements that reduce downstream purification costs.
REACH registration requirements for synthetic butyric acid are tightening purity benchmarks and documentation burdens for volume-based tonnage bands. ECHA substance evaluation workflows are extending dossier approval timelines for producers lacking full toxicological datasets. Food-grade and pharmaceutical-grade synthetic material destined for European markets faces the most pronounced compliance cost inflation.
Compound feed mills are consolidating procurement decisions at corporate level rather than delegating to individual plant managers. This centralization is displacing spot-market purchasing with multi-year supply agreements specifying origin certification and chain-of-custody documentation. The pattern is most visible across German and Polish integrated pork operations seeking antibiotic-free supply chain credentials.
Global Butyric Acid Market Segmentation
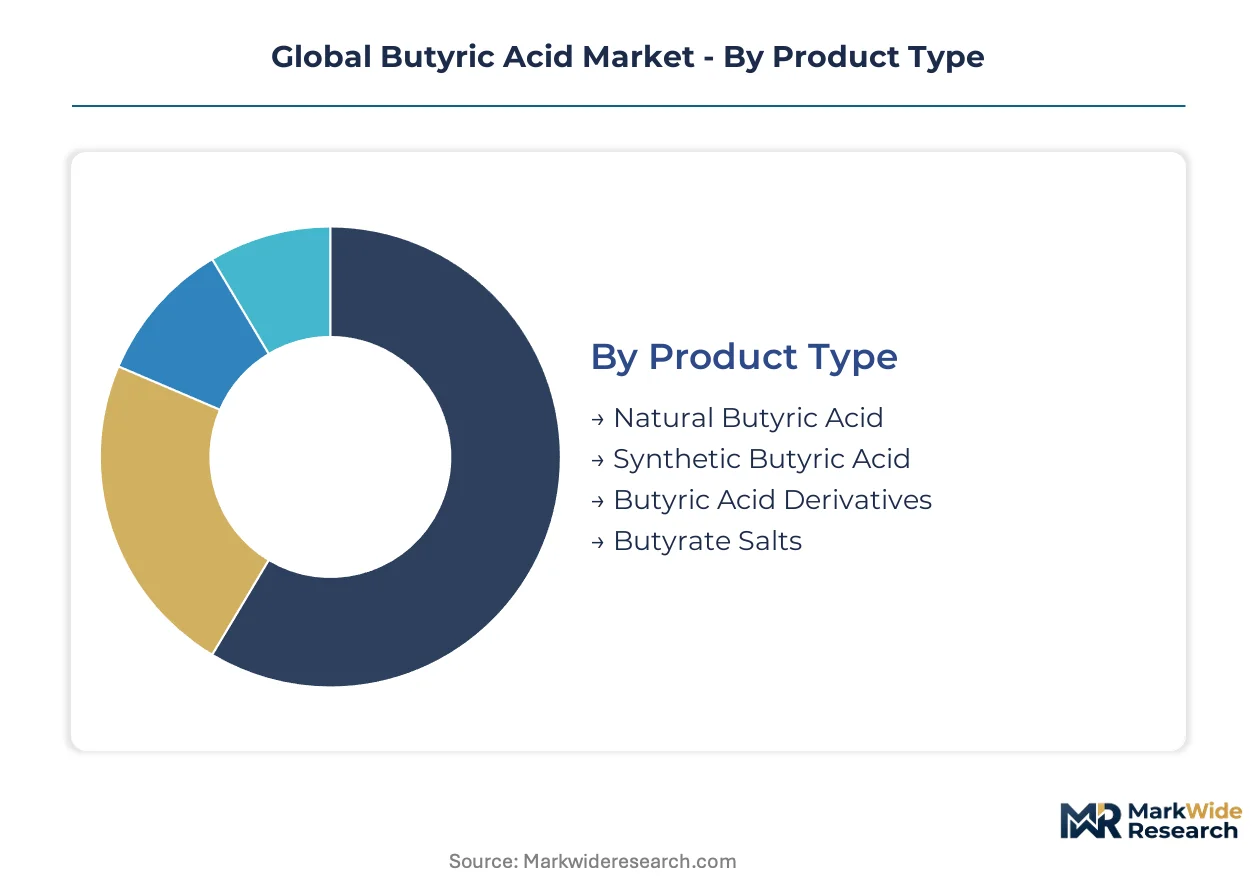
Butyric acid's bifurcated production pathways—petrochemical oxo-synthesis versus anaerobic fermentation—create distinct specification tiers that reshape procurement logic across end-use verticals. Segmentation clarity determines whether buyers prioritize cost efficiency, regulatory compliance, or clean-label positioning.
Product Type:
Synthetic material dominates bulk volume while fermentation-derived grades command premium positioning in regulated applications.
- Natural Butyric Acid:Carbohydrate fermentation by Clostridium strains yields material qualifying for EU flavoring regulations restricting petrochemical-derived additives. Clean-label food preservative demand in Germany and France concentrates procurement of fermentation-grade volumes certified under EFSA feed additive protocols.
- Synthetic Butyric Acid:Propylene oxo-synthesis generates cost-advantaged feedstock for downstream esterification. REACH registration dossiers for synthetic material face extended ECHA evaluation timelines, compressing margin structures for European market entrants lacking full toxicological datasets.
- Butyric Acid Derivatives:Ester and amide compounds extend application scope into flavor precursors and pharmaceutical intermediates.
- Butyrate Salts:Sodium and calcium butyrate formulations serve antibiotic-replacement protocols in poultry and swine gut-health applications.
Leading the category by volume: Synthetic Butyric Acid. Expanding most quickly: Natural Butyric Acid.
Application:
Regulatory mandates and formulation science determine where butyric acid displaces incumbent chemistries.
- Food Preservatives:Fermentation-sourced material satisfies EU restrictions on synthetic additives in dairy and baked goods. Clean-label positioning in Dutch and Danish retail channels elevates specification requirements for chain-of-custody documentation.
- Animal Feed:Butyrate salts integrate into antibiotic-free broiler and swine diets under FDA Center for Veterinary Medicine oversight. EFSA re-evaluations expanding permissible inclusion rates across EU member states are accelerating contract volume commitments from German and Polish integrated pork operations.
- Pharmaceuticals:USP-NF monograph compliance governs excipient-grade material for oral dosage forms.
- Personal Care Products:Ester derivatives contribute to fragrance compounding and skin-conditioning formulations.
Animal Feed generates the steepest volume expansion. Food Preservatives maintain the tightest specification premiums.
End User:
Procurement centralization at corporate level is displacing plant-level purchasing across integrated operations.
- Food Industry:Compound feed mills and food manufacturers drive specification divergence between cost-optimized synthetic grades and fermentation-sourced clean-label material.
- Healthcare Sector:Pharmaceutical excipient demand concentrates in India where CDSCO tightening of purity standards creates entry windows for fermentation-grade suppliers.
- Agriculture:Contract grower networks in Brazil source gut-health formulations following ANVISA feed additive registration simplification.
- Cosmetic Industry:Fragrance houses and personal care formulators utilize ester derivatives for sensory profiles.
Food Industry commands the largest procurement volumes. Healthcare Sector presents the steepest regulatory barriers to entry.
Distribution Channel:
Supply chain configuration varies with volume scale, certification complexity, and geographic concentration of demand.
- Direct Sales:Multi-year supply agreements specifying origin certification dominate procurement for German and Polish integrated pork operations seeking antibiotic-free credentials.
- Distributors:Regional chemical distributors aggregate fragmented demand from mid-scale compound feed mills and flavor houses.
- Online Platforms:Digital procurement channels serve small-volume buyers in personal care and specialty chemical segments.
- Retail:Limited direct-to-consumer presence for technical-grade material.
Direct Sales captures the highest-value contract volumes. Distributors maintain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene feedstock availability along the US Gulf Coast anchors North American synthetic production, while Shandong and Jiangsu fermentation clusters concentrate natural-grade capacity in China. Regulatory divergence between REACH, FDA, and NMPA frameworks is fragmenting specification requirements across destination markets.
United States
Antibiotic-free poultry and swine protocols drive butyrate salt demand from integrated operations in Iowa and North Carolina. FDA Center for Veterinary Medicine oversight governs feed additive registrations, compressing approval timelines for new suppliers. Houston-area petrochemical complexes supply cost-advantaged oxo-synthesis feedstock for downstream esterification.
Germany
EFSA feed additive re-evaluations expanding permissible inclusion rates accelerate contract commitments from Lower Saxony and North Rhine-Westphalia pork operations. REACH registration dossiers face extended ECHA evaluation timelines, elevating compliance costs for synthetic material. Bavarian compound feed mills centralize procurement decisions at corporate level.
China
Domestic fermentation capacity in Shandong and Jiangsu provinces scales rapidly to meet food-grade and pharmaceutical-grade demand. NMPA pharmaceutical excipient rules and GB standards add compliance layers for natural-grade exporters. Qingdao and Shanghai derivative manufacturing clusters integrate upstream carbohydrate processing infrastructure.
Brazil
Integrated poultry operations in São Paulo and Paraná contract for gut-health formulations following ANVISA feed additive registration simplification. Soybean meal processing residues feed regional fermentation initiatives. Campinas research clusters advance microencapsulation technology for ruminant applications.
India
CDSCO tightening of pharmaceutical excipient purity standards creates entry windows for fermentation-grade suppliers meeting USP-NF monograph specifications. Mumbai and Hyderabad formulation houses drive specification premiums for oral dosage grade material. Gujarat chemical parks host emerging esterification capacity targeting personal care derivatives.
Global Butyric Acid Market Vendor Landscape
Capacity expansion dominates the current landscape as fermentation houses in China and synthetic producers along the US Gulf Coast add parallel lines. The vendor base separates into three tiers: integrated petrochemical majors with oxo-synthesis platforms, specialized fermentation houses with Clostridium strain expertise, and microencapsulation technology specialists serving animal nutrition. Strategic archetypes include backward-integrated feedstock controllers, purity-grade specialists, and formulation technology licensors. M&A activity concentrates on fermentation asset acquisitions and geographic licensing arrangements.
Among petrochemical-integrated majors, Celanese Corporation and Eastman Chemical Company exemplify the synthetic production archetype through acetyls platform leverage. OXEA GmbH anchors the European supply position through oxo-synthesis integration. Kemin Industries, Inc. occupies the animal nutrition specialization tier with microencapsulated butyrate formats. These three entities represent distinct competitive vectors: feedstock security, regional regulatory compliance, and end-use formulation technology.
| Leading Market Players |
|---|
| Tokyo Chemical Industry Co. Ltd. |
| Celanese Corporation |
| Eastman Chemical Company |
| Merck KGaA |
| Kemin Industries, Inc. |
| OXEA GmbH |
| BASF |
| Hangzhou Better ChemTech Ltd |
| Perstorp Holding AB |
| Others |
Supply Flow & Price Mechanics
Propylene spot indices on the US Gulf Coast cascade through oxo-synthesis operations into three distinct pricing tiers for butyric acid derivatives. Fermentation-grade material from Shandong carbohydrate processors commands substantial premiums over synthetic feedstock as EU flavoring regulations restrict petrochemical-derived additives in clean-label applications. Contract compounders in Germany and Poland absorb these spreads through multi-year supply agreements that lock in origin certification.
Pricing Analysis
Certificate-of-origin bundling separates premium fermentation-grade butyrate from unbundled synthetic material lacking chain-of-custody documentation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with pharmaceutical-grade USP-NF material sitting at the apex. Cost compression in standard-tier synthetic grades is intensifying because propylene feedstock volatility compresses oxo-synthesis margins. Mid-scale compound feed mills exhibit highest price sensitivity, while integrated pork operations in Lower Saxony prioritize specification compliance over unit cost.
Supply Chain Analysis
Multi-supplier qualification mandates from German and Polish integrated operations force derivative manufacturers to maintain parallel relationships with both Shandong fermentation houses and US Gulf Coast petrochemical complexes. Geographic supply concentration centers on China, the United States, and Germany, with raw material dependencies spanning propylene feedstock, carbohydrate substrates, and Clostridium strain libraries. Single-source fermentation risk from individual strain houses during environmental compliance audits constitutes the primary structural vulnerability. Distribution runs through direct sales channels for high-volume contract accounts and regional chemical distributors for fragmented mid-scale demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into carbohydrate processing and captive Clostridium strain development defines the current competitive race as players seek feedstock security and regulatory-grade certification control.
For Market Incumbents: Lock in long-term supply agreements with Shandong fermentation clusters before EFSA feed additive re-evaluations expand permissible inclusion rates across EU member states. Prioritize microencapsulation technology licensing to defend against emerging biotechnology entrants with superior release-profile formulations. Capacity addition in Jiangsu province secures natural-grade volume for clean-label preservative demand in Dutch and Danish retail channels. For New Entrants and Emerging Players: Continuous fermentation systems with integrated cell retention offer a technology-first wedge into animal nutrition applications previously closed to batch-wise producers. Target Brazilian contract grower networks following ANVISA feed additive registration simplification as the most penetrable geography. Pursue joint development agreements with Campinas research clusters to access microencapsulation IP for ruminant feed formulations. For Investors and Strategic Acquirers: Distressed-cycle entries favor fermentation asset specialists in China facing temporary margin compression from propylene price spikes rather than structural demand erosion. Five-to-ten-year viability hinges on regulatory divergence between synthetic and natural origin pathways under emerging green chemistry frameworks. Monitor ECHA substance evaluation workflows for extended dossier approval timelines as the inflection signal for synthetic producer distress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | Captive carbohydrate processing in Shandong reduces unit costs for natural-grade material by eliminating third-party substrate markups. |
| Microencapsulation Technology Licensing | pH-triggered release formulations from Campinas research clusters open ruminant feed applications previously inaccessible to unprotected butyrate. |
| Long-term Supply Agreement with Integrated Pork Operations | Multi-year contracts with German and Polish operations displace spot-market purchasing and lock in antibiotic-free supply chain credentials. |
| Joint Venture with Clostridium Strain Engineering Specialists | Partnerships with metabolic engineering houses address capability scarcity in optimizing butyrate titers under anaerobic industrial conditions. |
| Green Chemistry Certification Program | EFSA feed additive protocols and REACH registration alignment determine eligibility for public procurement programs and tariff treatment. |
Methodological Framework
Trade flow databases, EFSA feed additive registration filings, and SEC 10-K disclosures from petrochemical majors formed the secondary backbone for volume and value estimation. Primary interviews with compound feed procurement directors, fermentation plant managers, pharmaceutical excipient quality officers, and animal nutrition formulation scientists validated production capacity figures and substitution timelines. Bottom-up and top-down triangulation reconciled derivative demand estimates against upstream butyric acid supply capacity across both oxo-synthesis and fermentation pathways.
Bottom-up modeling built consumption estimates from application-level inclusion rates and livestock population forecasts, while top-down analysis cross-checked against regional chemical production indices. Segmentation dimensions spanned production pathway, grade tier, end-use vertical, and regional regulatory cluster throughout the forecast period. CAGRs derived from fitted trend lines incorporating EFSA re-evaluation timelines, antibiotic-replacement protocol adoption curves, and fermentation capacity expansion announcements from Shandong and Jiangsu provinces.
Several conditions sit outside the modeled scope, including unforeseen Clostridium strain patent litigation, abrupt propylene supply disruptions from Gulf Coast weather events, and radical shifts in EU flavoring regulation stringency. Deviation in ECHA substance evaluation timelines or FDA Center for Veterinary Medicine approval velocities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Lithium Benzoate Market
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
Europic Chloride Market
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
Potassium Sulphate Market
Bulk Chemicals
Sodium Nitrate Market
Bulk Chemicals
Furfuryl Alcohol Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
Mancozeb Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Triazine Market