
 Isoprene Market | 2026-2036
Isoprene Market Size, Share, and Industry Trends Forecast 2026-2036
Isoprene Market Analysis
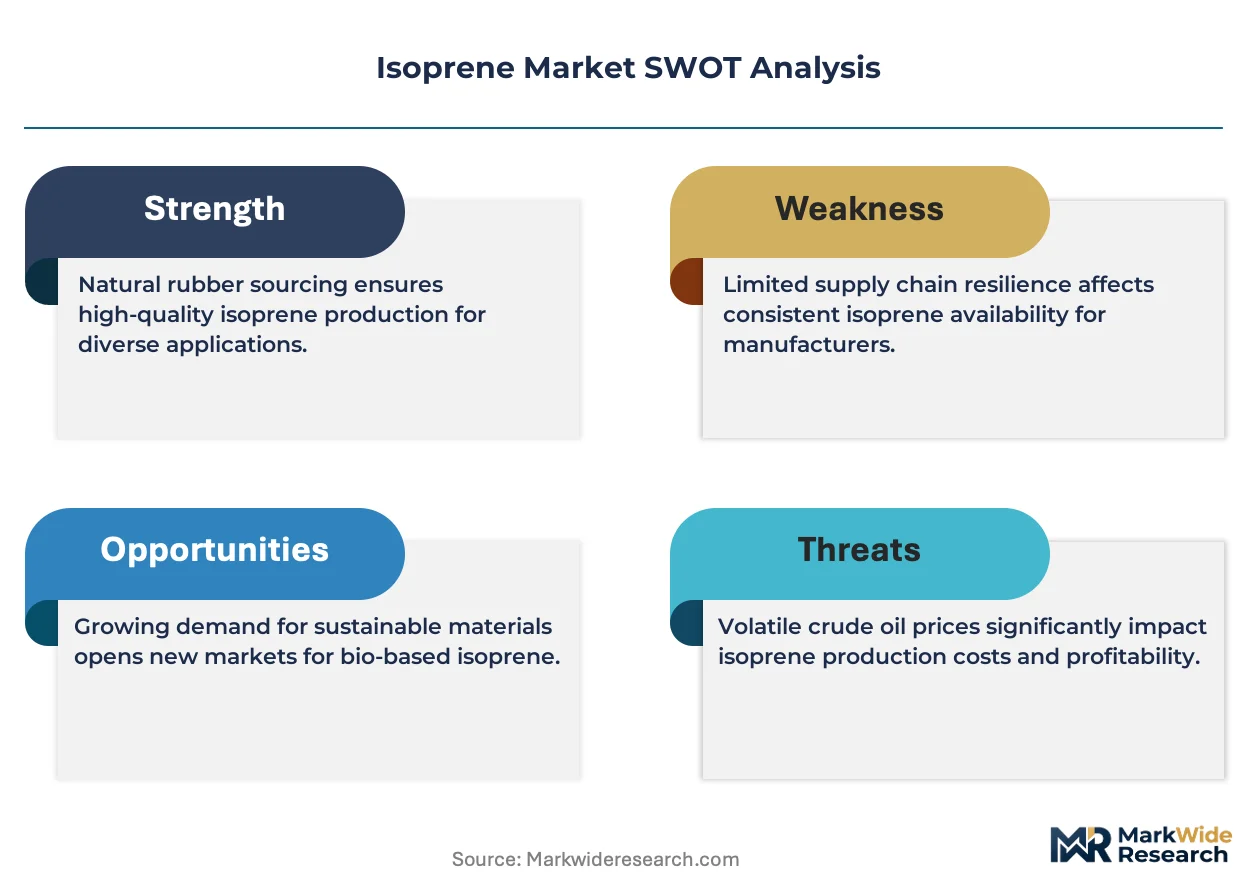
Project finance for on-purpose dehydrogenation units is reshaping competitive entry in isoprene production. Nizhnekamskneftekhim leverages captive naphtha supply to sustain cost leadership across CIS markets. Kuraray Co., Ltd. anchors premium polyisoprene capacity for medical glove applications in Japan. PJSC SIBUR Holding competes through integrated petrochemical corridors linking feedstock to derivative output.
Isoprene is a conjugated diene hydrocarbon with the formula C₅H₈, produced via steam cracking of naphtha or catalytic dehydrogenation of isopentane, serving primarily as a monomer for synthetic rubber and specialty polymers. Rubber applications dominate value capture given tire sector pull, while Adhesives segments expand fastest on packaging and construction bonding demand. Coatings formulations for automotive refinishing represent a concentrated margin pool where specification grades command quality premiums.
EPA emission standards for petrochemical crackers constrain US Gulf Coast expansion timelines, while REACH registration requirements in Europe elevate compliance costs for imported monomer grades. China's MEE enforces dual carbon goals that push producers toward lower-intensity process routes. Stakeholders must track regulatory divergence between jurisdictions to calibrate capacity placement and product certification investments.
Market Dynamics
Bio-based feedstock technology is displacing conventional naphtha cracking as the dominant production pathway, reshaping capital allocation and regional competitiveness across isoprene supply chains.
Growth Catalysts
- REACH registration requirements:European chemical compliance frameworks are elevating specification-grade premiums for certified medical polyisoprene, pulling investment toward high-purity production assets.
- Tire sector demand concentration:Asian automotive OEMs are expanding radial tire capacity in Thailand and Vietnam, creating dedicated offtake agreements for solution-polymerized rubber grades.
- On-purpose dehydrogenation:Catalytic isopentane-to-isoprene units are reducing feedstock cost volatility versus steam cracking economics, enabling project finance for greenfield Middle Eastern complexes.
Market Restraints
- Crude C5 stream concentration:Over 70% of merchant isoprene derives from Asian ethylene crackers, creating geographic supply vulnerability to regional naphtha price spikes.
- EPA New Source Review:US Gulf Coast expansions face 18-24 month permitting delays for emissions-intensive cracking units, constraining North American supply response.
- Natural rubber substitution:Hevea brasiliensis latex competes in medical glove and thread applications, capping price elasticity for synthetic polyisoprene in cost-sensitive segments.
Strategic Opportunities
- Indonesia downstream integration:Domestic tire manufacturing zones in Karawang and Cikarang lack local isoprene supply, creating import-substitution openings for integrated petrochemical investors.
- China dual carbon alignment:MEE enforcement of carbon intensity benchmarks is accelerating bio-based fermentation pilot projects, positioning early movers for preferential state-backed financing.
- Automotive refinishing coatings:Specification-grade isoprene-derived resins for OEM touch-up paints command 40-60% margin premiums over commodity rubber applications in European and Japanese markets.
Industry Challenges
- Catalytic process engineering talent:Dehydrogenation unit design and zeolite catalyst optimization require specialized skill sets concentrated at a handful of European and Japanese technology licensors.
- Polymerization reactor capex:Solution SBR and IR lines demand $200-400 million per train investment, stretching mid-cap producer balance sheets and extending payback periods.
- ISO 10993 biocompatibility certification:Medical device-grade polyisoprene requires 24-36 month validation timelines, delaying revenue recognition for new purification capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoprene Market |
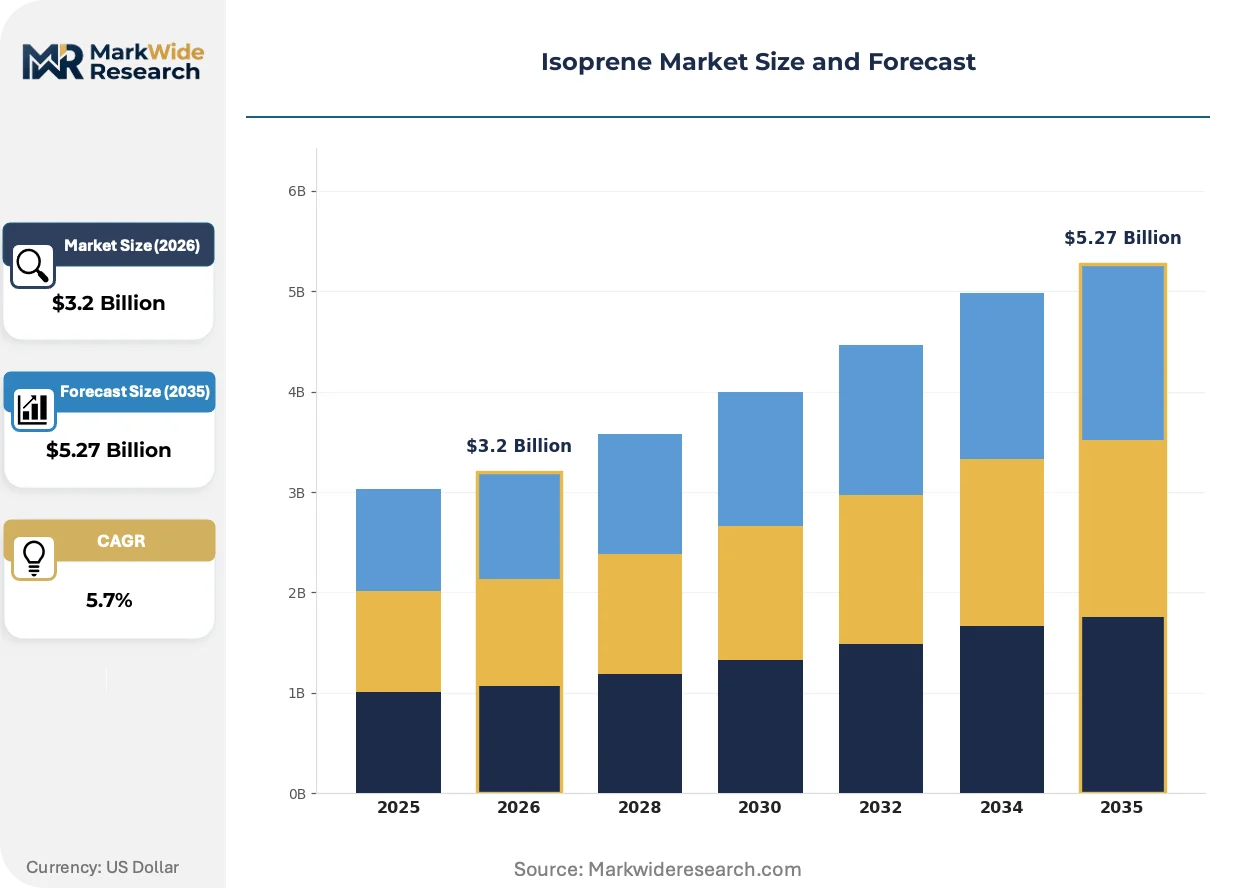
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.27 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber, Adhesives, Coatings, Fibers End User: Automotive, Construction, Consumer Goods, Healthcare Distribution Channel: Direct Sales, Wholesalers, Online Retail, Distributors Application: Footwear, Tires, Sealants, Latex Products |
| Companies Covered | Exxon Mobil Corporation, Nizhnekamskneftekhim, Shell plc, Kuraray Co., Ltd., JSR Corporation, PJSC SIBUR Holding, China Petrochemical Corporation, Kraton Corporation, LyondellBasell Industries Holdings B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoprene Market Emerging Trajectories
Process intensification and digital control systems are compressing unit economics for bio-based production routes, while regulatory carbon accounting reshapes feedstock sourcing decisions across major consuming regions.
Advanced process control using machine-learning-driven reactor optimization is digitizing yield management in continuous dehydrogenation units. European specialty chemical producers are piloting these systems at demonstration scale. Real-time kinetic modeling is enabling 3-5% throughput gains without capital expansion.
China's MEE dual carbon enforcement mechanism is tightening emissions intensity thresholds for petrochemical crackers in Shandong and Zhejiang provinces. Producers are responding by blending bio-based C5 feedstocks to meet carbon accounting benchmarks. This regulatory pressure is accelerating partnerships between fermentation technology developers and state-owned refinery operators.
Long-term offtake contracting is replacing spot purchasing among tire manufacturers with annual volume commitments exceeding 10,000 metric tons. This procurement consolidation is squeezing merchant market liquidity and favoring integrated producers with captive rubber polymerization capacity. The shift is most pronounced in procurement departments at Korean and Chinese automotive tire suppliers.
Isoprene Market Segmentation
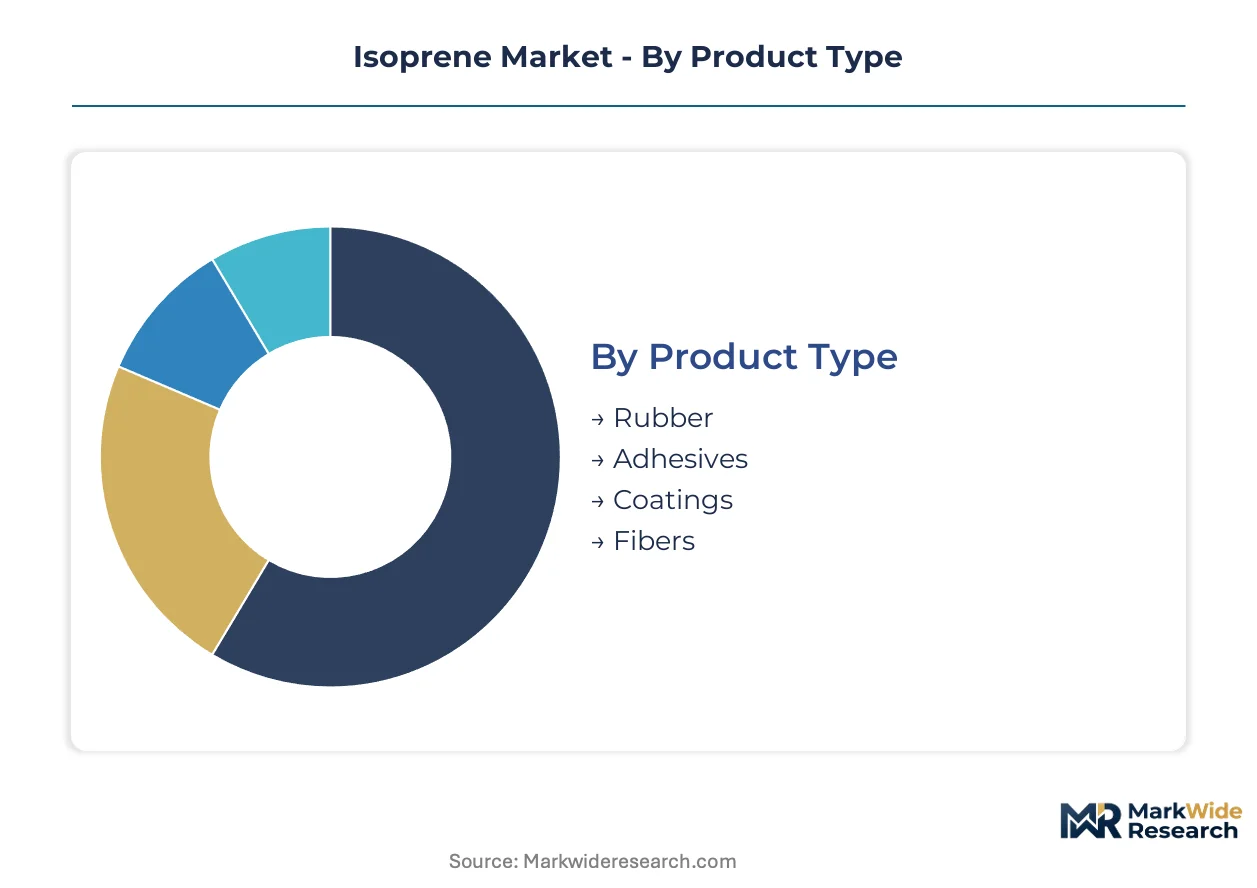
Isoprene derivatives serve fundamentally different technical requirements across rubber compounding, adhesive formulation, and coating resin applications. Segment boundaries determine specification grades, purity thresholds, and certification protocols that govern supplier-customer relationships. Understanding these divisions reveals where margin pools concentrate versus where volume commoditization dominates.
Product Type:
After-sales service intensity varies sharply across these categories, with medical-grade rubber demanding 24-36 month biocompatibility validation support while coatings resins require minimal technical assistance post-delivery.
- Rubber:Polyisoprene and styrene-isoprene-styrene block copolymers constitute the dominant product form, with solution-polymerized grades commanding specification premiums for tire tread and sidewall applications. Demand concentrates in Thai and Vietnamese radial tire manufacturing zones where automotive OEMs have expanded capacity, driven by long-term offtake contracting patterns among Korean and Chinese tire suppliers.
- Adhesives:Tackifying resins derived from isoprene oligomers serve hot-melt and pressure-sensitive formulations requiring precise softening point control. Construction bonding and packaging sealant applications in Germany and Japan are expanding most quickly, pulled by REACH-compliant certification requirements that elevate specification-grade premiums.
- Coatings:Isoprene-derived resins for automotive refinishing and industrial maintenance applications.
- Fibers:Specialty elastomeric fiber applications in textile and industrial belting.
By volume, Rubber leads. By growth pace, Adhesives is ahead.
End User:
Cost tier differentiation separates these segments, with Healthcare commanding 40-60% margin premiums over Automotive for equivalent purity grades due to ISO 10993 validation requirements.
- Automotive:Tire manufacturers and automotive OEMs represent the foundational demand base, with procurement departments consolidating toward annual volume commitments exceeding 10,000 metric tons. Thai and Vietnamese production zones lack local isoprene supply, creating import dependency for solution-polymerized rubber grades.
- Healthcare:Medical device manufacturers and glove producers require ultra-high-purity polyisoprene meeting biocompatibility standards. Japanese medical glove applications anchor premium capacity, though Hevea brasiliensis latex competition caps price elasticity in cost-sensitive segments.
- Construction:Sealant and adhesive formulators serving building envelope and infrastructure applications.
- Consumer Goods:Footwear, sporting equipment, and household product manufacturers.
Automotive generates the largest absolute offtake. Healthcare shows the steepest margin expansion trajectory.
Distribution Channel:
Supply chain configuration determines channel viability, with bulk liquid isoprene favoring direct sales while packaged derivatives move through intermediaries.
- Direct Sales:Large tire manufacturers and integrated rubber compounders procure isoprene monomer and solution-polymerized grades through dedicated supply agreements. This channel captures the majority of volume given procurement consolidation trends among Korean and Chinese automotive suppliers.
- Distributors:Regional chemical distributors serve mid-scale adhesive and coatings formulators requiring smaller lot sizes and technical support.
- Wholesalers:Bulk commodity grades for standard industrial applications.
- Online Retail:Emerging channel for specialty grades and small-volume laboratory quantities.
Direct Sales commands volume leadership. Distributors are gaining share fastest among specialty grade customers.
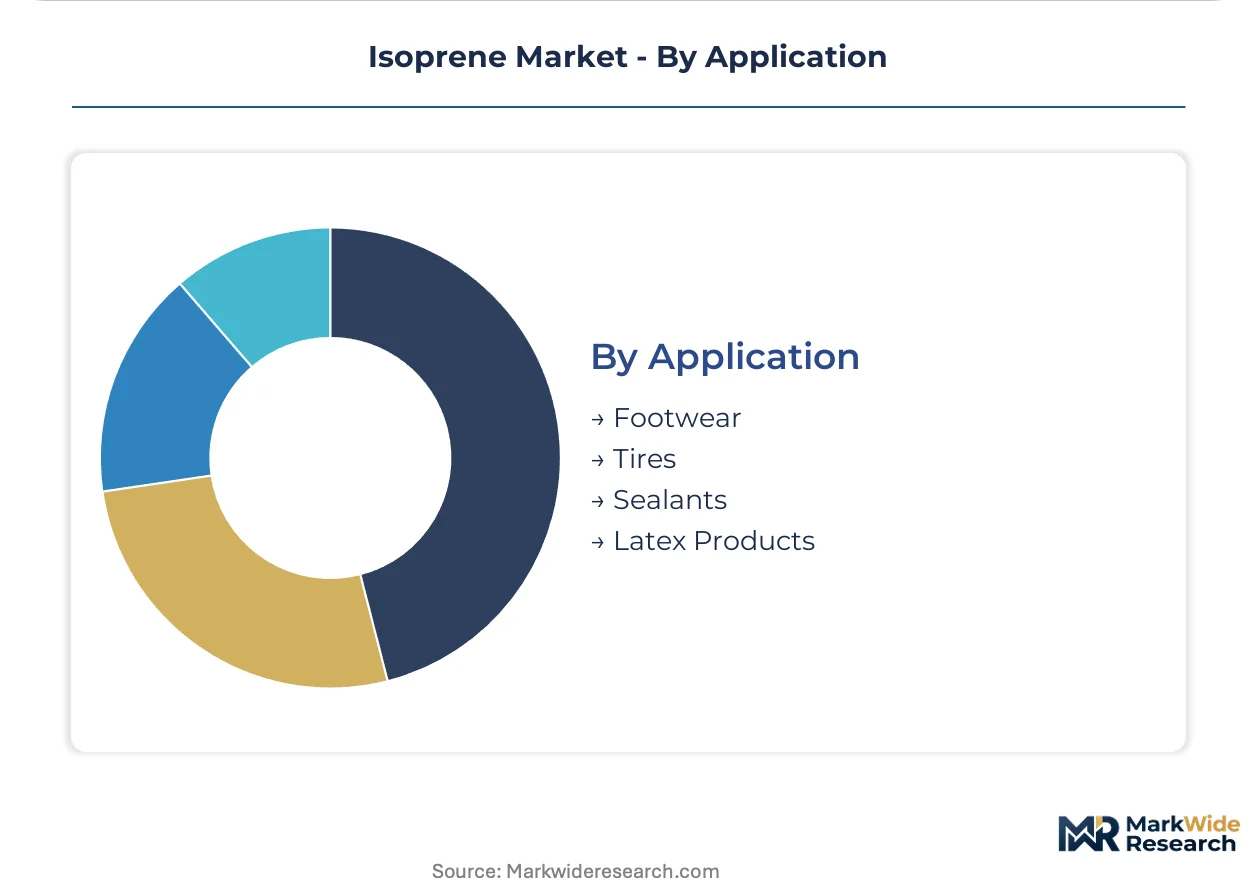
Application:
Customer type segmentation separates specification-driven from price-sensitive procurement, with Tires and Latex Products occupying opposite ends of this spectrum.
- Tires:Radial passenger and commercial vehicle tires consume the majority of polyisoprene and SIS copolymer output, with tread and sidewall formulations demanding precise molecular weight distribution. Chinese and Indian tire capacity expansion is concentrating demand, though natural rubber substitution pressure persists in cost-sensitive segments.
- Sealants:Construction and automotive sealing applications require tailored viscosity and adhesion properties. European building envelope regulations are pulling investment toward REACH-compliant formulation grades.
- Footwear:Soling and upper applications in athletic and industrial footwear.
- Latex Products:Medical gloves, condoms, and thread applications where Hevea brasiliensis competition constrains synthetic polyisoprene penetration.
Tires dominates by volume. Sealants is climbing the fastest on construction and automotive bonding demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isoprene trade flows tilt heavily toward net-importing tire manufacturing zones, with Asian crackers supplying raw monomer to derivative processors across Southeast Asia and Europe. Export capacity concentrates in naphtha-rich economies with integrated petrochemical infrastructure.
China
Shandong and Zhejiang provinces house the majority of domestic ethylene cracking capacity feeding merchant isoprene supply. MEE dual carbon enforcement tightens emissions intensity thresholds, pushing producers toward bio-based C5 blending to meet carbon accounting benchmarks. Qingdao and Ningbo industrial clusters anchor state-backed refinery partnerships with fermentation technology developers.
United States
Gulf Coast petrochemical corridors sustain residual isoprene output from naphtha crackers serving specialty rubber demand. EPA New Source Review delays 18-24 month permitting timelines for emissions-intensive expansion projects. Houston and Beaumont complex operators face constrained supply response capacity despite downstream tire investment announcements.
Germany
REACH registration requirements elevate compliance costs for imported monomer grades, protecting domestic specification-grade producers. ECHA enforcement tightens purity documentation for medical polyisoprene destined for device manufacturers. Marl and Ludwigshafen chemical parks concentrate European adhesive and coatings formulation expertise pulling certified isoprene derivatives.
Japan
Kansai and Chubu industrial regions anchor premium polyisoprene capacity for medical glove applications. METI industrial policy supports high-purity monomer production amid Hevea brasiliensis latex competition. Osaka and Nagoya clusters sustain specialized polymerization lines for ISO 10993-certified healthcare grades commanding margin premiums.
Thailand
Rayong and Eastern Economic Corridor zones lack local isoprene supply despite aggressive radial tire capacity expansion by Korean and Chinese automotive OEMs. Import dependency creates procurement vulnerability to Asian naphtha price volatility. Bangkok-based distributors manage spot purchasing consolidation toward annual volume commitments exceeding 10,000 metric tons.
Isoprene Market Vendor Landscape
On the supply side, the industry is consolidating around integrated petrochemical operators with captive feedstock access and specialized polymerization asset owners serving specification-grade niches. Three archetypes dominate: naphtha-integrated crackers with merchant monomer sales, on-purpose dehydrogenation specialists targeting cost-stable production economics, and medical-grade purifiers commanding certification premiums. Competitive moves center on backward integration into C5 feedstock control and strategic partnerships with tire OEMs for long-term offtake contracting.
Within the integrated petrochemical tier, Nizhnekamskneftekhim and PJSC SIBUR Holding exemplify operators leveraging captive naphtha supply to sustain cost leadership across CIS markets. Kuraray Co., Ltd. occupies a position representing premium polyisoprene specialization for medical applications where biocompatibility certification creates defendable margin pools.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Nizhnekamskneftekhim |
| Shell plc |
| Kuraray Co., Ltd. |
| JSR Corporation |
| PJSC SIBUR Holding |
| China Petrochemical Corporation |
| Kraton Corporation |
| LyondellBasell Industries Holdings B.V. |
| Others |
Supply Flow & Price Mechanics
Asian naphtha price volatility determines both tiered pricing spreads across medical-grade and commodity rubber segments and supply chain configuration toward captive C5 feedstock control. Buyers facing single-source dependency on Shandong and Zhejiang crackers absorb cost pass-through while seeking long-term offtake insulation.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with annual volume commitments exceeding 10,000 metric tons. Pricing stratifies across ISO 10993-certified medical grades, REACH-compliant specification tiers, and standard commodity rubber, with certification level and volume scale as primary differentiation drivers. Cost compression in commodity tire-grade polyisoprene is intensifying because of Hevea brasiliensis latex substitution pressure. Tire manufacturers in Thailand and Vietnam show highest price sensitivity, while Japanese medical glove producers accept premium positioning for biocompatibility-validated supply.
Supply Chain Analysis
Naphtha cracking economics in China, South Korea, and Japan feed the majority of merchant isoprene supply, with catalytic dehydrogenation units in the Middle East emerging as cost-stable alternatives. Feedstock draws from crude C5 streams, isopentane fractions, and emerging bio-based fermentation routes. Single-source vulnerability concentrates in Asian ethylene cracker corridors, exposing downstream tire plants to regional supply disruption. Distribution runs through direct sales agreements for monomer bulk, with regional chemical distributors handling packaged adhesive and coatings grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across bio-based and conventional production routes creates niche entry points for specialized players. Tire sector procurement consolidation and medical-grade certification barriers split competitive space between volume and premium positioning.
For Market Incumbents: Entrench through backward integration into C5 feedstock control and captive polymerization capacity in Karawang and Cikarang manufacturing zones. Secure long-term offtake agreements with Korean and Chinese automotive OEMs before dehydrogenation specialists achieve cost parity. Invest in fermentation technology partnerships to meet MEE dual carbon benchmarks and defend against bio-based entrants. For New Entrants and Emerging Players: Pursue import-substitution opportunities in Indonesian downstream tire clusters lacking local isoprene supply. Target specification-grade coatings resin production for European automotive refinishing applications where REACH compliance creates certification barriers. Build go-to-market credibility through ISO 10993 validation partnerships with Osaka and Nagoya medical device manufacturers. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors on-purpose dehydrogenation assets with feedstock cost stability. Five-to-ten year viability hinges on carbon intensity positioning as MEE enforcement tightens. Acquire catalytic process engineering capabilities and zeolite catalyst optimization expertise. Watch bio-based C5 blending ratios at state-owned refinery partnerships as inflection signal for regulatory preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C5 Feedstock | Captive naphtha supply insulates Nizhnekamskneftekhim from Asian price volatility. |
| Long-term Supply Agreement | Korean tire OEMs lock volume commitments exceeding 10,000 metric tons annually. |
| Green Manufacturing Transition | Bio-based fermentation pilots at Qingdao and Ningbo clusters attract state-backed financing. |
| Joint Venture | European adhesive formulators partner with Japanese high-purity producers for REACH-compliant grades. |
| Capacity Expansion | Solution SBR and IR lines in Thai Eastern Economic Corridor address import dependency. |
Methodological Framework
The analysis maps rubber compounding, adhesive formulation, coatings resin, and specialty fiber sub-sectors, each validated through plant managers, procurement leads at tire OEMs, distribution channel partners, and technical R&D directors. Primary interviews triangulate with customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE regulatory disclosure databases. Bottom-up capacity assessments and top-down demand modeling cross-validate segment outputs.
Assumptions held fixed include REACH and EPA regulatory enforcement intensity, while bio-based production cost curves and Asian naphtha price trajectories varied across scenario runs. The analytical framework segments by grade tier, end-use industry, and regional production hub throughout the projection horizon. CAGRs derive from elasticity-adjusted demand curves and capacity utilization trends, with tire sector procurement consolidation and medical-grade certification timelines as key forecast inputs.
Sensitivities concentrate around MEE dual carbon policy acceleration, Hevea latex substitution rates in medical gloves, and catalytic dehydrogenation technology licensing availability. Forecasts reflect documented assumptions about feedstock cost structures and regulatory enforcement timelines. Cross-checking against IEA petrochemical demand projections and tire OEM capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Hydrochloric Acid Electrolysis Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Europe Gamma Butyrolactone Market
Bulk Chemicals
Global Benzaldehyde Market
Bulk Chemicals
Propionic Anhydride Market
Bulk Chemicals
Barium Nitrate Market
Bulk Chemicals
Middle East and Africa Ferric Chloride Market
Bulk Chemicals
Bromacil Market
Bulk Chemicals
North America Calcium Chloride Market
Bulk Chemicals
Global 2-Ethylhexanoic Acid Market
Bulk Chemicals
North America Potassium Formate Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Atrazine Market
Bulk Chemicals
Calcium Hypophosphite Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market