
 Global Persulfates Market | 2026-2036
Global Persulfates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Persulfates Market Foresight
Asset-light toll manufacturing and third-party electrolysis leasing is narrowing the capital barrier for new persulfate entrants. Evonik Industries AG leverages its integrated hydrogen peroxide feedstock position to sustain cost leadership in European sodium persulfate. Hebei Jiheng Group anchors Chinese domestic supply through captive persulfate crystallization capacity. Mitsubishi Gas Chemical Company competes via specialized high-purity grades for Japanese electronics clients.
Persulfates are strong oxidizing salts—ammonium, potassium, and sodium persulfate—produced through electrolytic oxidation of the corresponding sulfates in sulfuric acid solution, with active oxygen content typically exceeding 6 percent. These compounds serve primarily as free-radical initiators in emulsion polymerization and as aggressive oxidizers in printed circuit board microetching. Sodium persulfate dominates volume flows due to its cost efficiency in water treatment and soil remediation, while ammonium persulfate captures premium positioning in electronics etching where metal contamination thresholds are tightest. Potassium persulfate occupies a narrower niche in specialty polymerization for adhesives and sealants, reflecting slower growth but stable margin pools.
EPA hazardous substance reporting requirements and REACH authorization protocols shape product formulation standards and cross-border shipment compliance for persulfate manufacturers. China's MEE enforces wastewater discharge limits on electrolysis plants, redirecting investment toward closed-loop sulfuric acid recovery systems. India's BIS certification mandates for imported industrial chemicals filter supplier eligibility for domestic water treatment tenders. Stakeholders must monitor regulatory divergence between EU F-Gas Regulation analogs and emerging national chemical registries as they calibrate regional production footprints.
Market Dynamics
Electrolytic oxidation capacity concentration in coastal China and the Rhine-Ruhr corridor is tightening feedstock access for mid-scale persulfate compounders, forcing toll manufacturing partnerships as the primary expansion pathway.
Growth Catalysts
- Semiconductor Etching Demand:South Korean fabricators are expanding ammonium persulfate offtake for advanced node microetching, tightening metal contamination specifications below 10 ppb thresholds.
- REACH Authorization Protocols:EU chemical registry updates are phasing out legacy oxidizer alternatives in polymerization, redirecting formulation demand toward persulfate-based initiator systems.
- Closed-Loop Sulfuric Acid Recovery:China's MEE wastewater mandates are accelerating capital deployment into captive acid regeneration, lowering unit electrolysis costs for compliant producers.
Market Restraints
- Input Cost Volatility:Hydrogen peroxide feedstock pricing swings tied to anthraquinone process energy costs compress margin stability for non-integrated persulfate manufacturers.
- Supply Concentration Risk:Electrolysis cell fabrication capability clusters in Germany and Japan, creating equipment delivery bottlenecks for new entrants seeking capacity expansion.
- Substitution Pressure:Peracetic acid formulations in PCB cleaning applications are displacing sodium persulfate in lower-precision etching tiers.
Strategic Opportunities
- India Water Treatment Tenders:BIS certification requirements for imported industrial chemicals are filtering supplier pools, creating first-mover advantage for certified persulfate exporters.
- Adhesives and Sealants Formulation:Potassium persulfate demand from automotive assembly plants in Mexico and Poland is outpacing legacy organic peroxide initiator adoption.
- EU Green Deal Chemicals Strategy:Carbon border adjustment mechanisms are incentivizing low-emission electrolysis retrofits, rewarding early compliance investments with tender preference.
Industry Challenges
- Electrolysis Engineering Talent Scarcity:Specialized cell design and membrane maintenance expertise concentrates among retiring German and Japanese technical workforces.
- High-Purity Certification Timelines:SEMI-grade qualification for electronics etching applications requires 18-24 month validation cycles with individual fabricators.
- Legacy Sulfate Supply Integration:Backward integration into ammonium or potassium sulfate crystallization demands capital commitments that conflict with asset-light competitive positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Persulfates Market |
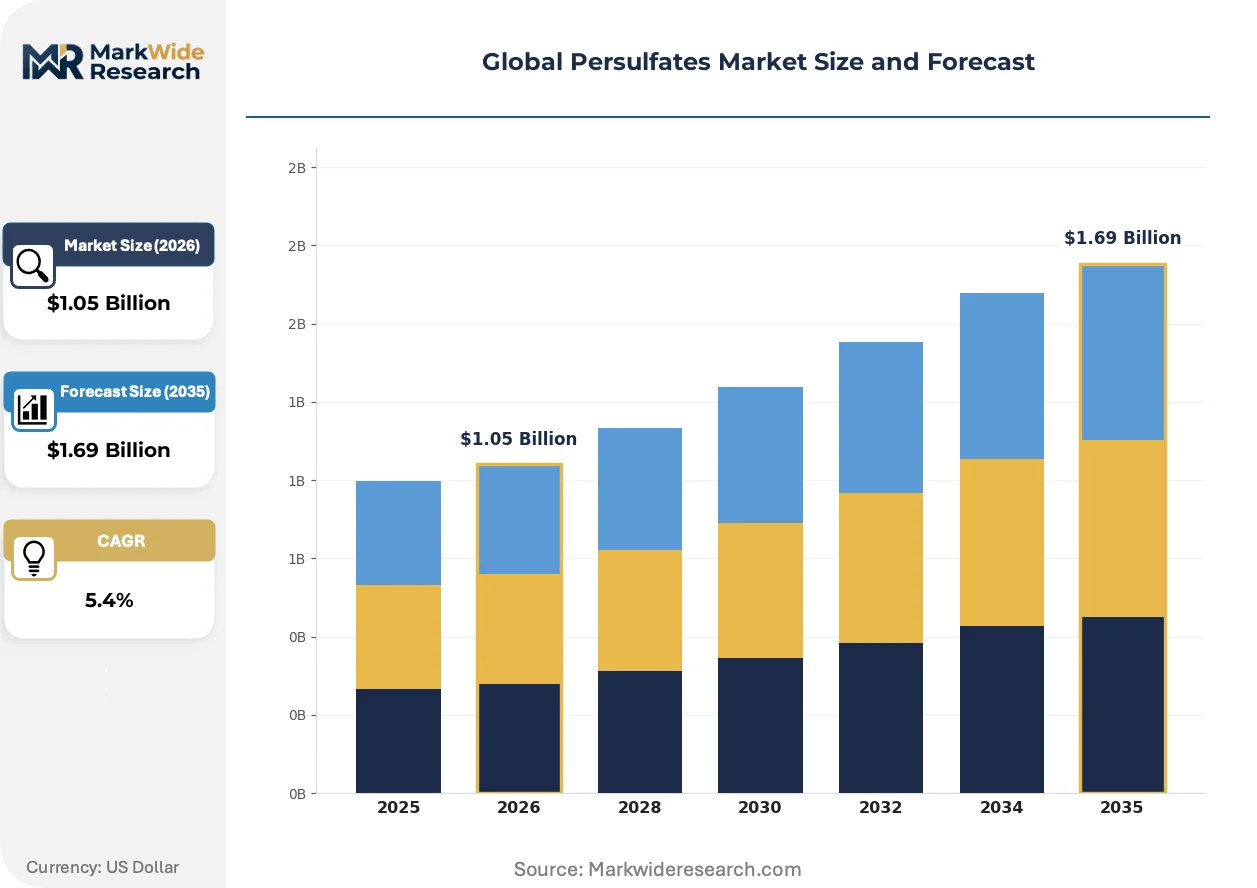
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.69 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ammonium Persulfate, Potassium Persulfate, Sodium Persulfate, Others Application: Polymerization Initiator, Water Treatment, Electronics Etching, Bleaching Agent, Soil Remediation End User Industry: Adhesives & Sealants, Mining, Surface Coatings, Printing Inks, Chemical Manufacturing Packaging Type: Drums, Bags, Bulk Containers, Cardboard Boxes |
| Companies Covered | Adeka Corporation, Hebei Jiheng Group Co., Ltd., Evonik Industries AG, VR Persulfates Pvt. Ltd., Fujian ZhanHua Chemical Co., Ltd., United Initiators GmbH, Lanxess AG, Ak-Kim Kimya, Mitsubishi Gas Chemical Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Persulfates Market Shifts & Advancements
Membrane cell architecture advances and regulatory chemistry restrictions are converging to reshape production economics and end-use specification tiers across persulfate supply chains.
Membrane electrolysis technology is hybridizing with boron-doped diamond anode coatings to boost current efficiency above 85 percent in sodium persulfate production. European specialty chemical manufacturers are piloting these retrofitted cells at industrial scale. The technology is compressing energy intensity differentials between integrated and toll-manufactured supply.
China's GB standards for industrial chemical purity are tightening specification requirements across export supply chains. Exporters serving electronics etching segments must now document sub-ppm heavy metal thresholds. South Korean semiconductor fabricators are requiring third-party certification of Chinese-origin ammonium persulfate batches.
Buyer concentration among adhesives and sealants compounders is consolidating procurement into annual framework agreements with volume-tier pricing. Regional distributors in Southeast Asia are losing share to direct manufacturer relationships. This pattern is most visible in Vietnam and Indonesia where multinational adhesive formulators are localizing blending operations.
Global Persulfates Market Segmentation
Persulfate procurement cycles vary dramatically across end-use applications, with electronics etching demanding quarterly qualification reviews while water treatment operates on annual framework agreements. Understanding these velocity differentials helps suppliers calibrate inventory positioning and technical service deployment.
Product Type:
Cycle times stretch from 18-month semiconductor qualification for high-purity grades to spot-market replenishment for standard industrial specifications.
- Sodium Persulfate:Produced through electrolytic oxidation of sodium sulfate in sulfuric acid solution, this compound carries the lowest unit cost among persulfate salts. Water treatment utilities in Germany and soil remediation contractors in the United States account for the bulk of offtake, though margin compression from hydrogen peroxide feedstock volatility constrains non-integrated producers.
- Ammonium Persulfate:Metal contamination thresholds below 10 ppb define the SEMI-grade specification tier for this salt. South Korean semiconductor fabricators in Pyeongtaek and Yongin are tightening batch certification requirements, extending validation timelines and locking in supplier relationships.
- Potassium Persulfate:Slower-turning specialty polymerization applications in automotive adhesives command stable margin pools.
- Others:Magnesium and calcium persulfate variants serve niche oxidative degradation applications with limited volume.
Sodium persulfate anchors the volume base while ammonium persulfate gains share at the steepest rate.
Application:
Margin structures diverge sharply between specification-driven electronics tiers and commodity-quoted water treatment segments.
- Polymerization Initiator:Free-radical generation for emulsion polymerization of acrylics and styrene-butadiene rubber depends on controlled decomposition kinetics. Adhesives compounders in Vietnam and Indonesia are consolidating procurement into direct manufacturer relationships, bypassing regional distributors.
- Electronics Etching:Microetching of copper surfaces in printed circuit board fabrication requires sub-ppm heavy metal documentation under China's tightening GB export standards. Third-party certification of Chinese-origin batches is now mandatory for South Korean fabricators.
- Water Treatment:Municipal and industrial wastewater oxidation represents high-volume, price-sensitive demand concentrated in India and Brazil.
- Bleaching Agent:Textile and pulp applications face displacement pressure from peracetic acid in lower-precision tiers.
- Soil Remediation:In-situ chemical oxidation for contaminated site cleanup operates on project-based procurement with irregular cadence.
Water treatment commands the largest revenue pool while electronics etching delivers the steepest margin expansion trajectory.
End User Industry:
Customer concentration patterns range from fragmented mining procurement to consolidated multinational adhesive formulators.
- Adhesives & Sealants:Automotive assembly plants in Mexico and Poland are outpacing legacy organic peroxide adoption with potassium persulfate formulations. Annual framework agreements with volume-tier pricing now dominate procurement between compounders and persulfate suppliers.
- Surface Coatings:Architectural and industrial paint polymerization uses sodium persulfate as a cost-efficient initiator, though REACH authorization protocols are redirecting some formulation demand from legacy oxidizer alternatives.
- Mining:Flotation and leaching applications in copper and gold extraction generate irregular, project-linked orders.
- Printing Inks:UV-curable and solvent-based ink polymerization represents a narrowing niche.
- Chemical Manufacturing:Intermediate synthesis and specialty oxidation steps consume variable grades depending on downstream specification.
Adhesives and sealants concentrate the fastest-growing demand while surface coatings provide the most stable baseline volume.
Packaging Type:
Handling economics and moisture sensitivity drive format selection across customer scale tiers.
- Bulk Containers:Integrated water treatment plants and large polymerization facilities favor ISO-tank and flexitank delivery to minimize handling costs and contamination risk.
- Drums:Standard 25-50 kg steel or plastic drums serve mid-scale chemical manufacturers with moderate consumption rates and warehouse storage constraints.
- Bags:Multi-layer laminated sacks with moisture barriers protect hygroscopic persulfate salts for regional distributors and smaller compounders.
- Cardboard Boxes:Laboratory and pilot-scale quantities for electronics etching qualification trials require minimal order quantities.
Bulk containers dominate tonnage flows while bagged formats retain importance in fragmented distributor channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water treatment utilities in Germany and semiconductor fabricators in South Korea anchor distinct buyer archetypes, while Chinese electrolysis clusters and Indian certification regimes reshape supplier access patterns across export corridors.
China
Electrolysis capacity concentrates in coastal provinces serving electronics etching and polymerization initiator demand. MEE wastewater discharge limits redirect investment toward closed-loop sulfuric acid recovery systems. The Yangtze River Delta hosts crystallization facilities supplying ammonium persulfate batches now requiring third-party certification for South Korean semiconductor clients.
Germany
Rhine-Ruhr corridor electrolysis plants supply sodium persulfate to water treatment utilities and soil remediation contractors. REACH authorization protocols phase out legacy oxidizer alternatives in polymerization formulations. Integrated hydrogen peroxide feedstock positions sustain cost leadership for domestic manufacturers serving European adhesives compounders.
South Korea
Semiconductor fabricators in Pyeongtaek and Yongin tighten ammonium persulfate metal contamination specifications below 10 ppb thresholds. MFDS alignment with international chemical registries filters import supplier eligibility. The Seoul Capital Area concentrates advanced node microetching demand with 18-24 month qualification cycles locking in supplier relationships.
United States
Soil remediation contractors and water treatment utilities generate price-sensitive sodium persulfate offtake. EPA hazardous substance reporting requirements shape product formulation standards and cross-border shipment compliance. The Gulf Coast and Midwest industrial corridors host project-based procurement with irregular cadence for contaminated site cleanup applications.
India
Municipal and industrial wastewater oxidation drives high-volume persulfate demand concentrated in western and southern states. BIS certification mandates for imported industrial chemicals filter supplier eligibility for domestic water treatment tenders. Gujarat and Maharashtra host blending operations where certified exporters capture first-mover advantage in framework agreement procurement.
Global Persulfates Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered specification grades. The vendor base clusters around integrated feedstock positions, captive crystallization capacity, and toll-manufacturing partnerships. Three archetypes dominate: hydrogen peroxide-integrated electrolysis operators, regional crystallization specialists, and asset-light toll manufacturers. Capacity expansion through electrolysis cell retrofits and strategic partnerships for sulfuric acid recovery represent the dominant competitive moves.
Among Asian fabricators, Hebei Jiheng Group Co., Ltd. and Fujian ZhanHua Chemical Co., Ltd. exemplify regional crystallization specialists with captive capacity positions. Evonik Industries AG represents the integrated archetype with upstream feedstock control. Mitsubishi Gas Chemical Company, Inc. occupies a position within the high-purity specialization tier serving electronics etching segments. These named entities anchor broader patterns of geographic clustering and specification-tier competition without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Adeka Corporation |
| Hebei Jiheng Group Co., Ltd. |
| Evonik Industries AG |
| VR Persulfates Pvt. Ltd. |
| Fujian ZhanHua Chemical Co., Ltd. |
| United Initiators GmbH |
| Lanxess AG |
| Ak-Kim Kimya |
| Mitsubishi Gas Chemical Company, Inc. |
| Others |
Supply & Pricing Matrix
Rhine-Ruhr corridor freight differentials compress margin pools for non-integrated compounders while amplifying price separation between SEMI-grade ammonium persulfate and standard sodium grades. Hydrogen peroxide feedstock volatility transmits through electrolysis tolling contracts, forcing buyers into longer-duration offtake commitments to secure volume certainty.
Pricing Analysis
Cost-plus contracts indexed to anthraquinone-process hydrogen peroxide benchmarks dominate sodium persulfate procurement, while ammonium persulfate commands fixed-price annual frameworks with metal-contamination premium tiers. Price differentiation hinges on SEMI-grade certification status and volume-scale commitments, with South Korean fabricators showing minimal sensitivity and Indian water treatment utilities exhibiting acute responsiveness. Pricing pressure stems from peracetic acid substitution in lower-precision PCB cleaning, eroding sodium persulfate spot-market premiums.
Supply Chain Analysis
Export-control restrictions on boron-doped diamond anode technology limit cell retrofit access for new entrants, reinforcing incumbent advantages in Germany and Japan. Electrolysis capacity clusters in coastal China, the Rhine-Ruhr corridor, and Japan's Chubu region, drawing from sulfuric acid, ammonium sulfate, and specialized membrane inputs. Single-source vulnerability concentrates in German-Japanese electrolysis cell fabrication, with distribution running through direct manufacturer relationships for multinational adhesive compounders and regional distributor networks for fragmented water treatment procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Persulfate incumbents face sustained substitution defense as peracetic acid formulations capture share in lower-precision electronics cleaning, requiring strategic positioning around irreplaceable high-purity grades.
For Market Incumbents: Insulate SEMI-grade ammonium persulfate relationships through captive crystallization investment and 18-24 month qualification pipeline locking. Peracetic acid encroachment in PCB cleaning demands accelerated high-purity certification timelines with South Korean fabricators, while backward integration into hydrogen peroxide feedstock buffers margin compression from energy-indexed input swings. For New Entrants and Emerging Players: India's western and southern states present underpenetration in BIS-certified water treatment tenders, where first-mover certification captures framework agreement procurement. Toll-manufacturing partnerships with coastal Chinese electrolysis operators bypass capital barriers, while potassium persulfate specialization for automotive adhesives in Mexico and Poland offers white-space positioning against legacy organic peroxide incumbents. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustment mechanisms reshape the acquisition landscape, rewarding early electrolysis retrofit compliance with tender preference and margin expansion. Five-to-ten year viability favors integrated hydrogen peroxide-electrolysis operators over asset-light toll manufacturers. Signal to watch: closure-rate differentials between REACH-authorized and legacy-oxidizer polymerization formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Peroxide | Anthraquinone-process feedstock control insulates Evonik-style operators from energy-indexed margin compression. |
| SEMI-Grade Certification Investment | 18-24 month South Korean fabricator validation cycles lock in supplier relationships against peracetic acid substitution. |
| Closed-Loop Sulfuric Acid Recovery | China MEE wastewater compliance lowers unit electrolysis costs for Yangtze River Delta crystallization facilities. |
| Toll-Manufacturing Partnership Expansion | Asset-light electrolysis leasing narrows capital barriers for potassium persulfate entrants in Polish automotive adhesives. |
| BIS Certification Pre-Positioning | First-mover compliance captures India water treatment tender frameworks before domestic capacity consolidation. |
Research Methodology
Cross-validation between primary fieldwork and secondary trade data anchors the qualitative findings in this study. Electrolysis plant managers, procurement leads at South Korean semiconductor fabricators, distribution channel partners in Southeast Asia adhesives, and technical R&D directors at European specialty chemical manufacturers provided operational intelligence. Secondary sources included Chinese customs export records, Cefic chemical industry reports, SEC 10-K disclosures from listed suppliers, and GB standards documentation. Bottom-up capacity modeling triangulated against top-down demand segmentation from polymerization initiator and electronics etching end-use analysis.
Calibration against historical capacity utilization and price realization data informed the analytical framework across the analysis window. Segmentation dimensions encompassed product grade tier, end-use industry application, packaging format, and regional production hub clustering. CAGRs derived from electrolysis capacity expansion pipelines, SEMI-grade qualification timelines, and substitution elasticity estimates in PCB cleaning applications. Industry-specific inputs included boron-doped diamond anode adoption curves and REACH authorization phase-out schedules for legacy oxidizer alternatives.
Macroeconomic conditions sit as an overlay; deviation in energy costs, semiconductor capital expenditure cycles, or Chinese environmental enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on electrolysis technology diffusion and regulatory compliance timelines. Material shifts in peracetic acid performance specifications or EU carbon border adjustment implementation pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Europe Gamma Butyrolactone Market
Bulk Chemicals
Calcium Chloride Market
Bulk Chemicals
Global Purified Terephthalic Acid (PTA) Market
Bulk Chemicals
Global Sodium Borohydride Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Global Potassium Metabisulfite Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Asia-Pacific Formic Acid Market
Bulk Chemicals
Castor Oil Derivatives Market
Bulk Chemicals
Sodium Tetraborate Market
Bulk Chemicals
North America Potassium Permanganate Market
Bulk Chemicals
Asia-Pacific Solid Sulfur Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
Calcined Petcoke Market