
 Phosphates Market | 2026-2036
Phosphates Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphates Market Analysis
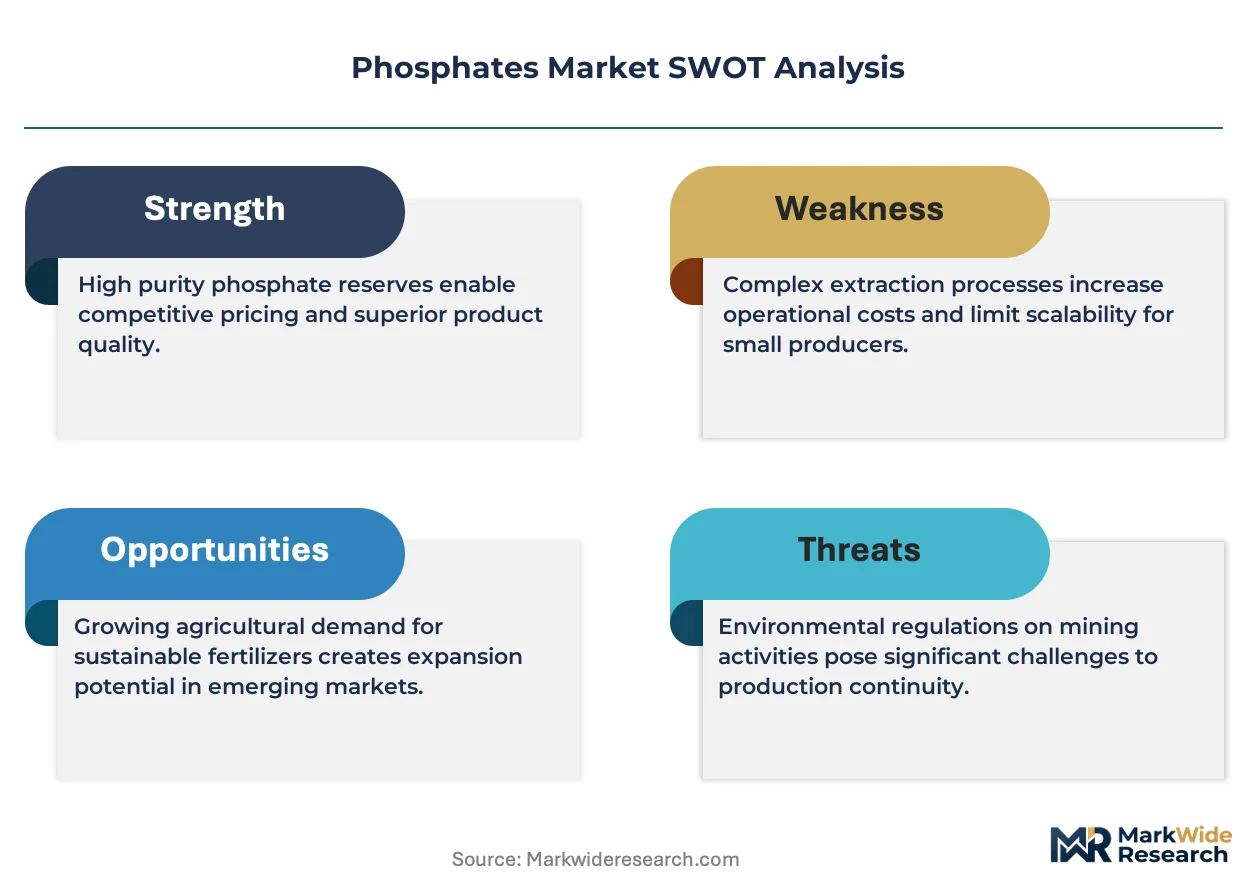
Green ammonia synthesis and precision fermentation for bio-based phosphate alternatives is fragmenting traditional capital allocation across the value chain. OCP Group leverages its integrated mine-fertilizer infrastructure in Morocco to sustain cost leadership on phosphate rock exports. The Mosaic Company anchors North American supply through its Florida and Louisiana processing complexes. Nutrien competes by controlling retail distribution networks that bypass commodity trading layers.
Phosphates are inorganic salts of phosphoric acid, typically formulated as ammonium, potassium, or sodium compounds with P2O5 content ranging from 46% to 54% by weight, produced via wet-process acid reaction or thermal reduction of phosphate rock for agricultural, food preservation, and industrial applications. Diammonium phosphate dominates fertilizer blends due to its nitrogen-phosphorus ratio and granule stability in bulk handling. Food grade sodium phosphate concentrates margin pools as clean-label pressure forces reformulation in processed meat and cheese applications. Agricultural grade volumes anchor the revenue base but face compressed returns from energy-linked input costs.
The EPA enforces Clean Water Act discharge limits on phosphorus runoff from processing facilities, while the EU REACH framework restricts cadmium and uranium contaminants in phosphate fertilizers sold within member states. China's MEE applies dual carbon goals to cap energy intensity at phosphoric acid plants, redirecting investment toward heat-recovery systems. Buyers and producers must monitor how carbon border adjustments and evolving contaminant thresholds reshape sourcing economics between rock-based and recycled phosphate streams.
Market Dynamics
EU F-Gas Regulation and broader European decarbonization mandates are tightening process standards for phosphate manufacturing, forcing capital reallocation toward heat-recovery systems and low-carbon ammonia integration across the value chain.
Growth Catalysts
- Agricultural intensification in Brazil:Soybean and corn expansion programs are pulling diammonium phosphate volumes upward through subsidized fertilizer distribution networks.
- REACH contaminant thresholds:Cadmium and uranium limits in EU phosphate fertilizers are accelerating investment in beneficiation and purification technologies that upgrade rock quality.
- Green ammonia synthesis:Electrolytic hydrogen routes are fragmenting traditional capital allocation and creating new feedstock partnerships between phosphate producers and renewable energy developers.
Market Restraints
- Sulfur price volatility:Wet-process phosphoric acid production depends on sulfuric acid, whose cost swings compress margins when energy markets spike.
- Moroccan supply concentration:OCP Group's captive phosphate rock reserves create single-source dependency risk for importers lacking backward integration.
- Precision fermentation substitutes:Bio-based phosphate alternatives from microbial cultivation threaten food-grade sodium phosphate margins in clean-label meat and cheese applications.
Strategic Opportunities
- India's PLI scheme for fertilizers:Production-linked incentives for domestic phosphoric acid capacity offer first-mover advantages to technology licensors.
- Recycled phosphate streams:Struvite recovery from municipal wastewater is emerging as a circular feedstock for niche agricultural applications.
- Carbon border adjustments:EU CBAM implementation creates arbitrage potential for low-carbon phosphate rock exporters versus high-intensity producers.
Industry Challenges
- Process engineering talent scarcity:Heat-recovery system design and carbon capture integration require specialized skills that outpace university pipeline output.
- Legacy asset retrofit timelines:Florida and Louisiana processing complexes face extended downtime risks when upgrading to meet EPA Clean Water Act discharge limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphates Market |
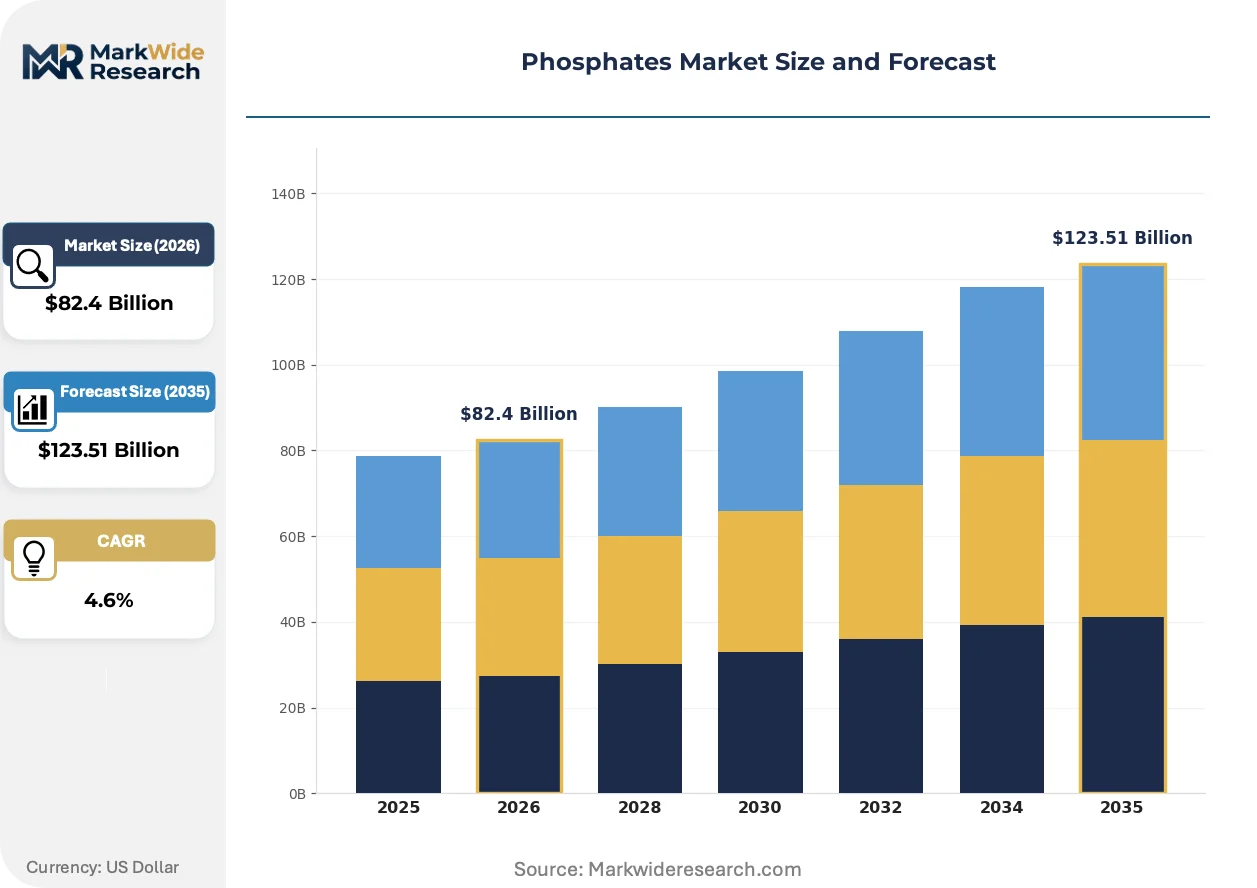
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $123.51 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoammonium Phosphate, Diammonium Phosphate, Tripotassium Phosphate, Sodium Phosphate End Use Industry: Agriculture, Food & Beverage, Animal Feed, Pharmaceuticals Grade: Food Grade, Industrial Grade, Technical Grade, Agricultural Grade Form: Granular, Powder, Liquid, Crystalline |
| Companies Covered | OCP Group, The Mosaic Company, Nutrien, Yara International, PhosAgro, ICL Group, EuroChem Group, Ma'aden, Foskor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphates Market Emerging Trajectories
Digital twin technology and precision fermentation are compressing traditional R&D cycles while regulatory pressure on carbon intensity reconfigures feedstock sourcing strategies across the phosphate value chain.
Digital twin platforms for phosphoric acid reactor optimization are virtualizing pilot-scale testing, allowing Moroccan and North American producers to simulate thermal efficiency gains without physical prototyping. Fertilizer blenders in Brazil and the US Midwest are adopting these tools to compress formulation development from months to weeks. The technology is virtualizing capital deployment decisions by reducing full-scale engineering risk before construction commitments.
China's MEE dual carbon goals are capping energy intensity at phosphoric acid plants and redirecting investment toward waste-heat recovery and co-generation systems. Plants in Guizhou and Yunnan provinces face binding consumption quotas that favor integrated mine-to-acid operations. Agricultural-grade producers are responding by consolidating smaller facilities into larger complexes that achieve economies of scale in emissions compliance.
Buyer consolidation among large-scale agricultural cooperatives is compressing procurement cycles and unbundling technical advisory services from commodity transactions. North American retail distribution networks now demand real-time inventory visibility and just-in-time delivery guarantees that bypass traditional trading layers. This pattern is most visible in the US Corn Belt and Southern Plains, where cooperative purchasing power has shifted negotiation leverage toward volume-commitment contracts with indexed pricing.
Phosphates Market Segmentation
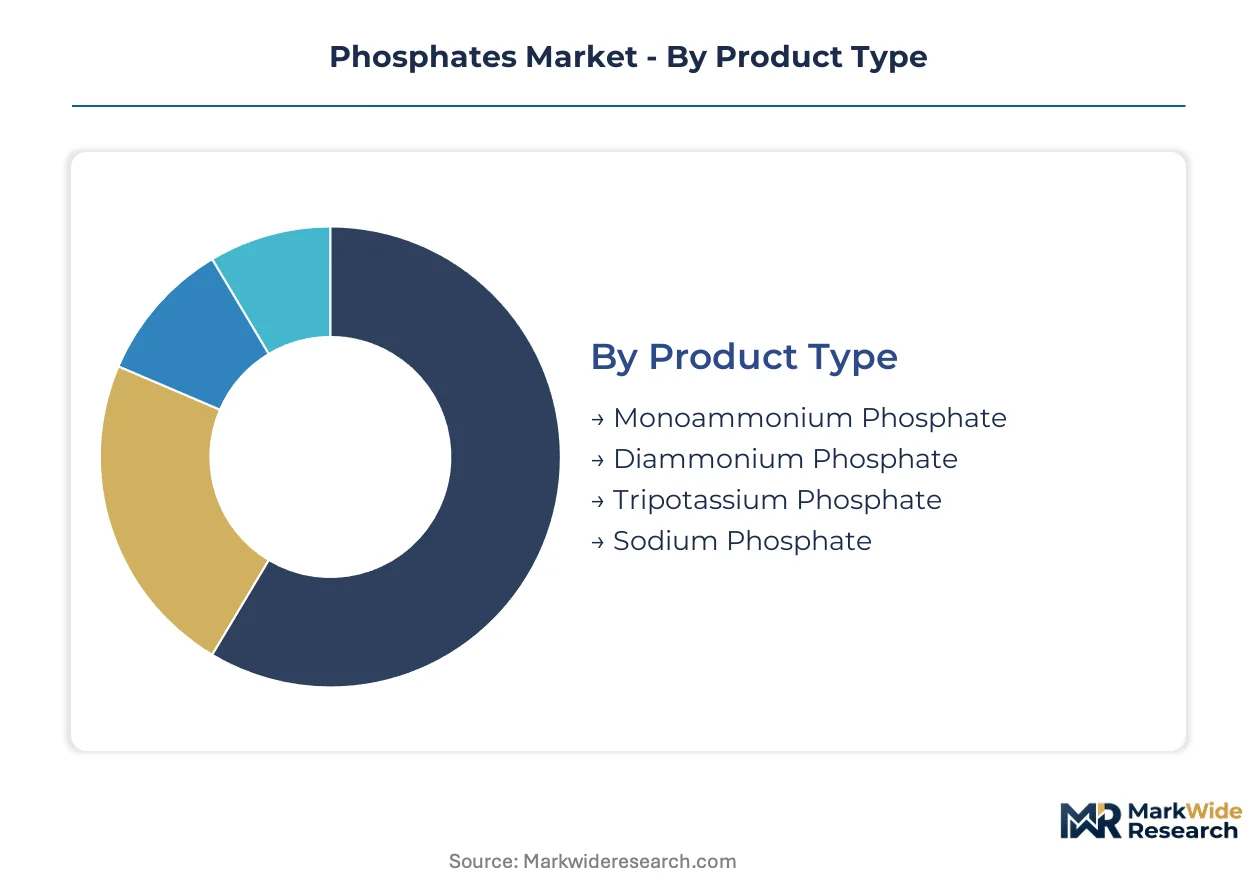
Phosphate producers configure product specifications and grade purity to match divergent buyer requirements across fertilizer blending, food preservation, and pharmaceutical synthesis. Segmentation discipline determines margin capture, as technical-grade volumes trade on cost efficiency while food-grade and pharmaceutical-grade streams command certification premiums.
Product Type:
Mature commodity formats dominate agricultural procurement, while specialized phosphate salts serve precision formulation needs in food and pharmaceutical applications.
- Diammonium Phosphate:Formulated with nitrogen-phosphorus ratio optimized for bulk fertilizer blending, this compound delivers granule stability essential for mechanized spreading equipment. Brazilian soybean expansion programs and US Corn Belt cooperatives anchor procurement volumes, though sulfur-linked input cost swings compress processor margins during energy market spikes.
- Sodium Phosphate:Clean-label pressure from European retail chains and North American natural-food distributors is fragmenting traditional food-grade phosphate demand. Precision fermentation alternatives from microbial cultivation threaten margin pools in processed meat and cheese applications, forcing reformulation toward reduced-phosphate or bio-based substitutes.
- Monoammonium Phosphate:Lower nitrogen content suits specialty crop fertilization and starter fertilizer programs in precision agriculture systems.
- Tripotassium Phosphate:Alkaline buffering properties serve liquid detergent formulations and specialized industrial cleaning compounds.
Diammonium Phosphate retains volume leadership; Sodium Phosphate holds the steepest expansion curve amid clean-label substitution risks.
End Use Industry:
Cost tier differentiation separates commodity-scale agricultural buyers from specification-driven pharmaceutical and food-grade purchasers.
- Agriculture:Diammonium phosphate and monoammonium phosphate blends constitute the foundational revenue base, with procurement concentrated among Brazilian subsidized distribution networks and North American cooperative purchasing alliances. Energy-linked ammonia and sulfur costs transmit directly into fertilizer pricing, compressing returns during feedstock volatility periods.
- Food & Beverage:Sodium phosphate and potassium phosphate compounds function as emulsifiers, pH stabilizers, and moisture-retention agents in processed meat, cheese, and bakery applications. EU REACH cadmium and uranium contaminant thresholds are accelerating beneficiation investment to upgrade rock quality for food-grade purification standards.
- Animal Feed:Calcium phosphate and defluorinated phosphate supplements address livestock nutritional requirements in concentrated feeding operations.
- Pharmaceuticals:High-purity phosphates serve as excipients and active pharmaceutical ingredients in tablet formulations and parenteral solutions.
Agriculture commands procurement scale; Food & Beverage offers the most rapid specification evolution.
Grade:
Application requirements dictate purity thresholds, with contaminant limits and certification protocols creating discrete margin tiers.
- Agricultural Grade:Bulk fertilizer applications tolerate higher cadmium and heavy metal content, sourcing from beneficiated phosphate rock with minimal downstream purification. Chinese MEE dual carbon goals are capping energy intensity at phosphoric acid plants and consolidating smaller facilities into larger complexes.
- Food Grade:FDA and EFSA regulations mandate arsenic, lead, and fluoride limits that necessitate dedicated processing lines and batch certification. Struvite recovery from municipal wastewater is emerging as a circular feedstock for niche agricultural applications, though food-grade standards exclude recycled streams.
- Industrial Grade:Metal surface treatment, water softening, and detergent manufacturing accept intermediate purity specifications.
- Technical Grade:Laboratory reagents and electronic-grade phosphoric acid demand ultra-low metallic impurity profiles.
Agricultural Grade dominates tonnage; Food Grade generates the highest unit margins.
Form:
Customer logistics infrastructure and application equipment determine physical format preferences across regional markets.
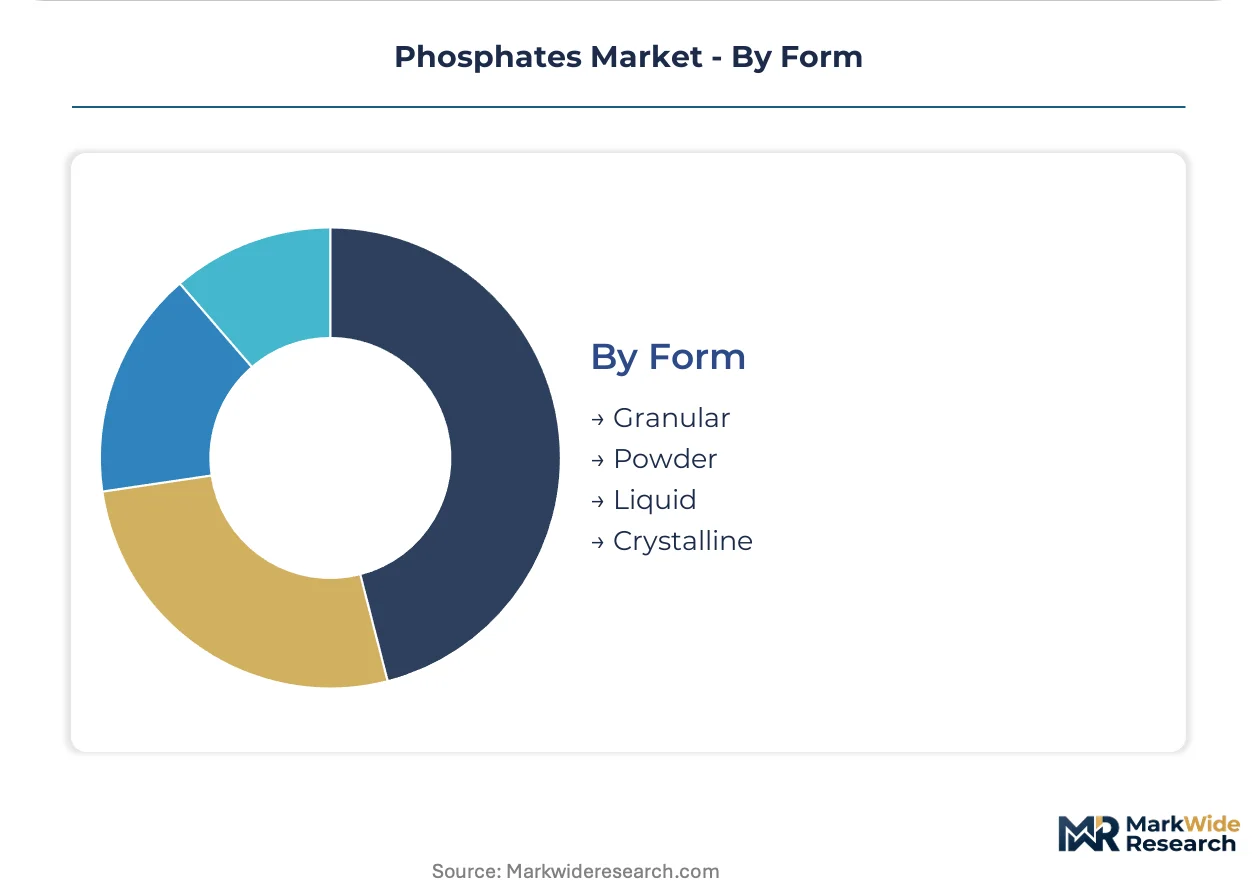
- Granular:Diammonium phosphate granules suit mechanized spreading and bulk blending operations in Brazilian Cerrado and US Midwest farming systems. Granule hardness and size distribution specifications vary by equipment type and climate exposure requirements.
- Powder:Fine-grind monoammonium phosphate and sodium phosphate compounds dissolve rapidly for fertigation systems and food processing lines.
- Liquid:Ammonium polyphosphate and phosphoric acid solutions integrate into drip irrigation and industrial process streams.
- Crystalline:High-purity sodium phosphate and potassium phosphate crystals meet pharmaceutical and laboratory reagent specifications.
Granular formats retain agricultural dominance; Liquid forms are gaining share fastest in precision irrigation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances are tightening across phosphate supply corridors as Moroccan rock shipments face carbon-border scrutiny and Brazilian import dependency deepens. The EU F-Gas Regulation and China's MEE dual carbon goals are reshaping regional production economics. Processing capacity is consolidating in jurisdictions with captive energy and beneficiated feedstock advantages.
Morocco
OCP Group's mine-to-market expansion drives phosphate rock export volumes through Jorf Lasfar and Safi port complexes. The country's national environmental regulator enforces discharge standards aligned with EU trade requirements. Khouribga and Gantour mining basins anchor beneficiation and phosphoric acid production clusters serving Atlantic shipping lanes.
United States
Florida and Louisiana processing complexes supply diammonium phosphate to domestic Corn Belt cooperatives and Latin American importers. EPA Clean Water Act discharge limits force capital reallocation toward wastewater treatment upgrades at phosphogypsum stack facilities. Tampa Bay and New Orleans port infrastructure handles bulk granular exports to Brazilian agricultural programs.
China
Guizhou and Yunnan province phosphoric acid plants face binding energy intensity caps under MEE dual carbon enforcement. The country's national standardization administration mandates beneficiation upgrades to reduce cadmium content in fertilizer-grade outputs. Yangtze River Delta chemical clusters are consolidating smaller facilities into integrated mine-acid complexes.
Brazil
Soybean and corn expansion programs pull diammonium phosphate volumes through Paranaguá and Santos port terminals. ANVISA regulates contaminant thresholds in imported fertilizers while subsidized distribution networks accelerate procurement cycles. Mato Grosso and Goiás farming cooperatives dominate volume contracting with indexed pricing structures.
India
Domestic phosphoric acid capacity expansion targets import substitution for diammonium phosphate blending operations. The PLI scheme for fertilizers offers production-linked incentives to technology licensors establishing acid plant infrastructure. Gujarat and Odisha industrial corridors concentrate sulfuric acid integration with phosphate processing facilities.
Phosphates Market Vendor Landscape
On the supply side, the industry is consolidating around integrated mine-fertilizer operators and diversified agricultural input conglomerates. Tiered competition separates captive rock producers from traders dependent on spot procurement. Strategic archetypes include backward-integrated mining majors, retail distribution network owners, and technology-focused purification specialists. Capacity expansion and low-carbon ammonia partnerships constitute the dominant competitive moves reshaping capital allocation.
Among integrated mining majors, OCP Group and The Mosaic Company exemplify divergent geographic anchoring strategies that determine feedstock security and shipping cost structures. Nutrien occupies a position bridging wholesale fertilizer production with retail distribution network control. These three operators represent the spectrum from captive reserve dominance to downstream channel capture that defines competitive positioning in phosphate value chains.
| Leading Market Players |
|---|
| OCP Group |
| The Mosaic Company |
| Nutrien |
| Yara International |
| PhosAgro |
| ICL Group |
| EuroChem Group |
| Ma'aden |
| Foskor |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Moroccan phosphate rock reserves determines both pricing tier spreads and supply chain shape across agricultural, food-grade, and industrial phosphate segments. Buyers lacking backward integration face asymmetric cost pass-through when sulfur-linked input volatility intersects with carbon-border adjustment exposure.
Pricing Analysis
Grade-certification pricing gaps separate agricultural-grade spot transactions from food-grade contract premiums and pharmaceutical-grade certification tiers. Three-tier pricing structure across premium, standard, and economy levels reflects contaminant thresholds, with EU REACH cadmium limits compressing mid-tier margins. Pricing pressure stems from sulfuric acid cost swings in wet-process phosphoric acid production. Agricultural cooperatives in Brazil and the US Midwest exhibit highest price sensitivity, while pharmaceutical excipient buyers accept premium stability.
Supply Chain Analysis
Upstream phosphate rock concentration in Morocco, China, and the United States anchors global supply. Sulfur, ammonia, and beneficiated phosphate rock constitute critical input dependencies. Single-source vulnerability concentrates around OCP Group's captive reserve dominance and Jorf Lasfar export infrastructure. Distribution runs through bulk granular shipments to Brazilian port terminals and North American Corn Belt cooperatives, with liquid and powder formats serving precision agriculture and food processing niches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green ammonia synthesis partnerships and carbon-accounting interoperability standards are repositioning phosphate value chains as platform economies where feedstock provenance and emission intensity determine access tiers.
For Market Incumbents: Entrench cost leadership through heat-recovery system deployment at Florida and Louisiana processing complexes. Deepen captive phosphate rock control via beneficiation technology licensing to offset precision fermentation substitution threats in food-grade sodium phosphate segments. Prioritize low-carbon ammonia offtake agreements with renewable energy developers to preempt EU CBAM exposure. For New Entrants and Emerging Players: Establish a beachhead in struvite recovery from municipal wastewater for niche agricultural applications. Target India's PLI scheme for fertilizers as the most penetrable geography, leveraging technology licensing partnerships with domestic phosphoric acid capacity expansions in Gujarat and Odisha. Pursue circular feedstock certification to differentiate from rock-based incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated mine-fertilizer operators with captive energy assets. Long-term viability across the analysis window hinges on carbon-intensity positioning rather than reserve scale alone. Watch for EU CBAM implementation timing as the critical inflection signal separating low-carbon premium capture from margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Green Ammonia Partnership | Electrolytic hydrogen routes fragment traditional capital allocation toward renewable feedstock integration. |
| Heat-Recovery System Deployment | China's MEE dual carbon goals favor plants achieving economies of scale in emissions compliance. |
| Beneficiation Technology Licensing | REACH cadmium thresholds accelerate investment in rock quality upgrading for EU market access. |
| Struvite Recovery Scale-Up | Municipal wastewater circularity creates niche agricultural feedstock outside conventional mining economics. |
| Carbon Border Adjustment Positioning | EU CBAM implementation creates arbitrage potential for verified low-carbon phosphate rock exporters. |
Methodological Framework
Initial hypotheses were tested against primary input from phosphate plant operations managers, agricultural cooperative procurement directors, food-grade phosphate quality assurance leads, and sulfuric acid supply specialists and refined through secondary validation against customs trade data, OCP Group and Mosaic Company SEC filings, China's MEE enforcement bulletins, and EU ECHA regulatory guidance. Bottom-up capacity modeling and top-down demand aggregation were triangulated to reconcile volume estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry concentration, physical form preferences, and regional regulatory cluster. CAGRs were derived from production capacity expansion schedules, import substitution trajectories, and intensity-of-use coefficients by crop type. Green ammonia cost curves and carbon-border adjustment phase-in schedules constituted phosphate-specific forecast inputs.
Stress conditions across sulfur price volatility bands, EU CBAM implementation pacing, and precision fermentation substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology cost reduction trajectories. Cross-checking against FAO fertilizer consumption statistics and national customs import records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
Ammonium Bromide Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Formate Brine Market
Bulk Chemicals
Borates Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Hydrochloric Acid Electrolysis Market
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
Sodium Bisulfite Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
2,4-Dichlorophenoxyacetic Market
Bulk Chemicals
North America Malic Acid Market
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
Carbonate Market