
 Pharmaceutical Surfactants Market | 2026-2036
Pharmaceutical Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Surfactants Market Analytics
The capital-intensity divergence between integrated petrochemical giants and specialized fine-chemical producers is redrawing competitive boundaries in pharmaceutical surfactants. BASF leverages its backward integration into ethylene oxide and fatty alcohols to sustain cost leadership across bulk non-ionic grades. Evonik Industries AG specializes in high-purity polysorbates and synthetic alternatives, anchoring its position in biologic drug formulation channels where endotoxin specifications are stringent. Croda International controls a differentiated portfolio of bio-based and lipid-derived surfactants, positioning the firm to capture premium segments as sustainability criteria tighten across European and North American buyer networks.
Pharmaceutical surfactants are surface-active compounds that reduce interfacial tension between immiscible phases, typically comprising hydrophilic head groups and hydrophobic tails with HLB values ranging from 1 to 30 to match specific formulation requirements; they function as solubilizers, emulsifiers, wetting agents, and stabilizers in drug delivery systems where active pharmaceutical ingredients exhibit poor aqueous solubility or chemical instability. Non-ionic surfactants, particularly polysorbates and polyoxyethylene castor oil derivatives, dominate current volume due to their compatibility with parenteral routes and established safety profiles in regulatory filings. Cationic surfactants occupy a narrower but higher-margin niche in topical antimicrobial formulations and gene delivery complexes, while anionic variants face structural headwinds from compatibility restrictions with certain protein therapeutics despite their cost efficiency in oral dosage manufacturing.
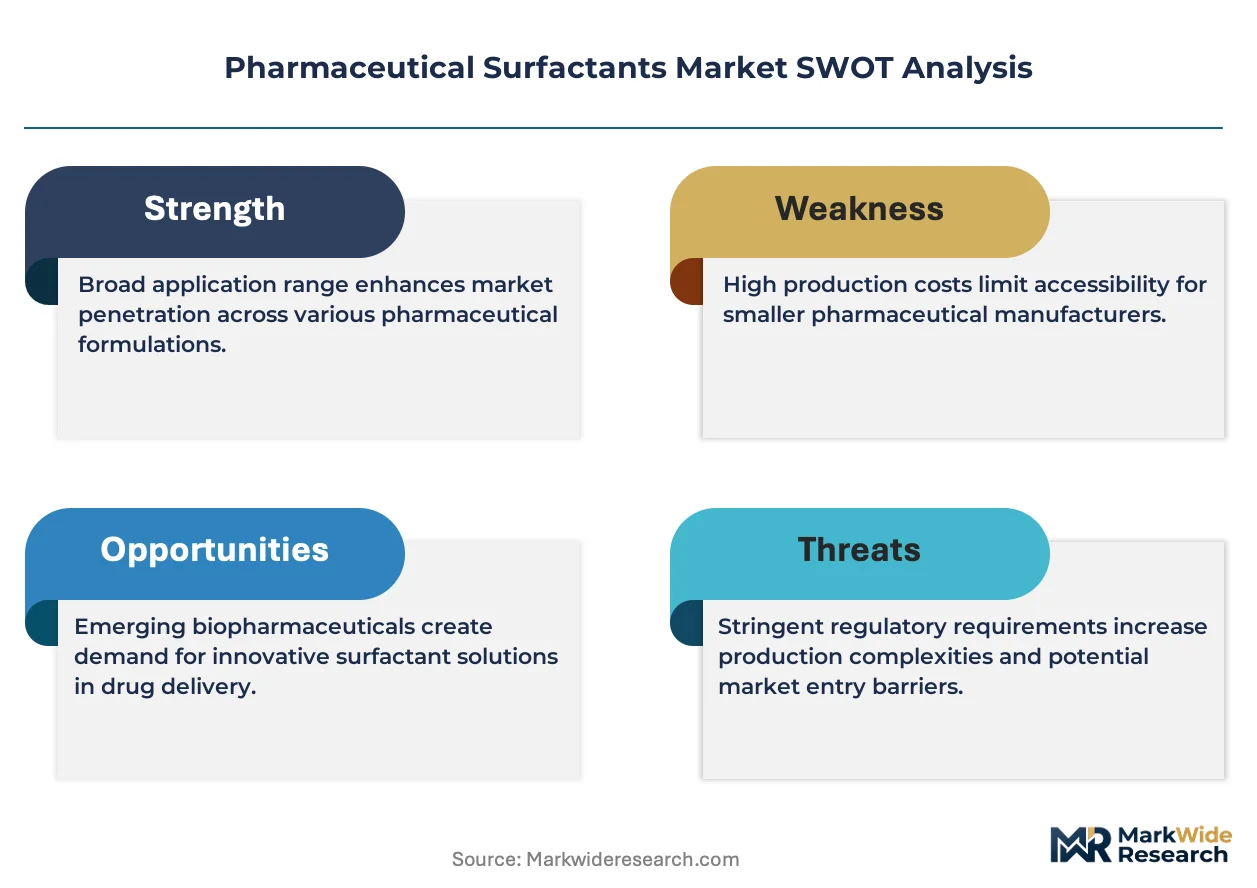
The FDA's immunogenicity guidance and the EMA's excipient quality expectations are elevating documentation burdens and supplier qualification costs for surfactant vendors serving regulated pharmaceutical markets. REACH registration requirements in Europe and China's NMPA technical standards for injectable-grade materials are creating divergent compliance pathways that favor regional production footprints over centralized export models. Stakeholders must monitor the trajectory of biosimilar approvals and the associated pressure on formulation costs, as these dynamics will determine whether premium synthetic surfactants or refined natural alternatives become the default choice in high-volume biologic manufacturing.
Market Dynamics
FDA immunogenicity guidance and EMA excipient quality standards are elevating supplier qualification costs and documentation burdens across pharmaceutical surfactant supply chains.
Growth Catalysts
- Biologic formulation expansion:Monoclonal antibody pipelines require specialized surfactants for protein stabilization. Parenteral drug developers in the United States drive premium-grade procurement.
- REACH registration pathways:European regulatory clarity on injectable-grade materials accelerates supplier consolidation. Qualified vendors capture recurring contracts from multinational pharmaceutical firms.
- CMO infrastructure concentration:Specialized contract manufacturing organizations in Germany and Switzerland expand captive demand for high-purity polysorbates.
Market Restraints
- Ethylene oxide feedstock volatility:Petrochemical input costs fluctuate with crude oil benchmarks. Non-ionic surfactant margins compress during energy price spikes.
- Supplier concentration in Western Europe:Three integrated chemical conglomerates control bulk fatty alcohol supply. Buyers face limited alternative sourcing for GMP-certified grades.
- Endotoxin specification ceilings:Protein therapeutic compatibility restricts anionic surfactant adoption. Formulators default to costlier synthetic alternatives despite price premiums.
Strategic Opportunities
- Indian biosimilar manufacturing:CDSCO regulatory alignment with ICH standards opens formulation chemical markets. Domestic biologic producers seek qualified excipient suppliers.
- Continuous processing technology:Microreactor synthesis of polysorbates reduces batch-to-batch variability. Early adopters in the Netherlands and Denmark achieve tighter endotoxin control.
- Bio-based surfactant mandates:EU Green Deal procurement criteria favor lipid-derived alternatives. Rapeseed and coconut oil feedstock processors gain preferential supplier status.
Industry Challenges
- Analytical method standardization:Compendial polysorbate characterization lacks harmonization between USP and Ph. Eur. protocols. Quality control laboratories maintain duplicate validation procedures.
- Multi-site audit coordination:Pharmaceutical buyers require simultaneous qualification of manufacturing and packaging locations. Supplier quality teams face overlapping inspection schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Surfactants Market |
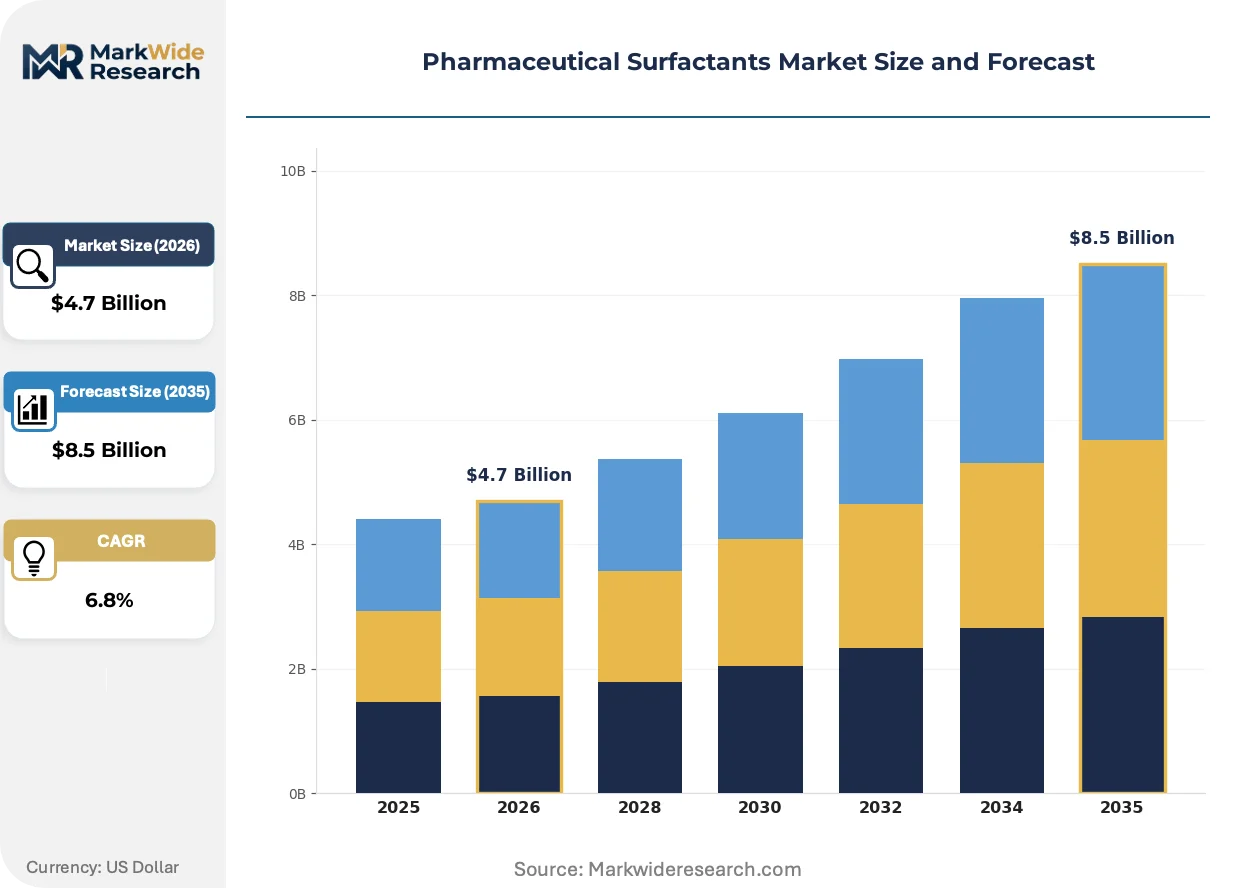
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anionic Surfactants, Cationic Surfactants, Non-ionic Surfactants, Zwitterionic Surfactants Application: Drug Formulation, Pharmaceutical Manufacturing, Topical Preparations, Injectable Solutions End User: Pharmaceutical Companies, Contract Manufacturing Organizations, Research Laboratories, Biopharmaceutical Firms Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Outlets |
| Companies Covered | Croda International, Clariant, BASF, Huntsman Corporation, Kao Corporation, Evonik Industries AG, Solvay, Akzo Nobel, Stepan Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Surfactants Market Evolving Landscape
Synthetic surfactant chemistry and natural-derived alternatives are diverging along performance-versus-sustainability axes, reshaping how formulators evaluate excipient portfolios.
Polysorbate 80 alternatives are bifurcating the biologic formulation market. Synthetic block copolymers demonstrate superior thermal stability in mAb formulations. Large-molecule developers in Massachusetts and California are adopting these substitutes for long-acting injectables. The technology is bifurcating procurement patterns between risk-averse innovators and cost-sensitive biosimilar manufacturers.
EMA's updated excipient information package requirements entered force in 2023. Drug manufacturers must now document surfactant supplier qualification history across the product lifecycle. Parenteral formulation teams in Germany and France face expanded pharmacovigilance obligations. Contract chemical suppliers are investing in dedicated regulatory affairs functions to manage centralized procedure submissions.
Buyer consolidation among CDMO networks is compressing supplier negotiation cycles. Top-ten contract manufacturers now account for the majority of high-purity surfactant volume in North America and Western Europe. Long-term supply agreements with fixed-price escalators are displacing spot-market purchasing. This concentration is most visible in the Boston-Cambridge biotech corridor, where specialized CMOs have integrated directly into sponsor development pipelines.
Pharmaceutical Surfactants Market Segmentation
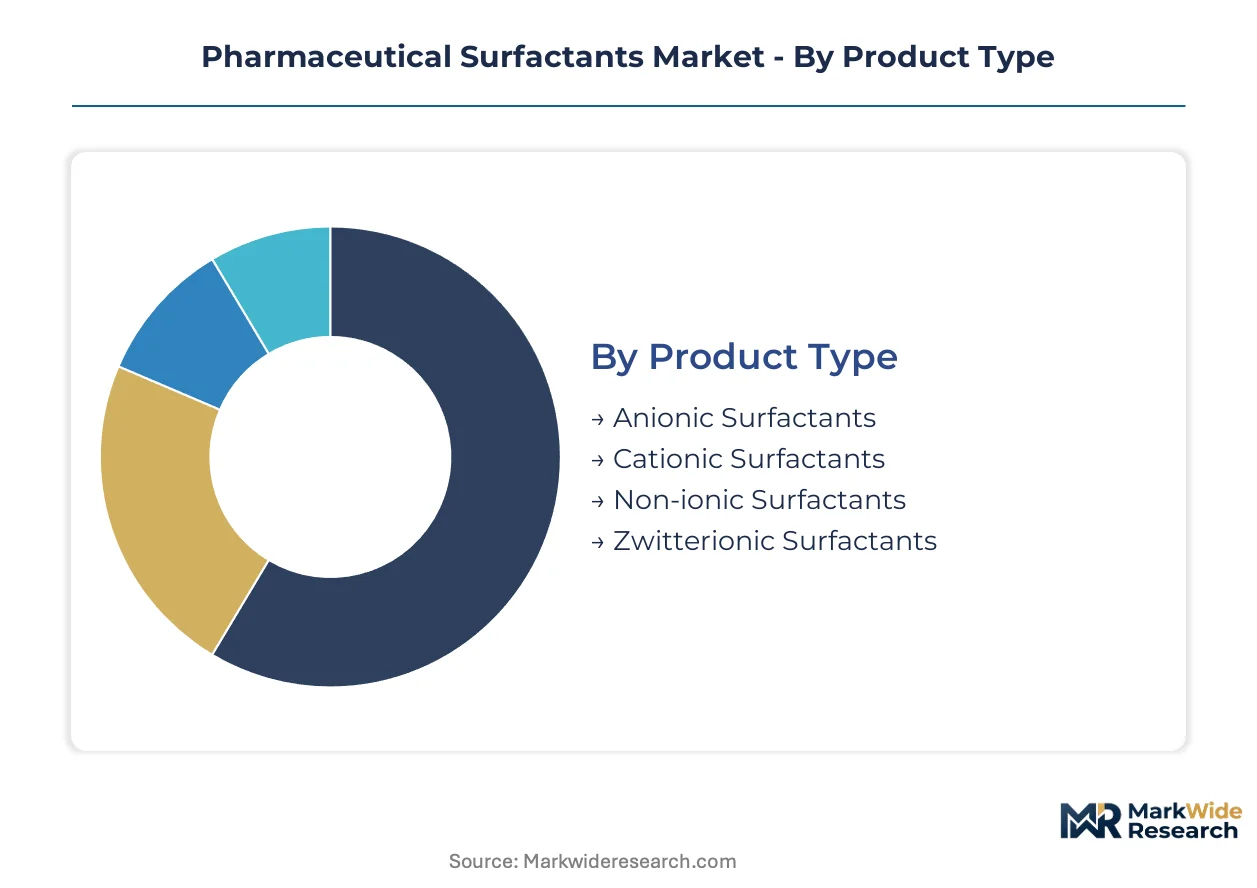
Segmentation in pharmaceutical surfactants reveals how formulation requirements, regulatory pathways, and procurement models create distinct margin architectures. Each dimension exposes different competitive pressures and supplier qualification barriers that shape vendor selection criteria.
Product Type:
Margin pools concentrate in non-ionic grades where biologic compatibility commands certification premiums, while anionic variants compete on manufacturing efficiency for oral dosage applications.
- Non-ionic Surfactants:Polysorbates and polyoxyethylene castor oil derivatives dominate parenteral formulations due to established safety profiles and thermal stability. Massachusetts and California biotech clusters drive premium-grade procurement for monoclonal antibody stabilization, with endotoxin specifications below 10 EU/g separating qualified suppliers from commodity producers.
- Anionic Surfactants:Alkyl sulfates and sulfonates offer cost efficiency in tablet manufacturing and oral liquid preparations. Protein therapeutic compatibility restrictions limit penetration into injectable segments, though sodium lauryl sulfate maintains volume leadership in solid dosage disintegration applications across Indian generic manufacturing.
- Cationic Surfactants:Quaternary ammonium compounds serve topical antimicrobial formulations and gene delivery complexes where positive surface charge enables nucleic acid complexation.
- Zwitterionic Surfactants:Phospholipid-derived amphoteric compounds occupy emerging niches in liposomal drug delivery where pH-dependent charge switching enhances cellular uptake.
The dominant share belongs to non-ionic surfactants, while zwitterionic alternatives are closing the gap fastest in advanced delivery system development.
Application:
Volume concentration tracks the expansion of biologic drug pipelines, with parenteral segments requiring the most intensive supplier qualification investment.
- Drug Formulation:Solubilization and stabilization of poorly water-soluble active pharmaceutical ingredients demands surfactants with documented excipient master files. FDA immunogenicity guidance elevates documentation burdens for polysorbate suppliers serving innovator biologics.
- Injectable Solutions:Parenteral-grade materials face stringent endotoxin and particulate specifications that restrict qualified supplier pools. German and Swiss CMO infrastructure creates concentrated demand for GMP-certified polysorbate 80 and synthetic block copolymer alternatives.
- Topical Preparations:Emulsion stability and skin penetration enhancement drive cationic and non-ionic selection for dermatological and transdermal delivery systems.
- Pharmaceutical Manufacturing:Equipment cleaning and process aids utilize commodity-grade surfactants where regulatory documentation requirements remain minimal.
Drug formulation commands the largest value share, though injectable solutions demonstrate the steepest expansion trajectory as biologic pipelines mature.
End User:
Procurement sophistication varies sharply between integrated pharmaceutical firms and outsourced manufacturing networks, creating tiered supplier relationship models.
- Biopharmaceutical Firms:Monoclonal antibody developers in the Boston-Cambridge corridor require dedicated regulatory affairs support and locked manufacturing processes. Long-term supply agreements with fixed-price escalators displace spot purchasing.
- Contract Manufacturing Organizations:CDMO consolidation concentrates volume among top-ten North American and Western European operators. Multi-site audit coordination demands simultaneous qualification of manufacturing and packaging locations.
- Pharmaceutical Companies:Integrated innovators maintain captive excipient qualification teams and direct supplier relationships for critical formulation components.
- Research Laboratories:Preclinical and early-phase development purchases small-batch, multi-compendial grades through distributor channels with minimal qualification overhead.
Biopharmaceutical firms represent the highest-margin customer segment, while CMOs are gaining procurement leverage fastest through buyer consolidation.
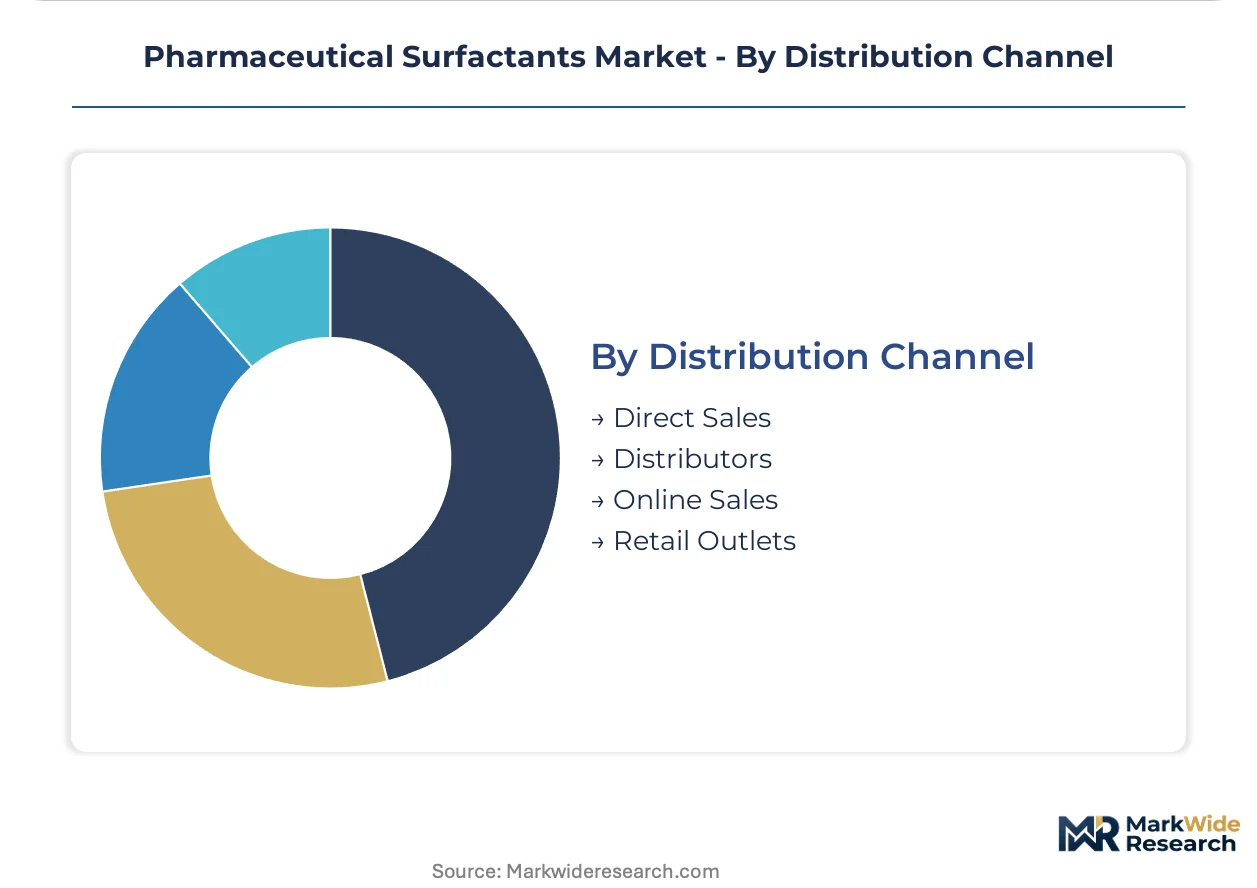
Distribution Channel:
Channel selection reflects order scale, regulatory documentation requirements, and the need for technical support integration.
- Direct Sales:High-volume pharmaceutical and biopharmaceutical accounts negotiate multi-year contracts with dedicated account management. Technical service teams coordinate regulatory submission support and customized specification development.
- Distributors:Regional chemical distributors serve mid-tier pharmaceutical manufacturers and research institutions with stocked inventory and consolidated procurement.
- Online Sales:E-procurement platforms capture laboratory-scale and developmental quantities where immediate availability outweighs price optimization.
- Retail Outlets:Minimal penetration in pharmaceutical-grade segments due to documentation and chain-of-custody requirements.
Direct sales maintains dominant share in value terms, though distributor channels are expanding coverage fastest in emerging biologic manufacturing geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European suppliers absorb elevated compliance costs. German and Swiss manufacturers face REACH registration burdens that compress margins against American competitors. This asymmetry reshapes procurement patterns across formulation-grade surfactant markets.
United States
Monoclonal antibody pipelines in Massachusetts and California drive premium-grade polysorbate consumption. FDA immunogenicity guidance tightens documentation requirements for excipient suppliers. The Boston-Cambridge biotech corridor hosts specialized CMOs that negotiate multi-year supply agreements with locked specifications.
Germany
Contract manufacturing clusters in Bavaria and North Rhine-Westphalia generate concentrated demand for GMP-certified non-ionic surfactants. EMA excipient quality standards and REACH registration pathways elevate supplier qualification costs. The Frankfurt-Rhine-Main region anchors technical service capabilities for multinational pharmaceutical accounts.
Switzerland
Basel-based biopharmaceutical innovators require endotoxin specifications below 10 EU/g for parenteral formulations. Swissmedic technical standards align with ICH guidelines to streamline cross-border supply chains. The Lake Geneva region concentrates formulation development for high-value biologics.
India
Domestic biosimilar manufacturers in Maharashtra and Telangana seek qualified excipient suppliers as CDSCO regulatory alignment with ICH standards advances. The country's national pharmaceutical regulator tightens import substitution policies for critical formulation chemicals. Hyderabad's active pharmaceutical ingredient cluster expands downstream into biologic drug production.
China
NMPA technical standards for injectable-grade materials diverge from Western compendial protocols. Yangtze River Delta pharmaceutical manufacturers upgrade purification capabilities to meet endotoxin specifications. Shanghai's contract development organizations attract multinational sponsors seeking cost-advantaged clinical material supply.
Pharmaceutical Surfactants Market Competitive Landscape
Concentration sits with integrated petrochemical conglomerates and specialized fine-chemical producers competing across distinct margin tiers. Three Western European chemical groups control bulk fatty alcohol supply chains for non-ionic surfactant production. Strategic archetypes separate into backward-integrated commodity suppliers, high-purity specialists serving biologic channels, and bio-based portfolio developers. Competitive moves center on capacity expansion in GMP-certified grades and technology licensing for continuous processing synthesis.
Among European-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify divergent positioning strategies. BASF anchors commodity-grade production through captive ethylene oxide supply. Evonik occupies the high-purity specialist tier where endotoxin control commands certification premiums. Croda International represents the bio-based archetype with lipid-derived surfactant portfolios aligned to tightening sustainability procurement criteria.
| Leading Market Players |
|---|
| Croda International |
| Clariant |
| BASF |
| Huntsman Corporation |
| Kao Corporation |
| Evonik Industries AG |
| Solvay |
| Akzo Nobel |
| Stepan Company |
| Others |
Value Network & Pricing Analysis
FDA immunogenicity guidance gates both supplier qualification and price differentiation simultaneously, separating GMP-certified polysorbate vendors from commodity producers through endotoxin documentation burdens. Certification premiums of 40-60% separate parenteral-grade materials from oral dosage alternatives, with locked manufacturing specifications commanding multi-year contract premiums.
Pricing Analysis
Configured-to-order pricing for custom endotoxin specifications and locked manufacturing processes commands substantial premiums over standard catalog grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth: parenteral-grade polysorbates with sub-10 EU/g specifications anchor the premium tier, while oral-grade materials compete on manufacturing efficiency. Pricing pressure stems from biosimilar manufacturer procurement consolidation, squeezing margins in high-volume segments. CDMO networks demonstrate lowest price sensitivity due to sponsor pass-through mechanisms, whereas Indian generic manufacturers drive aggressive standard-grade negotiation.
Supply Chain Analysis
Germany, Switzerland, and the United States anchor GMP-certified polysorbate production for parenteral applications. Ethylene oxide and fatty alcohol feedstocks draw from integrated petrochemical complexes in Western Europe and the Gulf Coast. Single-source vulnerability concentrates in ethoxylated castor oil derivatives, where three Western European conglomerates control bulk supply. Distribution runs through qualified chemical distributors with regional GMP warehousing for temperature-sensitive materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical surfactants represent early-cycle expansion as monoclonal antibody pipelines mature and biosimilar manufacturing scales across emerging biologic production hubs.
For Market Incumbents: Shield formulation-grade market share through captive ethylene oxide supply and dedicated regulatory affairs functions. Invest in continuous processing microreactors to tighten endotoxin control below 5 EU/g specifications. Defend against synthetic block copolymer substitutes by embedding technical service teams within Boston-Cambridge sponsor development pipelines. For New Entrants and Emerging Players: CDSCO alignment with ICH standards creates fast-track qualification pathways for Indian biosimilar suppliers. Target Maharashtra and Telangana formulation chemical markets where domestic biologic producers seek import substitution. Penetrate through technical partnership models with Hyderabad API clusters expanding downstream. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous processing synthesis and dedicated GMP infrastructure. Five-to-ten year viability favors acquisition of mid-cap specialists with locked supplier relationships in mAb stabilization channels. Monitor biosimilar approval trajectories as inflection indicators for premium-to-standard grade demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | BASF's captive feedstock supply secures cost leadership across bulk non-ionic grades. |
| Continuous Processing Technology | Microreactor synthesis in the Netherlands achieves tighter endotoxin control than batch methods. |
| GMP Certification Expansion | Dedicated regulatory affairs functions manage EMA centralized procedure submissions for parenteral grades. |
| Bio-Based Feedstock Transition | Rapeseed and coconut oil processors gain preferential status under EU Green Deal procurement criteria. |
| Long-Term Supply Agreements | Fixed-price escalators with Boston-Cambridge CMOs displace spot-market purchasing in premium segments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, customs/trade data, and ACC/Cefic industry reports. Interviews with drug development executives, regulatory affairs leads, CMO procurement managers, and technical R&D directors informed qualification barrier and pricing dynamics assessment. Bottom-up volume modeling triangulates against top-down value estimates from trade flow analysis.
Segmentation dimensions modeled span product type, application, end user, and distribution channel across the analysis window. Grade tier stratification, regional production hub concentration, and regulatory cluster alignment shape volume and value outputs. CAGRs derive from elasticity-adjusted demand projections tied to monoclonal antibody pipeline maturation and biosimilar manufacturing expansion.
Decision-makers should treat outputs as directional under assumptions of sustained biologic pipeline investment and stable regulatory harmonization; material deviation in FDA guidance stringency or ICH implementation pace would warrant model refresh. Recalibration cycles align with material shifts in biosimilar approval volumes and excipient quality standard updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Chlorooctane Market
Surfactants
Alkyl Polyglucoside (APG) Surfactant Market
Surfactants
Soap Salts Market
Surfactants
Sulfate Free Body Wash Market
Surfactants
Dodecanol Market
Surfactants
Global Calcium Sulfonate Market
Surfactants
Global Fluorosurfactants Market
Surfactants
Detergent Grade Zeolite Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Naphthalene Sulfonate Market
Surfactants
Surfactant EOR Market
Surfactants
Tetradecyl Chloride Market
Surfactants
Global Rhamnolipid Market
Surfactants
Polyoxyethylene Sorbitan Tristearate Market
Surfactants
Cetanol Market
Surfactants
Detergent Chemicals Market