
 North America Hydrochloric Acid Market | 2026-2036
North America Hydrochloric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hydrochloric Acid Market Analytics
Market Context
The EPA Risk Management Plan amendments are broadening compliance-driven investment in hydrochloric acid handling systems across chemical processing facilities. Olin Corporation leverages its integrated chlorine-alkali network to sustain cost advantages in merchant acid supply throughout the Gulf Coast. Westlake Corporation anchors regional production capacity through its chlorovinyls manufacturing complex in Louisiana. Dow Chemical Company differentiates via deep technical service relationships with oilfield and refining customers.
Technical Definition and Segment Structure
Hydrochloric acid is an aqueous solution of hydrogen chloride typically manufactured at concentrations between 31% and 37% by weight through the direct synthesis of hydrogen and chlorine or as a byproduct of chlorination processes, serving primarily as a strong mineral acid for pH adjustment, metal surface treatment, and chloride salt production. Industrial grade material dominates volume throughput due to its ubiquity in steel pickling and oil well acidizing operations, while electronic grade commands premium positioning as semiconductor fabrication demands ultrapure reagents for wafer etching and cleaning protocols. Reagent grade consumption is accelerating in pharmaceutical quality control laboratories where USP and ACS specification compliance determines supplier qualification.
Regulatory Frame and Outlook
EPA oversight under the Clean Air Act and TSCA, alongside OSHA Process Safety Management standards, shapes facility design, emissions controls, and worker exposure limits for hydrochloric acid producers and handlers throughout the United States. Health Canada and Environment and Climate Change Canada administer parallel frameworks under the Canadian Environmental Protection Act and WHMIS hazard classification requirements. Stakeholders must monitor evolving PFAS contamination scrutiny that could redirect chlor-alkali process investments and alter byproduct acid availability across North American supply chains.
Market Dynamics
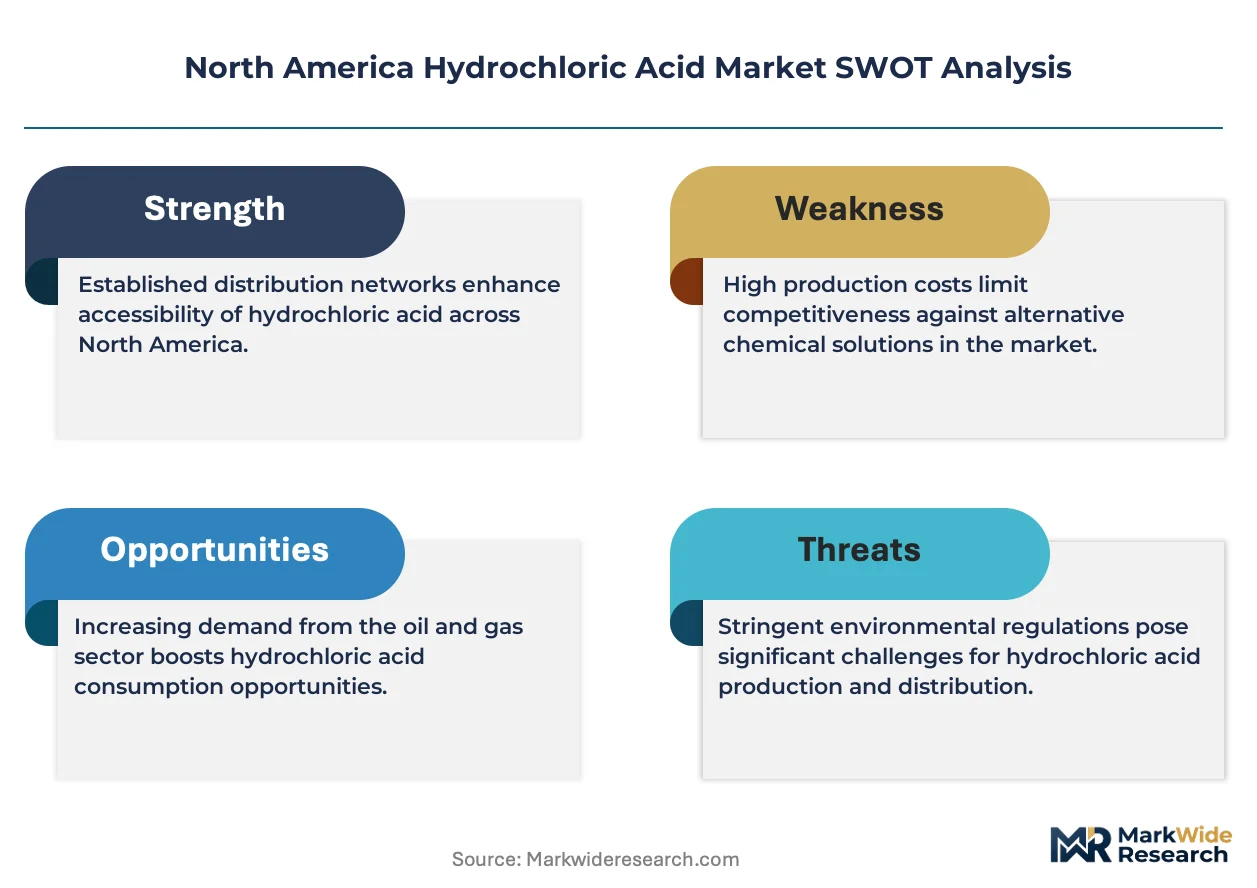
EPA Risk Management Plan amendments are forcing facility-wide overhauls in hydrochloric acid storage, containment, and emergency response systems across the US chemical processing corridor, redirecting capital from expansion into compliance infrastructure.
Growth Catalysts
- Steel Pickling Intensity:Automotive lightweighting programs are expanding cold-rolled high-strength steel consumption across Michigan and Ohio manufacturing clusters, directly lifting acid demand for surface oxide removal prior to galvanizing.
- REACH-Aligned Import Standards:Canadian regulators under the Environmental Protection Act are tightening purity documentation requirements for cross-border acid shipments, favoring integrated producers with captive analytical capabilities.
- Hydrogen Chloride Recovery Systems:Chlor-alkali operators are installing membrane cell retrofits that capture previously vented acid byproduct, expanding merchant supply availability without incremental chlorine demand.
Market Restraints
- Chlorine Feedstock Volatility:Electrolytic chlorine production consumes 2,100-2,400 kWh per ton, exposing acid economics to ERCOT and PJM electricity price spikes during summer peak demand periods.
- Gulf Coast Concentration Risk:Over 60% of North American merchant acid capacity sits within 200 miles of Houston, creating single-point vulnerability to hurricane-induced logistics disruption and force majeure declarations.
- Organic Acid Substitution:Citric and formic acid formulations are displacing mineral acid in select food-grade and pharmaceutical pH adjustment applications where chloride contamination tolerance has tightened.
Strategic Opportunities
- Alberta Oil Sands Expansion:SAGD well stimulation programs in the Athabasca basin are accelerating demand for 28-32% acid strength formulations tailored to carbonate formation dissolution.
- Semiconductor Fabrication:Electronic-grade acid specifications for 3nm node wafer etching are creating qualification windows for producers with sub-ppb metal contamination control and dedicated fluoropolymer packaging lines.
- Carbon Capture Retrofits:Post-combustion amine scrubbing installations at Texas and Louisiana refineries are generating new demand for acid regeneration in solvent recovery loops, diverting supply from traditional end-uses.
Industry Challenges
- Corrosion Engineering Talent Scarcity:Facility operators face acute shortages of materials specialists capable of specifying Hastelloy and titanium alloy systems for high-temperature acid service above 40% concentration.
- Process Safety Management Audit Compression:OSHA PSM three-year compliance cycles are accelerating to 18-month intervals for facilities with prior release incidents, consuming engineering resources that would otherwise support debottlenecking projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hydrochloric Acid Market |
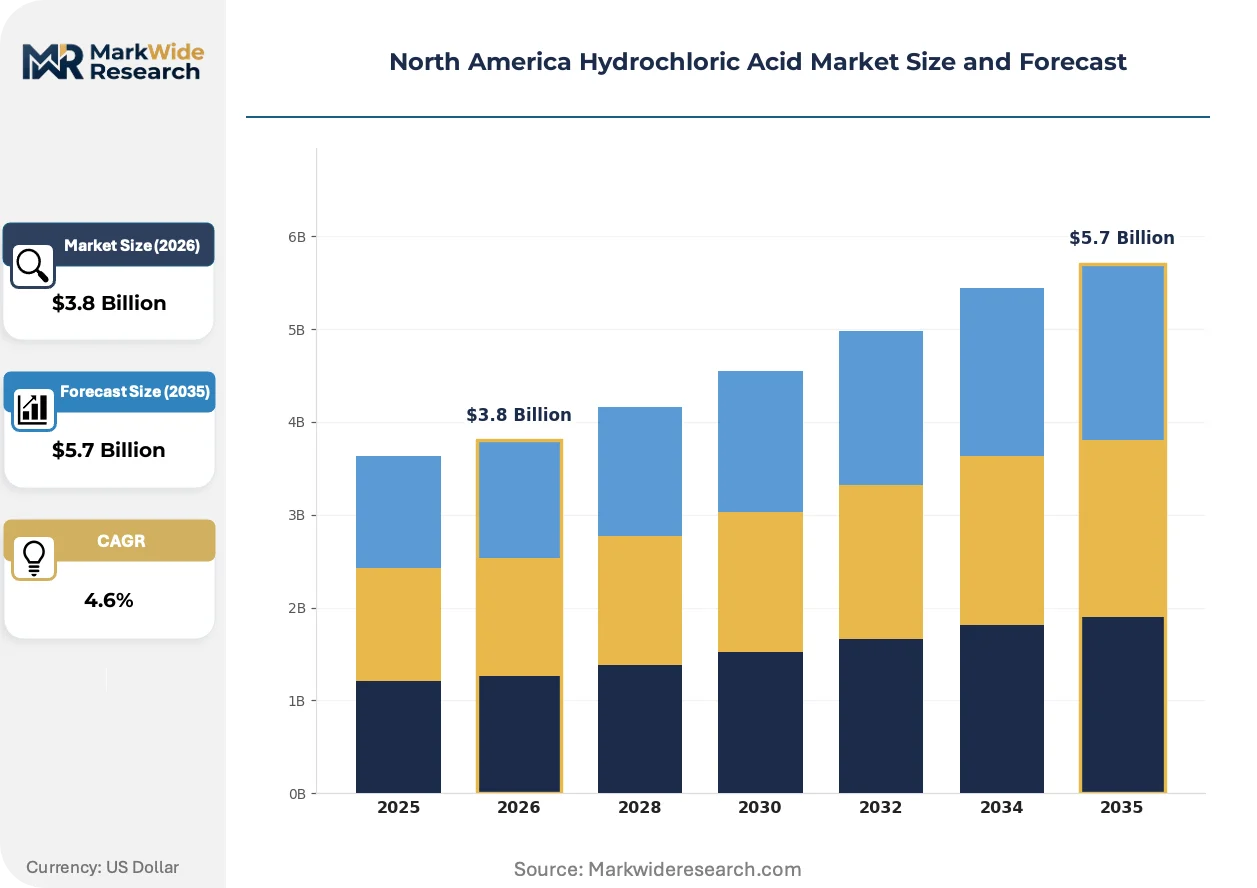
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Food Grade, Electronic Grade Application: Metal Cleaning, pH Control, Production of Chlorides, Food Processing End User: Chemical Manufacturing, Food & Beverage, Pharmaceuticals, Water Treatment Packaging Type: Drums, Totes, Bulk, Cylinders |
| Companies Covered | Olin Corporation, Occidental Petroleum Corporation, Westlake Corporation, ERCO Worldwide, Detrex Corporation, Formosa Plastics Corporation, U.S.A., Celanese Corporation, Dow Chemical Company, ASHTA Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hydrochloric Acid Market Evolving Landscape
Digital twin modeling of acid regeneration loops is compressing maintenance intervals and extending asset life across chlor-alkali integrated sites, while purity-grade stratification is fragmenting procurement specifications.
Membrane electrolysis technology is converging with real-time conductivity monitoring to enable continuous acid strength adjustment without batch neutralization. Chlor-alkali operators in Texas and Louisiana are deploying these systems to serve just-in-time delivery contracts with oilfield service companies. The convergence is compressing working capital requirements for midstream acid distributors who previously maintained 30-day inventory buffers.
EPA's updated Risk Management Plan rule is mandating third-party compliance audits and enhanced release modeling for facilities handling threshold quantities of hydrogen chloride. Chemical processors are responding by consolidating acid storage into fewer, larger containment structures with redundant secondary containment. The rule most acutely affects smaller independent terminals lacking in-house process safety engineering staff.
Buyers in the steel pickling segment are unbundling acid supply from spent acid recovery services, previously contracted as integrated packages. Large automotive tier-one suppliers are now sourcing acid directly from chlor-alkali producers while awarding regeneration and waste handling to specialized environmental service firms. This bifurcation is most visible across the Great Lakes corridor where integrated mill closures have eliminated captive acid supply options.
North America Hydrochloric Acid Market Segmentation
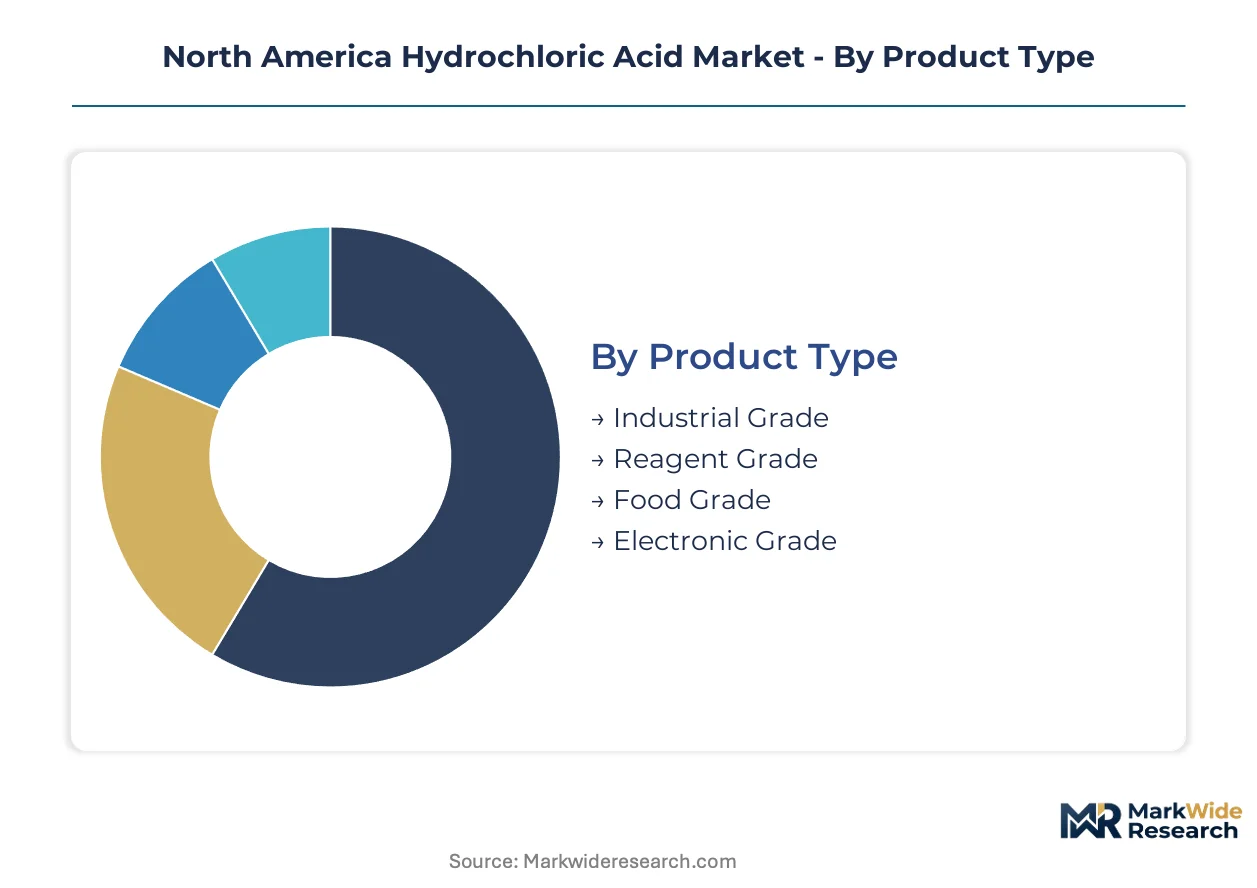
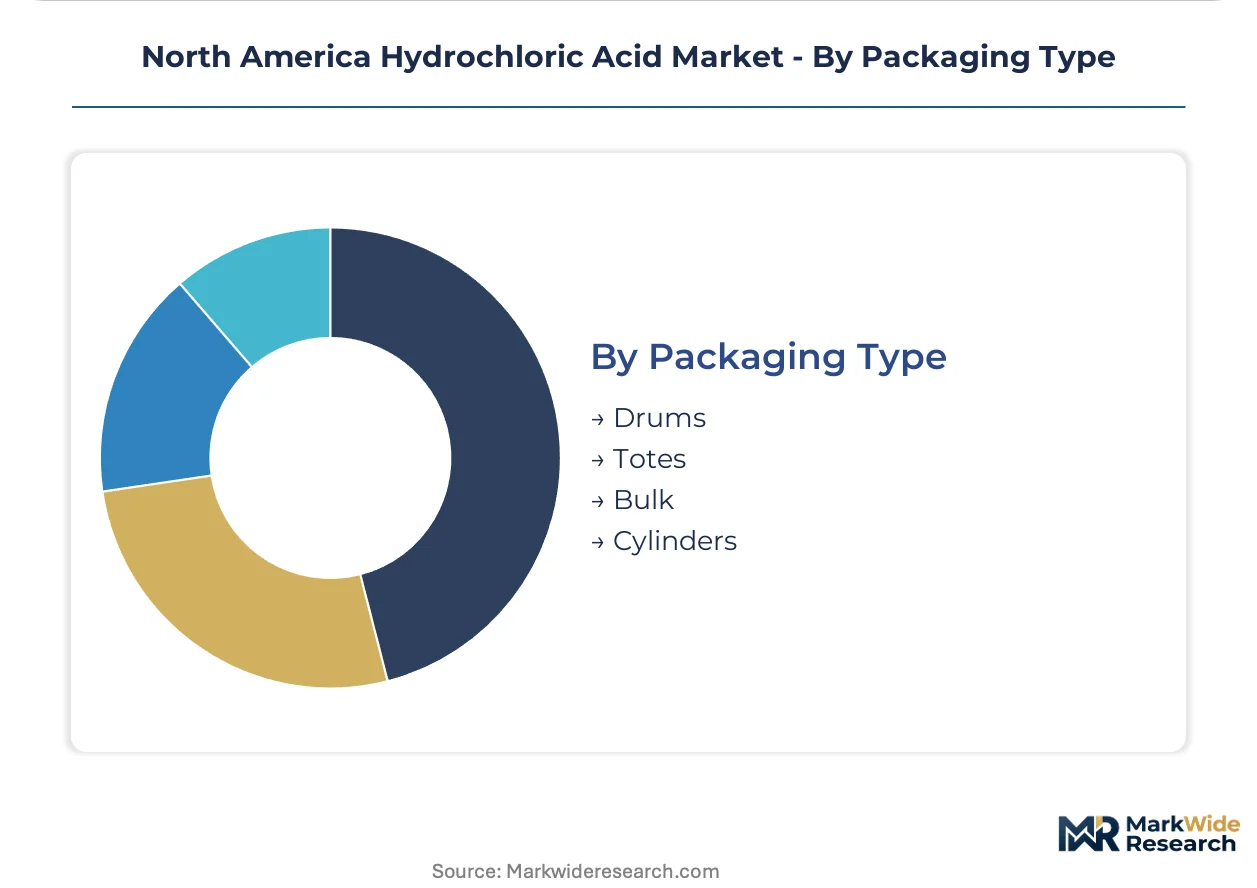
Segmentation in hydrochloric acid markets reveals how purity specifications and delivery formats map to distinct value capture opportunities. Each dimension carries different margin profiles and regulatory exposure, shaping supplier portfolio priorities across the North American supply base.
Product Type:
Integration depth varies sharply across grades, with electronic and reagent grades demanding captive purification infrastructure while industrial grade flows through merchant distribution networks.
- Industrial Grade:Manufactured at 31-37% concentration with controlled iron and heavy metal content for steel pickling and oilfield acidizing. Demand concentrates in Texas and Louisiana petrochemical corridors where chlor-alkali integration provides cost leverage.
- Electronic Grade:Sub-ppb metal contamination specifications for semiconductor wafer etching at 3nm nodes require dedicated fluoropolymer packaging and nitrogen-blanketed storage. Arizona and Oregon fabrication clusters are tightening qualification windows for regional suppliers.
- Reagent Grade:USP and ACS compliance for pharmaceutical quality control laboratories.
- Food Grade:FCC specifications for acidulation and pH adjustment in processing facilities.
Industrial grade leads volumes today; electronic grade is gaining share fastest.
Application:
Cost tier stratification separates commodity pH adjustment from specialized surface treatment where acid consumption correlates with manufacturing intensity.
- Metal Cleaning:Steel pickling for automotive lightweighting programs across Michigan and Ohio manufacturing clusters drives 28-32% acid strength formulations for oxide removal prior to galvanizing.
- pH Control:Wastewater neutralization and process water adjustment in chemical manufacturing facilities.
- Production of Chlorides:Feedstock for calcium chloride, ferric chloride, and polyaluminum chloride manufacturing.
- Food Processing:Acidulation of corn syrups and protein isolates where chloride tolerance permits.
Metal cleaning dominates revenue today; pH control applications are expanding most quickly.
End User:
Customer type determines contract structure, with chemical manufacturers favoring pipeline delivery while pharmaceutical buyers demand lot-level documentation.
- Chemical Manufacturing:Integrated chlor-alkali operators and merchant acid consumers across the Gulf Coast.
- Food & Beverage:Corn wet milling and protein processing facilities in Iowa and Illinois.
- Pharmaceuticals:API synthesis and quality control laboratories requiring reagent-grade specifications with full chain-of-custody documentation.
- Water Treatment:Municipal and industrial facilities using acid for pH correction and alkalinity reduction.
Chemical manufacturing anchors volume today; pharmaceuticals shows the steepest expansion trajectory.
Packaging Type:
Supply concentration in bulk formats reflects infrastructure economics, while specialized containers serve dispersed or high-purity demand nodes.
- Bulk:Railcar and tank truck delivery to integrated chemical facilities and large steel mills.
- Drums:55-gallon steel or composite containers for mid-volume industrial applications.
- Totes:Intermediate bulk containers for food processing and water treatment facilities.
- Cylinders:High-pressure gas-phase hydrogen chloride for semiconductor and specialty chemical applications.
Bulk delivery leads volumes today; totes are climbing the fastest among smaller formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American hydrochloric acid industry traces its modern scale to post-war chlor-alkali expansion along the Gulf Coast, where integrated chemical complexes established the continent's dominant production base.
United States
Steel pickling demand from automotive lightweighting programs drives consumption across Michigan and Ohio manufacturing corridors. EPA Risk Management Plan amendments are compelling facility-wide storage and containment upgrades at chemical processing sites. The Texas-Louisiana petrochemical cluster anchors over sixty percent of merchant acid capacity, with chlor-alkali integration providing sustained cost leverage.
Canada
Alberta oil sands SAGD well stimulation programs are accelerating demand for diluted acid formulations tailored to carbonate formation dissolution. Health Canada and Environment and Climate Change Canada administer tightened purity documentation requirements under the Environmental Protection Act for cross-border shipments. The Sarnia-Lambton chemical valley in Ontario concentrates refining and petrochemical acid consumption.
Mexico
Automotive manufacturing expansion across Nuevo León and Bajío Region states is lifting steel surface treatment demand from tier-one suppliers. Mexican regulators align import standards with REACH-equivalent frameworks, favoring integrated producers with captive analytical capabilities. Altamira petrochemical complexes on the Tampico corridor are expanding chlor-alkali derivative output.
North America Hydrochloric Acid Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity-grade stratification, with electronic and reagent-grade specialists capturing superior returns while industrial-grade merchants compete on chlor-alkali integration depth. The vendor base clusters around three strategic archetypes: integrated chlorine-alkali operators with captive acid byproduct, independent merchant producers relying on hydrogen chloride recovery systems, and specialty distributors serving high-purity semiconductor and pharmaceutical qualification windows. Dominant competitive moves include membrane cell retrofits that expand merchant supply without incremental chlorine demand, and consolidation of acid storage into fewer larger containment structures with redundant secondary containment.
Within the integrated operator tier, Olin Corporation and Westlake Corporation exemplify Gulf Coast chlor-alkali integration strategies, while Dow Chemical Company occupies a position emphasizing technical service depth with oilfield and refining customers.
| Leading Market Players |
|---|
| Olin Corporation |
| Occidental Petroleum Corporation |
| Westlake Corporation |
| ERCO Worldwide |
| Detrex Corporation |
| Formosa Plastics Corporation, U.S.A. |
| Celanese Corporation |
| Dow Chemical Company |
| ASHTA Chemicals |
| Others |
Value Network & Pricing Analysis
EPA Risk Management Plan amendments gate qualified supply and premium-tier pricing access for hydrochloric acid handlers, compelling facility-wide containment upgrades that bifurcate the vendor base between compliant integrated operators and stranded independent terminals. Chlor-alkali producers with captive membrane cell retrofits capture margin expansion while non-compliant distributors face forced exit or acquisition.
Pricing Analysis
Contract-based long-term offtake dominates industrial grade transactions, with price differentiation resting on chlor-alkali integration depth and EPA compliance certification status. Electronic and reagent grades command premium positioning through sub-ppb contamination control and dedicated fluoropolymer packaging. Cost compression in industrial grade is intensifying because merchant buyers are unbundling acid supply from spent acid recovery services. Steel pickling operations across Michigan and Ohio manufacturing clusters exhibit highest price sensitivity, while semiconductor fabrication facilities in Arizona and Oregon show least sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Railcar and tank truck logistics costs from Gulf Coast production clusters to Great Lakes manufacturing corridors constrain merchant acid economics, with freight representing a structural cost layer above chlor-alkali variable production. Supply concentrates in the United States, Canada, and Mexico, with over sixty percent of North American merchant capacity sitting within two hundred miles of Houston. Raw material dependencies center on electrolytic chlorine, hydrogen feedstock, and electricity from ERCOT and PJM grids. Hurricane-induced logistics disruption creates persistent single-point vulnerability. Distribution runs through integrated chemical facilities, midstream distributors, and specialized environmental service firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EPA Risk Management Plan amendments driving demand for compliant handling infrastructure and qualified supply.
For Market Incumbents: Deploy membrane cell retrofit programs to expand merchant acid supply without incremental chlorine demand, capturing volume from stranded independent terminals lacking compliance engineering staff. Consolidate acid storage into fewer larger containment structures with redundant secondary containment to deflect OSHA PSM audit compression. Organic acid substitution in food-grade and pharmaceutical pH adjustment applications threatens industrial grade margin pools. For New Entrants and Emerging Players: Specialized environmental service firms represent the most penetrable channel partner type for acid regeneration and waste handling services, as automotive tier-one suppliers unbundle these functions from acid supply contracts. Target Alberta oil sands SAGD well stimulation programs with 28-32% acid strength formulations tailored to carbonate formation dissolution. Pursue qualification windows for electronic-grade supply to Arizona and Oregon semiconductor fabrication clusters. For Investors and Strategic Acquirers: Roll-up economics work for regional midstream acid distributors because EPA compliance mandates are forcing consolidation among sub-scale terminals lacking in-house process safety engineering staff. Long-term viability hinges on captive chlor-alkali integration or specialized high-purity qualification capabilities. Watch membrane electrolysis technology adoption rates as inflection indicator for merchant supply expansion without incremental chlorine demand.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Retrofit | Captures previously vented acid byproduct, expanding merchant supply without incremental chlorine demand across Texas and Louisiana. |
| Electronic Grade Qualification | Enables premium positioning for semiconductor wafer etching at 3nm nodes through sub-ppb metal contamination control. |
| Carbon Capture Retrofit | Diverts acid supply to post-combustion amine scrubbing installations at Texas and Louisiana refineries. |
| Spent Acid Recovery Unbundling | Separates acid supply from regeneration services, creating specialized environmental service firm opportunities. |
| Containment Consolidation | Consolidates storage into fewer larger structures with redundant secondary containment to satisfy EPA Risk Management Plan mandates. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction triangulated against secondary validation. Interviews with chlor-alkali plant managers, steel mill procurement leads, oilfield service company technical directors, and semiconductor fabrication chemical specialists inform demand-side dynamics. Secondary sources include EPA enforcement databases, SEC 10-K filings from integrated chemical operators, American Chemistry Council production surveys, and Health Canada cross-border shipment records. Bottom-up volume modeling and top-down value reconciliation anchor quantitative outputs.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon. Segmentation dimensions include grade tier (industrial, electronic, reagent, food), end-use industry (chemical manufacturing, steel pickling, oilfield services, semiconductor fabrication, pharmaceuticals), packaging format (bulk, drums, totes, cylinders), and regional production hub (Gulf Coast, Great Lakes, Alberta, Nuevo León). CAGRs derive from regression analysis against industrial production indices, automotive lightweighting program trajectories, and oil well completion activity. Chlor-alkali capacity utilization rates and electricity price volatility from ERCOT and PJM grids feed industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PFAS contamination scrutiny redirecting chlor-alkali process investments and altering byproduct acid availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Silicate Market
Bulk Chemicals
Aluminum Sulfide Market
Bulk Chemicals
Global Linear Alpha Olefins Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
Sulfur Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
North America N-Hexane Market
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Europe Caustic Potash Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
2-Ethylhexanoyl Chloride Market
Bulk Chemicals
Calcium Carbonate Market