
 Europe Calcium Chloride Market | 2026-2036
Europe Calcium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Calcium Chloride Market Intelligence
The EU F-Gas Regulation is rebalancing the competitive landscape for de-icing and industrial chemical suppliers. TETRA Chemicals Europe leverages its integrated production network to sustain cost advantages across Nordic and Central European markets. Solvay S.A. anchors its position through specialized food-grade and pharmaceutical-grade calcium chloride portfolios. Zirax Limited competes on technical-grade purity standards for oilfield and construction applications.
Calcium chloride is an inorganic salt with the formula CaCl₂, typically produced via the Solvay process or as a by-product of soda ash manufacturing, and functions primarily as a hygroscopic desiccant, freezing-point depressant, and cement accelerator. Industrial grade dominates volume offtake due to its deployment in road de-icing and dust suppression across Germany, Poland, and Scandinavia. Food grade commands premium positioning within preservation and cheese-making applications, where E509 compliance under EFSA frameworks creates margin pools. Bulk packaging leads logistics economics for municipal de-icing contracts, though bagged formats sustain flexibility among mid-sized food processors and agricultural distributors.
REACH compliance and the EU Green Deal's carbon-border adjustment mechanisms are tightening production standards and reshaping import competitiveness from non-European suppliers. ECHA substance evaluations and national environmental agencies in Germany and France are enforcing stricter effluent controls on calcium chloride manufacturing. EFSA purity mandates for food-grade certification continue to elevate technical barriers for new entrants. Stakeholders must monitor the interplay between carbon-border tariffs and domestic production subsidies to calibrate sourcing and capacity decisions.
Market Dynamics
The EU Green Deal's carbon-border adjustment mechanisms are forcing calcium chloride producers to reconfigure energy inputs and sourcing footprints, compressing margins for import-dependent distributors while rewarding integrated Nordic manufacturers with captive energy assets.
Growth Catalysts
- Nordic De-Icing Mandates:Municipalities across Sweden, Norway, and Finland maintain statutory road safety obligations that institutionalize winter calcium chloride consumption regardless of price cycles.
- REACH Compliance Barriers:ECHA substance evaluation protocols create defensible positions for incumbent European producers against lower-cost non-European imports lacking registration data.
- Food-Grade Certification Expansion:EFSA purity mandates for E509 compliance in cheese-making and preservation applications generate premium margin pools distinct from commodity industrial grades.
Market Restraints
- Natural Gas Cost Volatility:Solvay process energy intensity exposes producers to TTF hub price swings that erode cost competitiveness against soda ash by-product supply.
- Limestone Feedstock Concentration:High-calcium stone suitable for food-grade production concentrates in specific Jura Mountain quarries, creating geographic supply vulnerability.
- Magnesium Chloride Substitution:Road maintenance authorities in Germany and Poland increasingly blend MgCl₂ formulations that reduce pure calcium chloride tonnage per lane-mile treated.
Strategic Opportunities
- Eastern European Infrastructure Buildout:Polish and Romanian highway expansion programs create de-icing demand growth corridors underserved by existing distribution networks.
- Carbon Capture Integration:Producers retrofitting Solvay plants with amine-based CO₂ capture qualify for EU Innovation Fund subsidies and scope 3 reduction credits.
- Direct-to-Food-Processor Channels:Bypassing agricultural distributors to supply dairy cooperatives in the Netherlands and Ireland captures margin currently lost to intermediaries.
Industry Challenges
- Process Engineering Talent Scarcity:Solvay process optimization and brine purification expertise concentrates among retiring cohorts at legacy Belgian and German facilities.
- REACH Registration Renewal Complexity:ECHA's 2024-2027 dossier update timeline demands toxicology data regeneration that strains mid-tier producer R&D budgets.
- Legacy Packaging Line Retrofit Costs:Transitioning from bulk municipal tenders to food-grade bagged formats requires capital deployment in automated filling and traceability systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Calcium Chloride Market |
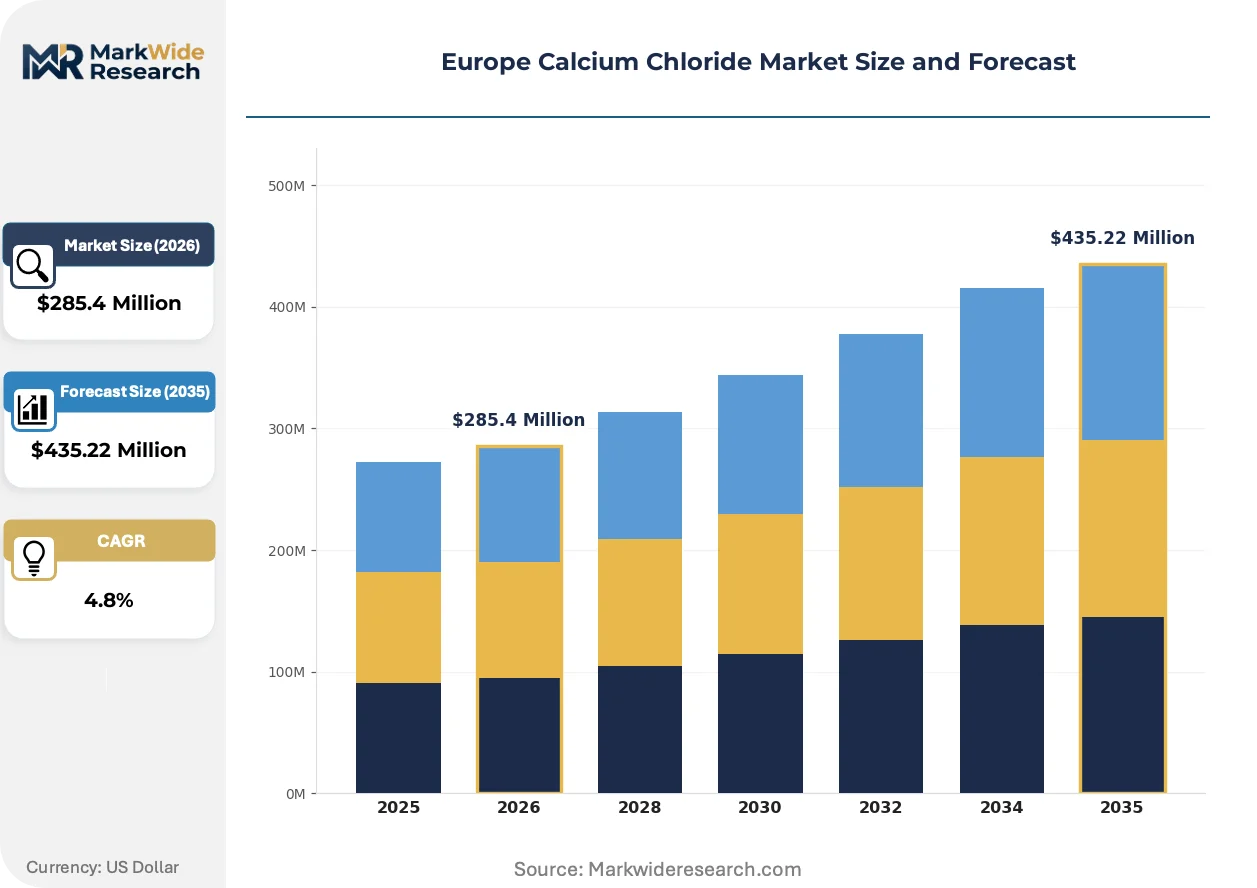
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: De-icing, Dust Control, Food Preservation, Drying Agent Grade: Industrial Grade, Food Grade, Technical Grade, Anhydrous Packaging Type: Bags, Drums, Bulk, Pallets End User: Chemical Industry, Food Industry, Construction, Agriculture |
| Companies Covered | TETRA Chemicals Europe, Zirax Limited, Solvay S.A., Tangshan Sanyou Chemical Industries Co. Ltd., Weifang Haibin Chemical Co. Ltd., Occidental Chemical Corporation, Ward Chemical Ltd., Qingdao Huadong Calcium Producing Co. Ltd., Tata Chemicals Europe, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Calcium Chloride Market Strategic Shifts & Innovations
Production decarbonization and purity segmentation are bifurcating competitive positions, with low-carbon process credentials becoming a separable product attribute rather than a uniform baseline expectation.
Membrane electrolysis brine concentration is overtaking traditional thermal evaporation in new European capacity investments. Food-grade producers in Belgium and Switzerland deploy this technology to achieve EFSA-mandated heavy metal thresholds without multiple recrystallization stages. The capital efficiency and energy intensity advantages are compressing payback periods for greenfield installations below six years.
CSRD disclosure requirements are mandating scope 3 supply chain transparency for chemical distributors serving municipal buyers. German and French public procurement frameworks now embed carbon intensity scoring that disadvantages imports lacking verified production data. Industrial-grade suppliers are responding by securing mass-balance certifications and blockchain-tracked logistics documentation.
Consolidated tendering by Nordic municipal purchasing cooperatives is displacing fragmented county-level procurement. Swedish and Norwegian road authorities now contract through centralized bodies that demand multi-year price commitments and guaranteed winter stockpile availability. This behavioral shift favors producers with integrated storage terminals over traders lacking physical asset backing.
Europe Calcium Chloride Market Segmentation
Calcium chloride demand fragments across distinct performance specifications and delivery formats. Grade purity and packaging economics determine margin capture, while application requirements dictate regional deployment patterns across Nordic and Central European markets.
Application:
Standalone bulk consumption dominates road maintenance and industrial processes, whereas embedded formulations in food systems and specialty chemicals demand precision integration.
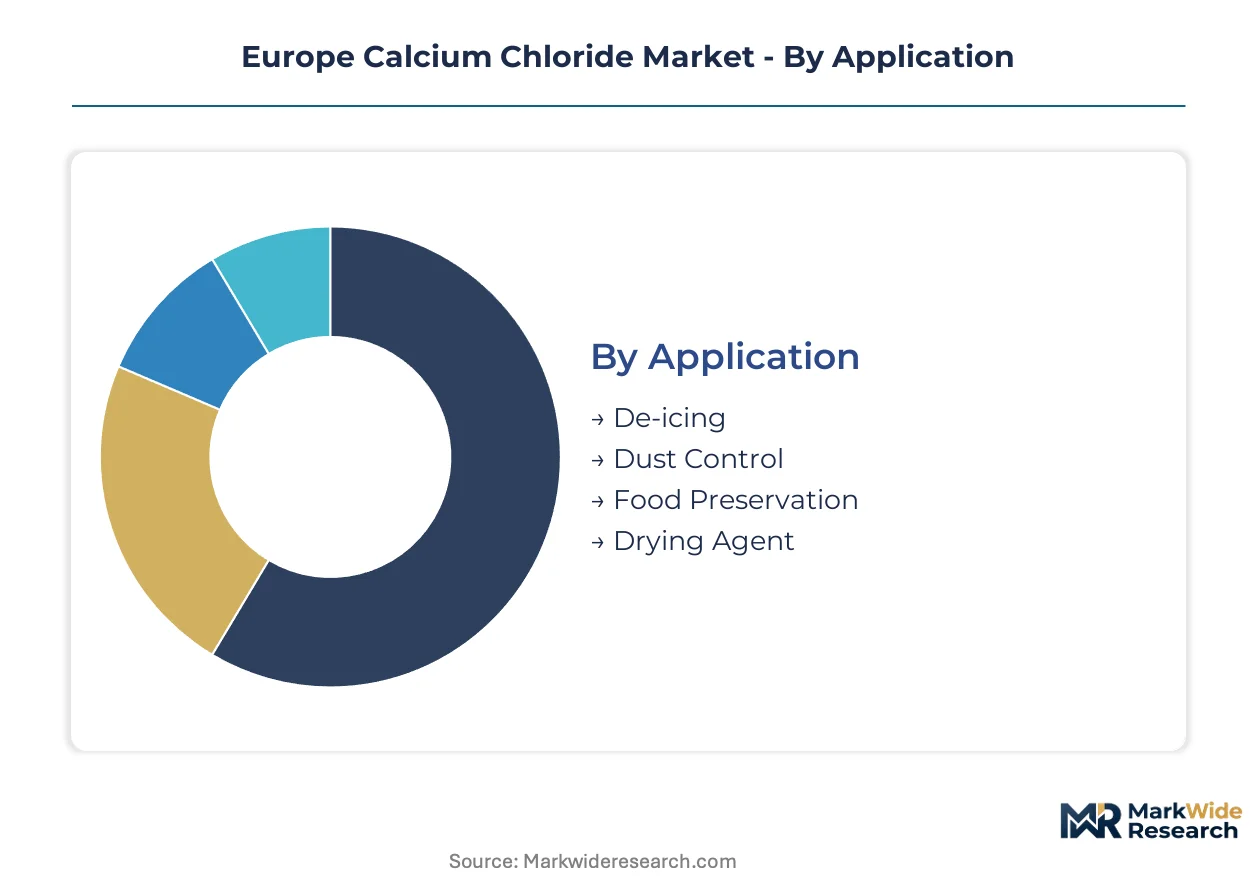
- De-icing:Municipal road authorities deploy calcium chloride as a freezing-point depressant for winter highway safety across Sweden, Norway, and Finland. Nordic statutory obligations institutionalize this consumption regardless of price cycles, creating predictable offtake volumes tied to climatic severity rather than economic conditions.
- Dust Control:Mining operations and unpaved road maintenance in Poland and Romania utilize calcium chloride hygroscopicity to suppress particulate emissions. Infrastructure expansion in Eastern European extractive industries is accelerating adoption where environmental compliance pressures intensify.
- Food Preservation:E509-compliant applications in cheese-making and brining operations require certified purity grades.
- Drying Agent:Desiccant applications in chemical processing and gas dehydration concentrate in German industrial corridors.
Volume placements concentrate in De-icing; the faster expansion belongs to Dust Control.
Grade:
Cost tiers separate commodity industrial supply from certified food and pharmaceutical channels, with purity thresholds determining accessible end-markets and margin structures.
- Industrial Grade:Road de-icing and dust suppression applications tolerate higher impurity loads, enabling Solvay process by-product sourcing. German and Polish municipal tenders prioritize cost efficiency over purity, sustaining volume leadership despite thinner margins.
- Food Grade:EFSA-mandated heavy metal thresholds and E509 certification requirements restrict supply to Jura Mountain limestone feedstock and membrane electrolysis purification. Dairy cooperatives in the Netherlands and Ireland pay premiums for traceable provenance.
- Technical Grade:Oilfield and construction applications demand consistent assay without food-certification overhead.
- Anhydrous:Desiccant and chemical synthesis applications require minimal moisture content specifications.
Industrial Grade commands absolute tonnage; Food Grade captures the steepest margin expansion trajectory.
Packaging Type:
Customer scale and handling infrastructure determine format selection, with automated systems favoring bulk and mid-sized operations requiring unitized flexibility.
- Bulk:Municipal de-icing contracts and large chemical processors receive pneumatic or conveyor-fed deliveries. Nordic purchasing cooperatives now mandate guaranteed stockpile availability, favoring producers with integrated storage terminals.
- Bags:Mid-sized food processors and agricultural distributors require 25-50kg formats for manual handling. Automated filling and traceability system investments are compressing per-unit logistics costs.
- Drums:Specialty chemical and pharmaceutical applications utilize sealed containment for moisture-sensitive anhydrous grades.
- Pallets:Distribution efficiency for bagged consolidation serves regional agricultural and construction supply chains.
Bulk tonnage dominates municipal procurement; bagged formats are climbing fastest as food-grade channel direct sales expand.
End User:
Maturity gradients separate established chemical and construction demand from emerging agricultural and food-processing growth corridors.
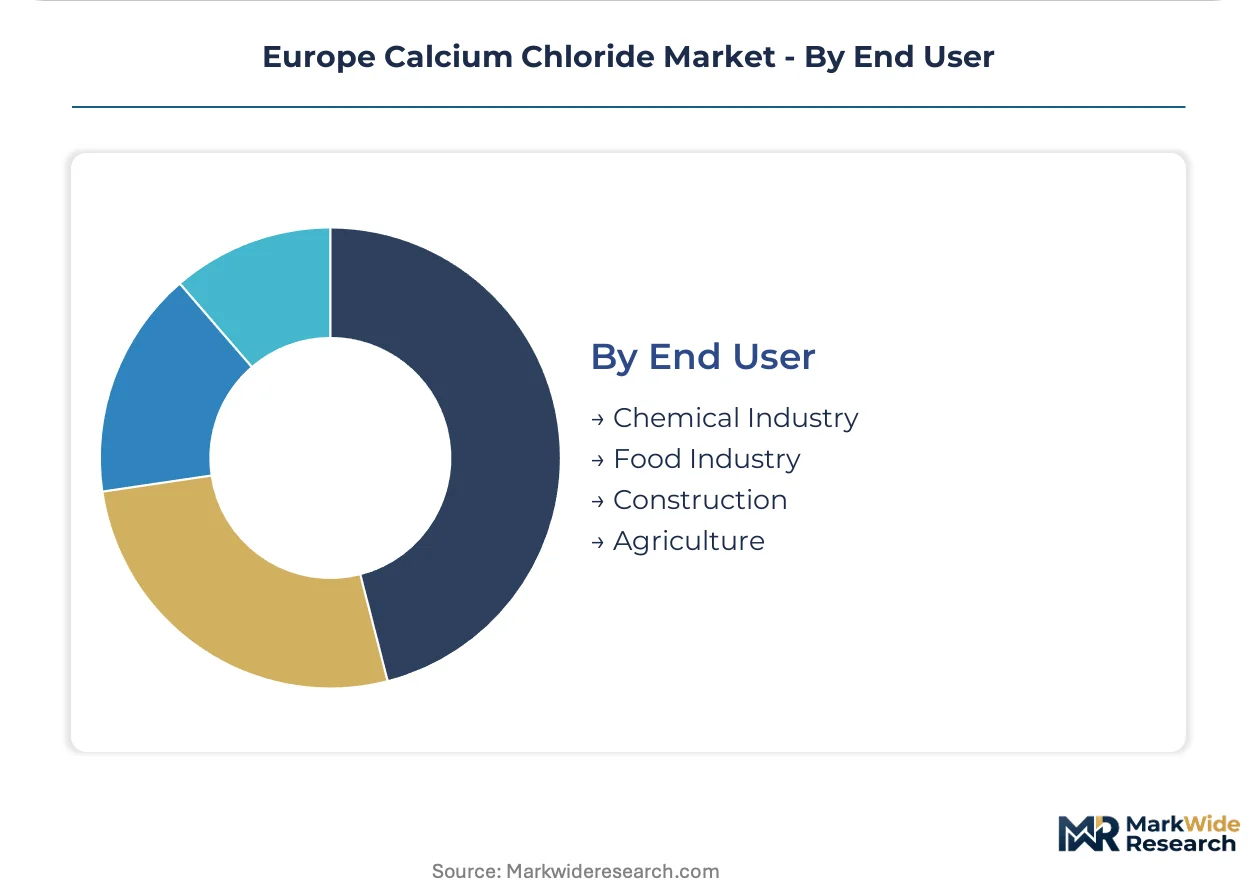
- Chemical Industry:Soda ash co-production and inorganic synthesis absorb substantial calcium chloride volumes. Solvay process integration at Belgian and German legacy facilities sustains captive supply economics.
- Food Industry:Cheese-making cooperatives and preservation processors in the Netherlands, Ireland, and Denmark require E509-compliant supply. Direct-to-processor channels are displacing agricultural distributor intermediation.
- Construction:Cement acceleration and concrete curing applications concentrate in German and Polish infrastructure projects.
- Agriculture:Soil stabilization and livestock dust suppression in Eastern European farming operations represent underpenetrated expansion potential.
Chemical Industry tonnage anchors current supply; Food Industry channels are expanding most quickly as certification barriers elevate technical-grade premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, where chemical processing and winter road maintenance create sustained offtake. Nordic municipalities institutionalize consumption through statutory road safety obligations. Eastern European infrastructure expansion is opening growth corridors underserved by existing distribution networks.
Germany
Road de-icing and chemical processing absorb the majority of German calcium chloride offtake. The KBA enforces winter road maintenance standards that mandate pre-positioned stockpiles before November. The North Rhine-Westphalia industrial corridor hosts integrated Solvay process facilities that supply captive soda ash co-production.
Sweden
Statutory road safety obligations institutionalize winter calcium chloride consumption regardless of price cycles. The Swedish Transport Administration consolidated tendering through centralized purchasing cooperatives that demand multi-year price commitments. Stockholm and Gothenburg anchor distribution networks requiring guaranteed winter stockpile availability.
Poland
Highway expansion programs and mining dust suppression are accelerating adoption across Polish infrastructure projects. EU Green Deal carbon-border adjustment mechanisms are tightening production standards for import-dependent distributors. The Silesian mining belt generates concentrated demand for hygroscopic dust control applications.
Netherlands
Cheese-making cooperatives and dairy processors require E509-compliant food-grade supply with traceable provenance. EFSA purity mandates restrict supply to certified membrane electrolysis purification. The Rotterdam chemical cluster serves as a distribution hub for food-grade bagged formats.
Belgium
Legacy Solvay process facilities sustain captive supply economics for industrial-grade production. ECHA substance evaluation protocols create defensible positions against non-European imports lacking registration data. The Antwerp industrial zone concentrates brine purification expertise among established chemical operations.
Europe Calcium Chloride Market Key Industry Players
Nordic producers anchor one tier; Central European specialists hold certification-driven positions. The vendor base splits between integrated chemical conglomerates with captive energy assets and focused distributors serving municipal tenders. Three archetypes dominate: Solvay-integrated manufacturers, membrane-electrolysis food-grade specialists, and import-dependent traders. Competitive moves concentrate on securing mass-balance certifications and retrofitting plants with carbon capture integration.
Within the integrated production tier, TETRA Chemicals Europe and Solvay S.A. exemplify archetypes with captive supply networks. Zirax Limited occupies a position among technical-grade specialists serving oilfield and construction applications. These three represent the competitive spectrum from commodity industrial supply through certified food-grade channels.
| Leading Market Players |
|---|
| TETRA Chemicals Europe |
| Zirax Limited |
| Solvay S.A. |
| Tangshan Sanyou Chemical Industries Co. Ltd. |
| Weifang Haibin Chemical Co. Ltd. |
| Occidental Chemical Corporation |
| Ward Chemical Ltd. |
| Qingdao Huadong Calcium Producing Co. Ltd. |
| Tata Chemicals Europe |
| Others |
Cost & Logistics Intelligence
Solvay process engineering expertise concentrates among aging cohorts at legacy Belgian and German facilities, and labor-cost differentials between these established chemical corridors and emerging Eastern European production zones drive pricing-tier spreads across industrial and food-grade segments.
Pricing Analysis
Volume-municipal de-icing contracts trade at thin margins against food-grade membrane-electrolysis output capturing steeper premiums. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified dairy supply from technical-grade oilfield applications and bulk road-salt tenders. Price differentiation rests on REACH registration depth and carbon-border documentation completeness. Cost compression in industrial-grade channels is intensifying because TTF hub volatility erodes Solvay process economics. German municipal procurement teams exhibit highest price sensitivity; Dutch cheese cooperatives demonstrate lowest sensitivity due to E509 compliance requirements.
Supply Chain Analysis
Reverse-logistics flows for empty bulk containers and reusable bagged-format totes create working-capital efficiency for Nordic municipal cooperatives demanding guaranteed winter stockpile rotation. Geographic supply concentrates in Belgium, Germany, and Norway, with limestone feedstock drawing from Jura Mountain quarries and brine sourcing anchored in North Sea deposits. Raw material dependencies include high-calcium limestone, natural gas for process heat, and membrane-electrolysis cell stacks. Single-source vulnerability runs through Jura Mountain food-grade stone reserves. Distribution runs through integrated storage terminals at Antwerp, Rotterdam, and Hamburg serving consolidated tendering cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon-border adjustment mechanisms are forcing import-dependent traders toward exit, making this market a consolidation play for integrated producers with captive energy assets and verified scope 3 data.
For Market Incumbents: Lock in multi-year municipal tender commitments through guaranteed stockpile availability and carbon-intensity scoring advantages against non-European imports lacking mass-balance certification. Deepen backward integration into Jura Mountain limestone quarries to secure food-grade feedstock exclusivity against emerging membrane-electrolysis competitors. Magnesium chloride substitution in German road maintenance represents the core threat to volume retention. For New Entrants and Emerging Players: EU Green Deal carbon-border adjustment mechanisms in Europe open a window for carbon-capture-integrated greenfield capacity qualifying for Innovation Fund subsidies. Target Polish and Romanian highway expansion corridors underserved by existing Nordic distribution networks. Pursue direct-to-processor channels bypassing agricultural distributors for Dutch and Irish dairy cooperatives. For Investors and Strategic Acquirers: Re-rating potential sits with membrane-electrolysis food-grade specialists given EFSA purity mandate enforcement and CSRD disclosure requirements embedding carbon intensity into procurement scoring. Long-term viability favors producers with integrated storage terminals and captive brine supply over traders lacking physical asset backing. Watch Nordic municipal purchasing cooperative consolidation velocity as inflection indicator for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Amine-based CO₂ retrofit at Solvay plants unlocks EU Innovation Fund subsidies and scope 3 reduction credits. |
| Backward Integration into Limestone | Jura Mountain quarry control secures EFSA-compliant feedstock against geographic supply concentration risk. |
| Direct-to-Processor Channel Buildout | Bypassing agricultural distributors for Dutch dairy cooperatives captures margin currently lost to intermediaries. |
| Membrane Electrolysis Capacity Expansion | New Belgian and Swiss installations achieve heavy metal thresholds without multiple recrystallization stages. |
| Mass-Balance Certification Program | Blockchain-tracked logistics documentation satisfies German and French public procurement carbon scoring requirements. |
Research Approach
Multi-period observation of Nordic municipal tender awards, TTF hub pricing volatility, and ECHA dossier renewal timelines anchored the trend analysis, supplemented by interviews with plant managers at Solvay-integrated facilities, procurement leads at German road maintenance authorities, distribution channel partners serving Polish mining operations, and technical R&D directors overseeing membrane-electrolysis purification. Secondary validation drew from customs and trade data, Cefic chemical industry reports, SEC 10-K filings of listed chemical conglomerates, and EFSA regulatory guidance documents. Bottom-up volume estimates triangulated against top-down market sizing across grade tiers and application segments.
Segment-weighting approaches distributed value and volume projections across industrial, food, and technical grade tiers; de-icing, dust control, food preservation, and drying agent applications; bulk, bagged, drum, and pallet packaging formats; and regional production hubs spanning Belgium, Germany, Norway, Poland, and the Netherlands. CAGRs were derived from regression analysis of historical offtake patterns against climatic severity indices and infrastructure investment pipelines. Forecast inputs incorporated EU Green Deal implementation velocity and REACH registration renewal compliance rates.
The model assumes a particular technology adoption path; alternative pathways for thermal evaporation versus membrane electrolysis brine concentration would alter the outlook for energy intensity and capital efficiency assumptions. Forecasts reflect embedded assumptions about carbon-border tariff enforcement and municipal procurement consolidation trajectories. Practitioners should monitor Nordic purchasing cooperative tender consolidation, TTF hub price volatility spikes, and ECHA substance evaluation protocol updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Dichromate Market
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
Europe Hydrogen Bromide Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Middle East and Africa Ferric Chloride Market
Bulk Chemicals
Ammonium Molybdate Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
Calcined Petcoke Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
Castor Oil Derivatives Market
Bulk Chemicals
Europe Carbon Black Market
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
Barium Nitrate Market