
 Castor Oil Derivatives Market | 2026-2036
Castor Oil Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Castor Oil Derivatives Market Analysis
Premium pharmaceutical-grade castor oil derivatives is rebalancing away from commodity lubricant bases as purity premiums widen. Jayant Agro-Organics Limited anchors India's seed-crushing infrastructure with backward integration into Gujarat's farming cooperatives. Arkema SA specializes in high-performance polyamides from sebacic acid, leveraging European chemical compliance to sustain margin premiums. Emery Oleochemicals GmbH operates integrated oleochemical complexes across Southeast Asia, competing on hydrogenation scale for industrial wax outputs.
Castor oil derivatives comprise chemically modified products extracted from Ricinus communis seeds, typically containing 85-95% ricinoleic acid obtained through cold-pressing or solvent extraction followed by hydrogenation, sulfonation, or alkoxylation. These compounds serve as bio-based feedstocks for lubricants, cosmetics emollients, nylon intermediates, and pharmaceutical excipients requiring specific hydroxyl functionality and thermal stability. Hydrogenated castor oil dominates value capture due to its use in coatings and personal care, where odorless, oxidatively stable grades command formulation premiums. Ricinoleic acid represents the fastest-expanding chemistry platform as polymer producers seek sebacic acid precursors for bio-based nylons. Castor wax maintains mature demand in candle and polish applications with limited growth but stable offtake from industrial buyers.
India's BIS certifies castor oil grades for export quality, while REACH in Europe mandates registration and hazard communication for derivative imports, directly shaping supplier documentation burdens and testing costs. The FDA governs pharmaceutical excipient standards for US-bound castor oil derivatives, requiring compliance with USP-NF monographs that filter out non-GMP producers. Stakeholders must monitor regulatory divergence between India's PLI scheme for oleochemicals and tightening EU Green Deal bio-based content rules, as compliance positioning in one jurisdiction increasingly constrains market access in the other.
Market Dynamics
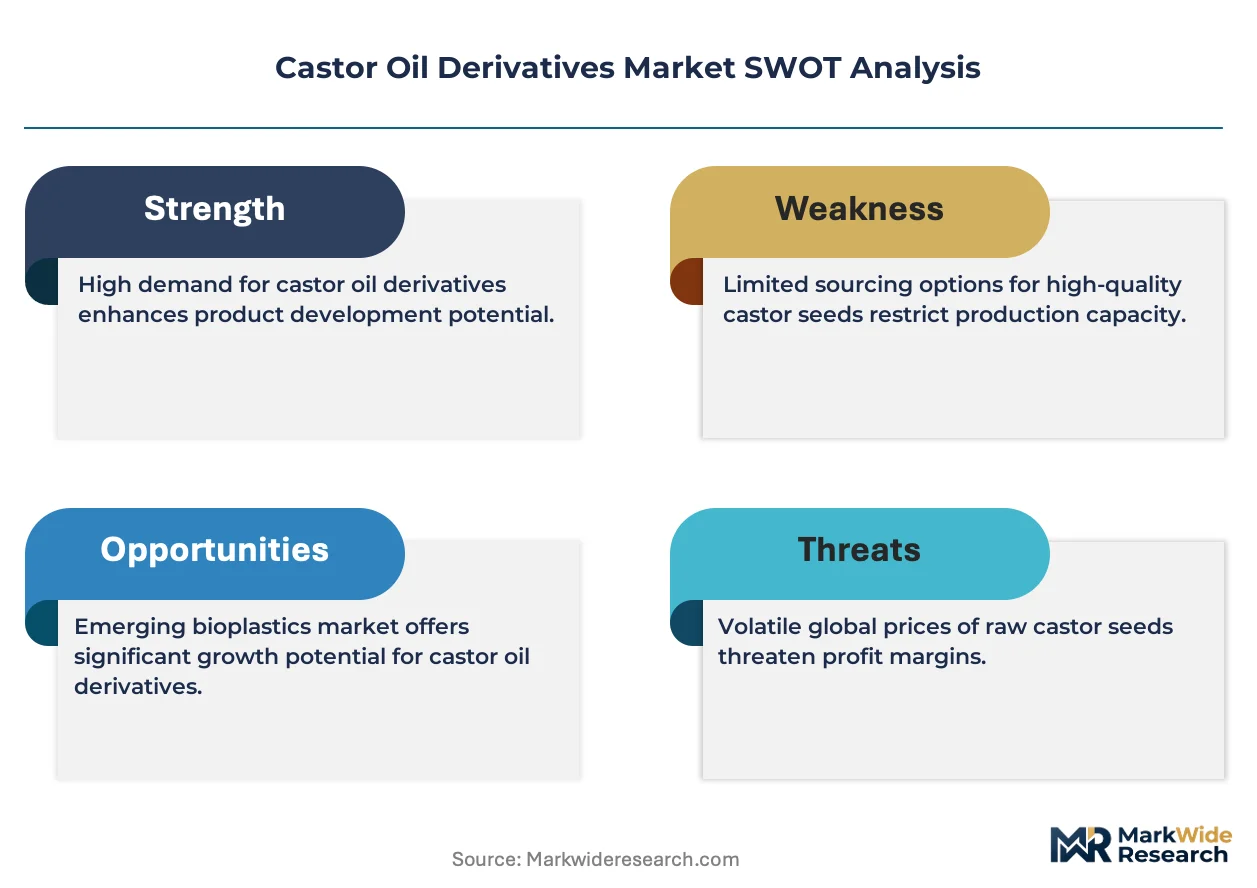
REACH compliance in Europe is tightening purity standards for pharmaceutical-grade derivatives, forcing upstream refiners to reconfigure hydrogenation and filtration infrastructure. This regulatory pressure cascades through Gujarat's seed-crushing clusters, where BIS-certified exporters must now maintain dual documentation streams for EU and domestic offtake.
Growth Catalysts
- EU Green Deal bio-based content rules:Mandates for renewable feedstocks in coatings and lubricants are pulling hydrogenated castor oil into industrial formulations previously dominated by petrochemical waxes.
- Sebacic acid demand from polymer producers:Ricinoleic acid chemistry platforms are expanding as nylon intermediates seek bio-based precursors to meet Scope 3 reduction targets.
- Gujarat farming cooperatives:Backward integration into seed supply is stabilizing input costs for crushing clusters serving Asian and European refiners.
Market Restraints
- Seed price volatility:Castor seed costs fluctuate with monsoon patterns across Gujarat's Saurashtra belt, compressing crusher margins during drought cycles.
- REACH registration burdens:ECHA documentation requirements for derivative imports impose testing costs that filter out small-scale Indian exporters lacking in-house regulatory teams.
- Petrochemical wax substitution:Paraffin and microcrystalline waxes retain cost advantages in candle and polish applications where odor stability requirements remain low.
Strategic Opportunities
- India's PLI scheme for oleochemicals:Production-linked incentives for hydrogenation capacity expansion are enabling domestic refiners to capture value previously exported to European compounders.
- Pharmaceutical excipient certification:USP-NF monograph compliance for US-bound castor oil derivatives opens formulation slots in parenteral drug delivery systems.
- Cosmetics emollient channels:Direct procurement relationships between Gujarat refiners and Indian skincare formulators are bypassing traditional European trading houses.
Industry Challenges
- GMP certification timelines:FDA facility inspections for pharmaceutical-grade output create 18-24 month approval windows that delay market entry.
- Hydrogenation catalyst sourcing:Nickel and palladium supply constraints from Russian sanctions are extending equipment commissioning schedules for new capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Castor Oil Derivatives Market |
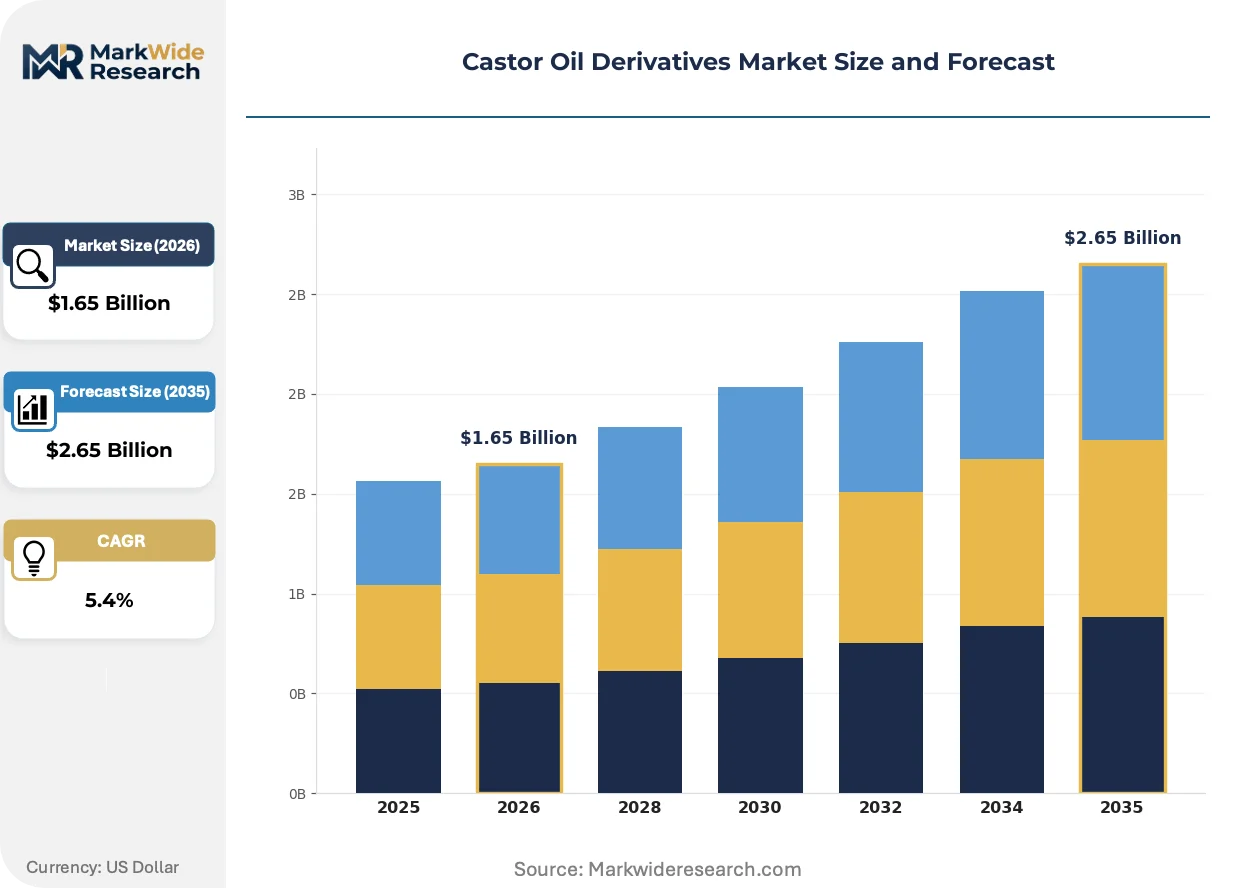
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Triacontanol, Ricinoleic Acid, Castor Wax, Hydrogenated Castor Oil Application: Personal Care, Biofuels, Coatings, Pharmaceuticals End User: Cosmetics Manufacturers, Automotive Industry, Textile Producers, Food Industry Form: Liquid, Solid, Powder, Emulsion |
| Companies Covered | Adani Wilmar Ltd., ITOH Oil Chemicals Co., Ltd., Jayant Agro-Organics Limited, N.K. Proteins Pvt. Limited, Emery Oleochemicals GmbH, Arkema SA, Thai Castor Oil Industries Co., Ltd., Gokul Agri International Ltd., Croda International PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Castor Oil Derivatives Market Emerging Trajectories
Process intensification and regulatory convergence are compressing the traditional separation between seed-crushing, refining, and derivative synthesis. Technology investments now target continuous hydrogenation and membrane filtration to meet pharmaceutical-grade specifications without batch rework.
Continuous hydrogenation reactor systems are automating the transition from batch to steady-state castor wax production. Specialty chemical manufacturers in India are adopting these units to reduce solvent carryover and color inconsistency. The technology is automating quality assurance steps that previously required manual sampling and offline testing, shrinking certification cycles for REACH-bound shipments.
EU CSRD disclosure requirements are mandating supply chain carbon accounting for imported oleochemicals. Downstream formulators in coatings and personal care must now document Scope 3 emissions from Gujarat seed farms through European distribution. This policy is compressing supplier qualification timelines and favoring refiners with farm-level traceability systems already operational.
Long-term offtake contracts are displacing spot market purchases among major lubricant compounders. Buyers are locking in multi-year hydrogenated castor oil supply to hedge seed price volatility and secure bio-based content certificates. This pattern is most visible in German automotive lubricant supply chains, where OEM sustainability scorecards now weight feedstock renewability in supplier selection.
Castor Oil Derivatives Market Segmentation
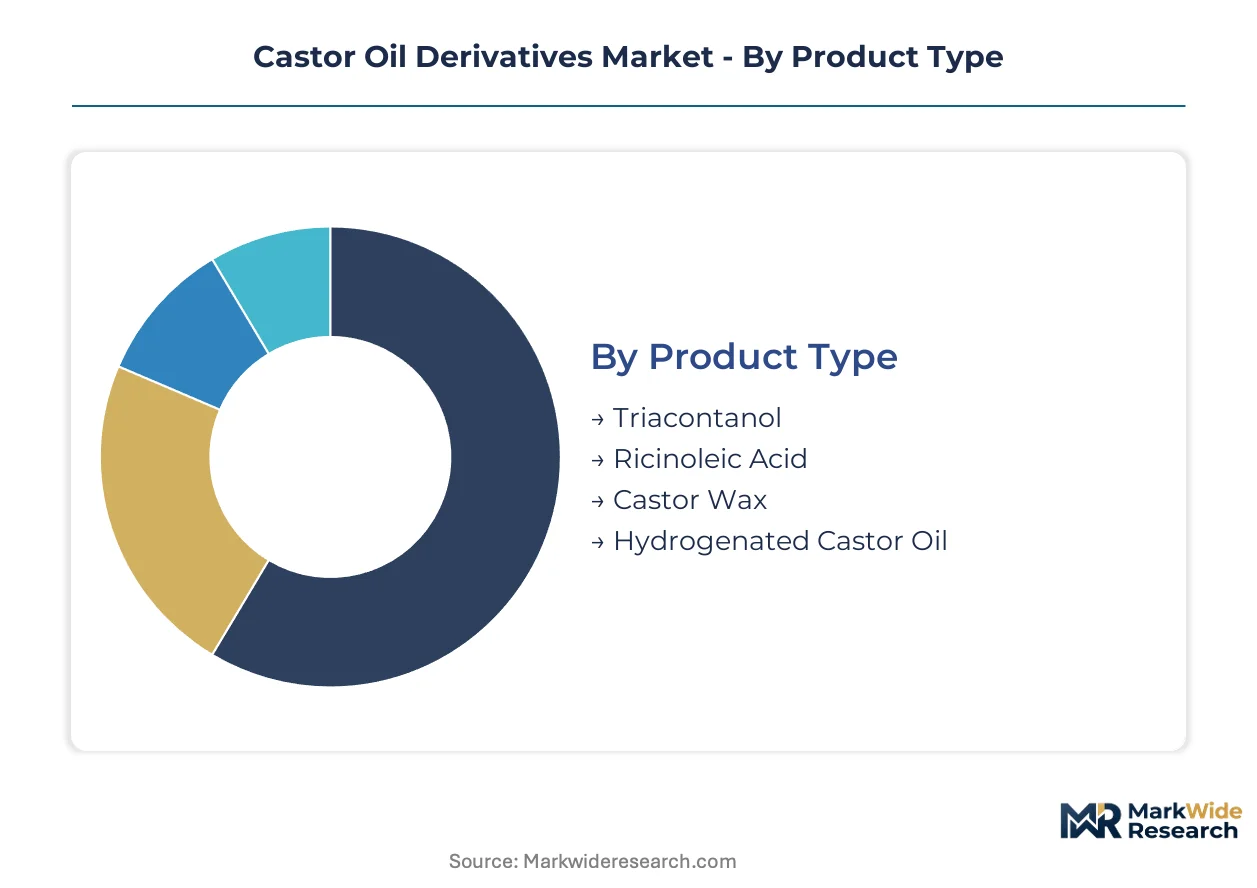
Castor oil derivatives fragment across four distinct axes, each reflecting how chemical functionality maps to divergent value capture. Product chemistry determines margin structure, while application verticals impose contrasting purity regimes and certification burdens.
Product Type:
Supply concentration in Gujarat's hydrogenation clusters shapes competitive positioning across derivative grades, with capacity scale determining which chemistries achieve cost parity against petrochemical alternatives.
- Hydrogenated Castor Oil:Fully saturated triglyceride produced via catalytic hydrogenation of refined castor oil, yielding odorless, oxidatively stable wax with melting points between 82-88°C. Coatings formulators in Germany and personal care compounders in Maharashtra are locking in multi-year offtake to secure bio-based content certificates under EU Green Deal rules. REACH registration costs filter out smaller refiners, cementing advantage for integrated hydrogenation operators with in-house ECHA documentation teams.
- Ricinoleic Acid:Monounsaturated hydroxy fatty acid comprising 85-95% of native castor oil, isolated through saponification and acidification. Polymer producers seeking sebacic acid precursors for bio-based nylons are pulling this platform into the fastest-expanding demand trajectory. Arkema SA's polyamide operations in France anchor European offtake, while Indian specialty chemical entrants target domestic nylon-6,12 capacity expansion.
- Castor Wax:Natural ester wax derived from castor oil through fractional crystallization, retaining characteristic high hydroxyl content. Candle manufacturers and polish compounders in mature industrial markets maintain stable procurement despite limited growth headroom.
- Triacontanol:Long-chain fatty alcohol isolated from castor wax fractions, functioning as plant growth regulator and cosmetic emollient. Agricultural biotechnology applications in controlled-environment farming drive niche demand from specialty distributors.
Today's leader: Hydrogenated Castor Oil. Tomorrow's challenger: Ricinoleic Acid.
Application:
Cost tier differentiation separates premium pharmaceutical grades from commodity industrial formulations, with certification overhead creating steep pricing stratification.
- Pharmaceuticals:USP-NF monograph compliance for parenteral excipients demands GMP-certified hydrogenation and membrane filtration infrastructure. FDA facility inspections impose 18-24 month approval windows that delay market entry for Indian refiners lacking prior pharmaceutical track records.
- Personal Care:Emollient and surfactant applications in premium skincare drive procurement of low-color, low-odor hydrogenated grades. Indian cosmetics manufacturers are expanding direct sourcing from Gujarat refiners, bypassing European trading houses and compressing margin capture for intermediaries.
- Coatings:Bio-based wax additives for powder coatings and industrial finishes compete against petrochemical paraffins on renewable content metrics. German automotive OEM sustainability scorecards now weight feedstock renewability in supplier qualification.
- Biofuels:Castor oil methyl ester serves as lubricity improver in diesel formulations, though feedstock competition from food and industrial uses constrains dedicated biofuel refining economics.
Premium pharmaceutical grades command the steepest margins. Coatings applications are climbing fastest on regulatory pull.
End User:
Customer type determines procurement sophistication, with multinational formulators imposing traceability requirements that outpace domestic buyer capabilities.
- Cosmetics Manufacturers:Premium skincare and color cosmetic formulators in India and Europe specify hydrogenated castor oil for emollient and thickening functions. Direct refiner relationships are displacing distributor channels as procurement teams seek farm-level carbon accounting under EU CSRD disclosure mandates.
- Automotive Industry:Lubricant compounders and coating suppliers prioritize bio-based content certificates for OEM sustainability reporting. German automotive supply chains exhibit the most advanced supplier qualification timelines, with renewable feedstock documentation now standard.
- Textile Producers:Dyeing auxiliaries and finishing agents utilize sulfonated castor oil derivatives for wetting and lubrication. Mature demand from South Asian garment manufacturing clusters shows limited technology shift.
- Food Industry:Food-grade castor oil applications as mold release and additive carrier require FSSAI compliance in India and parallel national standards elsewhere. Regulatory fragmentation constrains cross-border trade in food-contact grades.
Cosmetics manufacturers dominate value capture. Automotive qualification standards are tightening fastest.
Form:
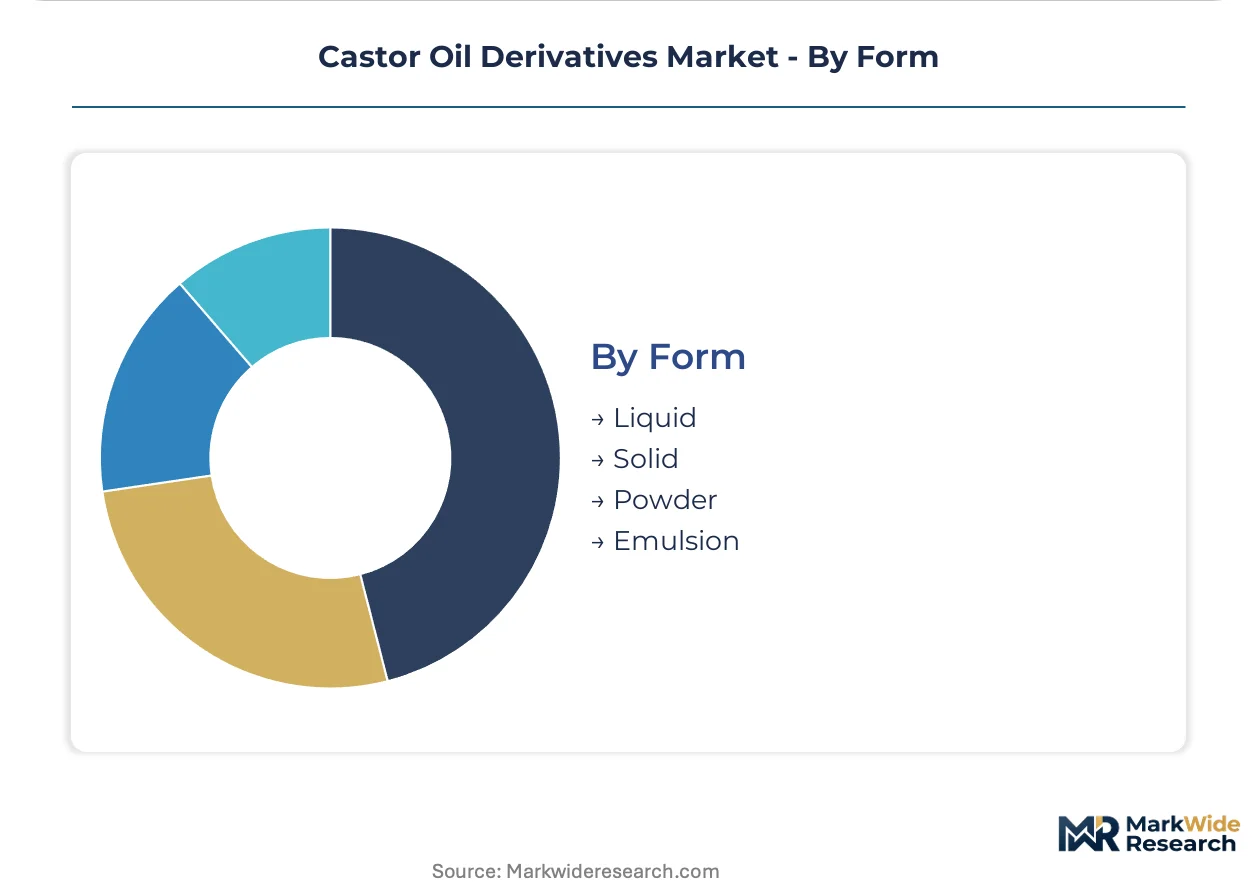
Physical state governs logistics economics and formulation compatibility, with liquid and solid forms commanding divergent distribution infrastructure.
- Liquid:Native castor oil and partially hydrogenated grades flow through bulk tanker and drum distribution networks. Standard packaging for industrial lubricant and textile chemical applications.
- Solid:Fully hydrogenated castor oil and castor wax ship as flakes, pastilles, or blocks requiring heated storage and melting equipment. Coatings compounders and candle manufacturers absorb this handling overhead for performance benefits.
- Powder:Micronized hydrogenated castor oil enables dry blending in powder coatings and cosmetic pressed powders. Grinding and classification add processing cost that limits adoption to premium formulations.
- Emulsion:Aqueous dispersions of castor oil derivatives serve water-based coatings and personal care applications. Stability requirements constrain shelf life and complicate supply chain planning.
Liquid forms anchor volume throughput. Powder grades are gaining share fastest in premium coatings and cosmetics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's chemical engineering workforce anchors the global castor oil derivatives supply base, with specialized talent pools in hydrogenation catalysis and pharmaceutical-grade filtration commanding premium wages across the Saurashtra belt.
India
Cosmetics manufacturers in Maharashtra expand direct procurement of hydrogenated castor oil for premium skincare formulations. BIS certification mandates filter export quality grades through documented testing protocols. Seed crushing clusters in Gujarat's Kutch and Saurashtra districts supply downstream refiners across Asia and Europe with backward integration into farming cooperatives.
Germany
Automotive lubricant compounders prioritize bio-based content certificates for OEM sustainability scorecards. REACH compliance through ECHA tightens purity standards for pharmaceutical-grade derivative imports. Industrial hydrogenation facilities in the Ruhr region process Indian feedstock into coatings additives for powder coating formulators.
France
Polymer producers seek sebacic acid precursors from ricinoleic acid platforms to meet Scope 3 reduction targets. EU Green Deal bio-based content rules mandate renewable feedstock documentation across supply chains. Arkema SA's polyamide operations near Lyon anchor European offtake for bio-based nylon intermediates.
China
Coatings formulators absorb hydrogenated castor oil into industrial finishes competing with petrochemical waxes on renewable metrics. NMPA pharmaceutical excipient standards parallel USP-NF monographs for import qualification. Yangtze River Delta chemical parks host toll hydrogenation capacity serving domestic personal care compounders.
United States
FDA pharmaceutical excipient standards govern castor oil derivatives for parenteral drug delivery systems. USP-NF monograph compliance filters out non-GMP producers from formulation slots. New Jersey and Pennsylvania host specialty chemical distributors qualifying Indian refiners through 18-24 month facility inspection windows.
Castor Oil Derivatives Market Vendor Landscape
Capital-heavy seed crushers compete with asset-light specialty chemical refiners across divergent margin structures. Integrated operators with captive hydrogenation capacity capture value previously exported to European compounders, while toll processors serve fragmented domestic demand. Three archetypes dominate: Gujarat-based agricultural processors with farming cooperative ties, European chemical majors with REACH registration infrastructure, and Southeast Asian oleochemical specialists with multi-site hydrogenation networks. Capacity expansion and backward integration into seed supply constitute the dominant competitive moves.
Among India-based agricultural processors, Jayant Agro-Organics Limited exemplifies the integrated crusher-refiner archetype with cooperative-linked seed procurement. Arkema SA occupies a position representing European chemical majors leveraging compliance infrastructure for margin premiums. Emery Oleochemicals GmbH anchors the Southeast Asian multi-site hydrogenation specialist tier with integrated oleochemical complex operations.
| Leading Market Players |
|---|
| Adani Wilmar Ltd. |
| ITOH Oil Chemicals Co., Ltd. |
| Jayant Agro-Organics Limited |
| N.K. Proteins Pvt. Limited |
| Emery Oleochemicals GmbH |
| Arkema SA |
| Thai Castor Oil Industries Co., Ltd. |
| Gokul Agri International Ltd. |
| Croda International PLC |
| Others |
Supply Flow & Price Mechanics
Backward integration into Gujarat farming cooperatives anchors supply positioning and pricing power for seed-crushing clusters serving Asian and European refiners. This captive seed sourcing buffers input cost volatility while enabling margin capture across hydrogenation and derivative synthesis stages that commodity traders cannot replicate.
Pricing Analysis
Contract-based long-term offtake dominates premium grades, while spot transactions persist for commodity industrial waxes. Price differentiation stems from REACH registration status and USP-NF certification tier, with pharmaceutical-grade hydrogenated castor oil commanding substantial premiums over technical grades. Cost compression in standard industrial waxes is intensifying because petrochemical paraffin substitutes retain cost advantages in odor-tolerant applications. Candle manufacturers exhibit highest price sensitivity, whereas cosmetics formulators prioritize certification compliance over unit economics.
Supply Chain Analysis
Castor seed supply rests on Gujarat's Saurashtra belt, with secondary concentration in Brazil and China. Hydrogenation catalysts draw from Russian-sanctioned nickel and palladium sources, while pharmaceutical-grade filtration membranes hinge on German and Japanese specialty suppliers. Single-source vulnerability in catalyst procurement extends equipment commissioning schedules for new capacity. Distribution runs through bulk liquid tankers for native oil and heated container systems for solid wax grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The castor oil derivatives market functions as a stable compounder, with bio-based feedstock mandates under EU Green Deal rules driving steady formulation substitution across coatings and lubricants.
For Market Incumbents: Hedge seed price volatility through multi-year farming cooperative contracts and expand hydrogenation capacity under India's PLI scheme. Arkema SA's polyamide operations demonstrate how REACH registration infrastructure defends margin premiums against commodity entrants. Nickel catalyst supply constraints represent the critical vulnerability requiring alternative sourcing relationships. For New Entrants and Emerging Players: Capture direct procurement relationships with Indian cosmetics manufacturers bypassing European trading houses. The personal care emollient segment offers lowest barriers to entry for BIS-certified Gujarat refiners with existing hydrogenation assets. Lead with farm-level carbon accounting documentation to qualify under EU CSRD disclosure mandates. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale hydrogenation specialists because regulatory compliance burdens filter out sub-scale competitors incapable of bearing ECHA documentation costs. Five-to-ten year viability hinges on positioning ahead of pharmaceutical excipient certification waves. Watch FDA facility inspection backlogs as the signal indicating capacity-constrained pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Supply | Gujarat farming cooperatives stabilize input costs for crushing clusters against monsoon volatility. |
| Pharmaceutical-Grade Certification Investment | USP-NF compliance opens parenteral drug formulation slots previously blocked to non-GMP producers. |
| Continuous Hydrogenation Technology Adoption | Membrane filtration automation shrinks REACH certification cycles for European-bound shipments. |
| Long-Term Supply Agreement Structuring | German automotive lubricant compounders lock in bio-based content certificates for OEM scorecards. |
| Joint Venture with Catalyst Suppliers | Palladium sourcing partnerships mitigate Russian sanctions exposure for new capacity commissioning. |
Methodological Framework
Direct dialogue with hydrogenation plant managers, cosmetics procurement leads, pharmaceutical excipient specialists, and ECHA regulatory consultants grounded qualitative findings in operational reality. Secondary validation drew from BIS certification registries, Indian customs export data, ECHA substance registration databases, and SEC filings from listed oleochemical producers. Bottom-up capacity modeling and top-down demand segmentation were triangulated against trade flow analysis.
Segment-level outputs across product chemistry, application vertical, end-user category, and physical form were stress-tested against historical price realization data. CAGRs were derived from regression analysis of seed crush volumes, hydrogenation capacity utilization, and derivative export trajectories. Key forecast inputs included EU Green Deal implementation timelines and FDA pharmaceutical facility inspection queue projections.
Monsoon failure patterns, REACH substance evaluation acceleration, and hydrogenation catalyst supply disruptions are the dominant revision risks. Forecasts reflect assumptions around regulatory continuity and seed yield stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Butachlor Market
Bulk Chemicals
Elemental Sulfur Market
Bulk Chemicals
Ethyleneamines Market
Bulk Chemicals
Furfuryl Alcohol Market
Bulk Chemicals
Global Sodium Chlorate Market
Bulk Chemicals
Triammonium Citrate Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
Sodium Selenite Market
Bulk Chemicals
Ethylene Oxide Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Ammonium Sulfate Food Grade Market
Bulk Chemicals
North America Starch Derivatives Market
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
Ammonium Bromide Market