
 Global Inorganic Fluorides Market | 2026-2036
Global Inorganic Fluorides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inorganic Fluorides Market Foresight
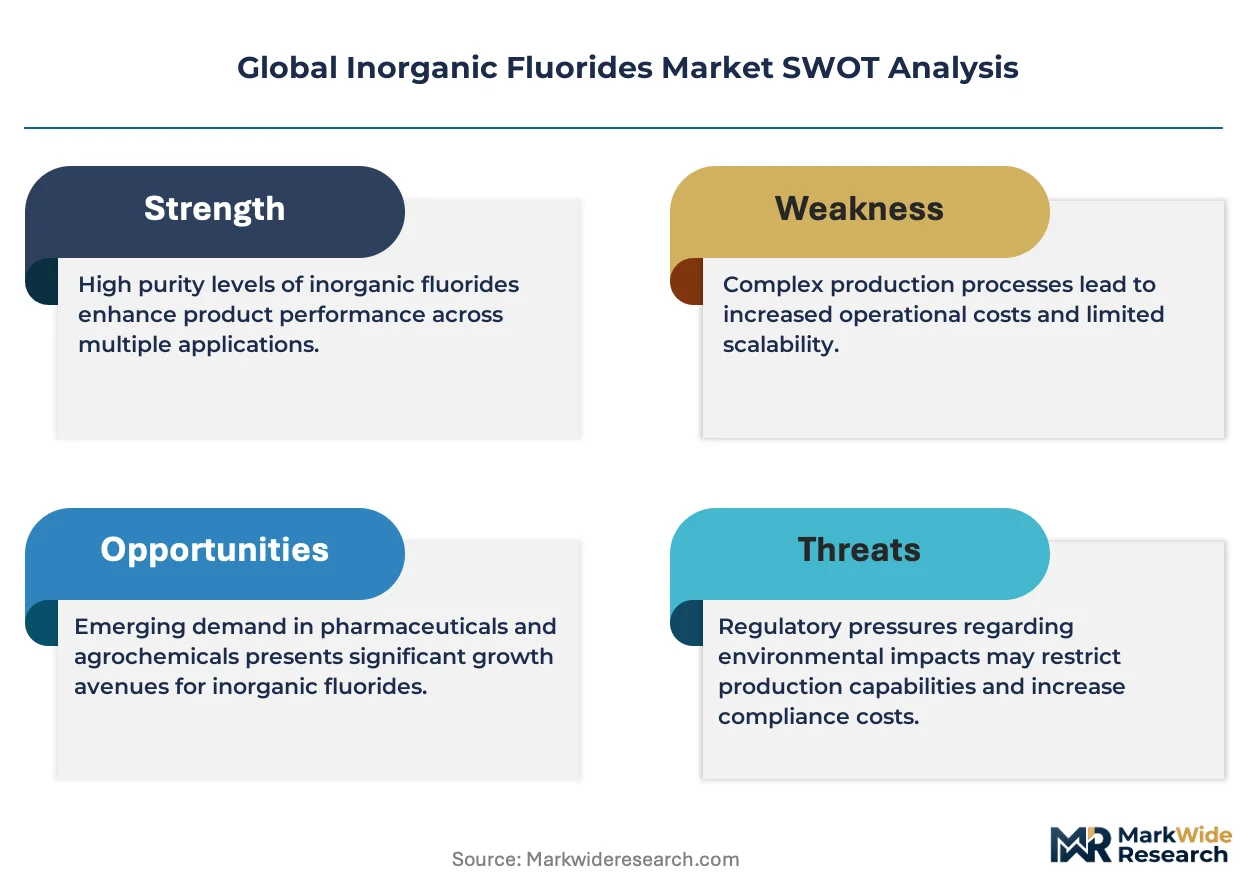
Aluminum production is restructuring demand patterns across the Global Inorganic Fluorides Market as smelters seek higher-purity cryolite and aluminum fluoride inputs. Solvay leverages its integrated fluorine chemistry platform to serve European metallurgical customers with consistent technical-grade supply. Navin Fluorine International Limited anchors South Asian demand through specialized fluorochemical manufacturing at scale.
Inorganic fluorides encompass ionic compounds formed between fluorine and metallic elements, typically produced via neutralization of hydrofluoric acid with metal oxides, carbonates, or hydroxides, yielding products with purity thresholds spanning industrial-grade to semiconductor-grade specifications. These compounds function as essential fluxing agents, etchants, and fluorinating precursors across metallurgical, electronic, and chemical processing industries. Calcium fluoride and aluminum fluoride products dominate volume flows, while pharmaceutical-grade sodium fluoride commands concentrated margin pools due to stringent purity certifications and limited qualified supply. Technical-grade potassium fluoride segments exhibit the fastest trajectory, propelled by lithium-ion battery electrolyte salt demand and expanding semiconductor fabrication capacity.
The EPA regulates fluoride discharge limits under Clean Water Act provisions, while China's MEE enforces tightening emissions standards for hydrofluoric acid production facilities. REACH and RoHS frameworks in Europe restrict certain fluoride compound classifications in consumer-facing applications, redirecting industrial volumes toward technical end-uses. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate product registration costs and qualify alternative fluorine feedstocks.
Market Dynamics
Aluminum smelters are consolidating cryolite and aluminum fluoride procurement around higher-purity specifications, forcing chemical producers to restructure purification assets and technical service capabilities. This demand-side concentration is compressing margins for commodity-grade suppliers while rewarding integrated fluorine chemistry platforms with captive acid production and metallurgical application expertise.
Growth Catalysts
- Lithium-ion battery electrolyte salts:Potassium fluoride and lithium hexafluorophosphate precursors are drawing capacity expansions as cell manufacturers secure localized fluorochemical supply.
- China's dual carbon goals:Emissions benchmarks for hydrofluoric acid production are accelerating closures of inefficient capacity, tightening supply for compliant producers.
- Semiconductor etching demand:High-purity hydrogen fluoride and buffered oxide etchants are required for advanced node fabrication, with South Korean and Taiwanese foundries driving specification escalation.
Market Restraints
- Fluorspar supply concentration:Acid-grade fluorspar mining concentrates in Mexico, China, and South Africa, exposing processors to export quota volatility and freight cost spikes.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon restrictions are compressing demand for certain fluorinated intermediates, redirecting capital toward non-ozone-depleting alternatives.
- Substitution by fluoride-free fluxes:Aluminum smelters in Norway and Canada are piloting inert anode technologies that eliminate cryolite consumption entirely.
Strategic Opportunities
- Pharmaceutical-grade sodium fluoride:Dental and osteoporosis applications command certified purity premiums with limited qualified supply, creating margin pools for GMP-compliant producers.
- India's PLI scheme for advanced chemistry cell manufacturing:Battery electrolyte salt localization mandates are attracting fluorochemical investment into Gujarat and Tamil Nadu industrial corridors.
- Closed-loop acid regeneration:Semiconductor fabs in Japan are contracting for spent acid recovery services, converting waste streams into technical-grade feedstock.
Industry Challenges
- Semiconductor-grade certification timelines:Qualification for sub-ppb metal impurity specifications requires 18-24 month validation cycles with individual foundry customers.
- Hydrofluoric acid logistics complexity:Corrosive material handling regulations restrict intermodal transport options, forcing regional production footprints and duplicative asset deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inorganic Fluorides Market |
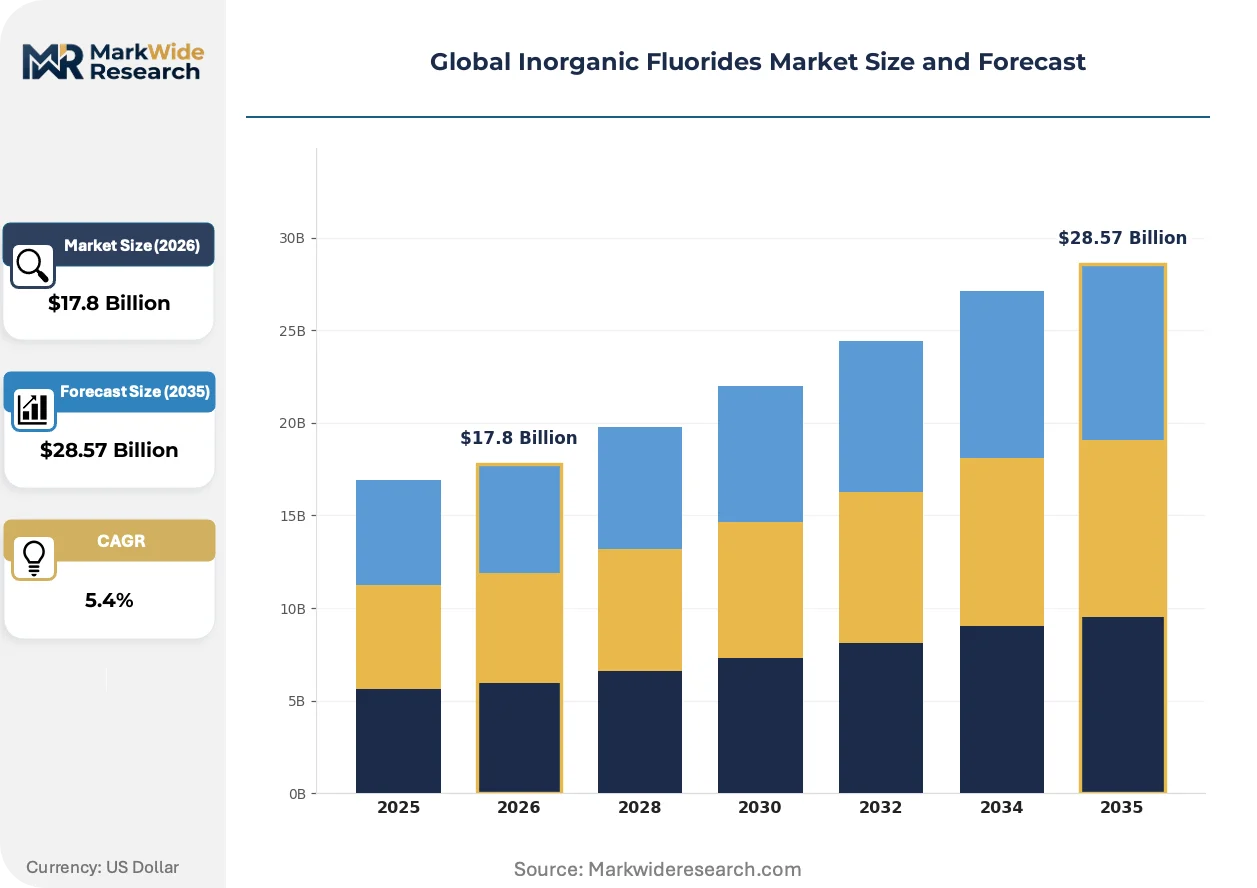
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $28.57 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Fluoride, Sodium Fluoride, Potassium Fluoride, Ammonium Fluoride, Magnesium Fluoride Grade: Industrial Grade, Pharmaceutical Grade, Technical Grade, Food Grade, Laboratory Grade Application: Glass Etching, Aluminum Production, Water Treatment, Metallurgical Industry, Chemical Manufacturing End User: Metal Fabricators, Water Treatment Plants, Chemical Producers, Pharmaceutical Manufacturers, Research Laboratories |
| Companies Covered | Solvay, Navin Fluorine International Limited, Shanghai Mintchem Development Co., Aditya Birla Group, Do-Fluoride Chemicals Co. Ltd, Honeywell International Inc., DuPont de Nemours, Inc., Arkema S.A., Shandong Dongyue Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inorganic Fluorides Market Shifts & Advancements
Fluorochemical production is bifurcating between commodity-scale acid derivatives and precision-purity electronic materials, with process technology and analytical capabilities becoming the primary competitive differentiators rather than raw material access alone.
Dry fluoride gas generation is overtaking aqueous acid routes for semiconductor pre-clean and chamber cleaning applications. Taiwan Semiconductor Manufacturing and Samsung Foundry are specifying anhydrous hydrogen fluoride delivery systems to reduce water contamination risks at 3nm nodes. This transition is compressing demand for traditional aqueous acid containers and forcing chemical suppliers to install gas-phase purification and bulk distribution infrastructure.
The EU F-Gas Regulation's hydrofluorocarbon phase-down is redirecting fluorochemical investment toward unsaturated HFO alternatives and inorganic fluoride recovery systems. European refrigerant and aerosol propellant manufacturers are reformulating product portfolios, with consequential demand shifts for tetrafluoromethane and hexafluoroethane etchants in chip fabrication. German and French chemical producers are consolidating acid regeneration assets to serve both legacy fluorocarbon and emerging HFO supply chains.
Smelters are consolidating annual cryolite and aluminum fluoride contracts into multi-year technical partnerships with embedded application engineering support. Russian and Middle Eastern aluminum producers are requiring suppliers to station metallurgical specialists at smelter sites for bath chemistry optimization. This service bundling is displacing spot-market purchasing in the Persian Gulf and Central Asian supply corridors.
Global Inorganic Fluorides Market Segmentation
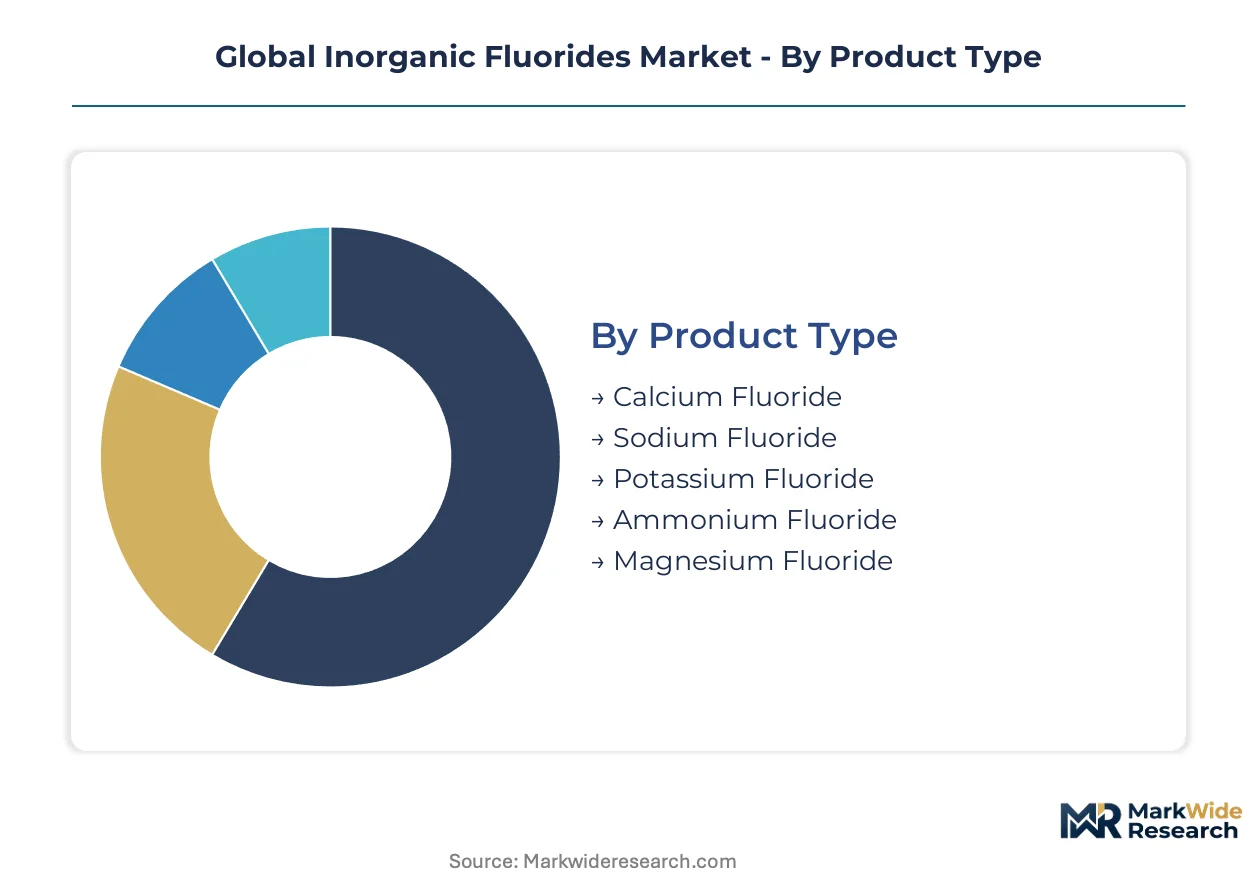
Inorganic fluorides exhibit divergent margin profiles and supply chain requirements across product categories. Grade purity thresholds and application-specific certifications fragment procurement patterns, forcing producers to align asset configurations with concentrated demand pockets.
Product Type:
Supply concentration varies sharply across fluoride chemistries, with acid-grade feedstock access determining competitive positioning in volume segments.
- Calcium Fluoride:Natural mineral form (CaF₂) serving as the primary fluorspar-derived feedstock for hydrofluoric acid production. Demand concentrates in China's Shandong and Henan provinces, where integrated processors convert acid-grade ore into metallurgical and chemical intermediates. Mexico's San Luis Potosí deposits anchor Western Hemisphere supply.
- Potassium Fluoride:White crystalline salt produced via neutralization of hydrofluoric acid with potassium carbonate. Battery electrolyte salt demand in South Korea and Japan is drawing capacity expansions from specialized fluorochemical manufacturers seeking to localize supply for lithium-ion cell producers.
- Sodium Fluoride:Synthetic compound used in water fluoridation and dental applications. Municipal treatment facilities in the US and EU drive specification standardization.
- Ammonium Fluoride:Acidic salt employed in glass etching and metal surface treatment. Taiwanese semiconductor foundries specify ultra-low metal content grades for wafer processing.
- Magnesium Fluoride:Optical-grade material for lenses and windows in ultraviolet applications. German and Japanese optics manufacturers dominate qualified demand.
Today's leader: Calcium Fluoride. Tomorrow's challenger: Potassium Fluoride.
Grade:
Cost tier stratification separates commodity-scale acid derivatives from certified-purity materials commanding qualification premiums.
- Industrial Grade:Standard purity specifications (typically 95-98%) for metallurgical fluxes and bulk chemical synthesis. Aluminum smelters in Russia and the UAE drive volume procurement through annual contract structures.
- Technical Grade:Enhanced purity (99%+) for semiconductor etchants and battery electrolyte precursors. South Korean foundries impose sub-ppm metal impurity limits, forcing producers to install dedicated purification trains.
- Pharmaceutical Grade:GMP-certified sodium fluoride for dental and osteoporosis therapeutics. FDA and EMA validation requirements limit qualified supply to a handful of specialized manufacturers.
- Food Grade:Regulated purity for water fluoridation and food preservation additives. NSF/ANSI Standard 60 certification dominates North American municipal procurement.
- Laboratory Grade:High-purity reagents for analytical and research applications. Academic and industrial R&D facilities in Switzerland and the Netherlands specify trace metal documentation.
Industrial Grade commands current volume dominance. Technical Grade is climbing the fastest on battery and semiconductor demand.
Application:
Customer type fragmentation splits the market between process-integrated consumers and specification-driven buyers.
- Aluminum Production:Cryolite and aluminum fluoride consumption in Hall-Héroult cell electrolysis. Smelters in Bahrain and Iceland are consolidating procurement around multi-year technical partnerships with embedded metallurgical support.
- Glass Etching:Hydrofluoric acid and ammonium fluoride for decorative and technical surface treatment. Artisan glass manufacturers in Italy and the Czech Republic sustain specialized demand for buffered etching solutions.
- Water Treatment:Sodium fluoride and fluorosilicic acid for municipal fluoridation. EPA discharge limits under the Clean Water Act constrain processor site selection in the US.
- Metallurgical Industry:Fluxing agents for steel and non-ferrous metal refining. Indian secondary aluminum producers are expanding consumption as capacity scales in Gujarat.
- Chemical Manufacturing:Fluorinating precursors for refrigerants, pharmaceuticals, and agrochemicals. EU F-Gas Regulation phase-downs are redirecting investment toward unsaturated HFO alternatives.
Aluminum Production anchors present demand. Glass Etching represents the steadiest niche trajectory.
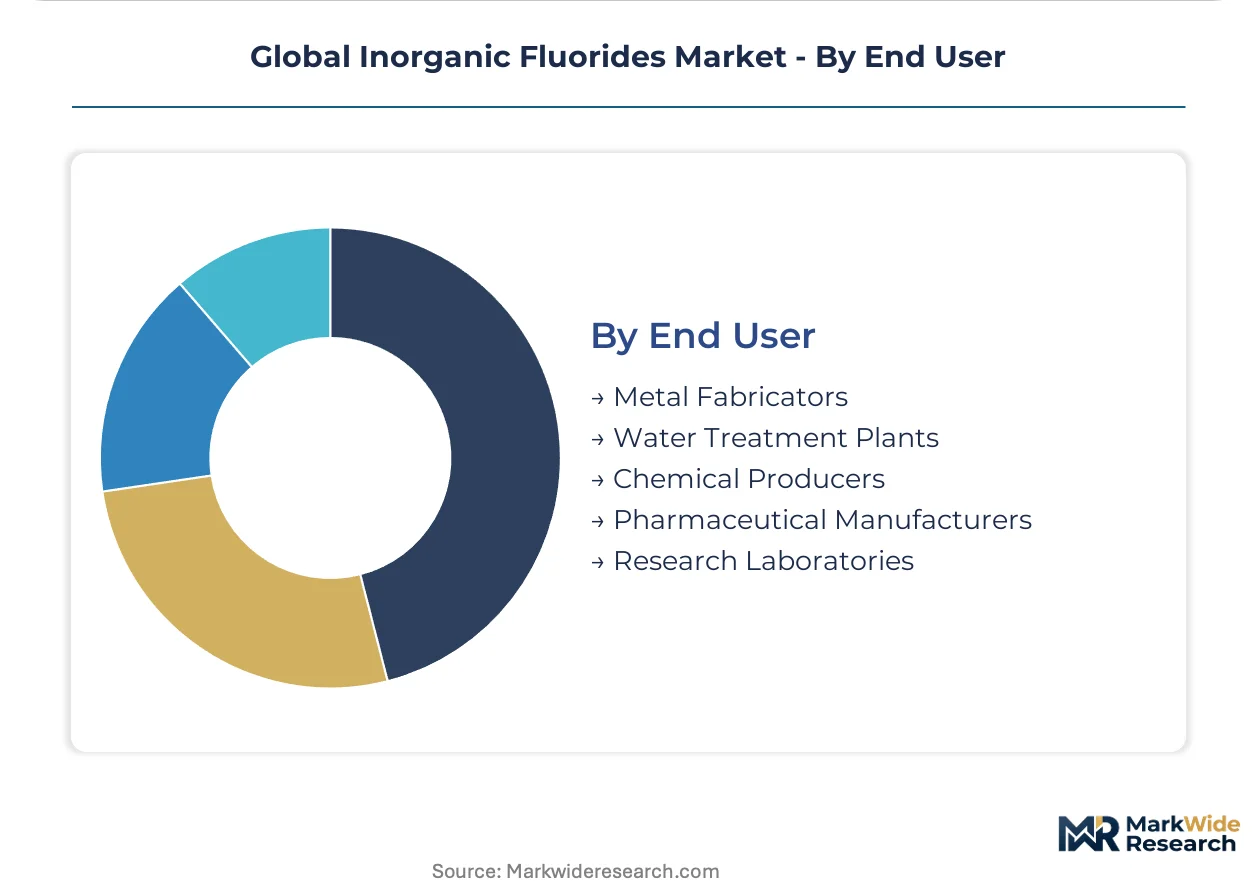
End User:
Maturity gradients separate established industrial consumers from emerging technology-driven segments with accelerating specification requirements.
- Chemical Producers:Integrated fluorochemical manufacturers consuming inorganic fluorides as intermediates. German and French producers are consolidating acid regeneration assets to serve both legacy and emerging supply chains.
- Metal Fabricators:Aluminum smelters and steel refineries requiring consistent fluxing agent supply. Norwegian pilot programs for inert anode technology threaten long-term cryolite displacement.
- Pharmaceutical Manufacturers:GMP-compliant drug producers sourcing certified sodium fluoride. Limited qualified supply creates margin pools for producers with regulatory validation capabilities.
- Water Treatment Plants:Municipal utilities managing fluoridation dosing systems. China's MEE tightening of emissions standards is accelerating closure of inefficient fluoride production capacity.
- Research Laboratories:Academic and industrial R&D facilities requiring documented trace analysis. Japanese semiconductor materials research drives specification escalation for next-generation etchants.
Chemical Producers dominate current procurement volumes. Pharmaceutical Manufacturers offer the steepest expansion trajectory on certified purity premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers relocate to jurisdictions with lower compliance costs for hydrofluoric acid emissions. China's MEE standards and the EU F-Gas Regulation have widened cost-of-compliance gaps between regions, redirecting investment toward India and the Middle East.
China
Shandong province hosts the world's densest fluorochemical manufacturing cluster, supplying battery electrolyte and semiconductor etching markets. The MEE's tightening emissions standards for hydrofluoric acid production are accelerating closures of inefficient capacity in Henan and Guizhou provinces. Zhejiang's fluorochemical processors are upgrading purification assets to meet South Korean foundry specifications for sub-ppm metal impurities.
United States
Aluminum smelters in Kentucky and South Carolina drive concentrated demand for cryolite and aluminum fluoride through multi-year technical partnerships. The EPA's Clean Water Act discharge limits constrain greenfield acid production site selection in the Ohio River Valley. Texas Gulf Coast chemical complexes are expanding fluorochemical intermediates capacity to serve refrigerant and aerosol propellant reformulation under SNAP program requirements.
Germany
Integrated fluorochemical producers in North Rhine-Westphalia are consolidating acid regeneration assets to serve both legacy fluorocarbon and emerging HFO supply chains. The EU F-Gas Regulation's hydrofluorocarbon phase-down is redirecting capital toward unsaturated alternatives and inorganic fluoride recovery systems. Bavarian specialty chemical manufacturers dominate pharmaceutical-grade sodium fluoride supply to EMA-validated drug producers.
India
Gujarat's industrial corridor is attracting fluorochemical investment under the PLI scheme for advanced chemistry cell manufacturing and localized battery electrolyte salt production. Navin Fluorine International Limited anchors South Asian demand through specialized manufacturing at scale. Tamil Nadu's emerging electronics manufacturing zones are creating specification-driven demand for technical-grade potassium fluoride from semiconductor fabrication facilities.
South Korea
Samsung Foundry and SK Hynix are driving specification escalation for high-purity hydrogen fluoride and buffered oxide etchants at advanced nodes. The MFDS regulates pharmaceutical-grade fluoride imports while METI-aligned technical standards govern semiconductor materials qualification. Yeongnam region chemical complexes are installing gas-phase purification infrastructure to supply anhydrous hydrogen fluoride delivery systems for 3nm fabrication.
Global Inorganic Fluorides Market Competitive Landscape
Capacity expansion dominates the current landscape as producers install dedicated purification trains to capture battery and semiconductor specification premiums. The vendor base separates into three tiers: integrated multinational platforms with captive acid production, regional specialists with metallurgical application expertise, and commodity-scale processors dependent on spot fluorspar markets. Strategic archetypes include backward-integrated miners with downstream chemical assets, application-focused technical service providers, and pure-play electronic materials specialists. M&A activity concentrates on acid regeneration capabilities and semiconductor-grade certification assets, while geographic expansion targets India's PLI corridors and Middle Eastern aluminum smelter partnerships.
Within the integrated multinational tier, Solvay and Honeywell International Inc. occupy positions defined by fluorine chemistry platform breadth and regulatory compliance infrastructure. Navin Fluorine International Limited exemplifies the regional specialist archetype with concentrated South Asian manufacturing scale. Do-Fluoride Chemicals Co. Ltd represents Chinese vertical integration from acid-grade fluorspar through battery electrolyte precursors. These three anchors illustrate how competitive positioning increasingly depends on purification technology and foundry qualification timelines rather than raw material access alone.
| Leading Market Players |
|---|
| Solvay |
| Navin Fluorine International Limited |
| Shanghai Mintchem Development Co. |
| Aditya Birla Group |
| Do-Fluoride Chemicals Co. Ltd |
| Honeywell International Inc. |
| DuPont de Nemours, Inc. |
| Arkema S.A. |
| Shandong Dongyue Chemical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Acid-grade fluorspar spot prices in China and Mexico cascade through hydrofluoric acid production into three distinct pricing tiers—pharmaceutical-grade sodium fluoride commands certification premiums, technical-grade potassium fluoride captures battery electrolyte salt value, while industrial-grade aluminum fluoride trades on volume contract structures. This raw-material cost transmission concentrates margin power with backward-integrated processors owning captive mining assets.
Pricing Analysis
Distributor margins compress technical-grade fluoride salts by 8-12% before reaching South Korean battery cell manufacturers, while direct-to-smelter contracts for cryolite bypass channel markups entirely. Three-tier pricing structure across semiconductor-grade, technical-grade, and industrial-grade levels reflects purification capital intensity and foundry qualification timelines. Pricing pressure stems from China's MEE emissions standards accelerating closure of inefficient acid capacity. Aluminum smelters exhibit highest price sensitivity due to energy cost pressures, whereas semiconductor foundries prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston handle bulk acid-grade fluorspar before final-mile delivery to fluorochemical processors. Supply concentrates in China's Shandong province, Mexico's San Luis Potosí, and South Africa's Northern Cape, creating single-source vulnerability for acid-grade feedstock. Hydrofluoric acid production draws from fluorspar ore, sulfuric acid, and energy inputs, with logistics regulations restricting intermodal transport. Distribution runs through dedicated chemical tanker fleets and specialized container systems due to corrosive material handling requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Inorganic Fluorides Market functions as a stable compounder anchored by irreplaceable fluxing chemistry in aluminum smelting and escalating purity demands from semiconductor fabrication.
For Market Incumbents: Cement metallurgical application expertise through embedded technical service teams at Persian Gulf smelter sites, displacing spot-market competitors. Acquire acid regeneration capabilities serving Japanese semiconductor fabs to capture closed-loop service contracts. Inert anode pilot programs in Norway threaten long-term cryolite displacement—qualify alternative fluorine feedstocks before regulatory acceleration. For New Entrants and Emerging Players: Municipal water treatment utilities in secondary Indian cities represent underserved buyers with standardized NSF/ANSI certification requirements and limited incumbent penetration. Target Gujarat's PLI corridor for battery electrolyte salt localization mandates, partnering with cell manufacturers seeking supply security. Pursue toll manufacturing arrangements with established acid producers to bypass capital-intensive purification asset requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized electronic materials producers holding sub-ppb metal impurity qualifications with Samsung Foundry and TSMC. Five-to-ten year viability hinges on semiconductor node advancement sustaining specification escalation. Watch South Korean and Taiwanese foundry capex announcements as inflection indicators for technical-grade fluoride demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acid-Grade Fluorspar | Mexican and Chinese mining assets secure feedstock cost advantage against spot-market volatility. |
| Semiconductor-Grade Certification Investment | Sub-ppb qualification with TSMC and Samsung Foundry unlocks premium pricing tiers. |
| Closed-Loop Acid Regeneration Services | Japanese semiconductor fabs contract for waste stream conversion into technical-grade feedstock. |
| PLI Corridor Manufacturing Scale-Up | Gujarat and Tamil Nadu facilities capture India's localized battery electrolyte salt mandates. |
| Multi-Year Technical Partnership Structuring | Bahrain and Icelandic smelters consolidate procurement around embedded metallurgical support. |
Research Methodology
Multiple input streams — primary interviews with fluorochemical plant managers, procurement leads at aluminum smelters, and semiconductor materials engineers; secondary validation through customs trade data, SEC 10-K filings, and Cefic industry reports; plus technical literature from EPA and MEE regulatory databases — were reconciled through bottom-up and top-down triangulation. Supply-side estimates derived from named producer capacity disclosures were cross-checked against demand-side consumption patterns from end-use industry associations.
Data-stream reconciliation applied across the projection horizon modeled segmentation dimensions including grade tier (pharmaceutical, technical, industrial), end-use industry (aluminum smelting, semiconductor fabrication, battery manufacturing), and regional production hub configuration. CAGRs were derived from volume trajectory analysis incorporating fluorspar supply constraints, regulatory phase-down schedules, and foundry capacity expansion pipelines. Forecast inputs included China's dual carbon policy implementation pace and South Korean battery cell localization requirements.
Underlying measurement precision varies by segment; semiconductor-grade and pharmaceutical-grade categories carry tighter precision than industrial-grade commodities due to concentrated producer disclosure. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and substitution technology development. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that inert anode commercialization or accelerated EU F-Gas phase-downs could materially revise trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Selenium Sulfide Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
North America Ethylene Dichloride (EDC) Market
Chemicals
Global Hydrogen Fluoride Market
Chemicals
Resorcinol Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Egypt Acidulants Market
Chemicals
Immunochemicals Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Myclobutanil Market
Chemicals
South Korea Methanol Market
Chemicals
Methoprene Market
Chemicals
5 Dinitroaniline Market
Chemicals
Global Glycol Ether Market
Chemicals
Lauryl Dimethyl Amine Oxide Market
Chemicals
Amine Oxide Market