
 Calcium Hydride Market | 2026-2036
Calcium Hydride Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Hydride Market Outlook
Capital-intensity divergence between integrated miners and specialty chemical producers is rotating competitive advantage toward backward-integrated suppliers. Albemarle Corporation leverages its lithium-bromine infrastructure to sustain captive calcium feedstock access at scale. Materion Corporation anchors North American supply through in-house reduction capabilities and aerospace-qualified production lines. Merck KGaA differentiates via pharmaceutical-grade certification and European REACH compliance leadership.
Calcium hydride (CaH₂) is an alkaline earth metal hydride with a hexagonal crystal structure and density of approximately 1.7 g/cm³, produced industrially through direct reduction of calcium oxide with hydrogen at temperatures exceeding 600°C under controlled atmospheric conditions. The compound functions primarily as a high-capacity drying agent and portable hydrogen source, releasing hydrogen through controlled hydrolysis reactions with water or alcohols. Powder and granule formulations dominate current volume, with tablet and pellet formats capturing margin pools in aerospace and pharmaceutical end uses where precise dosing and handling safety command premium positioning. Hydrogen generation applications lead absolute demand expansion, while drying agent sales sustain steady replacement cycles across chemical manufacturing facilities.
EPA hazardous waste classifications and OSHA permissible exposure limits govern North American handling protocols, while REACH registration and CLP hazard communication standards shape European market access requirements. China's MEE enforces dual carbon-aligned emissions thresholds for hydride production facilities, elevating compliance costs for non-integrated manufacturers. Stakeholders must monitor evolving hydrogen purity standards across jurisdictions, as regulatory stringency in fuel cell feedstock specifications will determine which product grades retain commercial viability.
Market Dynamics
China's dual carbon goals and tightening GB hydrogen purity standards are compressing supply chain margins while redirecting production investment toward integrated facilities with captive calcium feedstock.
Growth Catalysts
- Fuel Cell Hydrogen Demand:Hydrogen generation applications in fuel cell systems are expanding as automotive and stationary power sectors seek cleaner energy carriers with portable storage requirements.
- REACH Compliance Premium:European pharmaceutical and aerospace buyers now mandate REACH-registered material grades, creating price premiums for certified suppliers with documented supply chain transparency.
- Germany's Chemical Corridor Concentration:BASF and Linde operate integrated hydrogen infrastructure clusters in Ludwigshafen and Leuna that require high-purity desiccant materials for process gas drying.
Market Restraints
- Calcium Metal Input Volatility:Electrolytic calcium production costs fluctuate with electricity pricing, exposing non-integrated hydride manufacturers to margin compression during energy price spikes.
- Chinese Supply Concentration:Over half of global calcium oxide feedstock originates from Shandong and Hebei provinces, creating geographic risk for downstream hydride producers without diversified sourcing.
- Silica Gel Substitution:Regenerable molecular sieve desiccants are capturing share in stationary industrial drying where portability is not required.
Strategic Opportunities
- India PLI Hydrogen Incentives:India's production-linked incentive scheme for green hydrogen electrolyzers will create localized demand for portable hydrogen storage and generation materials.
- Aerospace Tablet Formats:Precision-dosed pellet and tablet formulations command margin premiums in satellite and aircraft applications where handling safety and exact stoichiometry are critical.
- ISO 14687-2 Convergence:Harmonizing fuel cell hydrogen purity standards across ISO, SAE, and GB frameworks is enabling qualified suppliers to serve multiple jurisdictions with single product grades.
Industry Challenges
- Pyrophoric Handling Certification:Operators must maintain OSHA-compliant confined space entry protocols and specialized fire suppression systems, extending facility commissioning timelines.
- Pharmaceutical GMP Compliance:CaH₂ suppliers seeking drug master file status face multi-year validation cycles with FDA and EMA inspectors for excipient-grade material.
- Legacy Process Equipment Retrofit:Batch reduction furnaces designed for lower purity outputs require capital-intensive upgrades to meet tightening particulate and moisture specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Hydride Market |
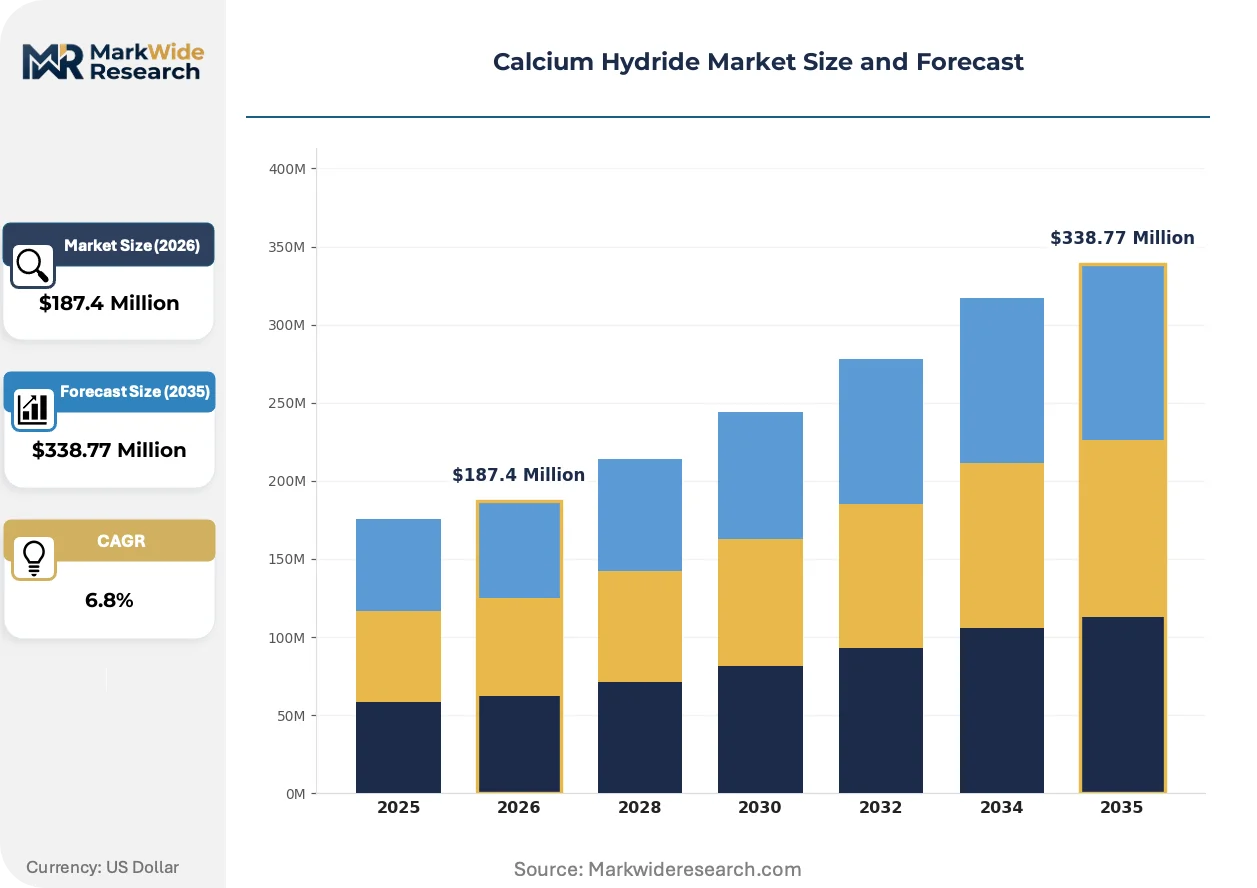
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Tablets, Pellets End User: Chemical Manufacturing, Aerospace, Electronics, Pharmaceuticals Application: Hydrogen Generation, Drying Agent, Fuel Cell, Chemical Reaction Packaging Type: Bags, Drums, Containers, Bulk |
| Companies Covered | Albemarle Corporation, Materion Corporation, Merck KGaA, American Elements, SHINYA CHEM, Anhui Wotu Chemical Co., Ltd., Noah Technologies Corporation, Alfa Aesar, Tokyo Chemical Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Hydride Market Strategic Shifts
Technology and regulatory trajectories are fragmenting traditional supply relationships while creating new entry points for specialized material grades and service models.
Continuous flow hydrogen generation systems using controlled hydrolysis of calcium hydride slurries are fragmenting the market between portable field-deployable units and fixed industrial installations. Military and disaster relief agencies are adopting cartridge-based systems for rapid deployment scenarios. This fragmentation is compressing demand for bulk powder formats while expanding tablet and pellet contract manufacturing opportunities.
China's MEE enforcement of dual carbon-aligned emissions thresholds for hydride production facilities is elevating compliance costs for non-integrated manufacturers. Facilities in Shandong province must now document renewable energy sourcing for electrolytic calcium feedstock. European importers are responding by qualifying alternative supply from Kazakhstan and Uzbekistan with lower carbon intensity profiles.
Specification-driven procurement now dominates fuel cell hydrogen supply agreements, with buyers unbundling material certification from logistics and inventory management services. Tier-1 automotive suppliers are requiring vendor-managed inventory with real-time purity documentation. This pattern is most visible in Germany's Rhineland and Bavaria clusters where BMW and Siemens Energy operate integrated hydrogen validation centers.
Calcium Hydride Market Segmentation
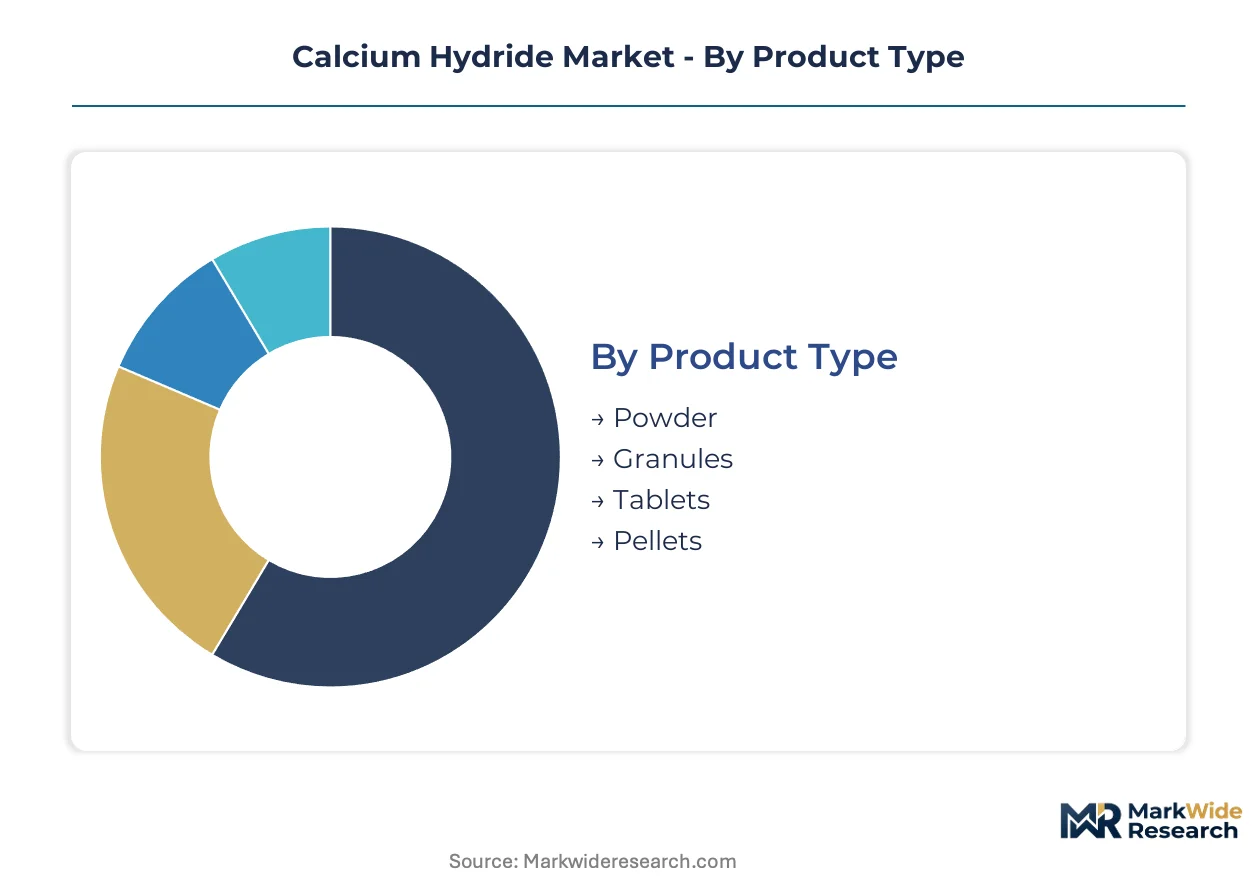
Calcium hydride's dual role as desiccant and hydrogen carrier fragments demand across incompatible performance tiers. Product form and purity specifications determine which segments face immediate substitution from silica gel or liquid organic hydrogen carriers.
Product Type:
Powder and granule formats face the strongest silica gel substitution pressure in stationary drying, while tablet and pellet configurations defend position through handling safety requirements.
- Powder:Fine particulate with high surface area enables rapid moisture absorption in batch chemical processes. Chemical manufacturing facilities in Germany's Ludwigshafen cluster specify powder grades for process gas drying lines where regeneration cycles are impractical.
- Tablets:Precision-compressed forms with controlled dissolution rates command premium positioning. Aerospace applications in satellite propulsion systems require tablet formats where exact stoichiometry and pyrophoric handling safety are non-negotiable.
- Granules:Intermediate particle size balances reactivity with flow characteristics for industrial handling.
- Pellets:Extruded cylindrical forms suit automated feeding systems in continuous hydrogen generation installations.
Powder anchors the volume base while tablets gain share at the steepest rate.
End User:
Customer sophistication varies dramatically, with pharmaceutical and aerospace buyers enforcing certification barriers that chemical manufacturers rarely match.
- Chemical Manufacturing:Bulk consumers of standard-grade material for solvent drying and inert atmosphere generation. BASF and Linde infrastructure clusters in Germany consume substantial volumes for hydrogen feedstock and process protection.
- Pharmaceuticals:Excipient-grade requirements demand drug master file status with FDA and EMA validation. REACH-registered suppliers capture price premiums through documented supply chain transparency for European formulators.
- Aerospace:Satellite and aircraft applications require lot-traceable material with aerospace-qualified production lines.
- Electronics:Semiconductor fabrication uses high-purity grades for moisture-sensitive assembly environments.
Chemical manufacturing anchors the volume base while pharmaceuticals climbs the fastest on compliance premiums.
Application:
Application mix reflects the fundamental tension between mature drying utility and emerging hydrogen economy positioning.
- Hydrogen Generation:Controlled hydrolysis releases hydrogen for fuel cell feedstock and portable power. Military and disaster relief agencies adopt cartridge-based systems for rapid deployment scenarios where grid independence matters.
- Drying Agent:Established utility in solvent dehydration and inert atmosphere maintenance faces regenerable molecular sieve competition in stationary installations.
- Fuel Cell:Dedicated hydrogen purity grades for proton exchange membrane systems must meet ISO 14687-2 specifications.
- Chemical Reaction:Reducing agent applications in organic synthesis consume consistent volumes with lower purity requirements.
Drying agent anchors the volume base while hydrogen generation expands most quickly on fuel cell demand.
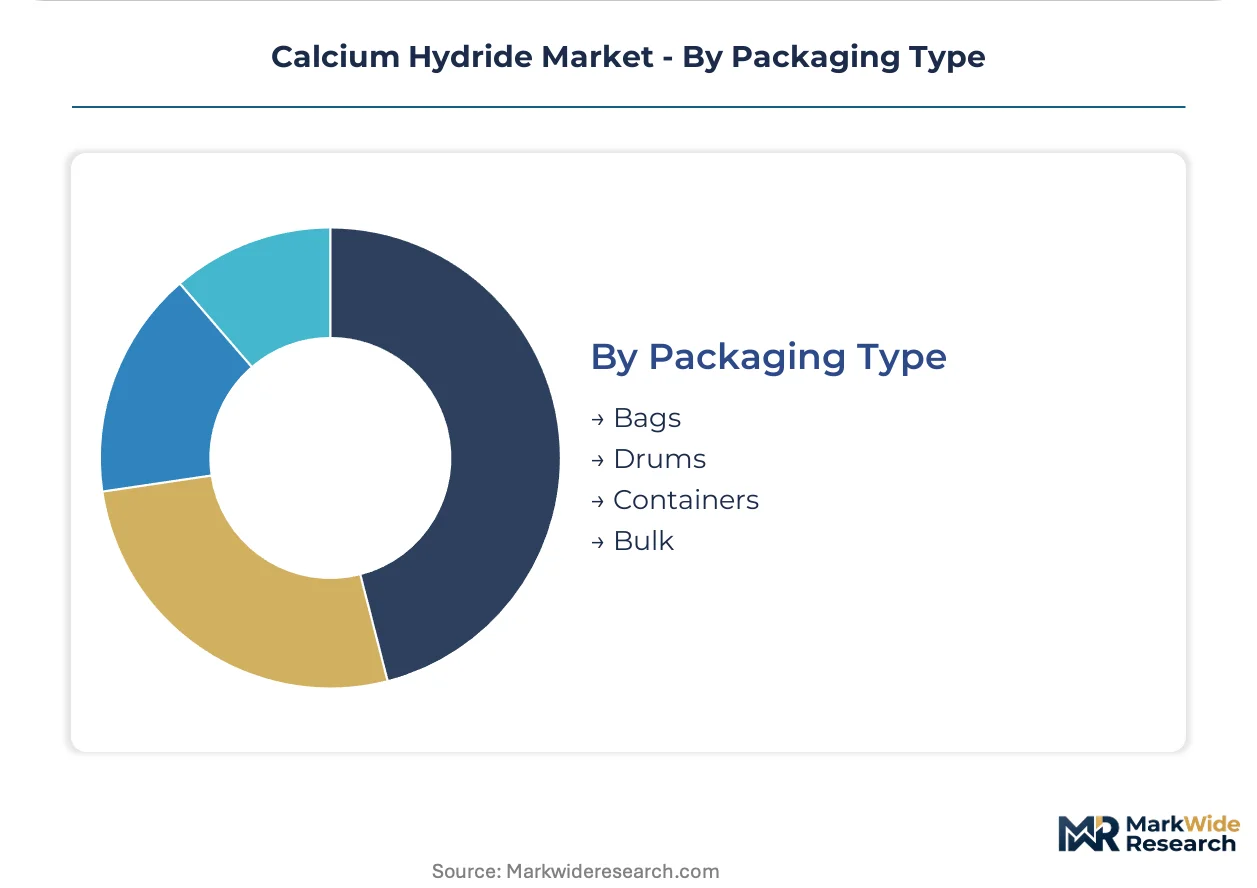
Packaging Type:
Packaging configuration directly reflects customer scale and handling infrastructure investment.
- Drums:Steel or fiber containers dominate mid-volume chemical plant procurement with established handling protocols.
- Bulk:Tanker or silo delivery serves integrated hydrogen infrastructure clusters with dedicated unloading systems.
- Bags:Multi-layer barrier packaging protects moisture-sensitive material for smaller-scale laboratory and pilot plant consumption.
- Containers:Intermediate bulk containers bridge drum and bulk formats for flexible manufacturing operations.
Drums anchor the volume base while bulk gains share fastest among integrated producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany's chemical corridor exceeds that of Chinese export hubs by substantial margins, reflecting certification premiums and integrated hydrogen infrastructure investment. This asymmetry redirects capacity expansion toward European REACH-registered facilities while compressing margins for standard-grade exporters.
United States
Fuel cell validation centers in Michigan and California drive demand for ISO 14687-2 qualified hydrogen generation materials. OSHA permissible exposure limits and EPA hazardous waste classifications elevate handling compliance costs for non-integrated processors. The Gulf Coast petrochemical corridor sustains steady desiccant consumption for solvent dehydration and inert atmosphere protection.
Germany
BASF and Linde operate integrated hydrogen infrastructure clusters in Ludwigshafen and Leuna requiring high-purity desiccant materials for process gas drying. REACH registration and CLP hazard communication standards create price premiums for certified suppliers with documented supply chain transparency. Bavaria's aerospace-qualified production lines command tablet format premiums for satellite propulsion applications.
China
Shandong and Hebei provinces originate over half of global calcium oxide feedstock, concentrating geographic risk for downstream hydride producers. MEE enforcement of dual carbon-aligned emissions thresholds elevates compliance costs for facilities without renewable energy sourcing documentation. Yangtze River Delta chemical processors are upgrading batch reduction furnaces to meet tightening particulate specifications.
India
The production-linked incentive scheme for green hydrogen electrolyzers will create localized demand for portable hydrogen storage and generation materials. BIS standards alignment with ISO frameworks enables qualified suppliers to serve domestic fuel cell manufacturers. Gujarat's specialty chemical corridor is attracting backward-integrated investment for captive calcium feedstock security.
Japan
METI hydrogen roadmap targets elevate fuel cell purity requirements for proton exchange membrane systems. JIS standards for industrial chemicals create certification barriers for non-domestic suppliers seeking automotive tier-1 qualification. Kansai region semiconductor fabricators consume high-purity grades for moisture-sensitive assembly environments.
Calcium Hydride Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with backward-integrated miners commanding feedstock security while specialty chemical houses capture certification premiums. The vendor base stratifies into three tiers: integrated mining-chemical conglomerates with captive calcium access, REACH-registered European specialists with pharmaceutical-grade validation, and regional standard-grade processors serving cost-sensitive chemical manufacturing. Dominant competitive moves include capacity expansion at integrated facilities and strategic partnerships between hydride processors and hydrogen infrastructure operators.
Among North American integrated suppliers, Albemarle Corporation and Materion Corporation occupy positions reflecting captive feedstock access and aerospace-qualified production infrastructure. Merck KGaA represents the European pharmaceutical-grade archetype with REACH compliance leadership. Chinese processors including Anhui Wotu Chemical Co., Ltd. exemplify regional scale-driven positioning serving standard-grade chemical manufacturing demand. These three archetypes—integrated North American, European certified, and Chinese scale—define competitive tension across product purity tiers and geographic markets.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Materion Corporation |
| Merck KGaA |
| American Elements |
| SHINYA CHEM |
| Anhui Wotu Chemical Co., Ltd. |
| Noah Technologies Corporation |
| Alfa Aesar |
| Tokyo Chemical Industry Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Silica gel substitution in stationary industrial drying is simultaneously redrawing supply geography toward regenerable desiccant hubs and compressing pricing power for bulk powder grades. This displacement forces calcium hydride producers to retreat into premium tablet and pellet formats where handling safety requirements defend margins.
Pricing Analysis
The customization-premium spread between configured-to-order tablet formulations and standard powder grades spans three distinct pricing tiers anchored by certification level and volume scale. Pharmaceutical-grade material with FDA drug master file status commands substantial premiums over industrial desiccant grades, while aerospace-qualified production lines extract additional margins through lot-traceability documentation. Cost compression in standard powder tiers is intensifying because silica gel molecular sieves capture share in stationary installations where portability is irrelevant. Chemical manufacturing facilities in Germany's Ludwigshafen cluster exhibit the least price sensitivity due to integrated hydrogen infrastructure dependencies, whereas regional processors in Shandong province face acute pressure from undifferentiated Chinese export competition.
Supply Chain Analysis
Inbound logistics costs from Shandong and Hebei province ports to European fuel cell hubs have elevated landed costs for non-integrated distributors amid container availability constraints on Asia-Europe trade lanes. Supply concentrates in China's calcium oxide belt, with Kazakhstan and Uzbekistan emerging as alternative qualified sources for REACH-registered importers seeking lower carbon intensity profiles. Raw material dependencies center on electrolytic calcium metal, hydrogen feedstock, and high-purity alumina crucibles for reduction furnace operations. Single-source vulnerability in Chinese calcium oxide feedstock creates structural exposure for downstream hydride producers without diversified sourcing. Distribution runs through integrated hydrogen infrastructure clusters operated by BASF and Linde in Germany, with drum and bulk formats serving chemical plant procurement and tanker delivery respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across fuel cell purity tiers, pharmaceutical certification grades, and aerospace handling requirements creates multiple defendable niches for specialized entrants. The unbundling of material certification from logistics services in German procurement patterns particularly rewards nimble contract manufacturers.
For Market Incumbents: Fortify captive calcium feedstock access through backward integration into electrolytic metal production or long-term offtake agreements with Shandong-based oxide processors. Capacity expansion at REACH-registered European facilities captures pharmaceutical and aerospace premiums while insulating against Chinese standard-grade export competition. Silica gel substitution in stationary drying represents the primary threat requiring product mix migration toward tablet formats.
For New Entrants and Emerging Players: Differentiate on ISO 14687-2 qualification for fuel cell hydrogen grades, where harmonizing standards across jurisdictions enable single-product multi-market access. India's PLI scheme for green hydrogen electrolyzers offers the most penetrable white-space geography, with Gujarat's specialty chemical corridor attracting localized portable hydrogen storage demand. A vendor-managed inventory model with real-time purity documentation addresses unmet needs in German automotive tier-1 supply agreements.
For Investors and Strategic Acquirers: China's MEE enforcement of dual carbon-aligned emissions thresholds reshapes the acquisition landscape by elevating compliance costs for non-integrated manufacturers and rewarding facilities with documented renewable energy sourcing. The five-to-ten year viability window favors backward-integrated processors with captive calcium security over pure-play hydride converters exposed to electricity price volatility. Acquisition target archetypes include European REACH-registered specialists with pharmaceutical-grade validation and Central Asian oxide producers with low-carbon intensity profiles. The signal to monitor is BIS standards alignment with ISO frameworks in India, which would unlock domestic fuel cell qualification pathways for qualified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolytic Calcium | Captive feedstock access insulates Albemarle and Materion from electricity price spikes. |
| REACH Registration Investment | Merck KGaA's compliance leadership captures pharmaceutical-grade price premiums across European formulators. |
| ISO 14687-2 Qualification | Harmonized fuel cell hydrogen standards enable single-product supply to German and Japanese automotive clusters. |
| Tablet Format Capacity Expansion | Precision-dosed configurations defend margins in satellite propulsion where handling safety is non-negotiable. |
| Vendor-Managed Inventory Partnerships | BMW and Siemens Energy validation centers demand real-time purity documentation with logistics integration. |
Study Parameters
A spread of perspectives from plant managers at integrated hydride facilities, procurement leads at BASF and Linde hydrogen clusters, pharmaceutical regulatory affairs directors, and aerospace-qualified production engineers converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC 10-K filings, Cefic chemical industry reports, customs and trade data for calcium oxide feedstock flows, and MEE emissions disclosure records. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across product formats and end-use applications.
Segmentation dimensions modeled include product type tiering across powder, granule, tablet, and pellet formats; end-user industry verticals spanning chemical manufacturing, pharmaceuticals, aerospace, and electronics; application splits between hydrogen generation, drying agent, fuel cell feedstock, and chemical reaction uses; and regional production hub clustering. CAGRs were derived from slope analysis of historical capacity utilization against projected fuel cell hydrogen demand curves, with electrolyzer deployment timelines and GB standards convergence serving as industry-specific forecast inputs across the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained fuel cell hydrogen purity standard harmonization, continued MEE enforcement stringency, or silica gel substitution rates in stationary drying would require recalibration. Forecasts reflect documented assumptions regarding electrolytic calcium production cost trajectories, renewable energy sourcing documentation requirements, and pharmaceutical excipient-grade validation cycle durations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Hydrogen Fluoride Market
Chemicals
Europe Biguanide Market
Chemicals
Aerosol Insecticides Market
Chemicals
Global Methyl Cellulose Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Benzophenone (Oxybenzone) Market
Chemicals
Integrated Chemistry Systems Market
Chemicals
Amine Oxide Market
Chemicals
Sunscreen Ingredients Market
Chemicals
Global Fluorosilicic Acid Market
Chemicals
Vinyl Acetate Market
Chemicals
North America Tartaric Acid Market
Chemicals
Welding Chemicals Market
Chemicals
Phenylethyl Market
Chemicals
Africa Mining Chemicals Market
Chemicals
Aluminum Ammonium Sulfate Market