
 Global Construction Adhesives Market | 2026-2036
Global Construction Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Adhesives Market Foresight
Multi-source procurement is consolidating across the construction adhesives sector as builders seek supply security amid resin volatility. Henkel AG & Co. KGaA leverages its European manufacturing footprint to sustain consistent delivery to infrastructure firms. Sika AG anchors its position through specialized waterproofing and sealing formulations. Dow Chemical Company competes by extending its acrylic and silicone portfolios across commercial and residential channels.
Construction adhesives are synthetic or natural polymer-based bonding agents formulated to achieve specified shear strength, elongation at break, and cure times under ambient or accelerated conditions; they replace mechanical fasteners in structural, flooring, and facade assemblies where load distribution and thermal bridging matter. Water-based technology leads volume shipments due to regulatory pressure on solvent emissions, while reactive systems capture premium margin pools in structural bonding applications. Polyurethane dominates flooring and insulation attachment for its flexibility and moisture resistance, whereas silicone commands facade and joint sealing segments through UV stability and movement accommodation.
REACH in Europe, EPA regulations in the United States, and GB standards under China's MEE collectively restrict volatile organic compound content and mandate hazard communication labeling, pushing manufacturers toward low-emission formulations and extended safety data sheets. ECHA's ongoing substance evaluations further tighten candidate list restrictions for phthalates and isocyanates common in polyurethane systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation lock-in that limits cross-border product portability.
Market Dynamics
Water-based adhesive technology is displacing solvent systems across residential and commercial construction as REACH, EPA, and GB standards tighten VOC thresholds simultaneously, forcing manufacturers to rebuild formulation portfolios around low-emission chemistry.
Growth Catalysts
- Prefabricated panel systems:Residential developers in the United States and China are expanding adhesive bonding in modular wall and floor assemblies to reduce thermal bridging and accelerate on-site assembly cycles.
- REACH substance evaluations:ECHA's tightening restrictions on phthalates and isocyanates are accelerating R&D investment in bio-based polyols and silane-terminated polymers across European manufacturing.
- Infrastructure spending corridors:Central government outlays in India, China, and the United States are concentrating demand for structural adhesives in bridge decking, tunnel waterproofing, and transit station facades.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate input costs swing with crude oil and natural gas pricing, compressing margin visibility for polyurethane system suppliers.
- Specialized resin concentration:Asia-Pacific producers dominate silane and specialty acrylic monomer supply, creating geographic single-source exposure for Western formulators.
- Cure time limitations:Water-based systems require extended ambient drying periods that conflict with compressed construction schedules in high-latitude winter markets.
Strategic Opportunities
- India's green building codes:GRIHA and IGBC certification expansion is creating specification pull for low-VOC flooring and facade adhesives in commercial high-rise construction.
- Reactive hot-melt convergence:Hybrid polyurethane-reactive systems are opening structural glazing and wind turbine blade bonding applications previously served by mechanical fastening.
- Direct-to-contractor digital channels:Specialty distributors in Germany and the United States are launching specification tools that bypass traditional wholesaler markups for mid-volume commercial projects.
Industry Challenges
- Formulation chemist scarcity:Expertise in silane chemistry and moisture-cure kinetics is concentrating at a handful of European and Japanese suppliers, constraining new entrant R&D velocity.
- Multi-jurisdiction certification lag:Securing simultaneous EPA, REACH, and GB standard compliance for a single product line extends commercialization timelines by eighteen to thirty-six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Adhesives Market |
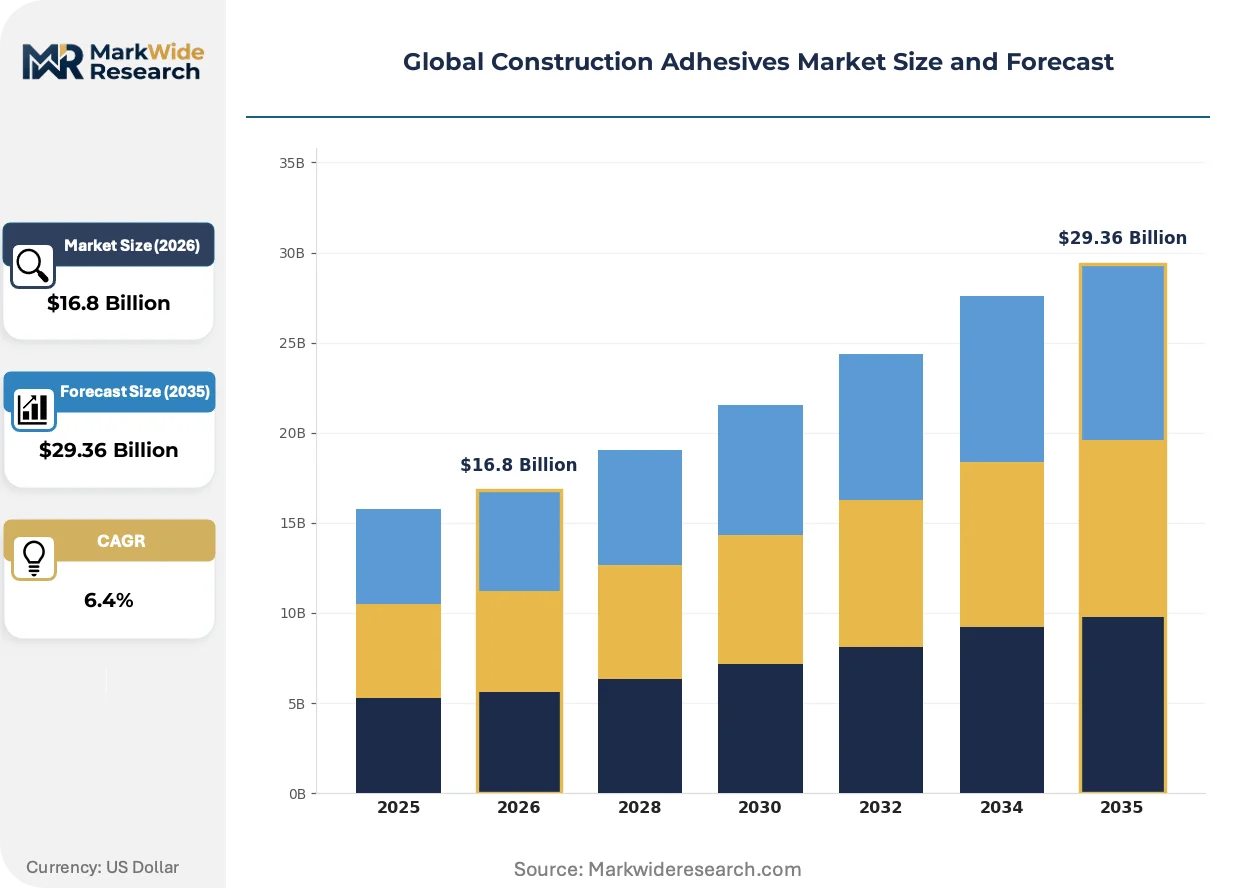
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $29.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic, Butyl, Latex Technology: Solvent-Based, Water-Based, Hot Melt, Reactive, Pressure-Sensitive, Anaerobic Application: Structural Bonding, Flooring, Insulation, Roofing, Facade, Joint Sealing End User: Commercial Builders, Residential Developers, Infrastructure Firms, Renovation Experts |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Sika AG, Dow Chemical Company, H.B. Fuller Company, Bostik SA, BASF SE, Arkema Group, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Adhesives Market Shifts & Advancements
Adhesive formulators are rebuilding product architectures around modularity, regulatory pre-certification, and direct specification relationships to capture margin in a market where performance claims face intensifying third-party verification.
Hybrid silane-terminated polyurethane technology is modularizing structural bonding applications by combining the tensile strength of reactive systems with the application simplicity of moisture-cure chemistry. Curtain wall contractors in Germany and the United States are specifying these systems for movement joints exceeding 25% elongation. The technology is compressing the traditional separation between structural and sealant product categories.
China's MEE is enforcing GB 30982-2014 VOC limits for construction adhesives through expanded provincial inspection regimes in Jiangsu and Guangdong. Domestic manufacturers are accelerating water-based and hot-melt capacity additions to avoid production halts. Imported solvent systems are retreating from facade and flooring specification lists in tier-one city developments.
Specification authority is migrating from general contractors to facade consultants and energy modelers who prioritize whole-assembly U-value performance over unit adhesive cost. German and Dutch engineering firms are embedding adhesive thermal bridging calculations directly into BIM workflows. This behavioral shift is most visible in commercial high-rise construction across Northern Europe and coastal China.
Global Construction Adhesives Market Segmentation
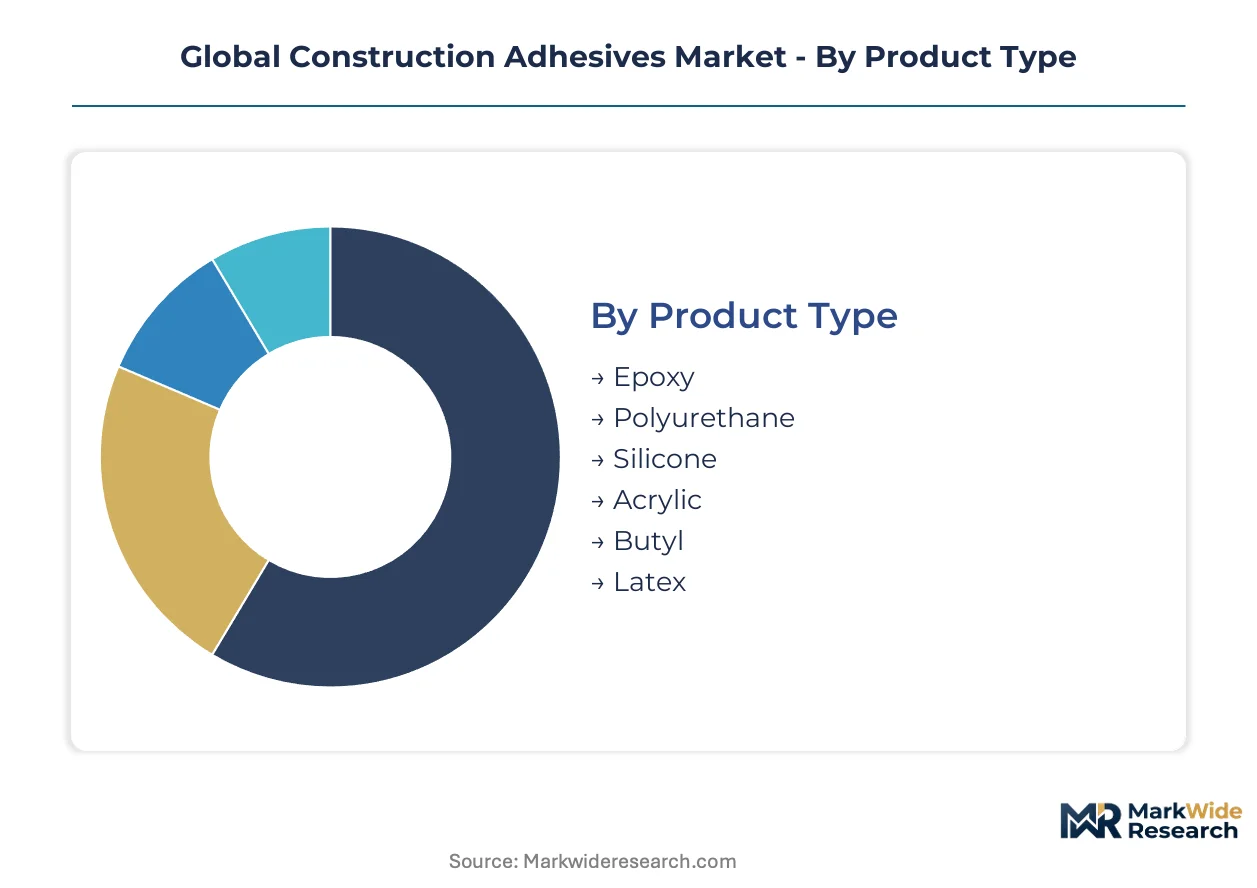
Construction adhesives segmentation reveals how certification burdens concentrate differently across chemistry types, curing mechanisms, and installation environments. Specification authority varies sharply by application, with facade and structural bonding demanding the most extensive third-party validation.
Product Type:
REACH substance evaluations and EPA VOC thresholds impose divergent compliance costs across polymer chemistries, with isocyanate-containing systems facing the heaviest documentation burdens.
- Epoxy:Two-part thermosetting systems deliver compressive strength exceeding 12,000 psi for structural anchoring and rebar bonding. Bridge decking contractors in Germany and the United States specify epoxy for load-bearing connections where creep resistance under sustained tension matters. ECHA's ongoing bisphenol-A restrictions are forcing reformulation toward aliphatic amine hardeners.
- Polyurethane:Moisture-curing systems dominate flooring and insulation attachment through flexibility retention across -40°C to 90°C service windows. Residential developers in China and India are expanding specification for prefabricated wall panels where thermal bridging reduction accelerates assembly cycles. GB 30982-2014 VOC limits are pushing domestic Chinese manufacturers toward water-based alternatives.
- Silicone:UV-stable formulations command facade and joint sealing segments through 50-year durability ratings and ±50% movement accommodation.
- Acrylic:Water-dispersed systems serve interior finishing and trim applications where fast tack and paint compatibility outweigh structural demands.
- Butyl:Preformed tapes and sealants anchor vapor barrier continuity in roofing and window perimeter detailing.
- Latex:Vinyl acetate copolymers capture economy-grade flooring and wallpaper adhesive volumes in residential renovation channels.
Polyurethane sits at the top of the volume ranking, with silicone climbing the fastest on facade specification growth.
Technology:
Cost tiers separate technologies by capital intensity and raw material exposure, with reactive systems commanding premium pricing against commodity water-based volumes.
- Solvent-Based:Hydrocarbon-carried systems retain niche specification in cold-weather roofing and specialty waterproofing where rapid solvent flash-off enables winter installation. Regulatory retreat is pronounced: China's MEE enforcement in Jiangsu and Guangdong provinces has halved domestic production capacity since GB standard tightening.
- Water-Based:Acrylic and polyurethane dispersions lead residential and commercial volumes through low odor and brush-cleanup convenience. Flooring contractors in the United States and Netherlands specify water-based systems for occupied-space renovations where VOC exposure liability concentrates. Extended ambient cure times constrain specification in high-latitude winter markets.
- Hot Melt:Thermoplastic EVA and polyolefin systems serve carpet tile and prefabricated panel bonding through instant green strength and automated dispensing compatibility.
- Reactive:Two-part epoxies and polyurethanes capture structural glazing and wind turbine blade bonding where load transfer and fatigue resistance justify premium pricing.
- Pressure-Sensitive:Permanent-tack formulations anchor membrane and flashing details in roofing and waterproofing assemblies.
- Anaerobic:Threadlocking and retaining compounds serve mechanical anchorage in infrastructure metalwork where vibration resistance matters.
Water-based technology holds the dominant volume position, with reactive systems gaining share fastest on structural application expansion.
Application:
Customer type determines specification authority, with infrastructure engineers and facade consultants wielding veto power over general contractor preferences in high-performance segments.
- Structural Bonding:Load-transfer adhesives replace mechanical fasteners in curtain wall, composite panel, and wind turbine blade assemblies where stress distribution and fatigue life override first-cost considerations. German engineering firms embed adhesive structural calculations directly into BIM workflows, migrating specification authority from contractors to energy modelers.
- Flooring:Subfloor preparation, tile setting, and carpet installation adhesives serve the largest addressable volume across residential and commercial channels. India's GRIHA and IGBC certification expansion is creating specification pull for low-VOC systems in commercial high-rise construction.
- Insulation:Board attachment and continuous insulation adhesives anchor thermal envelope performance in deep energy retrofit and new construction.
- Roofing:Membrane bonding, flashing attachment, and sealant applications demand UV and ponded-water resistance across single-ply and modified bitumen systems.
- Facade:Panel cladding, rainscreen, and curtain wall sealing applications command premium pricing through movement accommodation and weathering durability requirements.
- Joint Sealing:Expansion and control joint fillers bridge substrate movement while maintaining air and water barrier continuity.
Flooring commands the highest shipment volumes, with structural bonding expanding most quickly on prefabrication adoption.
End User:
Geographic concentration of demand aligns with infrastructure spending corridors, concentrating adhesive procurement in China, India, and the United States.
- Commercial Builders:Office, retail, and hospitality developers specify adhesives through performance-based procurement where whole-assembly U-value and air leakage targets override unit material costs. Facade consultants in Northern Europe and coastal China now embed adhesive thermal bridging calculations into specification documents.
- Residential Developers:Single-family and multifamily builders drive water-based and hot-melt volumes through prefabricated panel adoption and finish carpentry standardization. Chinese developers in tier-one cities are accelerating modular wall and floor assembly to compress on-site construction schedules.
- Infrastructure Firms:Bridge, tunnel, and transit station contractors specify structural and waterproofing adhesives through design-build contracts where durability warranties extend to 50 years. Central government outlays in India and the United States are concentrating demand for epoxy and polyurethane systems in bridge decking and tunnel waterproofing.
- Renovation Experts:Retrofit and maintenance contractors capture aftermarket volumes where substrate condition variability demands adaptive specification and rapid cure chemistry.
Residential developers anchor the volume base, with infrastructure firms ascending fastest on public spending acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta anchors construction adhesive demand through prefabricated housing clusters in Guangdong province. Infrastructure corridors in India and the United States concentrate structural bonding procurement. Regulatory divergence between REACH, EPA, and GB standards forces manufacturers to maintain parallel formulation portfolios.
China
Modular construction in Jiangsu and Guangdong provinces accelerates polyurethane specification for wall panel bonding. MEE enforcement of GB 30982-2014 VOC limits has halved domestic solvent-based capacity since standard tightening. Tier-one city developers in Shanghai and Shenzhen now exclude imported solvent systems from facade specification lists.
United States
Bridge decking contractors specify epoxy systems for load-bearing connections under sustained tension. EPA VOC thresholds tighten concurrently with REACH, forcing reformulation around low-emission chemistry. Infrastructure spending corridors in Texas and California concentrate demand for structural and waterproofing adhesives in transit station facades.
India
GRIHA and IGBC certification expansion creates specification pull for low-VOC flooring adhesives in commercial high-rise construction. Central government outlays concentrate structural adhesive demand in bridge decking and tunnel waterproofing. Manufacturing clusters in Maharashtra and Gujarat accelerate water-based capacity additions for domestic supply security.
Germany
Facade consultants embed adhesive thermal bridging calculations directly into BIM workflows. ECHA's tightening restrictions on phthalates and isocyanates accelerate R&D investment in bio-based polyols. Engineering firms in North Rhine-Westphalia and Bavaria migrate specification authority from contractors to energy modelers.
United Arab Emirates
Mega-project developments in Dubai and Abu Dhabi specify UV-stable silicone systems for 50-year durability ratings in facade applications. Regional building codes adopt European low-emission benchmarks for commercial high-rise construction. Local distributors stock reactive hot-melt systems for compressed construction schedules in extreme climate conditions.
Global Construction Adhesives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based formulation spaces and direct-to-contractor digital channels. The vendor base organizes around three archetypes: integrated chemical conglomerates with captive resin supply, specialized adhesive formulators with specification authority in niche segments, and regional distributors with logistics control over project sites. Competitive moves concentrate on portfolio diversification into hybrid chemistries and backward integration into specialty monomer production.
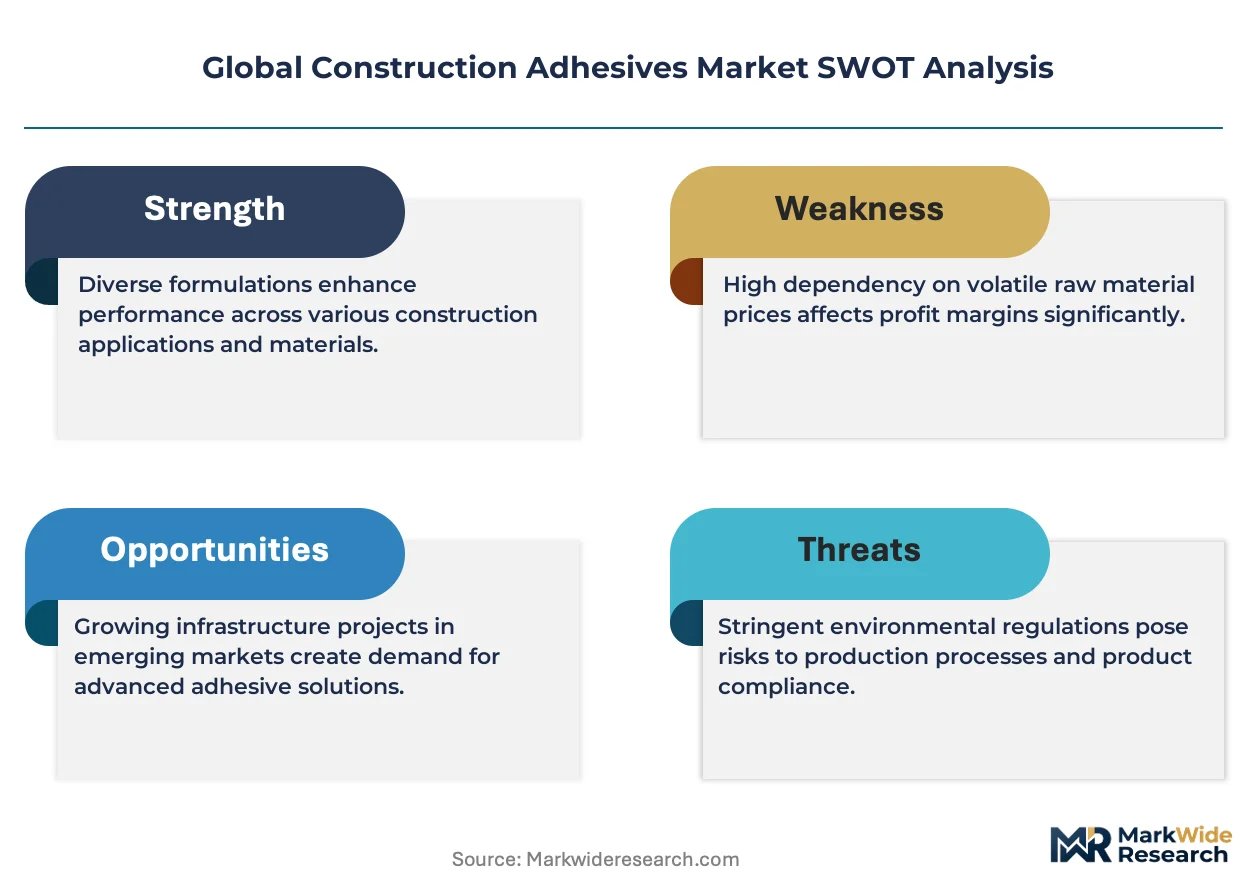
Among European-based formulators, Henkel AG & Co. KGaA and Sika AG occupy positions emphasizing specification relationships with infrastructure firms and facade consultants. Dow Chemical Company exemplifies the integrated archetype through upstream control over acrylic and silicone feedstocks. These three anchors represent distinct competitive vectors: formulation specialization, supply security, and raw material integration.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Sika AG |
| Dow Chemical Company |
| H.B. Fuller Company |
| Bostik SA |
| BASF SE |
| Arkema Group |
| Avery Dennison Corporation |
| Others |
Supply & Pricing Matrix
Modular construction procurement in China and India is forcing adhesive suppliers to reconfigure regional production footprints and absorb volatile petrochemical input costs into contract pricing. Builders consolidating purchase volumes across prefabricated panel projects extract volume discounts that compress margins for non-integrated formulators while rewarding suppliers with captive polyol supply.
Pricing Analysis
Polyol and isocyanate cost pass-through dominates polyurethane system pricing, with crude oil volatility transmitting directly to flooring and insulation attachment quotes within thirty to sixty days. Three-tier pricing structure across premium, standard, and economy levels separates reactive structural systems from water-based commercial grades and commodity latex renovation products. Cost compression in water-based tiers is intensifying because Chinese domestic capacity expansion floods regional spot markets. Residential renovation contractors exhibit the highest price sensitivity, while infrastructure firms prioritize performance guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, Texas, and Jiangsu province anchor hub-and-spoke delivery networks that position adhesive inventories within four-hour trucking radius of major construction corridors. Manufacturing concentration in China, Germany, and the United States draws from silane monomer feedstock anchored in Japanese and South Korean petrochemical complexes. Single-source vulnerability concentrates in specialty acrylic monomer supply from Asia-Pacific producers. Distribution runs through specification-grade distributors in commercial channels and direct-to-contractor digital platforms in residential renovation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European REACH compliance costs exceed Chinese manufacturing economics by a margin sufficient to sustain parallel formulation portfolios.
For Market Incumbents: Lock in specification authority with facade consultants and infrastructure engineers before bio-based entrants capture green building certification mindshare. Backward integration into specialty monomer production defends margin position against petrochemical volatility. Capacity additions in Maharashtra and Gujarat secure supply security for Indian infrastructure spending corridors. For New Entrants and Emerging Players: Begin with water-based flooring adhesives in Indian commercial high-rise construction where GRIHA and IGBC certification creates specification pull with limited incumbent saturation. Direct-to-contractor digital channels bypass traditional wholesaler markups and compress customer acquisition costs in mid-volume commercial projects. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized adhesive formulators possessing silane chemistry expertise and established REACH pre-certification asset bases. Five-to-ten year viability hinges on regulatory divergence persisting between jurisdictions. Watch for ECHA substance evaluation acceleration as an inflection signal for bio-based formulation R&D returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomers | Captive silane and polyol supply insulates margin from crude oil volatility. |
| REACH Pre-Certification Investment | Early bio-based formulation approval accelerates specification capture in German facade projects. |
| Direct-to-Contractor Digital Platform Launch | Bypassing distributor markups compresses price points in residential renovation channels. |
| Capacity Expansion in India | Domestic production addresses GRIHA-driven low-VOC demand without import duty exposure. |
| Hybrid Chemistry Joint Development | Silane-terminated polyurethane convergence opens structural glazing and wind turbine applications. |
Research Methodology
Bottom-up construction end-use modeling reconciled against top-down resin production tracking forms the analytical core of this study. Primary interviews with adhesive formulators, procurement leads at infrastructure firms, facade consultants, and distribution channel partners combined with secondary validation from customs trade data, ECHA substance evaluation registers, and SEC chemical segment filings. Cross-referencing EPA VOC threshold announcements with provincial MEE enforcement actions in Jiangsu and Guangdong triangulates regulatory impact assumptions.
Historical trendline analysis of polymer chemistry adoption rates and technology displacement patterns established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include product chemistry, curing technology, application environment, end-user archetype, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating infrastructure spending correlation coefficients and prefabrication adoption velocity. Forecast inputs incorporate resin price volatility indices and certification timeline lag estimates for multi-jurisdiction product launches.
Several conditions sit outside the modeled scope, including abrupt petrochemical supply disruptions, unilateral tariff regime shifts, and accelerated regulatory harmonization between REACH and GB standards. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
North America Hot Melt Adhesives Market
Adhesives & Sealants
United States Sealants Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
France Adhesives Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market
Adhesives & Sealants
Capillary Underfill Material Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
Gelatin Bone Glue Market
Adhesives & Sealants
UV-Curable Adhesives Market
Adhesives & Sealants
Metal Bonding Adhesives Market