
 Sodium Dichromate Market | 2026-2036
Sodium Dichromate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Dichromate Market Analysis
Technical-grade specification upgrades is bifurcating the sodium dichromate market into performance-tier suppliers and commodity producers. Lanxess leverages its European manufacturing base to sustain premium-grade output for pigment and metal finishing clients. Yinhe Group anchors Chinese supply through integrated chromium ore-to-chemical processing. Vishnu Chemicals competes on specialized leather tanning formulations across South Asian export markets.
Sodium dichromate is an inorganic compound with the formula Na₂Cr₂O₇, typically produced via the acidification of sodium chromate solutions derived from chromite ore roasting; it functions primarily as a powerful oxidizing agent and chromium source for industrial surface treatment and chemical synthesis. Metal finishing applications dominate volume consumption due to aerospace and automotive plating requirements, while pigment manufacturing commands higher margin pools through specialized colorant formulations. Leather tanning represents a maturing segment facing substitution pressure from vegetable-based alternatives, and technical grade leads industrial procurement through standardized purity thresholds.
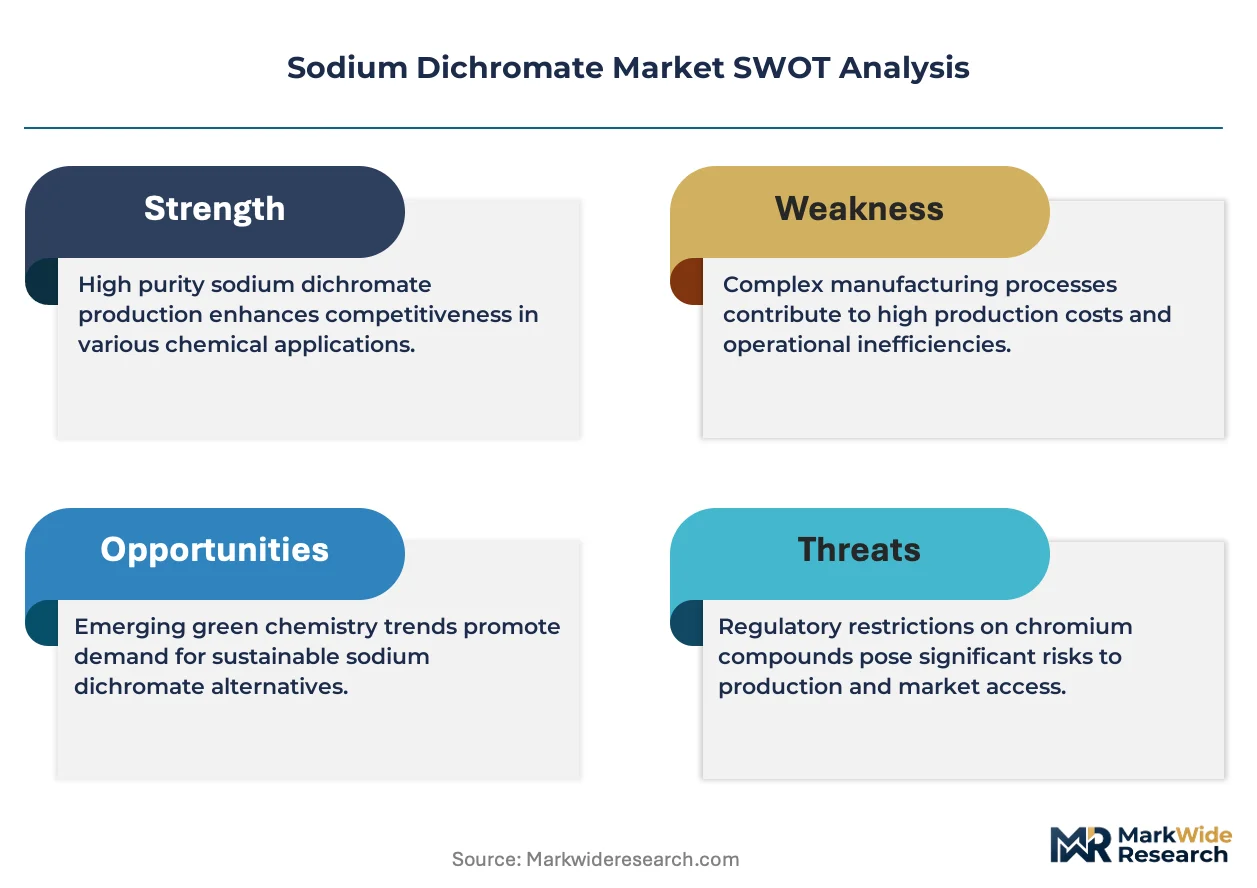
EPA regulations in the United States restrict hexavalent chromium emissions from electroplating facilities, compelling end users to adopt closed-loop recovery systems or seek trivalent alternatives. REACH authorization requirements in Europe constrain dichromate usage in consumer-facing applications, redirecting supply toward industrial-grade buyers with permitted exemptions. India's Central Pollution Control Board enforces effluent standards on tannery clusters in Tamil Nadu and Uttar Pradesh, reshaping regional demand patterns. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with emerging compliance boundaries.
Market Dynamics
REACH authorization requirements in Europe are bifurcating sodium dichromate procurement into exempt industrial-grade channels and restricted consumer-facing applications, redirecting supply concentration toward permitted metal finishing and pigment synthesis buyers.
Growth Catalysts
- Chromium plating demand from aerospace OEMs:Surface treatment specifications for jet engine components and landing gear assemblies sustain volume offtake from tier-one suppliers in the United States and France.
- REACH Annex XIV authorization renewals:Industrial-grade exemptions for metal finishing and pigment manufacturing create protected demand pools unavailable to substitute materials.
- Chromite ore processing clusters in China:Integrated roasting and acidification facilities in Shanxi and Henan provinces deliver cost-competitive sodium dichromate feedstock to domestic pigment producers.
Market Restraints
- Chromite ore supply concentration:South African and Kazakh ore deposits dominate metallurgical-grade feedstock, exposing processors to export duty volatility and logistics bottlenecks.
- Trivalent chromium substitution in decorative plating:Automotive exterior trim manufacturers in Germany and Japan are converting decorative chrome lines to Cr(III) electrolytes, eroding discretionary sodium dichromate demand.
- REACH sunset date uncertainty:Review timelines for dichromate authorization renewals extend capital planning horizons for European electroplating facilities beyond typical equipment depreciation cycles.
Strategic Opportunities
- Specialized leather tanning formulations in Vietnam:Footwear export zones near Ho Chi Minh City require chromium-based tanning agents to meet international hide preservation standards for European and North American brands.
- Closed-loop hexavalent chromium recovery systems:EPA emission limits for hard chrome plating shops create retrofit demand for ion exchange and membrane filtration equipment bundling sodium dichromate replenishment services.
- Wood preservation applications in Russia and Brazil:Utility pole and railway tie treatment specifications in these markets specify chromated copper arsenate alternatives where sodium dichromate serves as the active biocide component.
Industry Challenges
- Hexavalent chromium toxicity handling certification:OSHA permissible exposure limits require specialized respiratory protection programs and medical surveillance protocols that inflate operating costs for small-batch electroplating job shops.
- Legacy tannery effluent infrastructure:India's Central Pollution Control Board mandates zero liquid discharge systems in Kanpur and Unnao clusters, forcing capital-intensive upgrades that strain working capital for family-owned leather processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Dichromate Market |
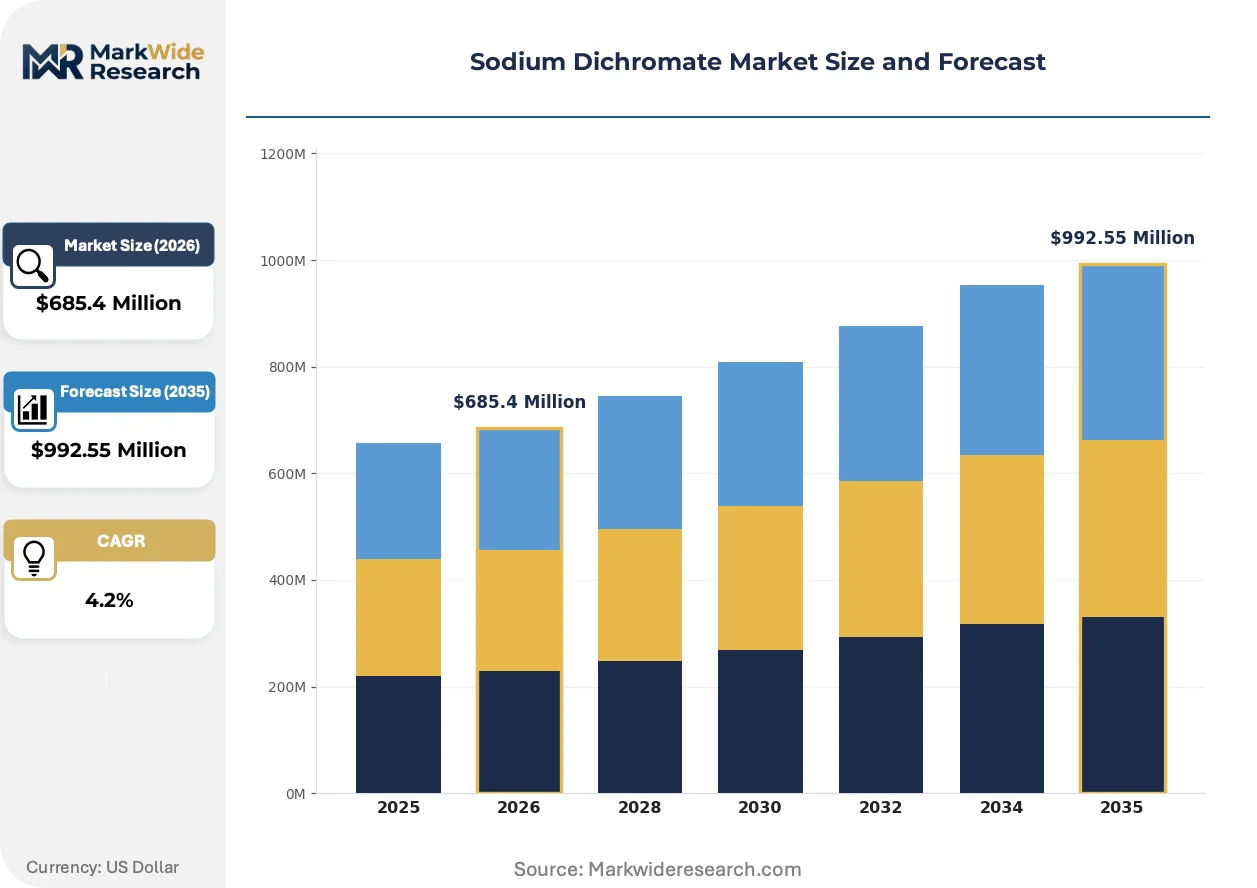
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Metal Finishing, Pigments, Leather Tanning, Wood Preservatives Grade: Technical Grade, Reagent Grade, Chemical Grade, Industrial Grade End User: Aerospace, Automotive, Construction, Electronics Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Lanxess, NPCC, Elementis, Yinhe Group, Nippon Chemical Industrial, Soda Sanayii, Vishnu Chemicals, Zhenhua Chem, Aktyubinsk Chemical Plant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Dichromate Market Emerging Trajectories
Electrochemical process intensification and closed-loop material recovery are compressing the viable operating envelope for conventional sodium dichromate production, favoring integrated producers with captive chromite supply and advanced emission controls.
Trivalent chromium conversion coating technologies are supplanting hexavalent-based passivation layers in automotive underbody and fastener applications. Tier-one suppliers in Stuttgart and Nagoya have accelerated qualification timelines for Cr(III) alternatives, compressing the addressable market for sodium dichromate-derived conversion coatings to aerospace and defense specifications where legacy approvals resist substitution.
EPA's National Emission Standards for Hazardous Air Pollutants for hard and decorative chromium electroplating are tightening stack monitoring and work practice requirements. Facilities in Ohio, Michigan, and California face retrofit deadlines that favor larger operations with capital reserves for fume suppressant systems and real-time hexavalent chromium detection, accelerating consolidation among independent plating shops.
Long-term supply agreements with fixed-volume minimums are displacing spot market purchases among pigment manufacturers. Procurement teams at major colorant houses in Germany and China now favor three to five year contracts with tier-one sodium dichromate producers, compressing trading margins for distributors and locking in supply security for integrated chromium chemical processors with verified REACH compliance documentation.
Sodium Dichromate Market Segmentation
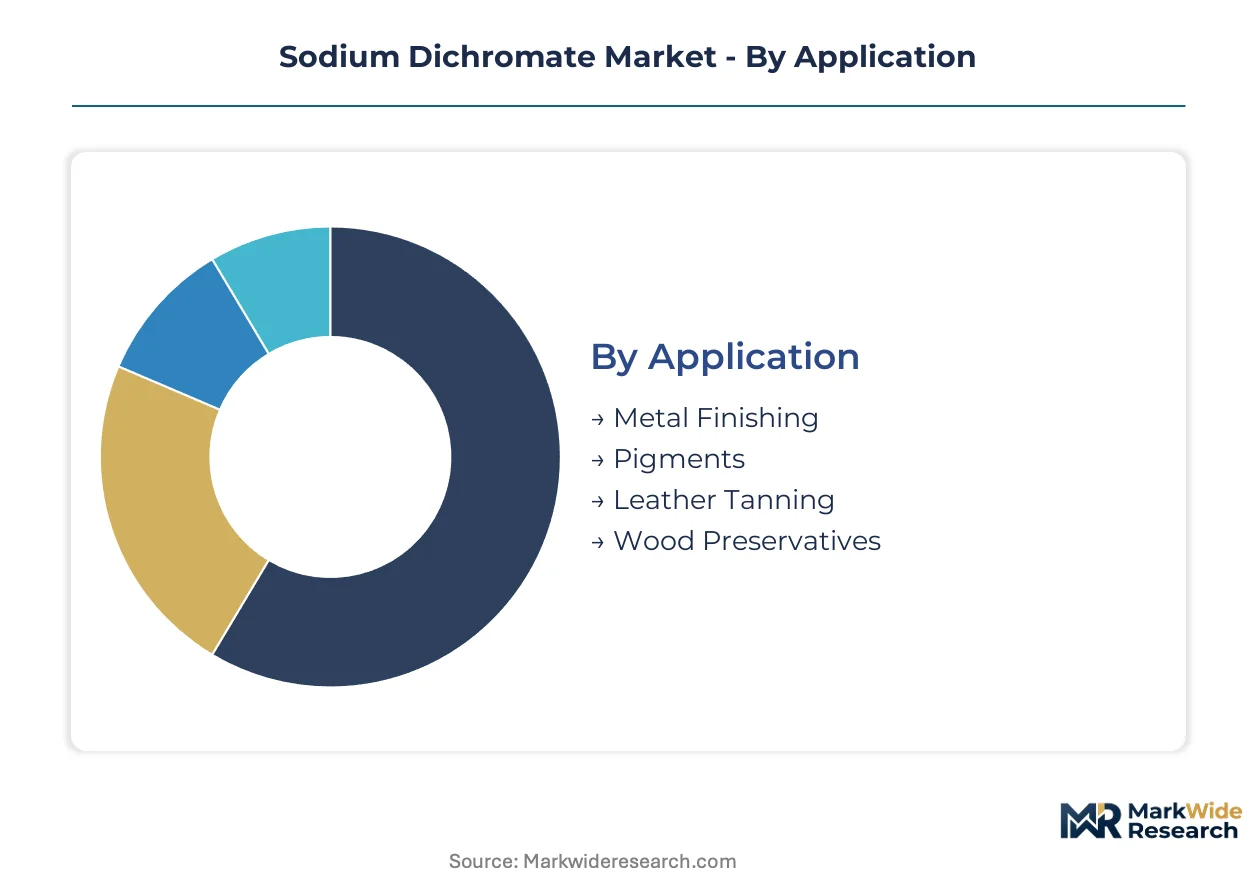
Sodium dichromate procurement patterns diverge sharply across application verticals, with aerospace plating specifications and REACH-compliant pigment synthesis commanding premium pricing tiers. Grade differentiation separates integrated chromite processors from toll manufacturers, while distribution channel selection reflects buyer scale and regulatory documentation requirements.
Application:
Margin pools concentrate in pigment manufacturing and specialized aerospace surface treatment, where formulation complexity and certification overhead protect pricing power.
- Metal Finishing:Hard chrome plating for jet engine components and landing gear assemblies requires high-purity sodium dichromate meeting AMS 2460 specifications. Boeing and Safran tier-one suppliers in the United States and France sustain volume offtake despite trivalent substitution pressure in decorative applications.
- Pigments:Lead chromate and molybdate orange synthesis for automotive and industrial coatings generates the highest margin per ton. German colorant houses leverage REACH Annex XIV exemptions to maintain dichromate-based pigment output for export markets.
- Leather Tanning:Chromium-based preservation for footwear and upholstery hides faces vegetable-tanner substitution in European luxury segments.
- Wood Preservatives:Chromated copper arsenate alternatives in Russian and Brazilian utility pole treatment specify sodium dichromate as the active biocide component.
The dominant share belongs to Metal Finishing, while Pigments is closing the gap fastest through specialized colorant formulations.
Grade:
Cost tier stratification separates captive chromite processors from merchant market participants, with specification breadth determining contract eligibility.
- Technical Grade:Standardized purity thresholds for industrial electroplating and chemical synthesis dominate procurement volumes. Chinese integrated producers in Shanxi province supply this tier through acidified sodium chromate roasting at scale.
- Industrial Grade:Bulk material for non-critical applications carries lower assay requirements and shorter documentation trails. Construction sector buyers in India favor this tier for cost-sensitive corrosion inhibition formulations.
- Reagent Grade:Laboratory and analytical applications demand sub-ppm impurity profiles with full certificate of analysis.
- Chemical Grade:Intermediate purity for specialty chromium compound manufacturing occupies a narrowing niche between technical and reagent tiers.
Technical Grade holds the volume lead, though Industrial Grade is expanding most quickly in emerging market construction chemicals.
End User:
Customer type determines contract structure, with aerospace and automotive OEMs imposing multi-year supply agreements and audit requirements.
- Aerospace:Jet engine component plating and conversion coating specifications resist trivalent chromium substitution due to legacy airworthiness certifications. Pratt & Whitney and Rolls-Royce supply chains enforce lot-level traceability from chromite ore forward.
- Automotive:Underbody and fastener applications are converting to Cr(III) alternatives at BMW and Toyota, compressing dichromate demand to legacy platform support.
- Construction:Rebar corrosion inhibition and concrete admixtures consume technical-grade material through regional distributor networks.
- Electronics:Printed circuit board etching and semiconductor tooling represent a declining segment facing perfluorinated chemical substitution.
Aerospace commands the premium position, while Automotive is surrendering share most rapidly to trivalent electrolyte conversion.
Distribution Channel:
Supply concentration favors direct relationships with integrated producers, squeezing intermediary margins on standardized grades.
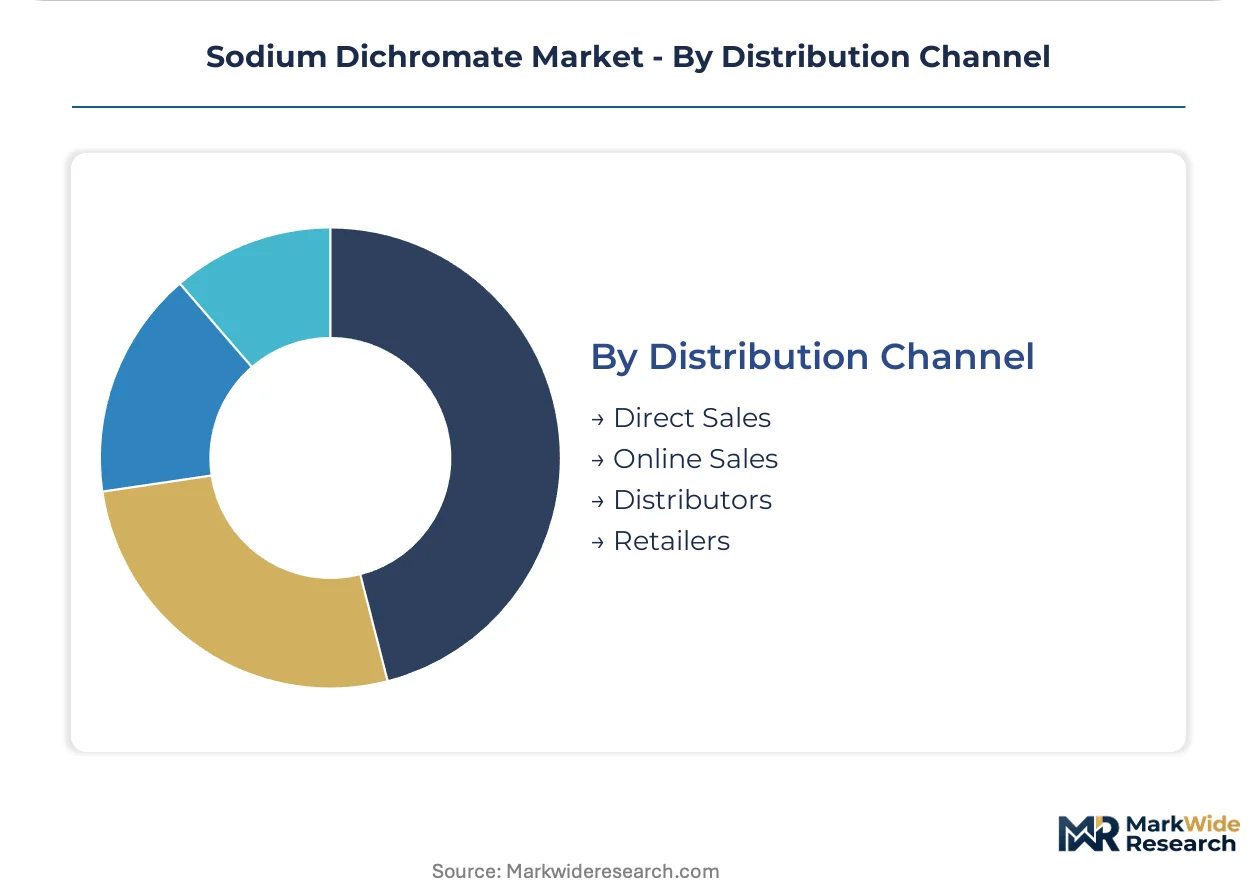
- Direct Sales:Multi-year offtake agreements with fixed-volume minimums now dominate pigment and aerospace procurement. Lanxess and Yinhe Group bypass distributors for tier-one accounts requiring REACH compliance documentation.
- Distributors:Regional chemical distributors serve mid-scale electroplating job shops with fragmented demand and spot purchasing patterns.
- Online Sales:E-procurement platforms capture small-laboratory and R&D reagent grade purchases with rapid fulfillment.
- Retailers:Limited to consumer-facing chromium compound products in jurisdictions without REACH-style restrictions.
Direct Sales anchors the channel mix, though Distributors are gaining traction fastest among small-batch metal finishing operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese integrated processors in Shanxi and Henan provinces export sodium dichromate feedstock to pigment manufacturers across Germany and France. South African chromite ore flows to Kazakh and Indian refiners, creating multi-leg supply corridors subject to export duty volatility.
China
Pigment synthesis and chromium chemical processing clusters in Shanxi and Henan provinces drive domestic consumption. MEE emission standards for hexavalent chromium discharge compel facility upgrades at acidification plants. The Yangtze River Delta hosts downstream colorant formulation facilities serving automotive OEM coating specifications.
Germany
REACH Annex XIV authorization renewals protect metal finishing and pigment manufacturing exemptions for industrial-grade buyers. ECHA review timelines extend capital planning horizons for electroplating facilities beyond standard depreciation cycles. The Ruhr industrial corridor maintains hard chrome plating capacity for aerospace tier-one suppliers.
United States
EPA National Emission Standards for Hazardous Air Pollutants enforce stack monitoring and fume suppressant retrofits at hard chrome plating facilities. OSHA permissible exposure limits require respiratory protection programs and medical surveillance at electroplating job shops. Ohio and Michigan plating clusters face consolidation pressure from compliance cost burdens.
India
Leather tanning for footwear export markets sustains chromium-based preservation demand from Tamil Nadu and Uttar Pradesh tannery clusters. The Central Pollution Control Board mandates zero liquid discharge systems in Kanpur and Unnao, forcing capital-intensive infrastructure upgrades. Vishnu Chemicals anchors specialized formulation supply across South Asian export corridors.
South Africa
Metallurgical-grade chromite ore deposits supply feedstock to processors in Kazakhstan and China, exposing shippers to logistics bottlenecks and export duty fluctuations. The country's national mining regulator oversees extraction licensing for chromium ore destined for chemical-grade roasting operations. Rustenburg and Limpopo mining belts concentrate ore output for international chemical processors.
Sodium Dichromate Market Vendor Landscape
Listed leaders compete with private specialists across integrated chromite processing and toll manufacturing segments. The vendor base stratifies into three tiers: captive ore-to-chemical processors, regional toll manufacturers, and specialized formulation suppliers. Strategic archetypes include backward-integrated mining-chemical conglomerates, REACH-compliant European premium-grade producers, and cost-optimized Asian merchant suppliers. Competitive moves concentrate on long-term offtake contracting and emission control technology licensing.
Within the integrated processing tier, Lanxess and Yinhe Group exemplify divergent geographic and regulatory positioning strategies. Lanxess occupies a position representing European REACH-compliant premium-grade output for pigment and metal finishing clients with verified authorization documentation. Yinhe Group anchors Chinese supply through Shanxi province acidification capacity serving domestic colorant houses. Among specialized regional suppliers, Vishnu Chemicals sits within the leather tanning formulation niche across South Asian export markets. Elementis and Nippon Chemical Industrial represent mid-scale toll manufacturers competing on specification breadth and regional distribution reach.
| Leading Market Players |
|---|
| Lanxess |
| NPCC |
| Elementis |
| Yinhe Group |
| Nippon Chemical Industrial |
| Soda Sanayii |
| Vishnu Chemicals |
| Zhenhua Chem |
| Aktyubinsk Chemical Plant |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with fixed-volume minimums lock in supply access for pigment manufacturers and aerospace tier-one suppliers while anchoring price visibility against chromite ore volatility. These multi-year contracts compress spot market liquidity and favor integrated processors with verified REACH documentation over merchant distributors.
Pricing Analysis
Current-generation REACH-compliant technical grade commands substantial premiums over prior-generation industrial grade due to authorization documentation burdens and lot-level traceability requirements. Pricing stratifies across premium, standard, and economy tiers based on purity thresholds and certification depth, with aerospace plating specifications showing least price sensitivity while Indian construction chemicals buyers face acute cost compression. Price differentiation stems from vertical integration depth and emission control technology bundling, though margins are tightening in decorative plating segments as trivalent chromium conversion accelerates.
Supply Chain Analysis
South Africa and Kazakhstan anchor metallurgical-grade chromite ore output feeding acidification plants in China and India. Sodium dichromate production draws from chromite roasting, sulfuric acid supply, and energy-intensive acidification infrastructure, with logistics bottlenecks at Richards Bay and Poti ports creating single-source vulnerability for European processors. Distribution runs through direct sales channels for tier-one pigment and aerospace accounts, while regional distributors serve fragmented electroplating job shops with spot purchasing patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a service-attach opportunity as closed-loop hexavalent chromium recovery systems and replenishment services expand faster than commodity chemical sales. Recurring revenue from ion exchange membrane maintenance and regulatory compliance auditing outpaces hardware growth in mature plating markets.
For Market Incumbents: Consolidate around captive chromite supply and emission control technology licensing to defend against trivalent chromium substitution in automotive decorative applications. Prioritize backward integration into South African ore offtake agreements and expand REACH-compliant technical grade capacity in the Ruhr corridor to lock in aerospace tier-one supply chains.
For New Entrants and Emerging Players: Lead with specialized leather tanning formulations in Vietnam's footwear export zones near Ho Chi Minh City, where chromium-based preservation standards remain entrenched for European brand compliance. Target wood preservative applications in Russia and Brazil with chromated copper arsenate alternatives, leveraging distributor partnerships for utility pole treatment specifications.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated chromite-to-chemical processors with verified emission control infrastructure and multi-year aerospace offtake contracts. The acquisition archetype favors Shanxi province acidification facilities serving domestic pigment synthesis clusters, with the signal to watch being ECHA authorization renewal timelines for dichromate metal finishing exemptions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromite Ore Supply | South African ore offtake agreements insulate processors from export duty volatility and logistics bottlenecks. |
| Closed-Loop Recovery System Deployment | EPA-compliant ion exchange bundling captures retrofit demand from Ohio and Michigan plating clusters. |
| REACH Authorization Documentation Investment | Verified Annex XIV compliance locks in premium-grade supply relationships with German colorant houses. |
| Specialized Formulation Development | Tailored leather tanning chemistry for Vietnamese footwear exporters meets European hide preservation standards. |
| Long-term Supply Agreement Structuring | Three to five year fixed-volume contracts displace spot purchasing among major pigment manufacturers. |
Methodological Framework
Desk research of customs trade data, ECHA authorization registries, and SEC filings preceded structured interviews with electroplating facility managers, pigment procurement leads, chromite ore traders, and leather tannery technical directors. Primary fieldwork across Shanxi province acidification plants and Tamil Nadu tanning clusters was cross-validated against secondary sources including MEE emission disclosure filings and Central Pollution Control Board enforcement records. Bottom-up volume estimates from application-grade consumption patterns were triangulated against top-down chromite ore trade flow analysis.
Variance decomposition across grade tier, end-use industry, and regional production hub dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling with chromite ore price elasticity and REACH authorization renewal probability as key forecast inputs. The modeling period incorporated aerospace plating specification persistence, trivalent chromium substitution curves in automotive applications, and leather tanning demand erosion from vegetable-based alternatives.
The analysis sits within stated boundaries; outcomes outside sustained REACH Annex XIV exemptions or accelerated trivalent chromium qualification timelines would require recalibration. Forecasts reflect documented assumptions regarding chromite ore supply concentration and EPA emission standard enforcement intensity. Recalibration cycles align with material shifts in ECHA authorization review schedules and MEE discharge standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Global Sodium Hydrosulfite Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Sodium Tungstate Dihydrate Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Global Nitrite Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Ethyleneamines Market
Bulk Chemicals
Global Ammonium Chloride Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
Ammonium Sulfate Market